
 Aluminium Battery Cable Market | 2026-2036
Aluminium Battery Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Battery Cable Market Insights
Certified aluminium metallurgists and high-voltage cable technicians is redrawing competitive boundaries across the supply base. Prysmian Group leverages integrated compound-to-cable operations to sustain cost discipline in European EV platforms. Nexans anchors its position through dedicated R&D centres focused on conductor alloy optimisation. Sumitomo Electric Industries dominates Asia-Pacific supply relationships with Japanese and South Korean battery manufacturers.
Aluminium battery cable consists of an aluminium alloy conductor sheathed in insulating polymers such as XLPE or TPE, engineered to carry direct current between battery cells, modules, and power distribution units in electrified systems. The conductor typically employs AA-8030 or AA-8176 aluminium alloys with conductivity ratings approaching 61% IACS, offering weight savings of roughly 48% versus equivalent copper gauges. Single-core configurations lead volume shipments due to their prevalence in high-amperage EV battery pack architectures, while multi-core designs capture expanding share in integrated battery management system harnesses. Flexible product types attract premium positioning as OEMs demand routing adaptability for compact underfloor battery layouts. PVC insulation retains cost-sensitive volume in commercial and industrial static installations, whereas XLPE commands technical specifications in automotive thermal cycling environments.
FDA, EPA, and NHTSA frameworks in the United States govern flammability, environmental release, and crash-safety performance of high-voltage cabling in road vehicles. ECHA REACH restrictions and EU RoHS substance limits constrain halogenated flame retardant selection across European supply chains, pushing compounders toward phosphorus-nitrogen alternatives. Stakeholders must monitor evolving GB standards from China's SAMR and MIIT as domestic EV export certification requirements tighten alloy and insulation testing protocols. Procurement teams should prioritise suppliers with concurrent UL, CE, and CCC qualification coverage to avoid market access discontinuities as regulatory divergence accelerates.
Market Dynamics
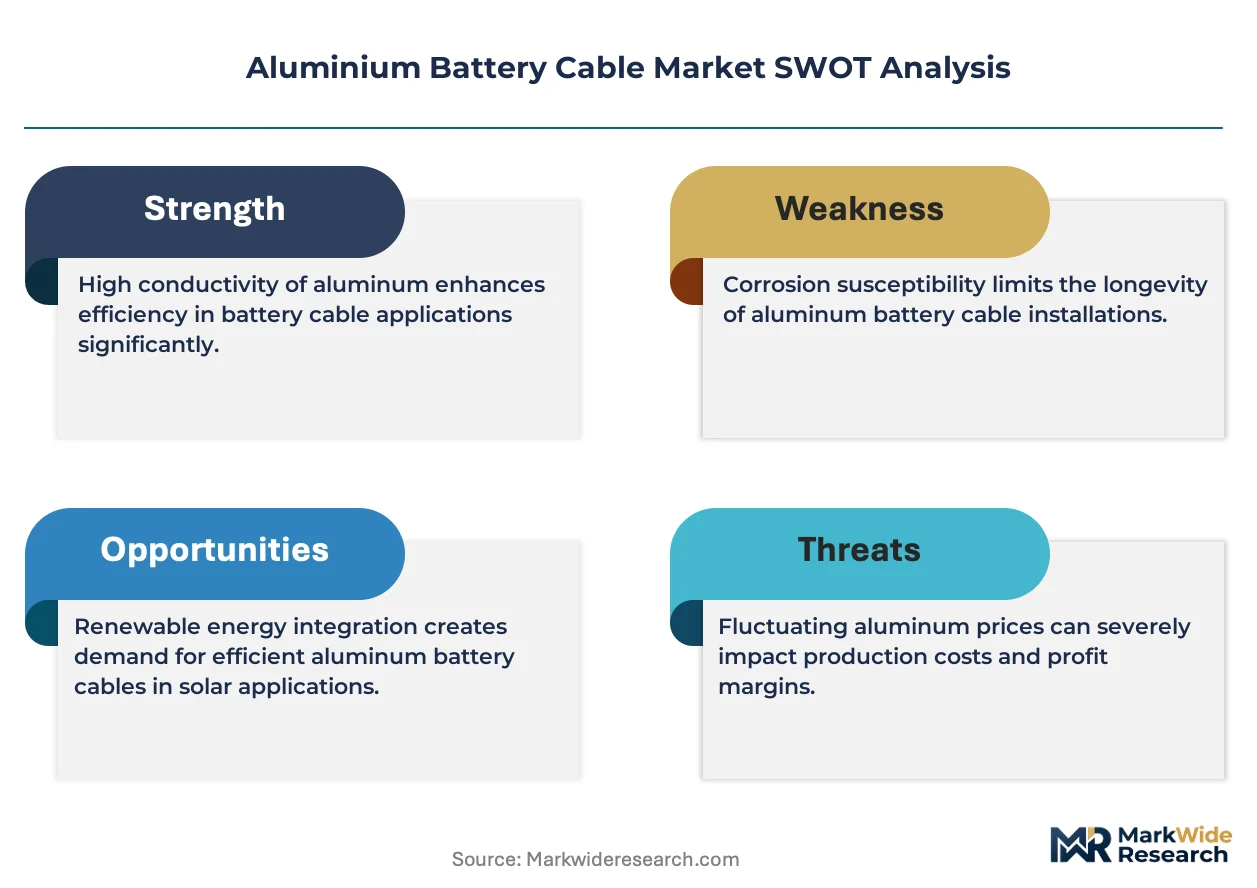
Copper price volatility and OEM lightweighting mandates are compressing substitution timelines for aluminium conductors in electrified vehicle architectures. Tier-1 suppliers face simultaneous pressure to reduce cable mass while maintaining conductivity parity with legacy copper harnesses.
Growth Catalysts
- EU RoHS substance limits:Halogenated flame retardant restrictions under Annex II amendments are accelerating phosphorus-nitrogen compound validation for European EV platforms.
- Underfloor battery packaging:Compact cell-to-pack architectures from Chinese and South Korean manufacturers demand flexible aluminium routing solutions with tight bend radii.
- AA-8176 alloy refinement:Conductivity improvements in 6xxx-series aluminium are narrowing the performance gap with copper for high-amperage DC fast-charging circuits.
Market Restraints
- Primary aluminium ingot exposure:LME price swings above fifteen percent annually destabilize conductor cost models for multi-year OEM supply agreements.
- Smelter concentration in China:Over sixty percent of global primary aluminium originates from Sichuan and Xinjiang provinces, creating geographic supply vulnerability.
- Terminations and crimping complexity:Aluminium oxide formation requires specialized tooling and inert gas welding, raising assembly line capital requirements versus copper.
Strategic Opportunities
- Indian PLI scheme for ACC batteries:Domestic cell manufacturing incentives are creating captive demand for localized aluminium cable production near Tamil Nadu and Gujarat gigafactories.
- Grid-scale BESS integration:Containerized battery energy storage systems for utility solar pairing require fire-rated aluminium interconnects with multi-hour thermal runaway containment.
- Recyclability certification:Closed-loop aluminium recovery protocols aligned with EU Green Deal circular economy targets command premium positioning in sustainability-scored tenders.
Industry Challenges
- High-voltage safety technician scarcity:OEMs and tier-1s compete for certified personnel capable of 800V+ system assembly and fault isolation.
- Concurrent UL, CE, CCC qualification:Divergent test protocols for flame propagation, thermal cycling, and mechanical abuse extend product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Battery Cable Market |
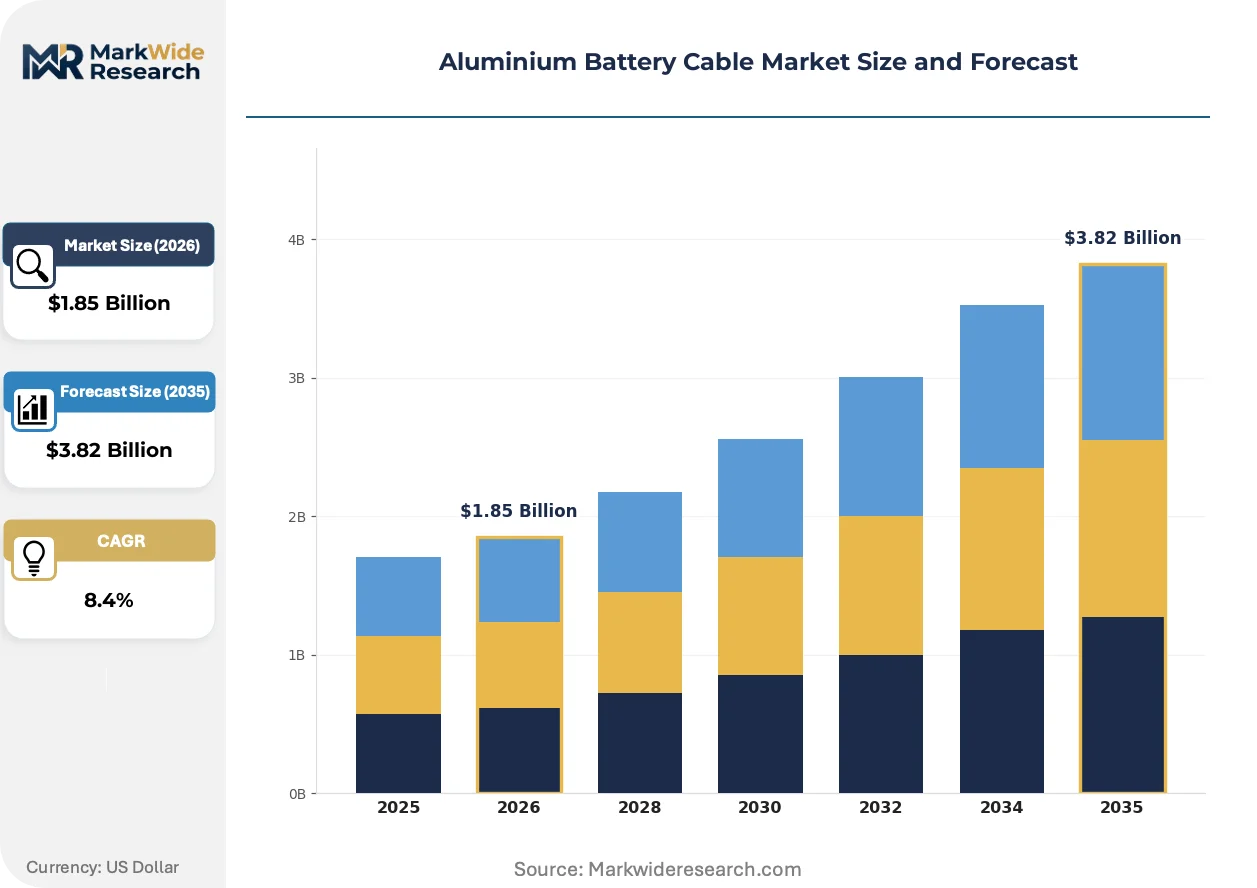
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Core, Multi-Core, Flexible, Rigid End Use: Automotive, Industrial, Renewable Energy, Commercial Insulation Material: PVC, XLPE, TPE, Rubber Application: Power Distribution, Electric Vehicles, Solar Installations, Battery Systems |
| Companies Covered | Southwire Company, Prysmian Group, Nexans, LS Cable & System, Sumitomo Electric Industries, General Cable, Furukawa Electric, NKT, Superior Essex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Battery Cable Market Trends and Innovations
Material science advances and regulatory chemistry constraints are fragmenting the insulation compound landscape. Suppliers must now optimize simultaneously for thermal endurance, halogen-free flame retardance, and end-of-life recyclability.
XLPE-TPE hybrid insulation systems are bifurcating the automotive cable specification landscape. Tier-1 harness manufacturers are adopting these compounds for their combined resistance to thermal aging and routing flexibility. The technology is bifurcating procurement standards, with premium EV platforms demanding customized compound formulations while commercial vehicle segments retain commodity PVC.
REACH Annex XVII restrictions on medium-chain chlorinated paraffins are forcing compound reformulation across European supply chains. Cable manufacturers face eighteen-month validation cycles for alternative plasticizers in existing OEM qualifications. Battery pack assemblers in Germany and Poland are absorbing higher compound costs to maintain CE marking compliance and avoid production stoppages.
Cell-to-pack architecture adoption is compressing cable routing distances and changing buyer specifications. Chinese OEMs are eliminating module-level wiring in favor of direct cell busbar connections, reducing per-vehicle cable mass. Tier-1 suppliers in South Korea and Japan are responding with ultra-flexible stranded conductor designs for the remaining interconnect segments in premium sedan and SUV platforms.
Aluminium Battery Cable Market Segmentation
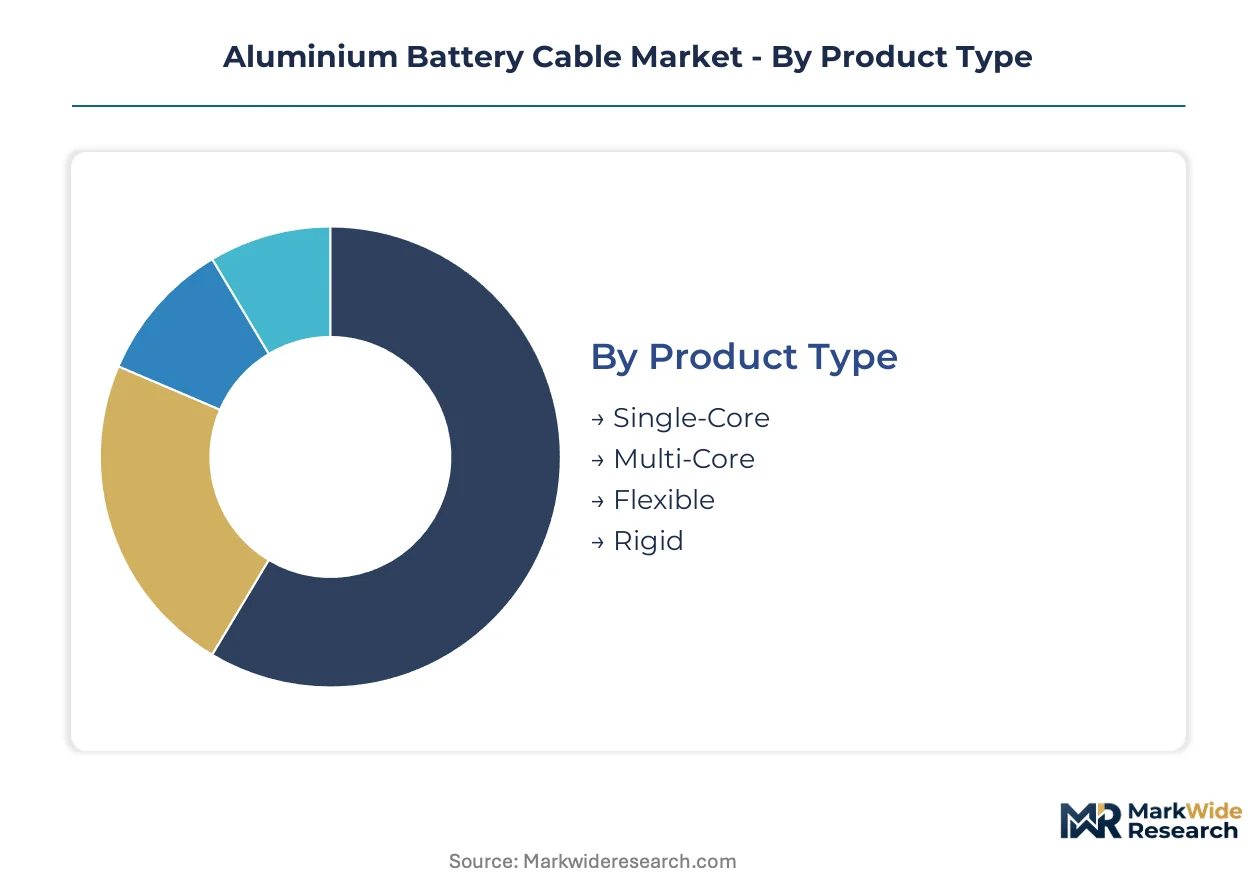
Aluminium battery cable procurement channels diverge sharply by technical specification and end-use certification requirements. OEMs route high-voltage automotive harnesses through tier-1 integrators with concurrent UL, CE, and CCC coverage, while industrial buyers source commodity single-core runs through electrical distributors.
Product Type:
Channel mix varies by conductor geometry—single-core and rigid products flow through industrial distribution, while flexible and multi-core cables route through automotive tier-1 harness manufacturers serving OEM assembly lines.
- Single-Core:Solid or stranded AA-8030 conductor engineered for high-amperage DC circuits with minimal voltage drop. Demand concentrates in German and Chinese EV battery pack architectures where cell-to-module interconnections require simplified routing. OEM lightweighting mandates compress substitution timelines from copper.
- Multi-Core:Bundled conductor configurations integrating power and signal lines for battery management system harnesses. South Korean battery manufacturers specify these for integrated pack designs in premium sedan platforms. Tighter bend radii requirements from underfloor packaging drive specification complexity.
- Flexible:Ultra-fine stranded construction with TPE or XLPE-TPE hybrid insulation for routing adaptability in compact battery layouts. Japanese tier-1 suppliers dominate channel relationships for this premium tier.
- Rigid:Fixed-form conductor assemblies for static industrial and commercial installations with lower movement tolerance. Chinese solar farm developers source through electrical wholesalers with BIS certification for Indian export projects.
By volume, Single-Core leads. By growth pace, Flexible is climbing the fastest.
End Use:
Cost tier stratification separates automotive EV platforms—where thermal cycling specifications command premium compound costs—from commercial and industrial segments retaining commodity PVC insulation.
- Automotive:High-voltage harnesses for battery electric and hybrid powertrains requiring 800V+ system capability. German OEMs enforce REACH-compliant phosphorus-nitrogen flame retardants through tier-1 supply agreements. NHTSA crash-safety protocols govern US market entry.
- Industrial:Stationary power distribution for manufacturing facilities and material handling equipment. Indian PLI scheme incentives for ACC battery manufacturing are creating captive cable demand near Tamil Nadu gigafactories.
- Renewable Energy:Grid-scale solar and wind farm interconnections with fire-rated containment requirements. Utility-scale BESS integration in China demands multi-hour thermal runaway protocols under GB standards from SAMR and MIIT.
- Commercial:Building infrastructure and data center power distribution with standard thermal cycling profiles. European commercial buyers absorb higher compound costs to maintain CE marking compliance under RoHS Annex II amendments.
Automotive commands the highest margin tier. Renewable Energy is expanding most quickly.
Insulation Material:
Application temperature dictates material selection—automotive thermal cycling environments specify XLPE, while static commercial installations tolerate cost-sensitive PVC.
- PVC:Cost-optimized polymer for commercial and industrial static installations with moderate thermal exposure. REACH Annex XVII restrictions on medium-chain chlorinated paraffins force eighteen-month reformulation cycles in European supply chains.
- XLPE:Cross-linked polyethylene with superior thermal aging resistance for automotive underhood and battery pack environments. Prysmian Group and Nexans anchor European supply through integrated compound-to-cable operations.
- TPE:Thermoplastic elastomer combining flexibility with halogen-free flame retardance for premium EV routing requirements. Chinese OEMs specify TPE for cell-to-pack architectures with tight bend radii.
- Rubber:Ethylene-propylene or silicone compounds for extreme temperature and abrasion resistance in industrial mobile equipment. Japanese mining and construction machinery manufacturers specify rubber-sheathed flexible conductors.
XLPE dominates automotive certification. TPE is gaining share fastest in premium EV platforms.
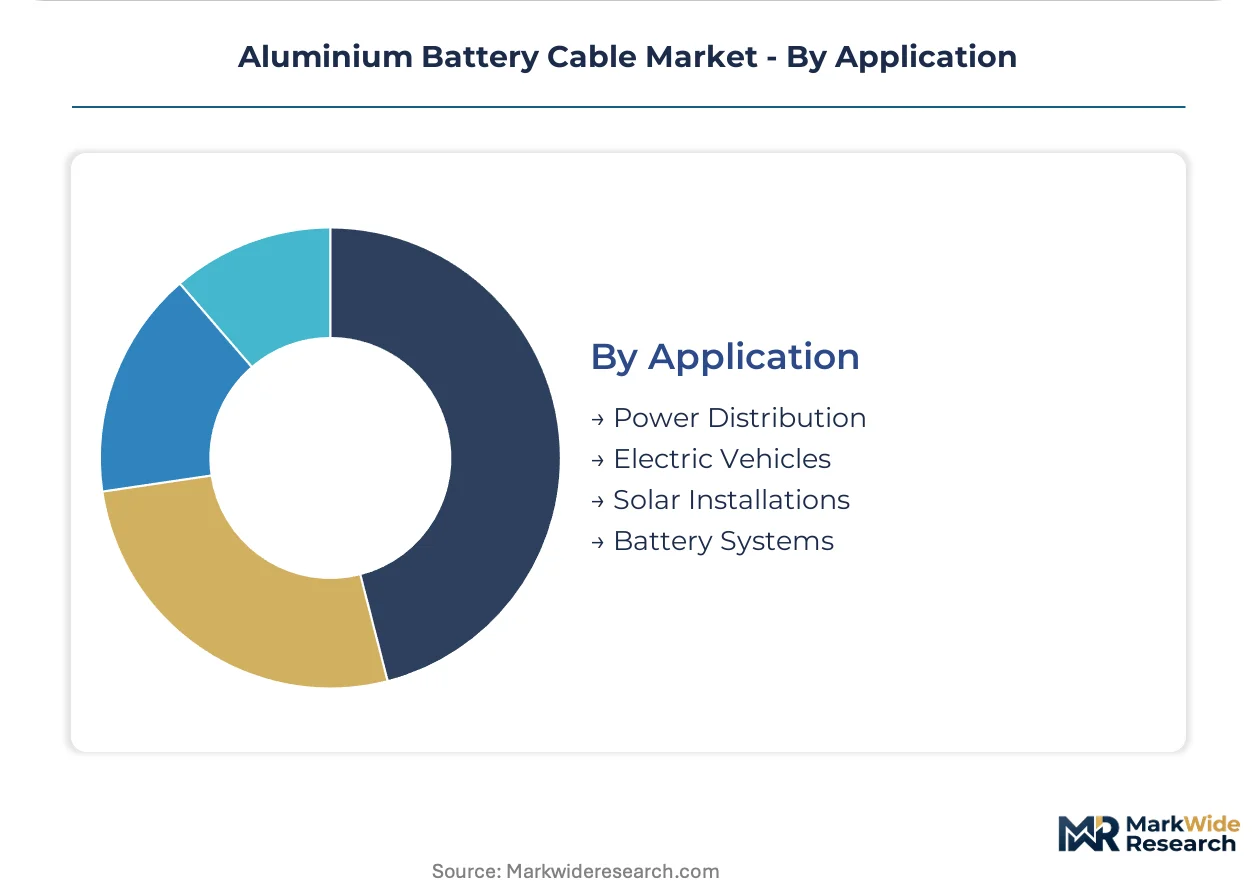
Application:
Customer type bifurcation separates automotive OEMs—demanding customized compound formulations and concurrent multi-market qualifications—from solar developers procuring standardized power distribution runs.
- Power Distribution:Utility-scale and industrial substation interconnects with standardized ampacity ratings. Chinese state grid procurement favors AA-8176 alloy refinement for conductivity parity with legacy copper infrastructure.
- Electric Vehicles:High-voltage battery-to-inverter and pack-to-charger circuits with 800V+ capability. South Korean battery cell manufacturers specify ultra-flexible stranded designs for remaining interconnect segments in premium platforms.
- Solar Installations:Photovoltaic array DC wiring and inverter interconnections with UV and moisture resistance. Indian domestic content requirements under PLI schemes localize production near Gujarat manufacturing clusters.
- Battery Systems:Containerized BESS interconnects for utility solar pairing with multi-hour thermal runaway containment. German grid operators enforce EU Green Deal circular economy targets for closed-loop aluminium recovery protocols.
Power Distribution holds the volume base. Electric Vehicles shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese smelter concentration grants raw material pricing leverage that European compounders struggle to match, creating a structural cost asymmetry across the value chain.
China
Domestic EV and energy storage manufacturing scales drive conductor consumption in the Yangtze River Delta and Pearl River Delta clusters. MIIT and SAMR tighten GB standards for alloy and insulation testing protocols on export-bound battery systems. Sichuan and Xinjiang provinces supply over sixty percent of global primary aluminium ingot, concentrating geographic vulnerability.
Germany
Battery cell gigafactories in Lower Saxony and Baden-Württemberg generate tier-1 harness demand for high-voltage platforms. ECHA REACH restrictions and EU RoHS Annex II amendments constrain halogenated flame retardant selection, pushing compounders toward phosphorus-nitrogen alternatives. Stuttgart-area OEMs enforce concurrent CE and UL qualification requirements through supply agreements.
United States
IRA production incentives accelerate domestic battery manufacturing investment in Michigan and South Carolina. NHTSA crash-safety protocols and EPA environmental release frameworks govern high-voltage cabling certification. Detroit-area automotive suppliers face technician scarcity for 800V+ system assembly.
South Korea
Premium sedan and SUV platforms from Seoul Capital Area manufacturers specify ultra-flexible stranded conductor designs. MFDS-aligned quality protocols intersect with OEM thermal cycling specifications. Busan-Ulsan industrial corridors host integrated cell-to-pack assembly operations with compressed cable routing distances.
India
PLI scheme incentives for ACC battery manufacturing create captive cable demand near Tamil Nadu and Gujarat gigafactories. BIS certification requirements localize production for solar export projects. Domestic content mandates under national manufacturing programs reshape procurement patterns for electrical distributors.
Aluminium Battery Cable Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the supply base. Integrated compound-to-cable operators compete with specialized metallurgical refiners for automotive platform qualifications. Three archetypes dominate: European integrated manufacturers with backward polymer control, Asia-Pacific relationship-based suppliers anchored in battery cell manufacturing corridors, and North American scale-driven producers serving industrial distribution channels. Competitive moves concentrate on concurrent multi-market qualification coverage and captive alloy refinement capacity.
Among European integrated manufacturers, Prysmian Group and Nexans exemplify the compound-to-cable archetype with cost discipline positioning. Sumitomo Electric Industries anchors the Asia-Pacific relationship tier through supply proximity to Japanese and South Korean battery manufacturers. These three occupy positions across the technology-cost spectrum without overlapping strategic territory.
| Leading Market Players |
|---|
| Southwire Company |
| Prysmian Group |
| Nexans |
| LS Cable & System |
| Sumitomo Electric Industries |
| General Cable |
| Furukawa Electric |
| NKT |
| Superior Essex |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German OEMs and Sichuan smelters lock in primary aluminium supply access while capping price volatility exposure for multi-year battery platform contracts. These contracts tether conductor cost models to LME benchmark corridors, compressing margin buffers for tier-1 harness manufacturers caught between fixed OEM pricing and floating raw material exposure.
Pricing Analysis
Geographic price spreads between European compounders and Chinese integrated producers exceed cost-of-delivery differentials, reflecting regulatory compliance premiums. Three-tier pricing structure across premium, standard, and economy levels separates UL-CE-CCC qualified automotive harnesses from BIS-certified industrial runs and commodity PVC commercial installations. Pricing pressure stems from LME aluminium volatility above fifteen percent annually, forcing renegotiation clauses into OEM supply agreements. Commercial and industrial segments exhibit highest price sensitivity, while automotive EV platforms absorb premium compound costs for thermal cycling certification.
Supply Chain Analysis
Inventory lead times for AA-8030 and AA-8176 alloy rod extend to sixteen weeks when Xinjiang smelter output faces power rationing or logistics disruption. Primary aluminium feedstock draws from Sichuan, Xinjiang, and Yunnan provinces, with secondary refining concentrated in Henan and Shandong. XLPE and TPE compound supply rests on petrochemical inputs from South Korean and Singaporean polymer producers. Single-source vulnerability concentrates in Chinese primary smelting, where over sixty percent of global ingot originates. Distribution runs through tier-1 harness integrators for automotive OEMs and electrical wholesalers for industrial and solar project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Chinese and South Korean battery cell manufacturers, compressing tier-1 supplier margins and forcing qualification consolidation around multi-market certification coverage.
For Market Incumbents: Shield automotive platform positions by deepening backward integration into AA-8176 alloy refinement and captive XLPE compound production. Prysmian Group and Nexans demonstrate this through European integrated operations that defend against Chinese cost arbitrage. Prioritize concurrent UL, CE, and CCC qualification maintenance to avoid market access discontinuities as regulatory divergence accelerates across jurisdictions. For New Entrants and Emerging Players: Anchor in Indian PLI scheme corridors near Tamil Nadu and Gujarat ACC gigafactories, where domestic content mandates create localized demand without incumbent supply relationships. Target grid-scale BESS integration for utility solar pairing, a segment with fire-rated containment specifications that favor specialized compound capabilities over scale economies. Pursue recyclability certification aligned with EU Green Deal circular economy targets as a sustainability-scored tender entry point. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier compounders with phosphorus-nitrogen flame retardant validation and existing OEM qualification relationships, positioned for acquisition by integrated cable manufacturers seeking backward polymer control. Long-term viability hinges on aluminium conductor substitution timelines compressing against copper price volatility and OEM lightweighting mandates. Watch for 800V+ platform adoption rates as the inflection signal for high-voltage safety technician scarcity and premium flexible cable demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Refinement | Captive AA-8176 production defends margin position against LME volatility and Chinese smelter concentration. |
| Phosphorus-Nitrogen Compound Validation | REACH Annex XVII compliance unlocks European EV platform access as halogenated flame retardants face restriction. |
| Concurrent Multi-Market Qualification | UL, CE, and CCC coverage prevents supply discontinuities for export-bound battery systems under diverging test protocols. |
| Cell-to-Pack Architecture Adaptation | Ultra-flexible stranded designs capture remaining interconnect demand as Chinese OEMs eliminate module-level wiring. |
| Closed-Loop Recovery Certification | EU Green Deal circular economy alignment commands premium positioning in sustainability-scored utility tenders. |
Research Methodology
Desk research of customs trade databases, MIIT and SAMR regulatory filings, and IHS Markit vehicle production data preceded structured interviews with tier-1 harness procurement managers, OEM platform engineers, aluminium alloy metallurgists, and compound formulation specialists. Primary fieldwork across the Yangtze River Delta, Stuttgart industrial corridor, and Detroit automotive supplier base validated secondary estimates. Bottom-up cable consumption modeling triangulated against top-down EV production forecasts and energy storage deployment pipelines.
Variance decomposition across product type, end use, insulation material, and application dimensions isolated growth contribution by segment. CAGRs were derived from installed base projections and content-per-vehicle assumptions across the analysis window. Forecast inputs incorporated OEM lightweighting mandate timelines, GB standards evolution from SAMR, and PLI scheme incentive disbursement patterns for Indian ACC manufacturing.
Material uncertainties — LME aluminium price swings, REACH Annex XVII amendment timing, and 800V+ platform adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity and regulatory harmonization trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Power and Control Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
High-Speed Interconnects Market
Cables
Global Ethernet Cable Market
Cables
Europe Wire and Cable Market
Cables
North America Copper Wire and Cable Market
Cables
UK Cables Market
Cables
Coaxial Cable Market
Cables
US Cables Market
Cables
North America Patch Cable Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Downhole Cables Market
Cables
United States Cable Accessories Market
Cables
Asia-Pacific Premise Cable Market
Cables
Global Cable Tie Market
Cables
XLPE Cables Market