
 Electric Bus Market | 2026-2036
Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bus Market Analysis
China is fragmenting as multiple provinces expand electric bus assembly capacity beyond traditional coastal hubs. BYD Company Ltd. leverages integrated battery manufacturing to control cost structures across its supply chain. Zhengzhou Yutong Bus Co., Ltd. anchors domestic procurement contracts with provincial transit authorities. Proterra Inc. competes on North American fast-charging infrastructure compatibility.
An electric bus is a battery-powered or fuel-cell-driven passenger vehicle designed for urban and interurban transit, typically operating at 350-800V architectures with lithium-ion phosphate or ternary cell packs. These vehicles eliminate tailpipe emissions while reducing per-kilometer energy costs versus diesel equivalents. Battery Electric Bus configurations now dominate procurement volumes due to declining cell prices and established charging protocols. Fuel Cell Bus segments occupy niche positions in cold-climate deployments where battery degradation accelerates. Fast Charging technology leads infrastructure rollout timelines as transit agencies prioritize depot turnaround efficiency.
China's MIIT enforces GB/T standards for vehicle safety and charging interoperability, while the EU F-Gas Regulation and MDR framework shape component compliance for European suppliers. The EPA and NHTSA in the United States coordinate on tailpipe-equivalent emission rules and crashworthiness standards for zero-emission transit vehicles. Stakeholders must monitor how subsidy phase-out timelines in major manufacturing jurisdictions alter procurement financing structures.
Market Dynamics
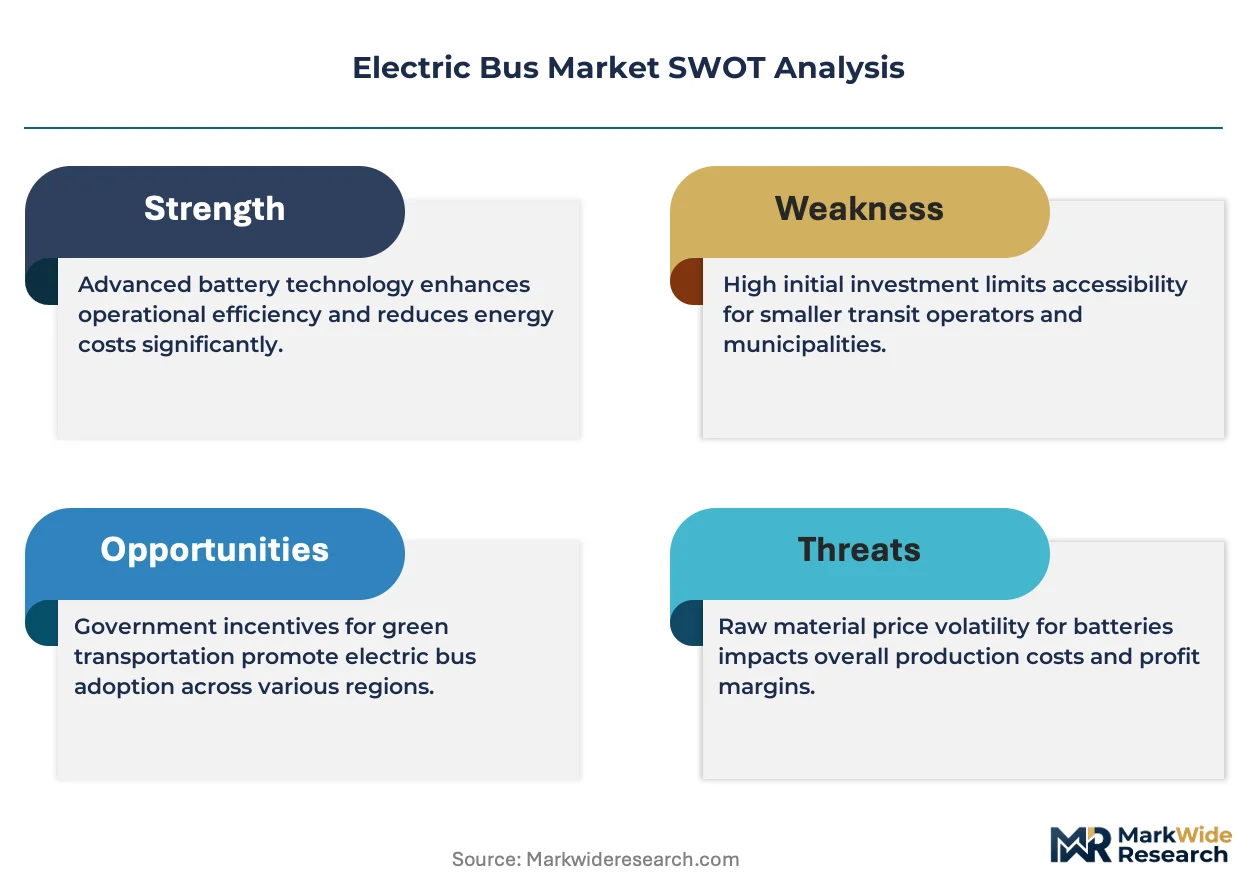
Battery chemistry transitions are compressing total cost of ownership differentials between electric and diesel bus platforms, forcing procurement committees to abandon pilot programs and commit to fleet-scale electrification timelines.
Growth Catalysts
- EU Green Deal mandates:Binding fleet decarbonization targets for municipal transit operators are accelerating tender volumes across German and French urban networks.
- Solid-state battery pilots:Early deployments in Nordic cold-climate corridors are validating extended range envelopes that eliminate depot charging infrastructure gaps.
- China's dual carbon goals:Provincial procurement quotas under MIIT supervision are channeling state-owned transit authority capital toward domestic electric bus manufacturers.
Market Restraints
- Lithium carbonate volatility:Cell pack input costs swing with South American brine extraction output, destabilizing OEM quotation validity windows.
- Charging hardware concentration:High-power pantograph and plug-in system assembly clusters in East Asian manufacturing zones expose European and North American operators to extended lead times.
- Grid interconnection queues:Utility upgrade approval timelines for depot megawatt-scale charging installations stretch 18-36 months in dense urban jurisdictions.
Strategic Opportunities
- India's PLI scheme:Component-level production incentives for battery pack and electric powertrain assembly are drawing module suppliers toward Gujarat and Tamil Nadu industrial corridors.
- Vehicle-to-grid integration:Bidirectional charging protocols enable transit authorities to monetize stationary battery capacity during off-peak hours.
- Interurban route electrification:Battery swapping infrastructure along highway corridors opens segments previously reserved for diesel coaches.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack personnel certified for 800V architecture troubleshooting and thermal runaway containment protocols.
- GB/T to CCS2 protocol harmonization:Chinese-built platforms require hardware retrofits for European charging network compatibility, extending homologation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bus Market |
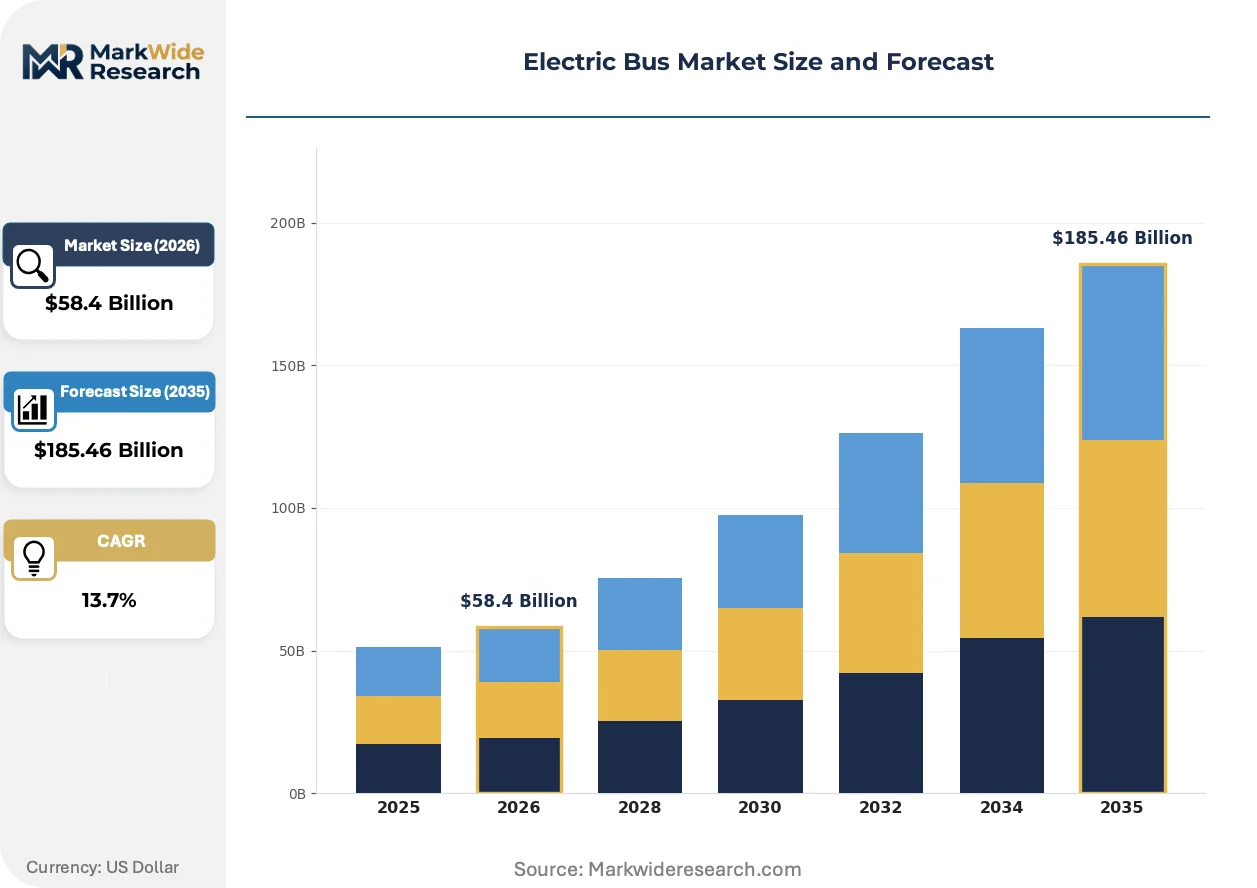
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $185.46 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Bus, Plug-in Hybrid Bus, Fuel Cell Bus, Chassis End User: Public Transit Agencies, Private Operators, School Districts, Tourism Services Technology: Fast Charging, Inductive Charging, Overhead Charging, Regenerative Braking Size: Standard Bus, Articulated Bus, Mini Bus, Double Decker Bus |
| Companies Covered | BYD Company Ltd., Zhengzhou Yutong Bus Co., Ltd., Proterra Inc., Volvo Buses, Daimler Buses, Solaris Bus & Coach, MAN Truck & Bus, CRRC Corporation Limited, Xiamen King Long United Automotive Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bus Market Emerging Trajectories
Transit agencies are abandoning incremental pilot deployments in favor of complete fleet replacement schedules, compressing technology validation cycles and forcing suppliers to accelerate platform maturation timelines.
Lithium iron phosphate cell chemistry is migrating from entry-range urban buses toward premium interurban coaches. Scandinavian operators are specifying LFP packs for 400-kilometer routes previously reserved for ternary lithium configurations. This chemistry shift is compressing thermal management system complexity and extending warranty coverage periods from eight to twelve years.
The EPA's tailpipe-equivalent emission rules under coordinated NHTSA review are reclassifying procurement evaluation criteria for US transit authorities. Federal funding eligibility now hinges on documented lifecycle carbon intensity rather than upfront capital cost. California and New York metropolitan planning organizations are rewriting tender specifications to prioritize vehicles with domestically sourced battery content.
Service contracting is fragmenting from bundled procurement-and-maintenance packages toward unbundled powertrain-as-a-service arrangements. Third-party fleet management specialists are assuming battery degradation risk from municipal balance sheets. This model is penetrating most aggressively in UK and Netherlands markets where public-private partnership frameworks already govern infrastructure concessions.
Electric Bus Market Segmentation
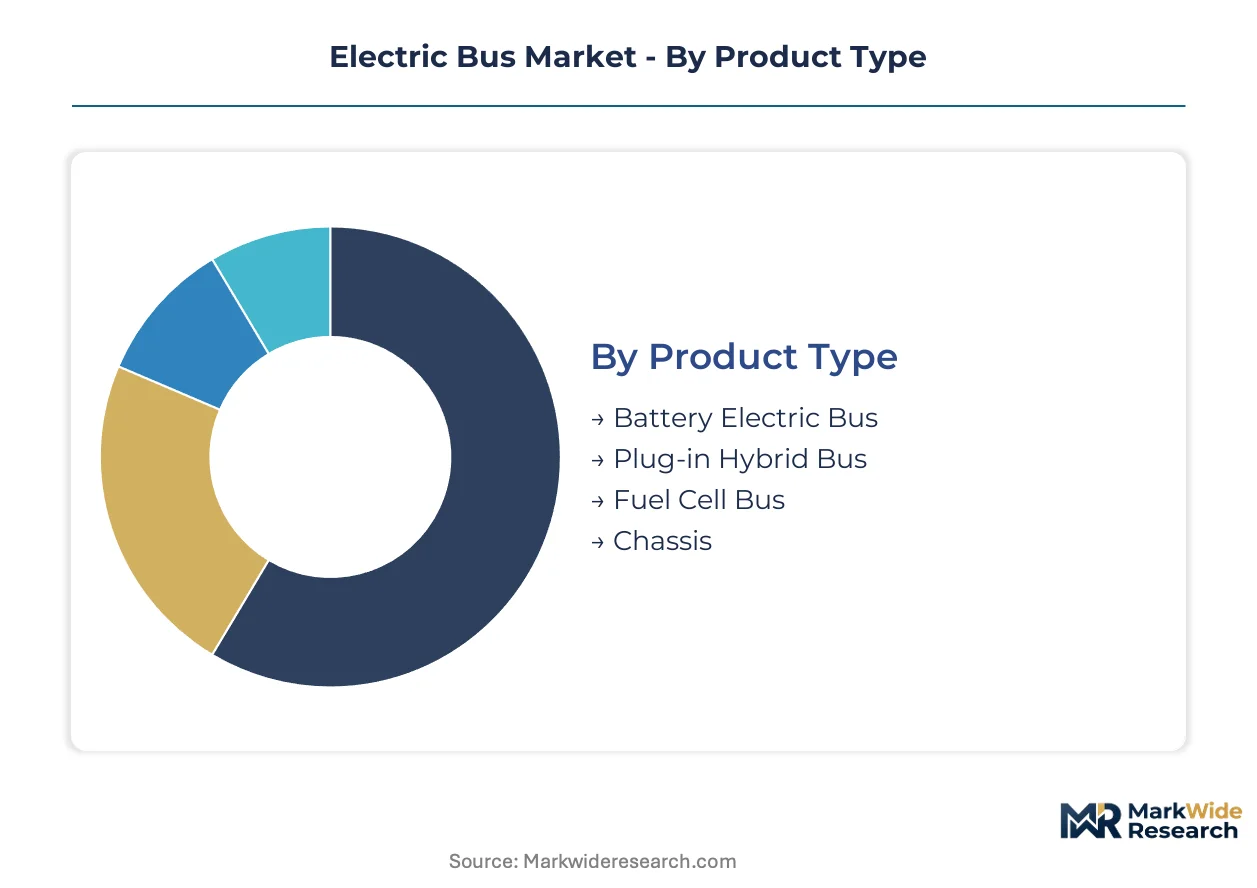
Segmentation in the electric bus market reveals how procurement committees weight total cost of ownership against operational flexibility. Distinct technology configurations and vehicle architectures command divergent maintenance protocols, charging infrastructure requirements, and residual value profiles.
Product Type:
After-sales service intensity varies sharply across powertrain architectures, with battery pack replacement schedules and fuel cell stack refurbishment cycles driving divergent lifecycle cost models.
- Battery Electric Bus:Lithium-ion phosphate or ternary cell packs operating at 350-800V architectures dominate procurement volumes across Shenzhen, London, and Santiago municipal fleets. Transit authorities in these corridors prioritize depot-based overnight charging infrastructure over opportunity charging due to route predictability.
- Plug-in Hybrid Bus:Dual-mode diesel-electric configurations retain residual demand in interurban corridors where charging infrastructure gaps persist. German and French regional operators specify these platforms for routes exceeding 300 kilometers until solid-state battery pilots validate extended range envelopes.
- Fuel Cell Bus:Proton exchange membrane systems occupy cold-climate niches where battery degradation accelerates. Nordic operators in Oslo and Stockholm deploy these for sub-zero temperature corridors.
- Chassis:Skateboard platforms with integrated battery packs enable third-party bodybuilder specialization. Indian manufacturers in Gujarat industrial corridors leverage this modularity for cost-competitive assembly.
By volume, Battery Electric Bus leads. By growth pace, Fuel Cell Bus is ahead in cold-climate procurement tenders.
End User:
Procurement patterns diverge based on balance sheet capacity and federal funding eligibility, with municipal entities accessing green bond financing unavailable to private fleet operators.
- Public Transit Agencies:State-owned authorities under China's MIIT supervision channel capital toward domestic manufacturers through provincial procurement quotas. These entities prioritize 12-year warranty coverage and domestic battery content requirements.
- Private Operators:UK and Netherlands-based fleet management specialists assume battery degradation risk through powertrain-as-a-service arrangements. Unbundled contracting fragments traditional bundled procurement models.
- School Districts:US EPA tailpipe-equivalent emission rules reclassify evaluation criteria toward lifecycle carbon intensity. California and New York districts rewrite specifications to prioritize domestically sourced cell packs.
- Tourism Services:Double-decker configurations in London and Edinburgh specify premium passenger experience features. These operators demand 400-kilometer range envelopes for interurban excursion routes.
Public Transit Agencies anchor procurement volumes. Private Operators are climbing the fastest through service model innovation.
Technology:
Charging protocol selection locks operators into specific hardware ecosystems, with pantograph and plug-in system assembly concentration in East Asian manufacturing zones exposing European and North American agencies to extended lead times.
- Fast Charging:High-power conductive systems at 350-450kW enable depot turnaround efficiency. Shenzhen's fleet operators pioneered overnight fast-charging protocols now replicated across Santiago's Transantiago network.
- Inductive Charging:Wireless power transfer eliminates connector wear but demands precise vehicle positioning. Limited deployments in German urban networks validate operational feasibility.
- Overhead Charging:Pantograph systems enable opportunity charging at route terminals. Scandinavian operators specify these for high-frequency corridor services.
- Regenerative Braking:Kinetic energy recovery systems extend effective range. All major platforms now integrate this as standard specification.
Fast Charging commands installed base leadership. Inductive Charging holds steepest expansion trajectory among pilot programs.
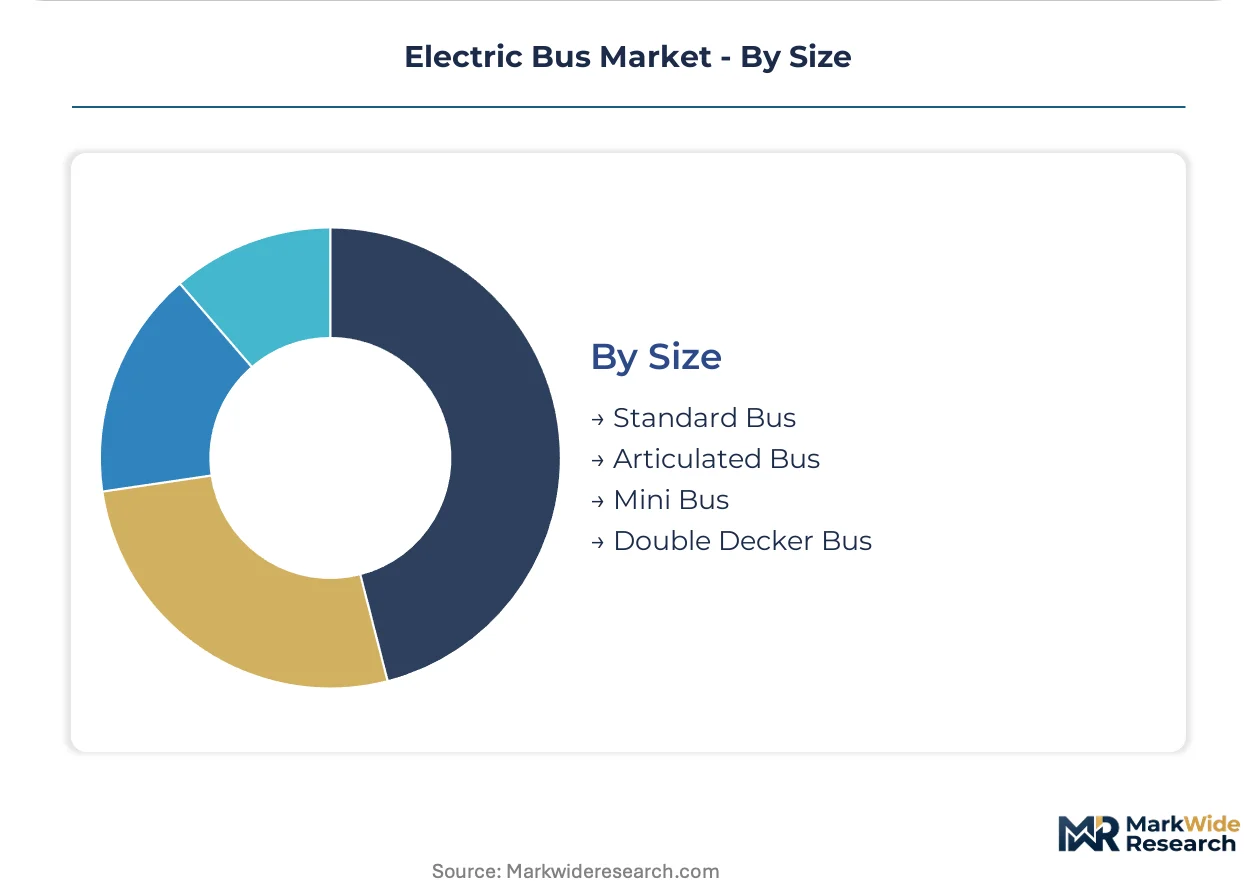
Size:
Vehicle dimensions determine battery pack configuration and thermal management complexity, with articulated platforms demanding cell pack architectures distinct from standard single-body designs.
- Standard Bus:12-meter single-body configurations represent the procurement baseline across municipal networks. These platforms optimize for 200-300 kilometer daily duty cycles.
- Articulated Bus:18-meter bendy bus designs serve high-capacity corridors in Bogotá TransMilenio and Istanbul Metrobus systems. Extended wheelbases accommodate larger cell pack volumes.
- Mini Bus:8-9 meter configurations penetrate last-mile feeder services and low-density suburban routes. Indian operators in Tamil Nadu industrial corridors specify these for narrow urban streets.
- Double Decker Bus:Two-level passenger compartments dominate London's iconic fleet renewal. These platforms require specialized battery placement to maintain lower deck headroom.
Standard Bus leads procurement volumes. Articulated Bus is gaining share fastest through BRT corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charging depot megaprojects and battery supply corridors are underwriting geographic specialization across the electric bus value chain. Grid interconnection capacity and state-backed procurement quotas determine where fleet electrification accelerates fastest.
China
Shenzhen's 16,000-unit all-electric municipal fleet anchors procurement volumes. MIIT supervision enforces GB/T charging interoperability standards and provincial procurement quotas for state-owned transit authorities. Zhengzhou and Xiamen industrial corridors concentrate final assembly capacity for domestic and export markets.
Germany
Berlin and Hamburg metropolitan planning organizations tender 12-meter and articulated configurations under EU Green Deal fleet decarbonization mandates. The KBA enforces UNECE R100 battery safety certification and WLTP range validation for platform homologation. Baden-Württemberg suppliers cluster around Stuttgart for powertrain component engineering.
United States
Los Angeles Metro and New York MTA access Federal Transit Administration formula grants tied to EPA tailpipe-equivalent emission rules. California Air Resources Board zero-emission bus regulations mandate 100% electric procurement by 2040. Proterra's South Carolina assembly plant serves southeastern transit agencies.
India
Delhi Transport Corporation and Bengaluru Metropolitan Transport Corporation tender standard and midi configurations under FAME-II subsidy schemes. The Ministry of Heavy Industries administers PLI production incentives for battery pack and electric powertrain assembly. Gujarat and Tamil Nadu industrial corridors attract module suppliers.
United Kingdom
Transport for London specifies double-decker electric platforms for iconic fleet renewal under ZEBRA funding allocations. The Department for Transport mandates 4,000 zero-emission bus deployments by 2024. Manchester and Birmingham metropolitan authorities pilot powertrain-as-a-service contracting models.
Electric Bus Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on cell chemistry and charging hardware. Market structure consolidates around state-backed domestic champions in China, diversified industrial conglomerates in Europe, and venture-capital-backed specialists in North America. Three archetypes dominate: vertically integrated battery manufacturers, chassis-bodybuilder partnerships, and powertrain technology licensors. Competitive moves center on backward integration into cell supply and geographic licensing arrangements for charging protocol compatibility.
Within the state-backed champion tier, BYD Company Ltd. and Zhengzhou Yutong Bus Co., Ltd. exemplify integrated manufacturing structures spanning cell production through final assembly. Proterra Inc. occupies a position among North American fast-charging infrastructure specialists. These three anchors illustrate how geographic origin and capital structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Zhengzhou Yutong Bus Co., Ltd. |
| Proterra Inc. |
| Volvo Buses |
| Daimler Buses |
| Solaris Bus & Coach |
| MAN Truck & Bus |
| CRRC Corporation Limited |
| Xiamen King Long United Automotive Industry |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Ningbo freight corridor anchors cell pack logistics cost dynamics, compressing margins for European assemblers while amplifying price differentiation between battery-integrated and module-importing platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement committees by warranty coverage and domestic content requirements. Price differentiation rests on battery chemistry grade and charging protocol certification, with MIIT-supervised GB/T compliance commanding premiums over uncertified configurations. Cost compression in standard-tier platforms is intensifying because lithium carbonate spot volatility destabilizes OEM quotation windows. School districts exhibit highest price sensitivity due to constrained capital budgets, while state-owned transit authorities prioritize lifecycle cost over upfront expenditure.
Supply Chain Analysis
Contract manufacturing concentration sits with BYD's in-house cell foundries and CATL's dedicated bus module lines, supplemented by Proterra's South Carolina pack assembly. Geographic supply concentration clusters in China, South Korea, and Japan for cathode active materials and cell production. Raw material dependencies draw from Chilean brine extraction, Australian spodumene, and Indonesian nickel processing. Single-source vulnerability in high-power pantograph assembly exposes European operators to extended lead times. Distribution runs through provincial transit authority procurement committees and third-party fleet management specialists in UK and Netherlands markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service model fragmentation creates white-space opportunities as powertrain-as-a-service contracting displaces traditional bundled procurement across municipal networks.
For Market Incumbents: Entrench position through backward integration into solid-state cell chemistry and captive LFP supply from Zhengzhou industrial corridors. BYD and Yutong should accelerate GB/T to CCS2 hardware retrofit capabilities before EU homologation cycles tighten. Priority lever: warranty extension to fourteen years to neutralize emerging powertrain-as-a-service specialists. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial corridors offer the most penetrable assembly geography under PLI production incentives. Target battery swapping infrastructure for interurban highway corridors previously reserved for diesel coaches. Go-to-market angle: unbundled maintenance contracts assuming battery degradation risk from municipal balance sheets. For Investors and Strategic Acquirers: The EPA's tailpipe-equivalent emission rule phase-in reshapes the acquisition landscape toward platforms with documented domestic battery content. Long-term viability favors powertrain technology licensors over chassis assemblers in the 5-10 year horizon. Target acquisition archetype: third-party fleet management specialists with established public-private partnership frameworks. Signal to watch: FTA formula grant disbursement velocity as inflection indicator for North American procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell allocation from CATL or BYD foundries against lithium carbonate volatility. |
| Charging Infrastructure Partnership | Locks pantograph hardware compatibility with Siemens or ABB depot systems for European tenders. |
| Platform Standardization | Reduces SKU complexity across 12-meter and articulated configurations for municipal procurement committees. |
| Software-Defined Vehicle Investment | Enables over-the-air thermal management updates extending warranty coverage periods. |
| Geographic Manufacturing Footprint | Positions assembly capacity within FTA grant-eligible zones for Los Angeles Metro and New York MTA. |
Methodological Framework
Initial hypotheses were tested against primary input from transit authority procurement directors, OEM platform engineers, battery cell R&D leads, and third-party fleet management specialists and refined through secondary validation. Sources included MIIT production license filings, EPA tailpipe-equivalent emission rule dockets, FTA formula grant disbursement records, and provincial tender documentation from Shenzhen and Zhengzhou authorities. Bottom-up unit deployment tallies triangulated against top-down value chain estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling vehicle class, propulsion architecture, charging technology, and regional regulatory cluster dimensions. CAGRs were derived from deployment trajectory analysis against infrastructure investment pipelines. Forecast inputs incorporated grid interconnection queue timelines and solid-state battery pilot validation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-capital-backed charging infrastructure specialists would shift outcomes beyond modeled ranges. Lithium carbonate spot volatility and FTA funding authorization cycles constitute primary revision risks. Quarterly review of provincial procurement quota announcements and utility depot interconnection approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
South Korea E-Bike Market