
 Blood Screening Market | 2026-2036
Blood Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Screening Market Intelligence
The consolidation of high-throughput molecular diagnostic reagent manufacturing in Europe and North America is rebalancing the supply landscape for blood screening. Roche Diagnostics leverages its dominance in polymerase chain reaction technology to lead in infectious disease detection. Abbott Laboratories sustains a strong market position through its extensive portfolio of immunoassays and point-of-care devices. Grifols specializes in plasma-derived products and associated screening technologies, controlling a significant portion of that niche market.
Blood screening involves a series of laboratory tests performed on blood or its components before transfusion to a recipient. These procedures are designed to detect specific infectious disease markers, such as viral antigens or nucleic acids, ensuring the safety of the blood supply. Within technology, molecular diagnostics like polymerase chain reaction represent the fastest-growing segment due to their high sensitivity. Transfusion safety remains the primary application, though prenatal testing for genetic disorders is an expanding area of use.
Regulatory frameworks from the US FDA and Europe's EMA mandate stringent testing protocols for blood donations, setting global benchmarks. In China, the NMPA enforces specific GB standards for diagnostic kits, influencing market access and product design for all manufacturers. Stakeholders must now decide how to allocate R&D investment between developing assays for novel pathogens and improving the cost-effectiveness of existing high-volume screening platforms.
Market Dynamics
The imperative to secure national blood supplies against emerging infectious diseases defines the market's central dynamic. Regulatory bodies like the US FDA and Europe's EMA are compelling blood banks to adopt more sensitive detection technologies, accelerating the replacement of older immunoassays.
Growth Catalysts
- Regulatory Mandates:Stricter screening protocols, such as US FDA guidance on testing for transfusion-transmitted pathogens, compel the adoption of advanced molecular diagnostic tests in blood donation centers.
- Healthcare Infrastructure Investment:Large-scale modernization projects in countries like China are expanding the capacity of public blood banks, creating new demand for high-volume screening platforms and reagents.
- Technology Advancement:The superior sensitivity and specificity of nucleic acid testing (NAT) in detecting viral genetic material during early infection windows drives its adoption over conventional serological methods.
Market Restraints
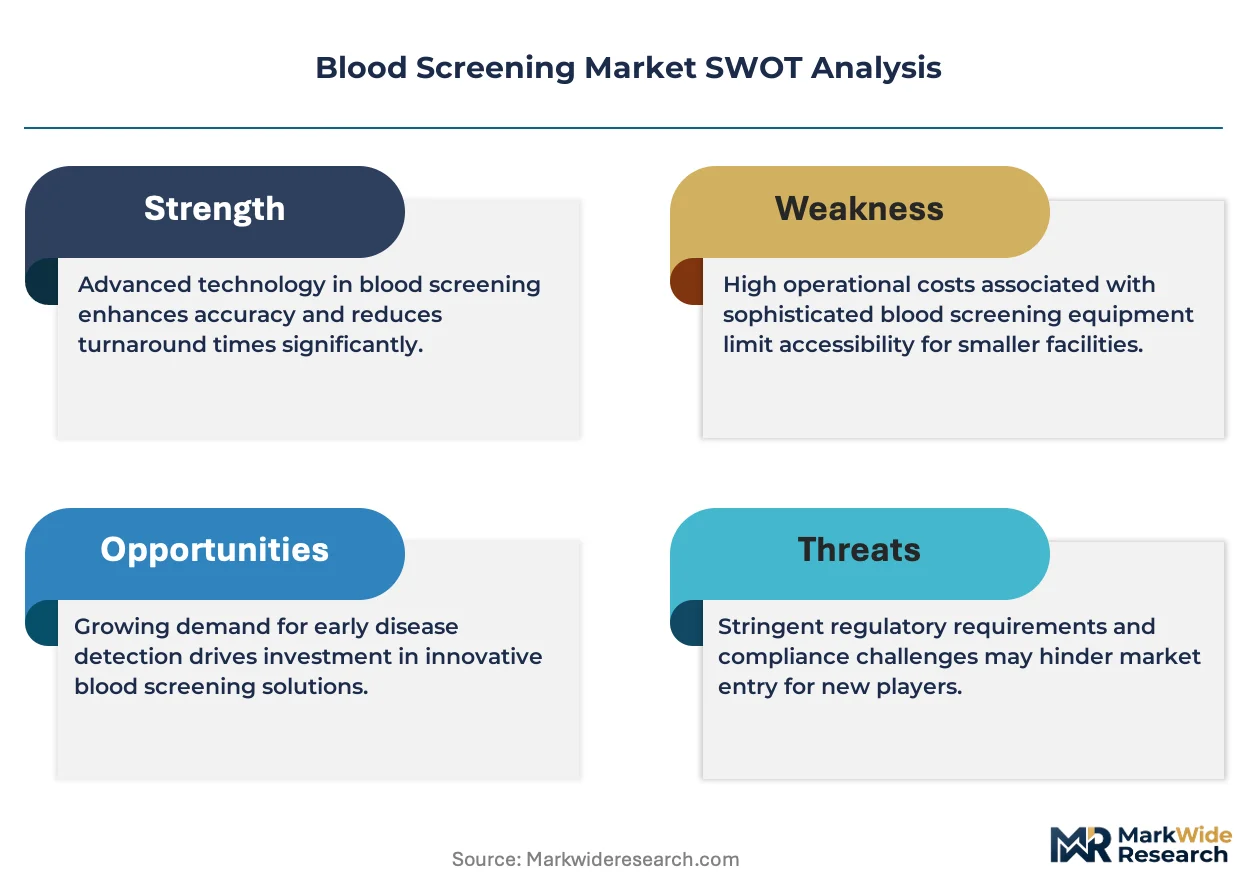
- High Platform Costs:The significant capital investment required for automated molecular diagnostic systems and the high per-test cost of reagents limit adoption in resource-constrained healthcare settings and smaller laboratories.
- Supply Chain Concentration:A few large manufacturers in Europe and North America control the supply of critical enzymes and reagents for polymerase chain reaction tests, creating potential pricing power and supply vulnerabilities.
- Assay Cross-Reactivity:Immunoassays can exhibit cross-reactivity with non-target antigens, leading to false-positive results that necessitate costly and time-consuming confirmatory testing with more specific molecular methods.
Strategic Opportunities
- Prenatal Screening Expansion:The application of blood screening technologies to non-invasive prenatal testing (NIPT) for genetic abnormalities and infectious diseases in expectant mothers represents a significant adjacent market.
- Emerging Market Penetration:Developing screening infrastructure in Southeast Asian and African nations, supported by public health initiatives from organizations like the WHO, offers substantial long-term growth potential.
- Multiplex Assay Development:Creating single tests capable of simultaneously detecting a wide panel of viral, bacterial, and parasitic pathogens offers significant workflow efficiency and cost-reduction benefits for blood banks.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers face significant hurdles in obtaining and maintaining approvals across different jurisdictions, each with unique standards, such as the NMPA's GB standards in China.
- Data Integration Complexity:Integrating high-throughput screening instruments with legacy Laboratory Information Management Systems (LIMS) without disrupting workflows or compromising data integrity is a major operational hurdle.
- Specialized Talent Scarcity:A shortage of medical technologists and bioinformaticians trained to operate, validate, and interpret results from complex molecular diagnostic platforms limits the pace of technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Screening Market |
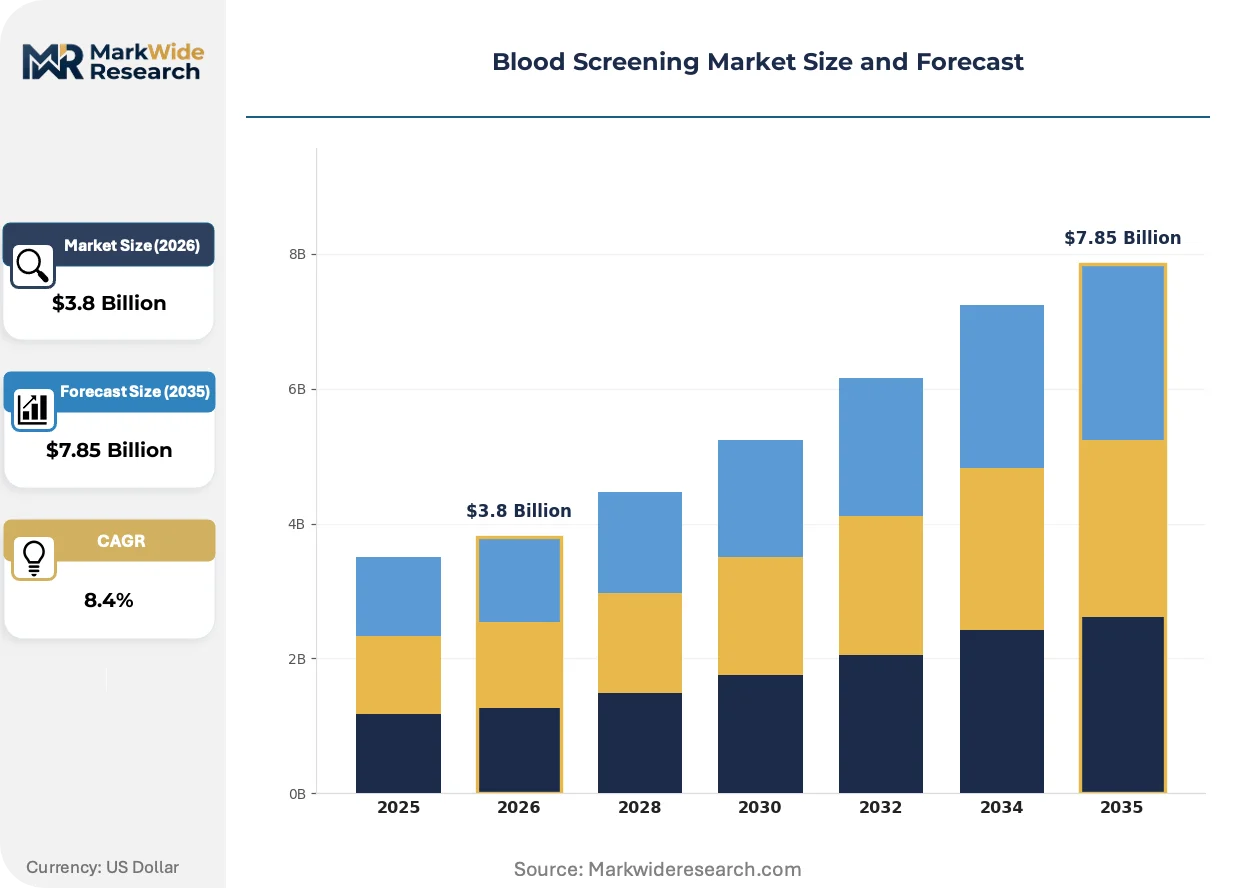
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serology Assays, Molecular Diagnostics, Immunoassays, Point-of-Care Devices, Microscopy Kits Application: Transfusion Safety, Infectious Disease Detection, Genetic Disorder Screening, Drug Abuse Testing, Prenatal Testing End User: Blood Banks, Diagnostic Laboratories, Research Institutes, Plasma Collection Centers, Forensic Labs Technology: Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction, Flow Cytometry, Chemiluminescence, Microfluidics |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Becton Dickinson and Company, Grifols, Bio-Rad Laboratories, Ortho Clinical Diagnostics, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Screening Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards full automation to increase throughput and reduce human error. This technological drive is complemented by tightening regulatory oversight and a shift in procurement models from capital purchases to service-based agreements.
Total laboratory automation (TLA) systems are transforming blood screening workflows by integrating robotic sample handling with analytical instruments. Large national blood banks and high-volume commercial laboratories are the primary adopters of these comprehensive platforms. This technology is automating entire testing processes from sample accessioning to result archiving, which improves traceability and minimizes turn-around time.
Europe's In Vitro Diagnostic Regulation (IVDR) is establishing more rigorous requirements for clinical evidence and post-market surveillance for all diagnostic tests. This change compels assay manufacturers to conduct more extensive performance and validation studies to secure or maintain CE marking. The immunoassay segment is particularly impacted, with many suppliers reformulating products or updating technical files to meet the new, stricter criteria for market access.
A notable behavioral shift is occurring in how plasma collection organizations acquire testing capabilities, moving from direct kit purchases to managed service contracts. This model displaces the traditional capital equipment sales cycle by bundling instrumentation, reagents, and service into a per-test fee. This trend is most prominent within the large-scale plasmapheresis networks operating in North America and parts of Europe.
Blood Screening Market Segmentation
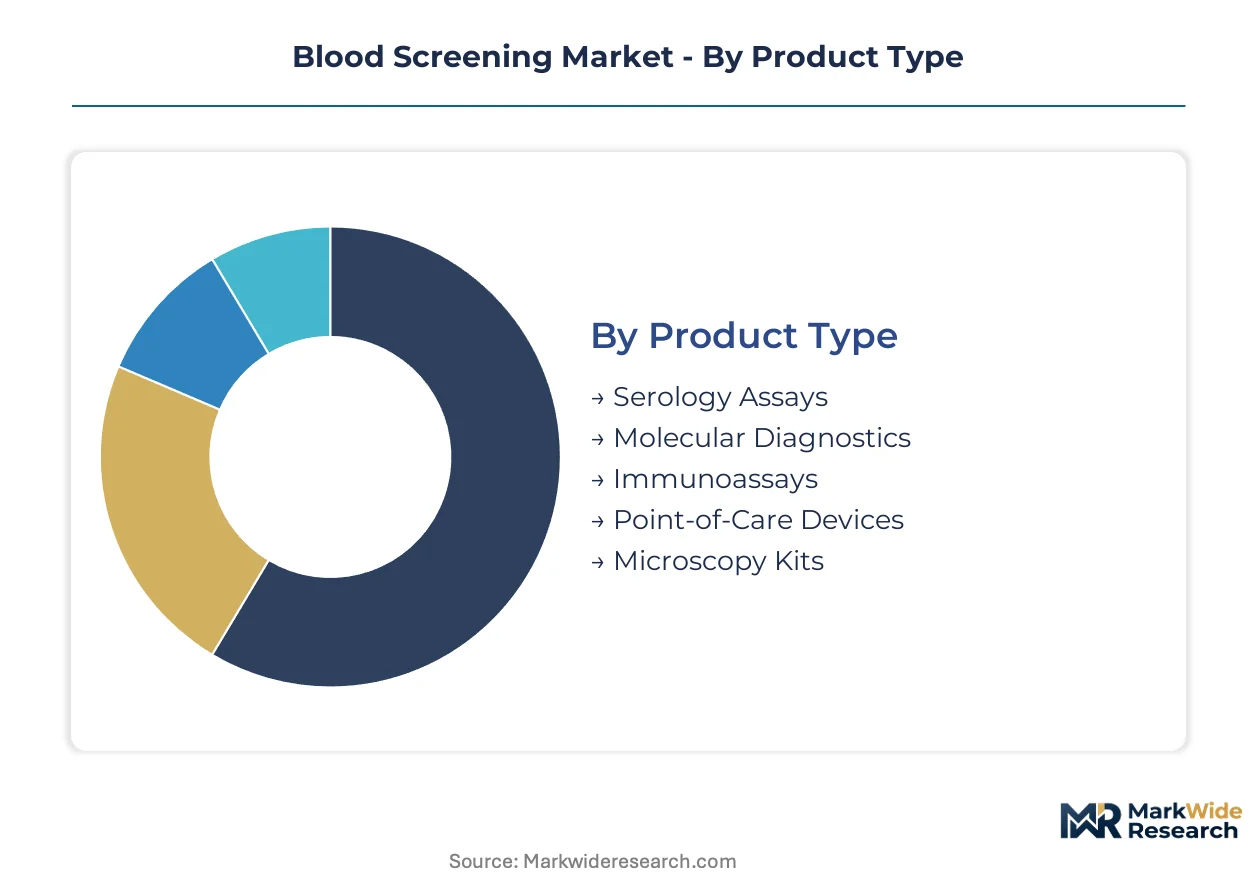
The blood screening market is segmented across diverse product types, applications, end-users, and technologies, reflecting the varied requirements for ensuring blood safety and diagnostic accuracy. Understanding these segments helps stakeholders identify specific growth vectors and allocate resources effectively for both established and emerging needs.
Product Type:
The product type segmentation differentiates between high-volume, cost-effective screening tools and advanced, premium diagnostic platforms.
- Molecular Diagnostics:These platforms utilize nucleic acid testing (NAT) methods like polymerase chain reaction (PCR) to detect viral genetic material with high sensitivity. Regulatory mandates from bodies like the US FDA and Europe's EMA compel blood banks to adopt these advanced tests, particularly in North America and Europe.
- Immunoassays:These tests detect antigens or antibodies in blood samples, offering a balance of speed and cost-effectiveness for routine screening. Abbott Laboratories sustains a strong market position through its extensive portfolio of immunoassays, which are widely deployed in diagnostic laboratories globally.
- Serology Assays:These traditional tests identify antibodies or antigens in serum, providing foundational screening for various pathogens.
- Point-of-Care Devices:Compact and portable, these devices enable rapid testing outside of centralized laboratories, improving accessibility in remote or emergency settings.
- Microscopy Kits:Used for visual examination of blood components, these kits offer a fundamental diagnostic approach, especially in resource-constrained environments.
Today's leader: Molecular Diagnostics. Tomorrow's challenger: Point-of-Care Devices.
Application:
Applications for blood screening span from critical safety protocols to specialized diagnostic procedures, each with distinct regulatory and technological demands.
- Transfusion Safety:This primary application involves screening donated blood for infectious agents like HIV, Hepatitis B, and Hepatitis C before transfusion to recipients. Stringent regulatory frameworks from the US FDA and Europe's EMA mandate rigorous testing protocols to prevent transfusion-transmitted infections in countries like Germany and France.
- Prenatal Testing:This expanding application uses blood screening technologies for non-invasive detection of genetic abnormalities and infectious diseases in expectant mothers. Demand for this testing is increasing in developed markets such as the United States and the United Kingdom.
- Infectious Disease Detection:Beyond transfusion safety, these applications focus on diagnosing specific infectious diseases in clinical settings, often utilizing sensitive molecular methods.
- Genetic Disorder Screening:This segment involves testing for inherited genetic conditions, leveraging advanced molecular techniques for early detection.
- Drug Abuse Testing:Blood screening technologies are also employed to detect the presence of illicit substances or their metabolites in individuals.
Transfusion Safety applications command the largest share, while Prenatal Testing is expanding most quickly.
End User:
End-user segments reflect varied operational scales and specific testing requirements, from centralized processing to specialized research.
- Blood Banks:These facilities are responsible for collecting, processing, and storing donated blood, requiring high-throughput screening platforms for extensive testing. Large-scale modernization projects in countries like China are significantly expanding the capacity and demand for screening in public blood banks.
- Diagnostic Laboratories:Centralized laboratories perform a broad spectrum of blood screening tests for hospitals, clinics, and private patients, often handling complex molecular diagnostics. These laboratories in Canada and Australia require robust data integration with Laboratory Information Management Systems (LIMS).
- Plasma Collection Centers:These specialized centers collect plasma for fractionation into therapeutic products, necessitating specific screening protocols for plasma-derived products.
- Research Institutes:Academic and private research institutions utilize blood screening technologies for disease surveillance, biomarker discovery, and assay development.
- Forensic Labs:These laboratories apply blood screening techniques in criminal investigations and identification, requiring highly specific and reliable methods.
Blood Banks represent the highest volume end-user segment, with Plasma Collection Centers also demonstrating significant procurement.
Technology:
Technology segmentation distinguishes between established, widely adopted methodologies and innovative, high-sensitivity detection techniques.
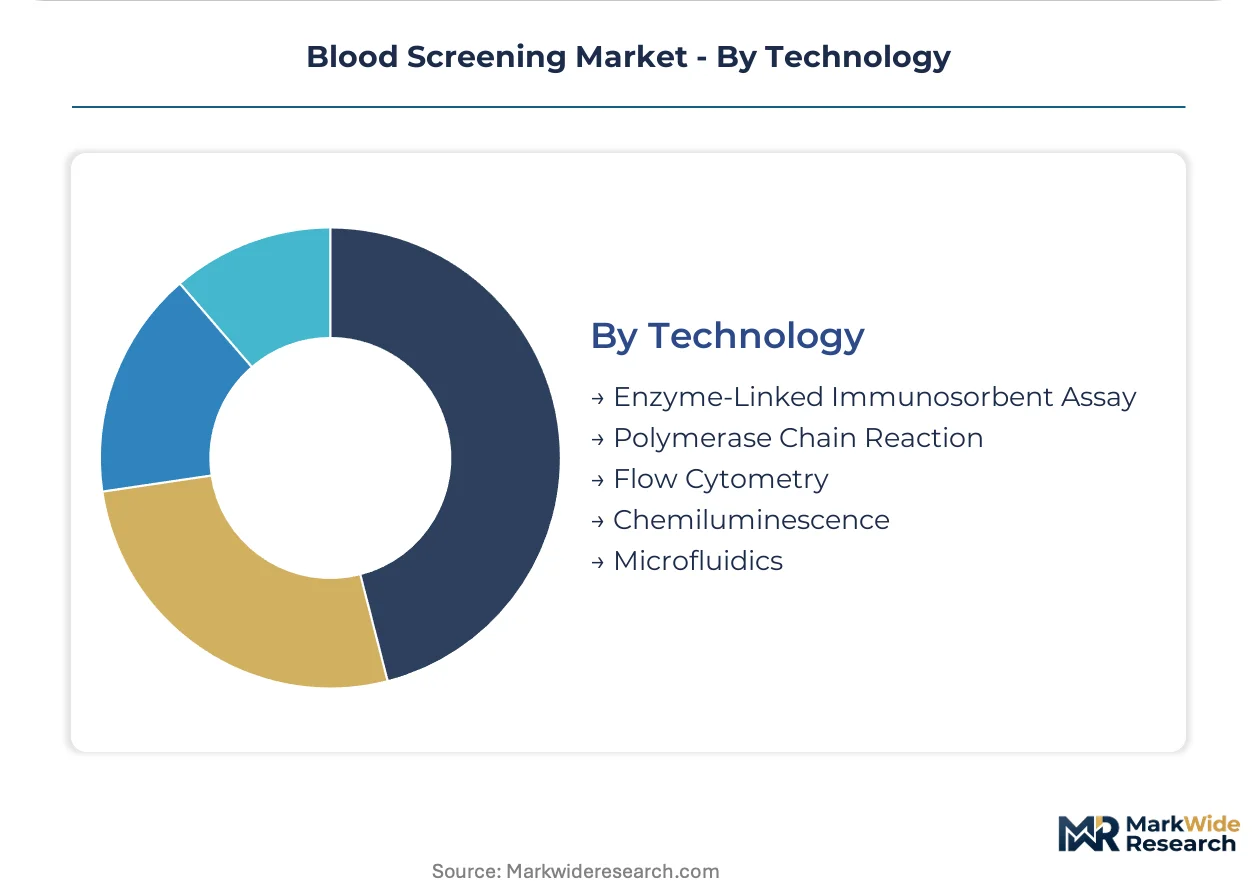
- Polymerase Chain Reaction:PCR represents the fastest-growing segment due to its high sensitivity and specificity in detecting viral genetic material, even in early infection windows. Roche Diagnostics leverages its dominance in PCR technology to lead infectious disease detection, particularly in Europe and the United States.
- Enzyme-Linked Immunosorbent Assay:ELISA is a widely used serological method for detecting antigens or antibodies, known for its cost-effectiveness and adaptability for high-volume screening. This technology remains a cornerstone for initial screening in many diagnostic laboratories across India and Brazil.
- Flow Cytometry:This technique analyzes physical and chemical characteristics of cells or particles in a fluid stream, useful for cell-based diagnostics.
- Chemiluminescence:Chemiluminescence assays offer high sensitivity in detecting analytes, often used in automated immunoassay systems for various markers.
- Microfluidics:This emerging technology enables miniaturized and integrated lab-on-a-chip devices, promising faster and more efficient sample processing for screening.
Polymerase Chain Reaction technology is gaining share fastest due to its superior sensitivity, while Enzyme-Linked Immunosorbent Assay remains foundational.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives innovation in molecular diagnostics, China's extensive healthcare modernization projects are creating significant new demand for high-volume screening platforms. Regulatory frameworks in both regions compel the adoption of advanced testing protocols to safeguard national blood supplies. This dynamic interplay defines regional market evolution.
United States
Demand for advanced blood screening technologies in the United States stems from stringent regulatory mandates for transfusion safety. The US FDA's guidance on emerging pathogens accelerates the adoption of nucleic acid testing. Key innovation hubs like Boston and San Francisco are fostering new assay development for genetic disorders.
China
China's market expansion is driven by large-scale public blood bank modernization and increased testing capacity. The NMPA enforces specific GB standards for diagnostic kits, influencing product design and market access. Major urban centers like Shanghai and Beijing are at the forefront of implementing high-throughput screening platforms.
Germany
Germany's demand for blood screening is supported by a robust healthcare system and strict regulatory oversight from the EMA. The country's IVDR mandates rigorous clinical evidence for diagnostic tests, impacting assay manufacturers. Research institutions in cities like Heidelberg are active in developing novel serological methods.
India
India's growing healthcare infrastructure and rising awareness of blood safety contribute to the demand for screening solutions. The national pharmaceutical regulator focuses on ensuring the availability of cost-effective diagnostic tools for infectious disease detection. Major metropolitan areas like Mumbai and Delhi are expanding their diagnostic laboratory networks.
United Kingdom
The United Kingdom exhibits consistent demand for blood screening driven by public health initiatives and a focus on prenatal testing. Regulatory bodies within the UK align with EMA guidelines for diagnostic test approval. Academic centers in London and Cambridge are pivotal in advancing non-invasive prenatal testing applications.
Blood Screening Market Key Industry Players
North American producers anchor one tier; European specialists hold another, while Asian players focus on scale and regional market penetration. The market structure is moderately consolidated, with a few large manufacturers dominating key technology segments. Strategic archetypes include high-throughput system providers and specialized reagent developers. Dominant competitive moves involve technology licensing and strategic partnerships to expand geographic reach.
Within the molecular diagnostics archetype, Roche Diagnostics and Abbott Laboratories exemplify companies leveraging extensive R&D and broad portfolios. Roche Diagnostics, a Swiss AG, occupies a strong position through its dominance in polymerase chain reaction technology. Abbott Laboratories, a US-based Inc., anchors the market with its extensive portfolio of immunoassays and point-of-care devices. Grifols, a Spanish S.A., represents a specialized player focusing on plasma-derived products and associated screening technologies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| Grifols |
| Bio-Rad Laboratories |
| Ortho Clinical Diagnostics |
| Hologic |
| Others |
Cost & Logistics Intelligence
Vertically integrated diagnostic corporations exert significant influence over pricing and supply, particularly for high-throughput molecular diagnostic reagents. Their scale and in-house capabilities shape market access and cost structures for blood screening technologies.
Pricing Analysis
Capacity additions in Europe and North America are reshaping price floors for molecular diagnostic reagents. The market primarily utilizes contract-based long-term agreements and per-test fee models for high-volume screening. Price differentiation stems from performance validation and comprehensive service bundling. Pricing softness reflects increasing competition among reagent suppliers for high-volume accounts. Resource-constrained healthcare settings and smaller laboratories exhibit high price sensitivity, while large national blood banks prioritize validated performance and integrated solutions.
Supply Chain Analysis
Direct sales forces and specialized distributors manage the complex distribution of blood screening platforms and reagents. Manufacturing concentrates in countries like Switzerland, the United States, and Spain. Supply chains rely on critical enzymes and specialized diagnostic reagents, often sourced from a limited number of producers. A structural risk involves single-source vulnerability for key components, creating potential supply disruptions. Procurement patterns are shifting towards managed service contracts, streamlining logistics for large plasmapheresis networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Blood Screening Market functions as a stable compounder, driven by continuous regulatory mandates for enhanced transfusion safety. This consistent demand ensures steady expansion across the forecast horizon.
For Market Incumbents: Hedge against emerging pathogen threats by accelerating R&D into multiplex assay development. Invest in total laboratory automation to enhance workflow efficiency and mitigate specialized talent scarcity. Secure long-term reagent supply contracts to counter supply chain concentration risks. Leverage existing regulatory expertise to navigate complex approval processes for new diagnostic platforms.
For New Entrants and Emerging Players: Launch via localized partnerships to penetrate developing screening infrastructure in Southeast Asian nations. Focus on cost-effective point-of-care devices for rapid infectious disease detection in remote settings. Target the expanding prenatal testing application with non-invasive solutions. Offer bundled service contracts tailored for smaller laboratories and new blood banks in emerging markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized reagent developers serving niche applications. The market offers sustained growth over the next decade, driven by ongoing public health imperatives. Prioritize acquisition targets with strong intellectual property in nucleic acid testing or advanced automation. Watch for shifts in regulatory frameworks, particularly new mandates for emerging pathogen screening, as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Assay Development | Offers significant workflow efficiency and cost reduction for blood banks. |
| Total Laboratory Automation Investment | Improves traceability and minimizes turn-around time for high-volume laboratories. |
| Emerging Market Infrastructure Partnerships | Creates new demand for high-volume screening platforms in countries like China. |
| Non-Invasive Prenatal Testing Portfolio Expansion | Addresses expanding demand in developed markets such as the United States. |
| Managed Service Contract Adoption | Displaces traditional capital equipment sales by bundling instrumentation, reagents, and service. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a robust market understanding. Primary data involved discussions with blood bank directors, diagnostic laboratory managers, and regulatory affairs specialists. Secondary validation drew from US FDA guidance, EMA IVDR regulations, NMPA GB standards, and relevant company financial filings. This dual approach enabled comprehensive bottom-up and top-down triangulation of market data.
Segment-specific weighting models were applied to analyze market dynamics across the projection horizon. The analytical framework incorporated segmentation by product type, application, end-user, technology, and regional regulatory compliance. Compound annual growth rates were derived from historical data trends and projected future demand. Key forecast inputs included public health spending allocations and regulatory approval timelines for novel assays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unforeseen pathogen outbreaks. All forecasts reflect underlying assumptions regarding technological advancement and healthcare investment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Follicular Lymphoma Treatment Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Multiple Myeloma Market
Hematology
Neutropenia Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Single Blood Drop Analysis Market
Hematology
Sickle Cell Anemia Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Hematopoietic Agents Market