
 Asia Pacific Biochar Market | 2026-2036
Asia Pacific Biochar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Biochar Market Analysis
Australia's expanding pyrolysis facility network is reconfiguring feedstock access patterns across the Asia Pacific biochar supply base. Pacific Biochar leverages its California-derived technology platform to dominate premium agricultural channels in Australian horticulture. ArSta eco anchors its position through backward integration into rice husk collection networks across South and Southeast Asia. MASH Makes competes via containerized, small-scale pyrolysis units designed for distributed biomass processing in Indonesia and the Philippines.
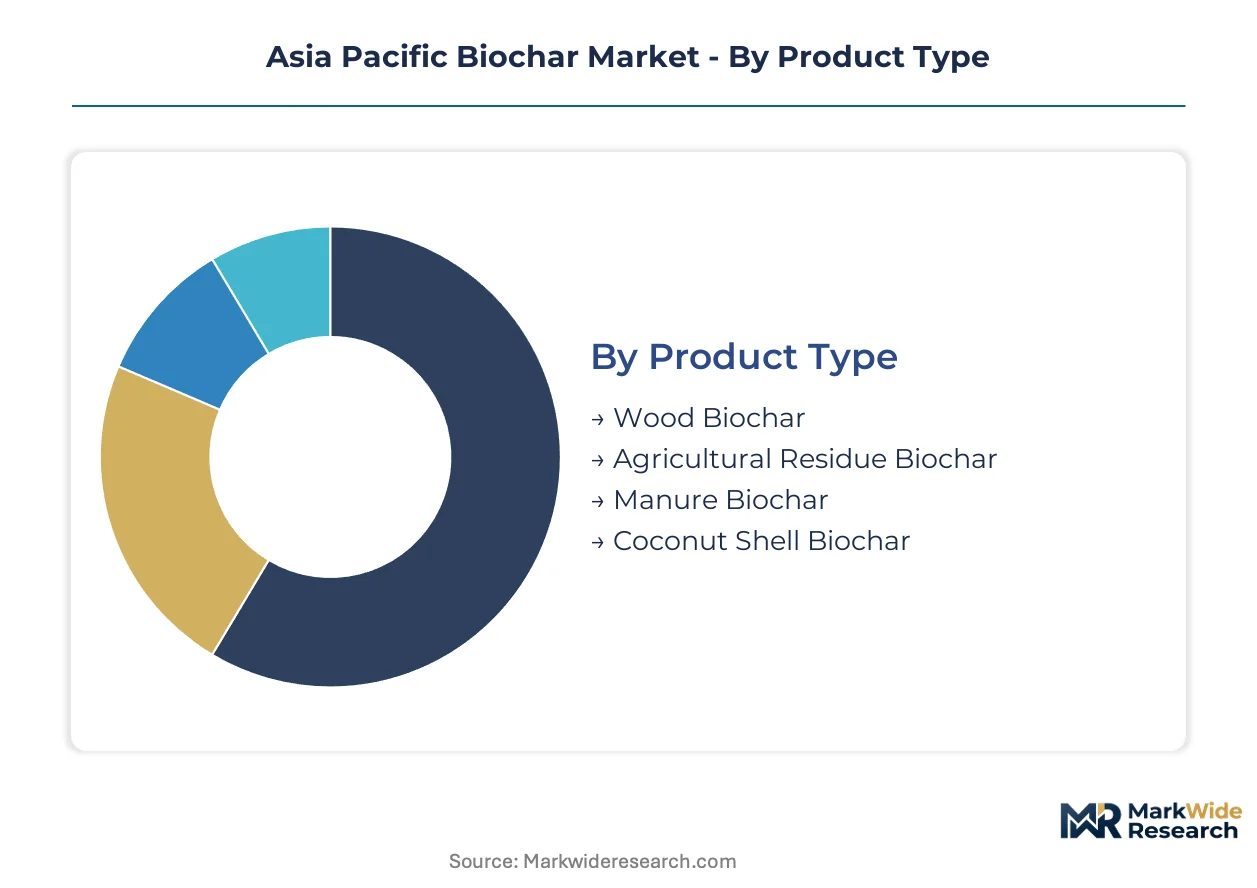
Biochar is a carbon-rich solid material produced through thermal decomposition of biomass in oxygen-limited conditions, typically at temperatures between 350°C and 700°C, yielding a porous structure with high surface area and cation exchange capacity that sequesters carbon while improving soil fertility and water retention. The Asia Pacific Biochar Market segments by product type reveal wood biochar occupying the dominant share due to consistent feedstock availability from plantation forestry residues, while coconut shell biochar represents the fastest-growing category driven by Southeast Asia's copra processing waste streams and premium activated carbon adjacency. Application segmentation shows agriculture and soil amendments commanding the largest volume flow, though water treatment applications are deepening as municipal utilities in Australia and Japan adopt biochar filtration for contaminant removal.
Australia's Clean Energy Regulator and India's BIS standards for soil conditioners are tightening product certification requirements, directly shaping market access thresholds for imported and domestic biochar suppliers. Japan's JIS standards for carbonized materials and METI circular economy guidelines further constrain product specifications while creating compliance-driven demand for certified producers. Stakeholders must monitor evolving carbon credit methodologies and soil carbon measurement protocols, as these frameworks will determine which production technologies and feedstock categories capture premium pricing in regulated offset markets.
Market Dynamics
Carbon credit methodology revisions across Australia and India are restructuring producer economics, favoring pyrolysis operators who can demonstrate permanent carbon removal through third-party soil carbon measurement protocols.
Growth Catalysts
- Australia's Clean Energy Regulator carbon farming framework:Certified biochar projects generate Australian Carbon Credit Units that trade at premiums to voluntary offsets, pulling investment toward compliant production facilities.
- India's PLI scheme for sustainable agriculture inputs:Domestic manufacturers receive production-linked incentives for soil conditioner registration, accelerating farmer-facing distribution buildout.
- Containerized pyrolysis technology:Distributed biomass processing units reduce feedstock transport costs for coconut husk and rice straw in Indonesia and the Philippines.
Market Restraints
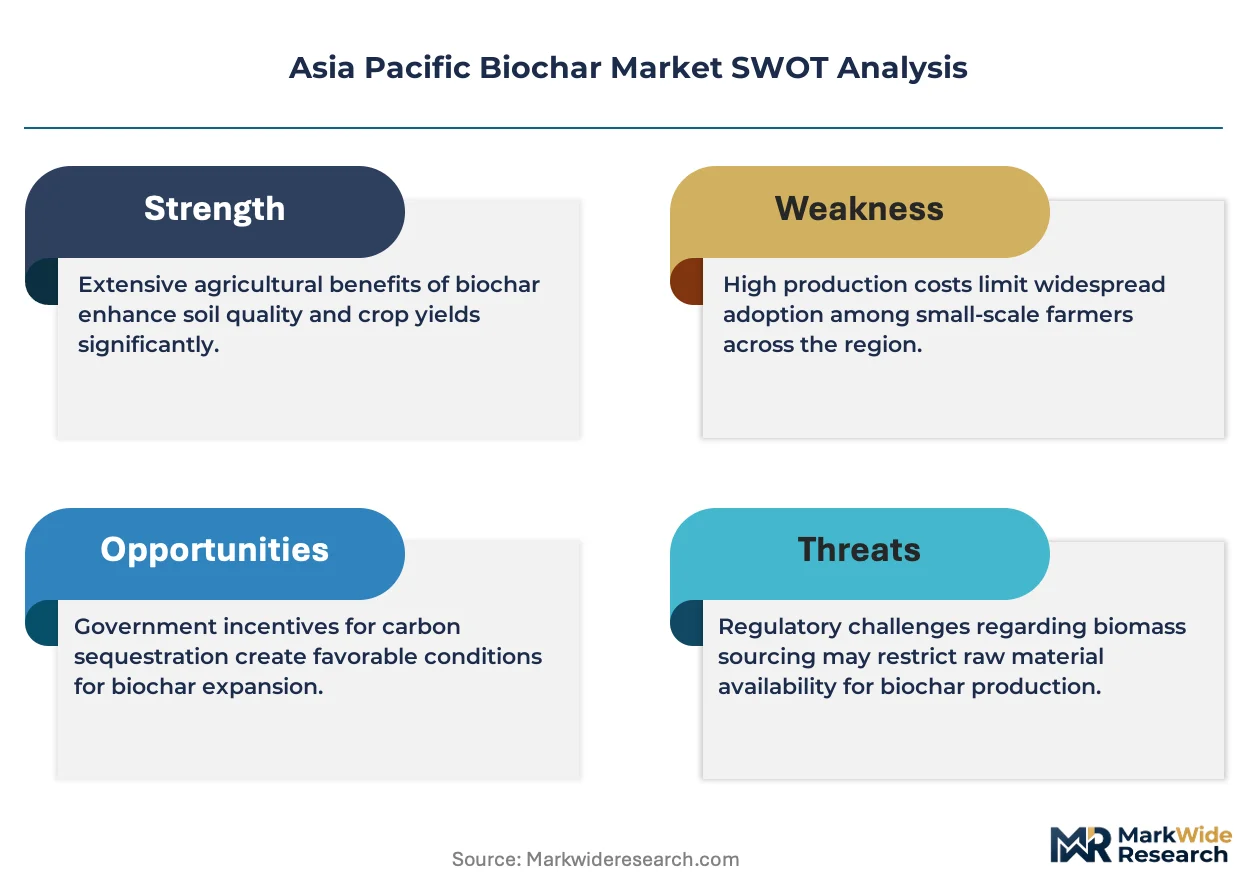
- Feedstock supply concentration:Plantation forestry residue access in Australia and New South Wales is tightening as pulp mills and panelboard producers compete for the same biomass streams.
- Japan's JIS certification timeline:Carbonized material standards require extended laboratory testing and documentation, delaying market entry for imported biochar products.
- Compost substitution pressure:Municipal organic waste composting programs in Australian cities offer lower-cost soil amendment alternatives for broadacre agriculture.
Strategic Opportunities
- Vietnam's Mekong Delta rice belt:Massive rice husk waste generation remains underutilized for biochar production, with minimal organized collection infrastructure currently in place.
- Water treatment application expansion:Australian municipal utilities are piloting biochar filtration for PFAS and heavy metal removal from industrial effluent.
- Digital soil carbon monitoring:Remote sensing and blockchain verification convergence enables real-time carbon credit issuance, attracting climate finance to smallholder-linked projects.
Industry Challenges
- Pyrolysis engineer scarcity:Specialized expertise in oxygen-limited thermal decomposition reactor design and emissions control is concentrated among a limited pool of practitioners across the region.
- Multi-jurisdiction certification stacking:Producers targeting Australia, Japan, and India simultaneously must navigate overlapping but non-harmonized standards for heavy metal limits, particle size distribution, and carbon stability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Biochar Market |
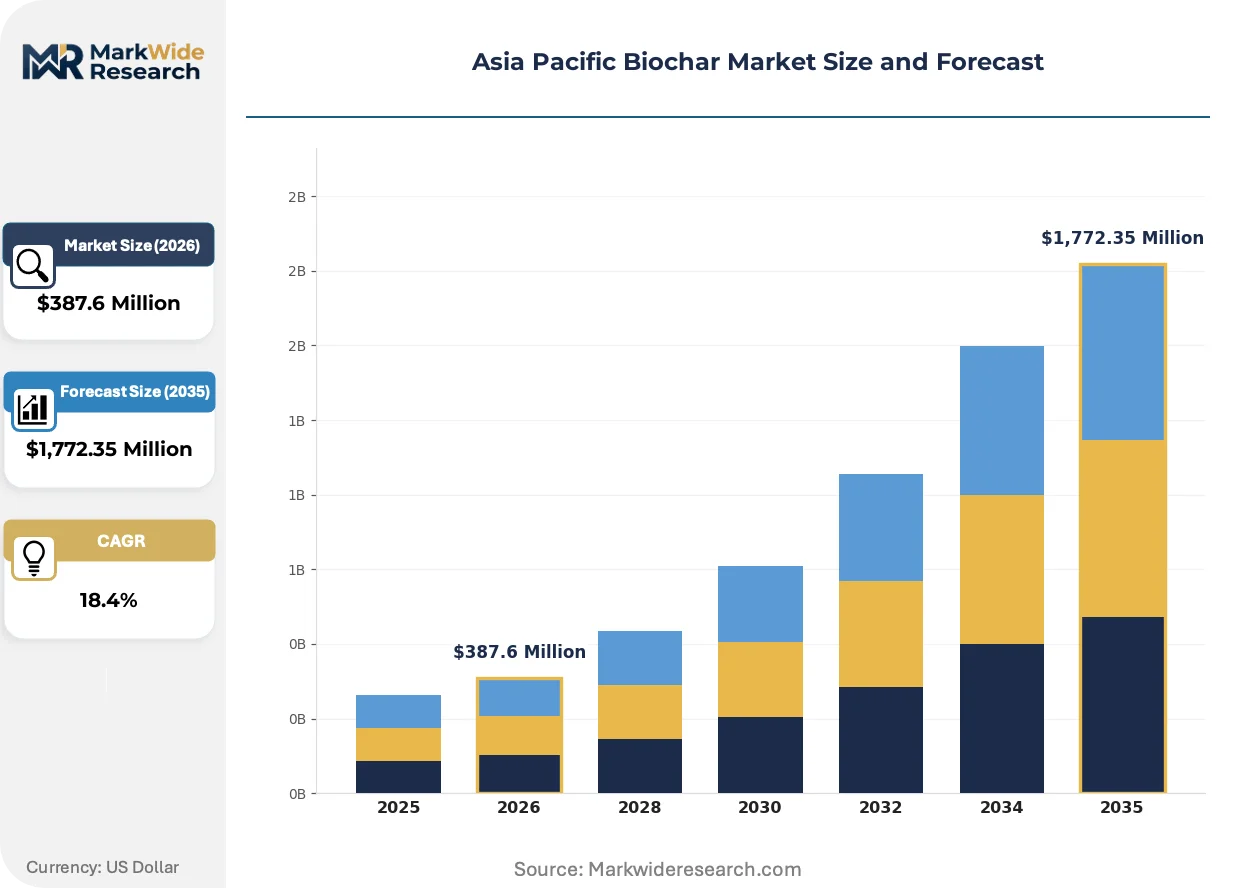
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Biochar, Agricultural Residue Biochar, Manure Biochar, Coconut Shell Biochar Application: Agriculture, Soil Amendments, Water Treatment, Energy Production Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Farmers, Environmental Organizations, Energy Companies, Research Institutions |
| Companies Covered | Biochar Products Inc., Pacific Biochar, ArSta eco, Diacarbon Energy Inc., Agri-Tech Producers LLC, Genesis Industries, MASH Makes, Zhengzhou Kelin Water Purification Material Co., Ltd., BioCarbon Australia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Biochar Market Emerging Trajectories
Pyrolysis technology platforms are fragmenting across scale and feedstock specificity, with divergent engineering approaches emerging for centralized industrial facilities versus distributed rural units.
Continuous-feed slow pyrolysis reactor designs with integrated syngas capture are virtualizing traditional batch kiln economics. Australian horticulture operators adopt these systems for on-farm biochar production at 500-kilogram-per-hour throughput. The technology is virtualizing capital requirements that previously constrained entry to large-scale waste-to-energy players.
India's BIS soil conditioner standards and Australia's Clean Energy Regulator measurement protocols are tightening in parallel, creating compliance complexity for cross-border suppliers. Domestic producers in both jurisdictions are building in-house certification capabilities rather than relying on third-party laboratories. Rice husk biochar faces additional heavy metal testing requirements under these evolving frameworks.
Direct contracting between pyrolysis operators and intensive horticulture growers is displacing distributor-mediated sales in Australian premium vegetable production zones. Queensland and Victoria greenhouse operators negotiate multi-year offtake agreements specifying carbon content, pH adjustment, and mycorrhizal inoculation compatibility. This channel compression is most visible in strawberry and tomato production clusters where input precision directly correlates with yield outcomes.
Asia Pacific Biochar Market Segmentation
Segmentation in the Asia Pacific biochar market reveals how feedstock origin, application intensity, and channel structure determine margin capture. Producers align pyrolysis scale and certification investment against specific buyer price sensitivity and carbon credit eligibility requirements.
Product Type:
Cost tier separation across feedstock categories drives equipment selection and certification strategy for pyrolysis operators.
- Wood Biochar:Derived from plantation forestry residues and sawmill waste, this category delivers consistent carbon content and low heavy metal contamination. Australian horticulture clusters in Queensland and Victoria specify wood biochar for greenhouse substrate integration, paying premiums for batch-certified material meeting Clean Energy Regulator protocols. The established plantation residue collection infrastructure supports centralized production at industrial scale.
- Coconut Shell Biochar:Southeast Asia's copra processing waste streams supply this high-surface-area variant with activated carbon adjacency. Indonesian and Philippine pyrolysis units target water treatment and filtration markets where porosity specifications command price multiples over agricultural grades. Containerized processing technology reduces feedstock transport economics for dispersed coconut husk collection.
- Agricultural Residue Biochar:Rice husk and straw feedstocks dominate this category across India's PLI scheme coverage zones and Vietnam's Mekong Delta collection networks.
- Manure Biochar:Dairy and poultry waste pyrolysis yields nutrient-dense output concentrated in Australian intensive livestock regions and Japanese circular economy demonstration projects.
Wood biochar commands the established base. The steepest expansion runs through coconut shell biochar.
Application:
Application intensity varies sharply between volume-driven soil amendment deployment and specification-heavy filtration contracts.
- Agriculture:Broadacre and intensive horticulture operations apply biochar for soil carbon sequestration, water retention, and cation exchange capacity improvement. India's PLI scheme accelerates farmer-facing distribution buildout for certified soil conditioners. Direct contracting between pyrolysis operators and greenhouse growers in Queensland and Victoria displaces distributor-mediated sales for precision-dependent crops.
- Soil Amendments:Commercial substrate blending and remediation projects require consistent particle size distribution and pH specification. Australian carbon farming projects under New South Wales frameworks generate Australian Carbon Credit Units through documented soil carbon increases.
- Water Treatment:Municipal utilities in Australia and Japan pilot biochar filtration for PFAS and heavy metal removal from industrial effluent.
- Energy Production:Syngas capture and solid fuel applications concentrate in co-located waste-to-energy facilities with integrated pyrolysis units.
Agriculture absorbs the dominant volume flow. Water treatment applications are climbing the fastest as regulatory pressure on contaminant removal intensifies.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and carbon credit documentation needs.
- Wholesale:Aggregators supply bulk agricultural markets across India's state-level fertilizer distribution networks and Australian broadacre farming cooperatives.
- Retail:Garden center and specialty agriculture stores serve smallholder and hobbyist segments with bagged product in urban periphery zones.
- Online:E-commerce platforms expand access for research institutions and environmental organizations requiring small-batch, specification-documented material.
- Direct Sales:Multi-year offtake agreements between pyrolysis operators and intensive horticulture growers specify carbon content, pH adjustment, and mycorrhizal inoculation compatibility in Australian premium vegetable production zones.
Wholesale channels handle the largest tonnage. Direct sales are expanding most quickly as precision agriculture operators seek supply security.
End User:
End user technical sophistication determines product specification stringency and certification documentation requirements.
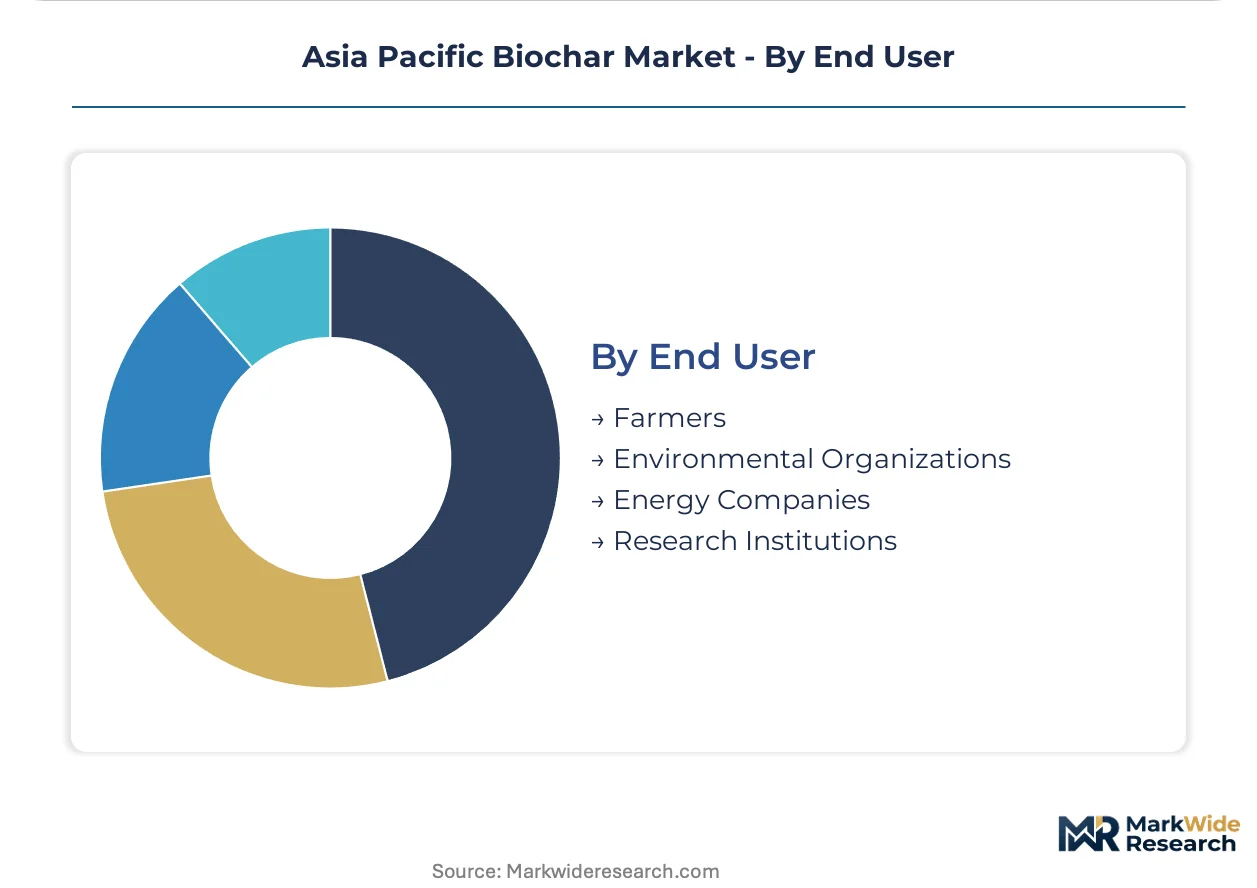
- Farmers:Broadacre operators prioritize cost per hectare and carbon credit eligibility under Australia's Clean Energy Regulator frameworks. Intensive horticulture growers in strawberry and tomato clusters demand batch-specific testing for substrate compatibility.
- Environmental Organizations:Restoration and remediation projects require heavy metal screening and ecological safety documentation for riparian and degraded land applications.
- Energy Companies:Co-processing and syngas utilization applications concentrate in waste-to-energy facilities with integrated thermal treatment infrastructure.
- Research Institutions:Universities and agricultural extension services drive method development for soil carbon measurement protocols and long-term sequestration verification.
Farmers represent the core demand base. Environmental organizations are gaining share fastest as restoration funding expands across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's carbon farming frameworks pull biochar toward soil carbon sequestration and Australian Carbon Credit Unit generation, while India channels production toward PLI-subsidized soil conditioners. Japan and Southeast Asian markets diverge toward water treatment and filtration applications.
Australia
Queensland and Victoria greenhouse operators drive precision horticulture demand for certified wood biochar. The Clean Energy Regulator's measurement protocols constrain import pathways while rewarding domestic pyrolysis facilities with verified carbon credit issuance. New South Wales carbon farming projects concentrate farmer-facing distribution networks around soil carbon verification services.
India
Rice husk and straw feedstocks dominate agricultural residue biochar production across the Indo-Gangetic Plain. The PLI scheme for sustainable agriculture inputs subsidizes domestic soil conditioner registration, accelerating state-level fertilizer distribution buildout. Maharashtra and Karnataka host emerging pyrolysis clusters targeting farmer cooperative networks with BIS-certified product.
Japan
Municipal utilities in Osaka and Tokyo pilot biochar filtration systems for industrial effluent contaminant removal. METI circular economy guidelines and JIS standards for carbonized materials impose extended laboratory testing timelines on imported product. Domestic producers leverage compliance capabilities to capture specification-heavy water treatment contracts.
Indonesia
Copra processing waste streams in Sulawesi and Kalimantan supply coconut shell biochar feedstock for activated carbon adjacency markets. Containerized pyrolysis units reduce transport economics for dispersed coconut husk collection across archipelago geography. Local operators target water filtration export channels rather than domestic agricultural adoption.
Vietnam
The Mekong Delta rice belt generates massive rice husk waste volumes with minimal organized collection infrastructure currently deployed. Provincial agricultural extension services pilot biochar soil amendment demonstration plots without centralized processing capacity. Ho Chi Minh City-based traders aggregate feedstock for cross-border supply to Thai and Cambodian pyrolysis operators.
Asia Pacific Biochar Market Vendor Landscape
Capability concentration sits with technology-originated specialists; scale advantage sits with feedstock-integrated regional operators. The vendor base separates into three tiers: California-derived technology licensors, Southeast Asian rice husk aggregators, and Australian carbon farming integrators. Competitive moves center on backward integration into plantation residue collection networks and multi-year offtake contracting with intensive horticulture growers.
Within the technology-licensor tier, Pacific Biochar exemplifies platform-based market development, while ArSta eco anchors feedstock-integrated positioning across South and Southeast Asian rice husk networks. MASH Makes occupies the distributed-processing archetype with containerized unit deployment. Zhengzhou Kelin Water Purification Material Co., Ltd. represents Chinese material science specialization in filtration-grade carbonized products.
| Leading Market Players |
|---|
| Biochar Products Inc. |
| Pacific Biochar |
| ArSta eco |
| Diacarbon Energy Inc. |
| Agri-Tech Producers LLC |
| Genesis Industries |
| MASH Makes |
| Zhengzhou Kelin Water Purification Material Co., Ltd. |
| BioCarbon Australia |
| Others |
Supply Flow & Price Mechanics
Underutilized pyrolysis capacity in Vietnam's Mekong Delta and Indonesia's outer islands is compressing feedstock procurement costs while forcing Australian operators toward long-term offtake structures to lock in margin visibility.
Pricing Analysis
Long-term offtake contracts dominate premium horticulture channels in Queensland and Victoria, while spot markets handle bulk agricultural grades across India's state fertilizer networks. Three-tier pricing structure across premium, standard, and economy levels separates Clean Energy Regulator-certified material from BIS-registered soil conditioners and uncertified bulk commodity grades. Pricing pressure stems from municipal compost substitution programs in Australian broadacre markets. Intensive greenhouse operators show least price sensitivity; broadacre wheat farmers exhibit highest.
Supply Chain Analysis
Upstream feedstock availability concentrates in Australia's plantation forestry belts, Indonesia's copra processing zones, and India's rice husk collection networks across the Indo-Gangetic Plain. Pyrolysis reactor components, emissions control systems, and soil carbon testing services anchor equipment and service dependencies. Single-source vulnerability runs through specialized pyrolysis engineering expertise concentrated among limited regional practitioners. Distribution runs through wholesale agricultural cooperatives in Australia, state-level fertilizer distribution networks in India, and direct contracting channels for premium horticulture offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: carbon credit certification protocols and soil conditioner registration requirements create switching costs that lock in compliant producers while excluding opportunistic entrants.
For Market Incumbents: Pre-empt emerging containerized pyrolysis competitors by securing exclusive multi-year feedstock agreements with plantation forestry operators in New South Wales and Queensland. Anchor backward integration into rice husk collection networks across South India before PLI scheme subsidies attract additional domestic capacity. Certification investment in parallel BIS and Clean Energy Regulator standards preserves cross-border pricing power.
For New Entrants and Emerging Players: Vietnam's Mekong Delta rice belt represents the most penetrable entry point, with massive feedstock availability and minimal organized collection infrastructure currently deployed. Containerized pyrolysis units sized for 500-kilogram-per-hour throughput unlock distributed processing economics without centralized capital requirements. Target direct sales channels to Australian environmental organizations conducting riparian restoration projects, bypassing established agricultural distribution.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized pyrolysis sub-segments as standardized reactor designs achieve manufacturing scale. Long-term viability over the coming decade hinges on positioning ahead of carbon credit methodology convergence across Australian, Indian, and Japanese frameworks. Acquisition targets should demonstrate in-house certification capabilities rather than third-party laboratory dependence. Watch for JIS standard harmonization proposals as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Captive supply of rice husk and plantation residue insulates margin from pulp mill competition. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, Clean Energy Regulator, and JIS compliance unlocks premium pricing across Australia, India, and Japan. |
| Containerized Pyrolysis Deployment | Distributed processing units reduce transport economics for dispersed coconut husk and rice straw feedstocks. |
| Direct Sales Channel Development | Multi-year offtake agreements with Queensland and Victoria greenhouse operators displace distributor-mediated sales. |
| Digital Soil Carbon Verification Platform | Blockchain-enabled real-time carbon credit issuance attracts climate finance to smallholder-linked projects. |
Methodological Framework
Operator-level perspectives from pyrolysis facility engineers, agricultural extension officers, carbon credit verification specialists, and horticulture procurement managers anchored the qualitative base. Secondary validation drew from Australia's Clean Energy Regulator project registries, India's BIS soil conditioner certification databases, Japan's METI circular economy guidelines, and customs trade data on carbonized material flows. Bottom-up feedstock availability modeling and top-down carbon credit market sizing were triangulated against facility-level production estimates.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption pathways over the analysis window. Segmentation dimensions modeled included feedstock origin, pyrolysis scale tier, application intensity, certification status, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical carbon credit issuance trajectories and soil amendment adoption rates. Forecast inputs incorporated PLI scheme subsidy disbursement schedules and evolving heavy metal testing protocol timelines.
Stress conditions across feedstock price volatility, carbon credit methodology revision frequency, and compost substitution rate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory stability and technology cost curves. Cross-checking against Australia's Clean Energy Regulator project pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
PET Recycling Market
Environment & Sustainability
Solar Frames Market
Environment & Sustainability
Saudi Arabia Medical Waste Management Market
Environment & Sustainability
Europe Carbon Dioxide Market
Environment & Sustainability
Asia-Pacific Industrial Waste Management Market
Environment & Sustainability
Green Building Market
Environment & Sustainability
Hazardous Waste Handling Automation Market
Environment & Sustainability
China Water and Wastewater Treatment (WWT) Technology Market
Environment & Sustainability
APAC Bio-Medical Waste Management Market
Environment & Sustainability
Plant Based Water Filter Market
Environment & Sustainability
Voluntary Carbon Credits Market
Environment & Sustainability
Europe Green Carbon Market
Environment & Sustainability
Mexico Water Consumption Market
Environment & Sustainability
Energy Efficient Window and Door Market
Environment & Sustainability
Shower Water Filters Market
Environment & Sustainability
Middle-East and Africa Industrial Air Quality Control Systems Market