
 Carbon-Aware Slot Booking and Delivery Windows Platforms Market | 2026-2036
Carbon-Aware Slot Booking and Delivery Windows Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon-Aware Slot Booking and Delivery Windows Platforms Market Insights
ISO 14064-1 greenhouse gas quantification and verification certification is reorganizing competitive entry in this space. Microsoft leverages its Azure cloud infrastructure to embed carbon-intensity signals directly into enterprise resource planning workflows. Google Cloud anchors its offering with real-time electricity grid data partnerships that enable minute-by-minute scheduling decisions. WattTime specializes in marginal emissions rate forecasting, differentiating its API layer for logistics software integrators.
Carbon-aware slot booking and delivery windows platforms are software systems that ingest real-time grid carbon intensity data, traffic patterns, and vehicle telemetry to dynamically schedule freight movements during low-emission intervals. These platforms typically process carbon signals at 15-minute or hourly granularity, interfacing with fleet telematics and warehouse management systems to shift load without service degradation. Cloud-based deployment models dominate current implementations, though edge computing solutions are gaining traction where latency constraints prevent round-trip data center routing. Last-mile delivery applications currently absorb the largest share of platform licensing, while cold chain distribution represents the fastest-growing segment due to refrigeration energy sensitivity and perishability windows that compress scheduling flexibility.
The EU Green Deal and F-Gas Regulation impose binding emissions disclosure requirements on freight operators across member states, directly mandating timestamped carbon accounting for logistics procurement. The EPA's greenhouse gas reporting program and emerging state-level clean freight standards in California and New York are creating parallel compliance obligations in North America. Stakeholders must monitor how rapidly carbon intensity APIs achieve standardization, as interoperability between grid data providers and logistics platforms will determine which scheduling engines capture enterprise accounts.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanisms are forcing logistics operators to timestamp every delivery against real-time grid carbon intensity, transforming scheduling software from operational convenience into compliance infrastructure. Third-party logistics providers now face binding scope-three emissions targets that require granular visibility into freight movement timing.
Growth Catalysts
- F-Gas Regulation:Industrial freight corridors across Germany face mandatory decarbonization deadlines, accelerating platform adoption for refrigerated transport scheduling.
- Cold chain distribution:Perishability windows and refrigeration energy sensitivity compress scheduling flexibility, creating demand for carbon-optimized slot allocation.
- Edge computing architectures:Latency-constrained warehouse environments are deploying local processing nodes to enable sub-second carbon signal response without data center round-trips.
Market Restraints
- API standardization gaps:Interoperability failures between regional grid data providers and logistics platforms lock enterprises into single-vendor scheduling stacks.
- Legacy warehouse management systems:Proprietary protocols in installed base equipment resist real-time carbon signal ingestion without expensive middleware layers.
- Grid data fragmentation:Carbon intensity signals vary across transmission operators, creating scheduling discontinuities at jurisdictional boundaries.
Strategic Opportunities
- California clean freight standards:State-level mandates for timestamped emissions accounting create parallel compliance markets beyond EU jurisdiction.
- ISO 14064-1 certification:Greenhouse gas verification frameworks open competitive entry for carbon accounting software vendors meeting audit-grade standards.
- Telematics convergence:Integration of vehicle telemetry with marginal emissions rate forecasting enables minute-by-minute route recalculation during transit.
Industry Challenges
- Carbon accounting talent scarcity:Logistics operators lack personnel trained in ISO 14064-1 quantification methodologies and grid marginal emissions interpretation.
- Real-time data infrastructure capex:Fifteen-minute granularity carbon signal processing requires dedicated stream processing architectures with sub-100ms latency budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon-Aware Slot Booking and Delivery Windows Platforms Market |
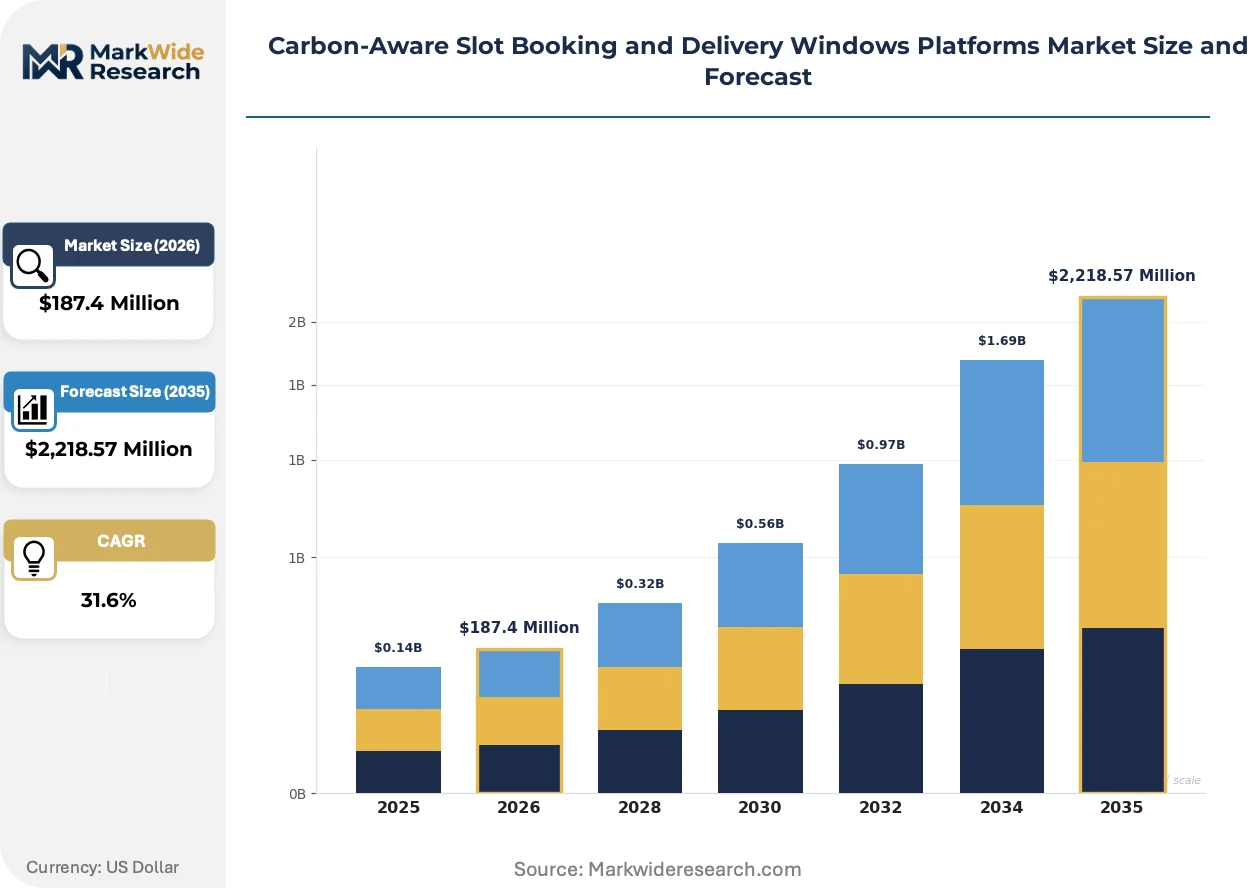
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: AI-Driven Scheduling, Predictive Analytics, Real-Time Tracking, Emission Monitoring, Route Optimization Application: Last-Mile Delivery, Supply Chain Coordination, Fleet Management, E-Commerce Logistics, Cold Chain Distribution End User: Retail Chains, Third-Party Logistics Providers, Food & Beverage Companies, Courier Services, Warehousing Operators Deployment Model: Cloud-Based, On-Premise, Hybrid Systems, SaaS Platforms, Edge Computing Solutions |
| Companies Covered | Microsoft, Google Cloud, IBM, WattTime, Electricity Maps, FlexiDAO, GreenPixie, Compute Gardener, Cirrus Nexus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon-Aware Slot Booking and Delivery Windows Platforms Market Trends and Innovations
Scheduling engines are absorbing capabilities from adjacent software categories, blurring boundaries between fleet management, warehouse control, and sustainability reporting systems. Platform vendors are racing to embed carbon intelligence deeper into operational decision layers.
Edge-native carbon signal processing is fragmenting the incumbent cloud-centric deployment model. Cold chain operators in Germany and the Netherlands are deploying local inference nodes that ingest WattTime marginal emissions data without round-trip latency to Azure or Google Cloud regions. This architecture enables sub-second slot reallocation when grid carbon intensity spikes, though it fragments vendor control over the software stack and complicates centralized audit trails for EU Green Deal compliance.
CSRD disclosure mandates are compressing procurement cycles for carbon-aware logistics software. Large enterprises under the EU Corporate Sustainability Reporting Directive must obtain assured emissions data for scope-three freight categories, forcing logistics procurement teams to specify timestamped carbon accounting in vendor RFPs. Third-party logistics providers serving these enterprises are responding by pre-integrating grid data APIs into their scheduling platforms before contract renewal negotiations.
Buyer procurement patterns are hardening around certification-driven vendor selection. Enterprises with science-based targets are disqualifying logistics providers lacking ISO 14064-1 verified scheduling systems, particularly in pharmaceutical and food manufacturing verticals where emissions disclosure affects brand positioning. This preference shift concentrates contract awards among platform vendors with third-party verified carbon accounting engines, squeezing uncertified competitors from premium freight segments.
Carbon-Aware Slot Booking and Delivery Windows Platforms Market Segmentation
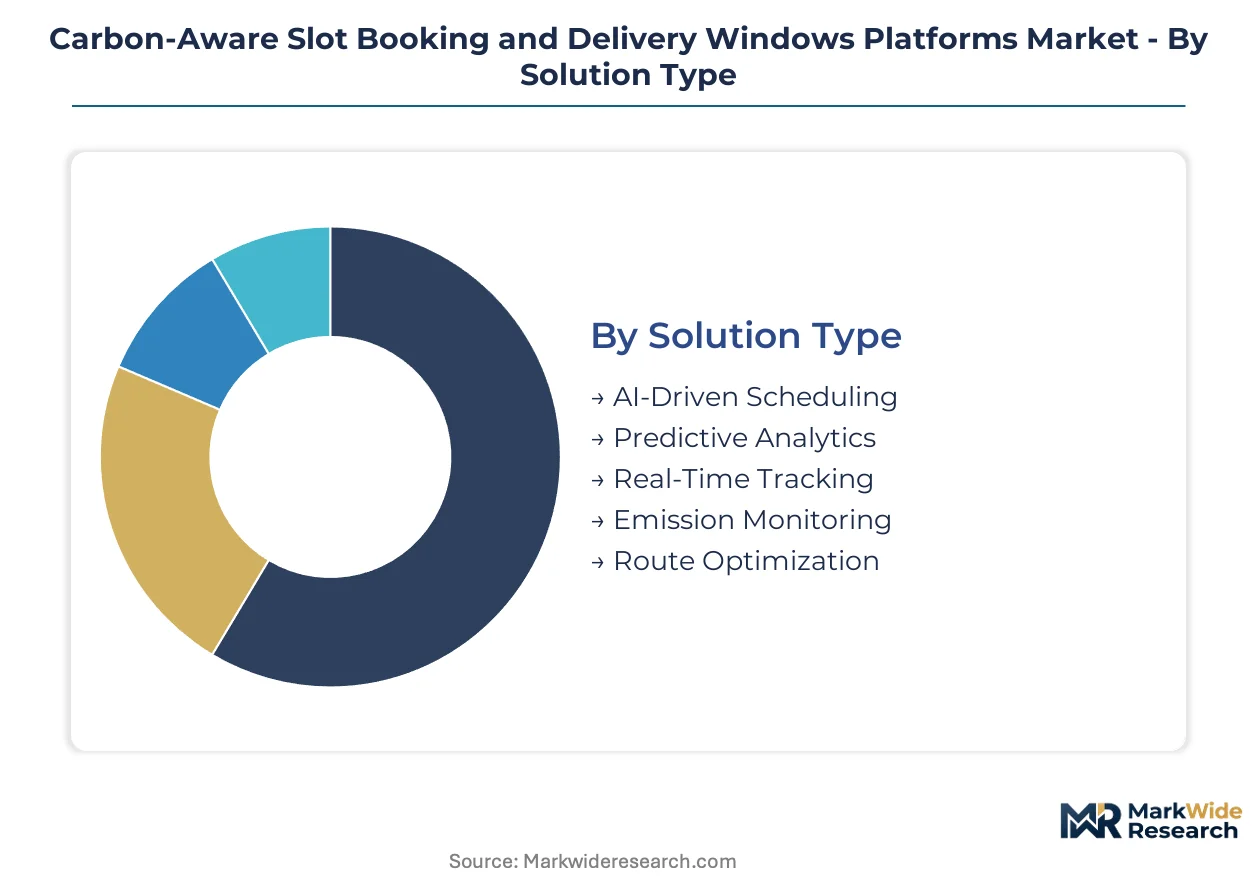
Platform architecture varies sharply by operational context. Cold chain operators prioritize sub-second carbon signal response, while e-commerce logistics networks favor cloud elasticity for demand spikes. Procurement teams increasingly specify deployment models before evaluating feature sets.
Solution Type:
Geographic adoption splits between domestic grid-integrated markets and export-led standardization plays. European freight corridors drive AI-driven scheduling demand, while predictive analytics vendors target North American compliance markets.
- AI-Driven Scheduling:Machine learning engines ingest marginal emissions rate forecasts alongside traffic telemetry to dynamically compress delivery windows. German automotive parts distributors deploy these systems to meet F-Gas Regulation timestamping mandates for inbound component flows.
- Predictive Analytics:Historical grid carbon intensity patterns train models that pre-position inventory before high-emission periods. California clean freight standards are accelerating procurement among drayage operators serving Los Angeles-Long Beach port complexes.
- Real-Time Tracking:GPS-telemetry fusion with 15-minute grid data granularity enables mid-route recalculation.
- Emission Monitoring:ISO 14064-1 audit-grade quantification engines for scope-three disclosure.
- Route Optimization:Static pathfinding augmented with dynamic carbon pricing signals.
AI-Driven Scheduling commands the established base. The steepest expansion runs through Predictive Analytics.
Application:
Cost tier stratification separates premium cold chain deployments from standard last-mile implementations. Refrigeration energy sensitivity justifies higher platform licensing fees.
- Last-Mile Delivery:Dense urban routing with frequent stop compression dominates current licensing volume. Courier services in Dutch cities integrate minute-by-minute grid signals to avoid evening carbon intensity peaks during residential delivery windows.
- Cold Chain Distribution:Perishability constraints and refrigeration load create the tightest scheduling optimization problem. German pharmaceutical distributors face binding EU Green Deal disclosure requirements for temperature-controlled shipments.
- Supply Chain Coordination:Multi-modal handoff synchronization across truck-rail-port interfaces.
- Fleet Management:Vehicle-agnostic carbon accounting across mixed diesel-electric-hydrogen assets.
- E-Commerce Logistics:Surge capacity allocation during promotional demand spikes.
Last-Mile Delivery retains volume leadership. Cold Chain Distribution is climbing the fastest as F-Gas deadlines tighten.
End User:
Customer type fragmentation reflects divergent compliance pressures. Retail chains internalize scope-three accountability, while third-party logistics providers externalize certification costs across client portfolios.
- Third-Party Logistics Providers:Multi-tenant platform architectures serve heterogeneous client emissions profiles. These operators pre-integrate WattTime and grid data APIs to win enterprise RFPs specifying timestamped carbon accounting.
- Food & Beverage Companies:Brand-sensitive emissions disclosure drives premium platform selection. Science-based target commitments force disqualification of uncertified scheduling vendors from refrigerated transport procurement.
- Retail Chains:Private fleet control enables deeper ERP integration.
- Courier Services:Asset-light models favor SaaS deployment with minimal customization.
- Warehousing Operators:Yard management and dock door scheduling optimization.
Third-Party Logistics Providers anchor current deployments. Food & Beverage Companies are gaining share fastest through procurement specification tightening.
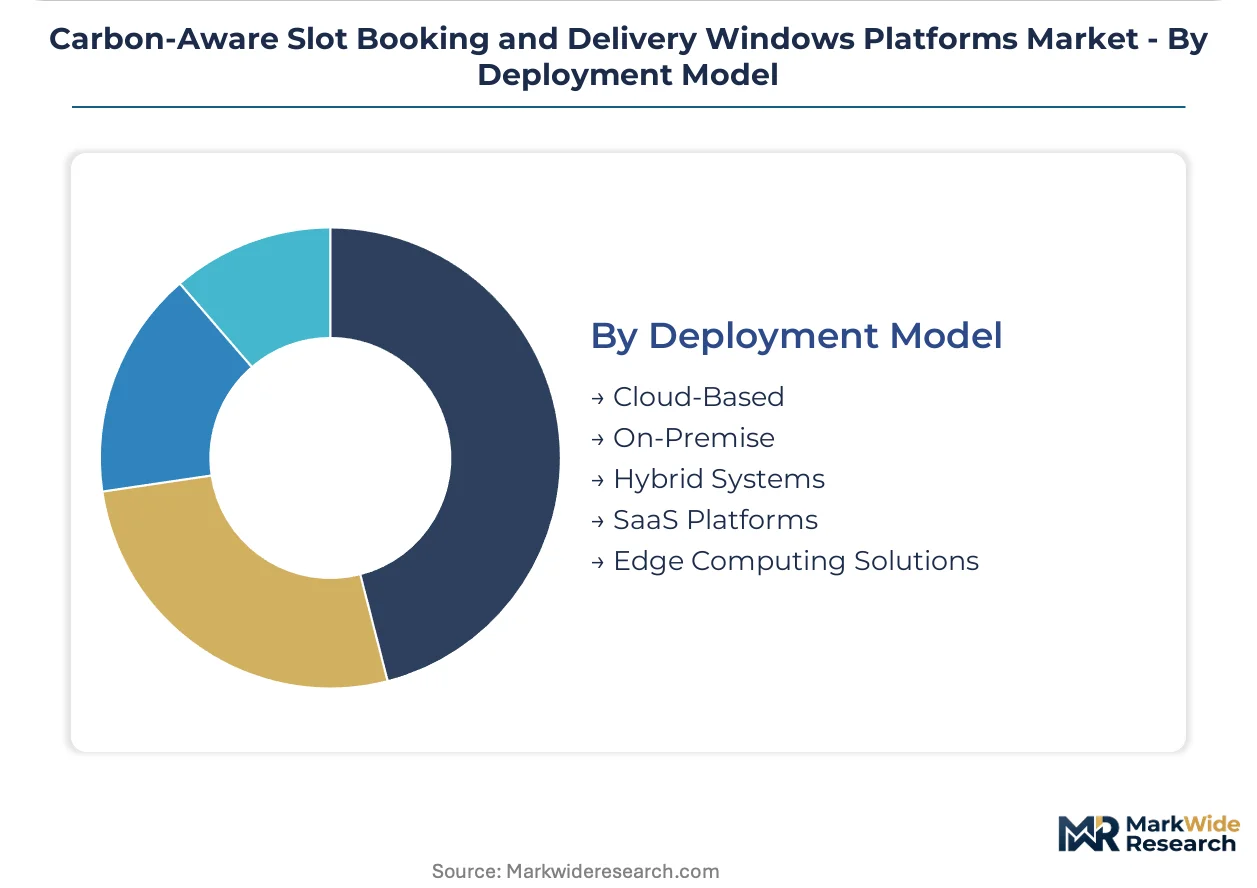
Deployment Model:
Maturity gradients separate established cloud architectures from emerging edge-native alternatives. Latency requirements fragment vendor control over software stacks.
- Cloud-Based:Centralized stream processing handles fifteen-minute granularity carbon signal ingestion at scale. Microsoft Azure and Google Cloud regions host the majority of current enterprise deployments.
- Edge Computing Solutions:Local inference nodes eliminate data center round-trip latency for sub-second slot reallocation. German cold chain operators deploy these at warehouse gates to respond instantly when grid carbon intensity spikes.
- SaaS Platforms:Subscription pricing with standardized API connectors.
- Hybrid Systems:Tiered processing with cloud analytics and edge execution.
- On-Premise:Air-gapped installations for security-sensitive defense or pharmaceutical logistics.
Cloud-Based systems command the established base. Edge Computing Solutions show the steepest expansion trajectory as latency constraints harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon border adjustment mechanisms are forcing logistics operators across multiple jurisdictions to timestamp deliveries against real-time grid carbon intensity, creating divergent compliance pressures that reshape platform adoption patterns by geography.
Germany
Industrial freight corridors face binding decarbonization deadlines under the F-Gas Regulation and national climate protection laws. The KBA enforces emissions disclosure standards for commercial vehicle fleets operating across federal states. Cold chain operators in the Rhine-Ruhr metropolitan region deploy edge-native carbon signal processing at warehouse gates to achieve sub-second slot reallocation during grid intensity spikes.
United States
State-level clean freight standards in California and New York create parallel compliance obligations beyond federal EPA greenhouse gas reporting programs. The California Air Resources Board mandates timestamped emissions accounting for drayage operators serving the Los Angeles-Long Beach port complex. Predictive analytics vendors target Pacific Northwest logistics networks where hydroelectric grid variability demands dynamic scheduling.
Netherlands
Dense urban last-mile delivery networks integrate minute-by-minute grid signals to avoid evening carbon intensity peaks during residential delivery windows. The Dutch Emissions Authority aligns national freight regulations with EU Green Deal disclosure timelines. Courier services in the Randstad conurbation pre-integrate marginal emissions rate APIs to meet enterprise procurement specifications.
United Kingdom
Post-Brexit carbon accounting frameworks maintain alignment with ISO 14064-1 verification standards while diverging from EU CSRD implementation schedules. The Environment Agency oversees scope-three disclosure requirements for logistics operators serving pharmaceutical manufacturing clusters. Cold chain distributors in the Midlands region deploy hybrid cloud-edge architectures to balance compliance audit trails with latency constraints.
France
Science-based target commitments from food manufacturing conglomerates drive disqualification of uncertified scheduling vendors from refrigerated transport procurement. The ANSM enforces emissions traceability requirements for pharmaceutical distribution networks. Logistics platforms in the Île-de-France region embed carbon intelligence directly into ERP workflows serving Paris metropolitan delivery zones.
Carbon-Aware Slot Booking and Delivery Windows Platforms Market Competitive Landscape
Player mix skews toward cloud hyperscalers with embedded sustainability services, creating a tiered structure where infrastructure scale determines carbon signal processing capabilities. Strategic archetypes include grid data specialists with marginal emissions forecasting APIs, ERP-integrated platform vendors, and edge-native latency optimizers for cold chain applications. Dominant competitive moves center on pre-integration partnerships with third-party logistics providers and certification-driven disqualification of uncertified rivals from enterprise RFPs.
Within the cloud infrastructure tier, Microsoft and Google Cloud anchor enterprise deployments through direct ERP workflow embedding and real-time electricity grid data partnerships respectively. WattTime occupies a specialist position exemplifying the grid data archetype, with its marginal emissions rate forecasting API serving logistics software integrators seeking minute-by-minute scheduling granularity. These three entities represent the competitive concentration points around which vendor selection patterns are hardening.
| Leading Market Players |
|---|
| Microsoft |
| Google Cloud |
| IBM |
| WattTime |
| Electricity Maps |
| FlexiDAO |
| GreenPixie |
| Compute Gardener |
| Cirrus Nexus |
| Others |
Pricing and Supply Chain Analysis
ISO 14064-1 certification gates both vendor qualification and price differentiation simultaneously, forcing logistics software providers to absorb audit costs upfront while enterprises with science-based targets pay premiums for verified carbon accounting engines.
Pricing Analysis
Certification level creates the primary spread between premium and standard platform tiers. Cloud-based SaaS subscriptions dominate, with pricing stratifying across ISO 14064-1 verified, CE-marked compliance-grade, and uncertified economy tiers. Cost compression in the economy tier intensifies because hyperscalers bundle carbon signals into existing ERP contracts at marginal cost. Third-party logistics providers exhibit the highest price sensitivity due to multi-tenant cost allocation pressures, while pharmaceutical manufacturers show lowest sensitivity given brand-risk exposure from emissions disclosure failures.
Supply Chain Analysis
Inventory lead times for edge computing hardware stretch delivery windows for latency-constrained deployments. Software development concentrates in the United States, Germany, and the Netherlands, with cloud infrastructure anchored in hyperscaler regions across Ireland, Virginia, and Singapore. Marginal emissions rate APIs draw from WattTime and Electricity Maps data feeds, creating single-source vulnerability when grid data providers alter access terms. Distribution runs through direct enterprise sales teams and third-party logistics integrators serving as channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment—EU Green Deal compliance infrastructure creates switching costs that lock enterprises into verified scheduling stacks once ISO 14064-1 audit trails are established.
For Market Incumbents: Shield market position by deepening API pre-integration partnerships with third-party logistics providers before contract renewal cycles, and accelerate certification investment to disqualify emerging grid data specialists from pharmaceutical RFPs. Microsoft and Google Cloud's embedded ERP workflows represent the primary substitution threat for standalone platform vendors. For New Entrants and Emerging Players: Anchor in the edge computing solutions segment where latency requirements fragment hyperscaler control and cold chain operators seek sub-second carbon signal response outside cloud regions. California clean freight standards offer the most penetrable geography given parallel compliance obligations beyond EU jurisdiction. A go-to-market angle through WattTime API integration partnerships bypasses direct hyperscaler competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based deployment models as hyperscalers absorb infrastructure costs into sustainability service bundles. Long-term viability favors acquisition targets with ISO 14064-1 verified engines and pre-integrated third-party logistics provider relationships rather than raw technology plays. The signal to watch is API standardization progress—interoperability breakthroughs would compress margins for proprietary scheduling stacks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14064-1 Certification Investment | Third-party verification opens enterprise RFP access in pharmaceutical and food manufacturing verticals. |
| Edge Computing Deployment | Local inference nodes enable sub-second slot reallocation for German cold chain operators facing F-Gas deadlines. |
| Grid Data API Partnership | WattTime and Electricity Maps integrations anchor minute-by-minute scheduling granularity for logistics software vendors. |
| ERP Workflow Embedding | Direct integration into Microsoft Azure and Google Cloud environments captures procurement decisions at platform selection stage. |
| California Market Entry | State-level clean freight standards create parallel compliance demand among Los Angeles-Long Beach drayage operators. |
Research Methodology
Initial hypotheses were tested against primary input from sustainability officers at third-party logistics providers, fleet operations directors, carbon accounting consultants, and enterprise procurement managers, then refined through secondary validation against EU regulatory filings, EPA greenhouse gas reporting databases, hyperscaler sustainability disclosures, and ISO certification registries. Bottom-up platform deployment estimates triangulated with top-down market sizing across solution type and application segments.
Variance decomposition across the projection horizon isolates growth contribution by deployment model, end-user vertical, and geographic regulatory cluster. CAGRs were derived from segment-level adoption curves weighted by compliance deadline proximity and carbon intensity API penetration. Forecast inputs include marginal emissions rate data availability expansion and F-Gas Regulation enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable grid data provider economics; material deviation in regulatory enforcement intensity or API standardization progress would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Environment & Sustainability
Environmental Software Market
Environment & Sustainability
South American Waste Management Market
Environment & Sustainability
Carbon Management System Market
Environment & Sustainability
Asia-Pacific Water Purifier Market
Environment & Sustainability
Industrial Air Quality Control Systems Market
Environment & Sustainability
Sustainable and Green Building Materials Market
Environment & Sustainability
Europe Waste Recycling Services Market
Environment & Sustainability
Plant Based Water Filter Market
Environment & Sustainability
Middle-East and Africa Industrial Air Quality Control Systems Market
Environment & Sustainability
UAE Biomedical Waste Management Market
Environment & Sustainability
Landfill Compactor Market
Environment & Sustainability
Europe Industrial Waste Management Market
Environment & Sustainability
Global Voluntary Carbon Credit Trading Market
Environment & Sustainability
ISO Certification Market
Environment & Sustainability
Marine Waste Handling Equipment Market