
 Product Stewardship Market | 2026-2036
Product Stewardship Market Size, Share, and Industry Trends Forecast 2026-2036
Product Stewardship Market Outlook
Retailers and wholesalers is rotating toward direct accountability for end-of-life product recovery, displacing traditional manufacturer-only liability models. ERM Group leverages its consulting footprint across heavy industry compliance programs. Sphera anchors its position through lifecycle assessment software integration. SAP SE competes by embedding stewardship modules within enterprise resource planning ecosystems.
Product stewardship encompasses the systematic management of environmental, health, and safety impacts across a product's full lifecycle from raw material extraction through disposal, incorporating chemical hazard classification, carbon footprint quantification, and circular material flow tracking. Its primary purpose is ensuring regulatory compliance while minimizing ecological externalities and operational risk exposure. Consulting services dominate revenue generation as enterprises navigate fragmented chemical notification requirements across jurisdictions. The automotive vertical absorbs substantial compliance spending due to ELV Directive material restrictions and battery passport obligations. Biodegradable packaging types attract accelerated investment as single-use plastic bans proliferate.
The EPA administers TSCA chemical reporting and RCRA hazardous waste rules that mandate cradle-to-grave tracking in the United States. The EU ECHA enforces REACH substance registration and SCIP database disclosure for articles containing candidate list substances. China's MEE implements GB standard compliance and solid waste import prohibitions that reshape global material recovery pathways. Stakeholders must evaluate how emerging digital product passport requirements will reconfigure data collection infrastructure and supplier verification protocols.
Market Dynamics
Extended producer responsibility mandates are forcing manufacturers to internalize end-of-life costs, converting compliance from a peripheral cost center into a core operational design constraint across electronics, automotive, and packaging sectors.
Growth Catalysts
- EU WEEE Directive revisions:Electronics manufacturers must achieve higher material recovery rates, triggering investment in automated disassembly infrastructure and rare earth reclamation capabilities.
- Automotive ELV Directive material restrictions:Carmakers redesign vehicle architectures to eliminate hazardous substances and enable 85% recyclability by weight, embedding stewardship into platform engineering.
- China's solid waste import prohibitions:Global material recovery pathways reorient toward domestic processing capacity, stimulating circular economy infrastructure buildout across Southeast Asia and South Asia.
Market Restraints
- Specialized chemical hazard assessment talent scarcity:Enterprises face 12-18 month recruitment cycles for toxicologists capable of navigating REACH and TSCA substance notification requirements simultaneously.
- Lithium-ion battery passport data infrastructure costs:Mid-tier automotive suppliers lack capital reserves to deploy blockchain-tracked material provenance systems mandated by EU battery regulations.
- Fragmented national packaging ordinances:Divergent deposit-return schemes across Germany, France, and Italy force parallel compliance architectures that resist economies of scale.
Strategic Opportunities
- India's emerging e-waste rules under E-Waste Management Rules:Formal recyclers can capture informal sector volume through producer responsibility organization partnerships as enforcement tightens.
- Digital product passport convergence with enterprise ERP:Lifecycle assessment software integration with SAP and Oracle ecosystems creates embedded stewardship subscription revenue streams.
- Biodegradable polymer feedstock certification:Industrial composting facilities in the Netherlands and Austria seek verified supply chains for food-contact packaging alternatives to conventional plastics.
Industry Challenges
- Cross-jurisdictional chemical substance database synchronization:Enterprises maintain parallel SCIP, TSCA, and REACH disclosure systems that resist unified data architecture.
- Legacy manufacturing equipment retrofit costs:Foundries and smelters require capital-intensive furnace modifications to process post-consumer scrap with tighter composition tolerances.
- Supplier verification protocol standardization delays:ISO 14001 and ISO 14044 audit fragmentation across certification bodies creates inconsistent environmental claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Stewardship Market |
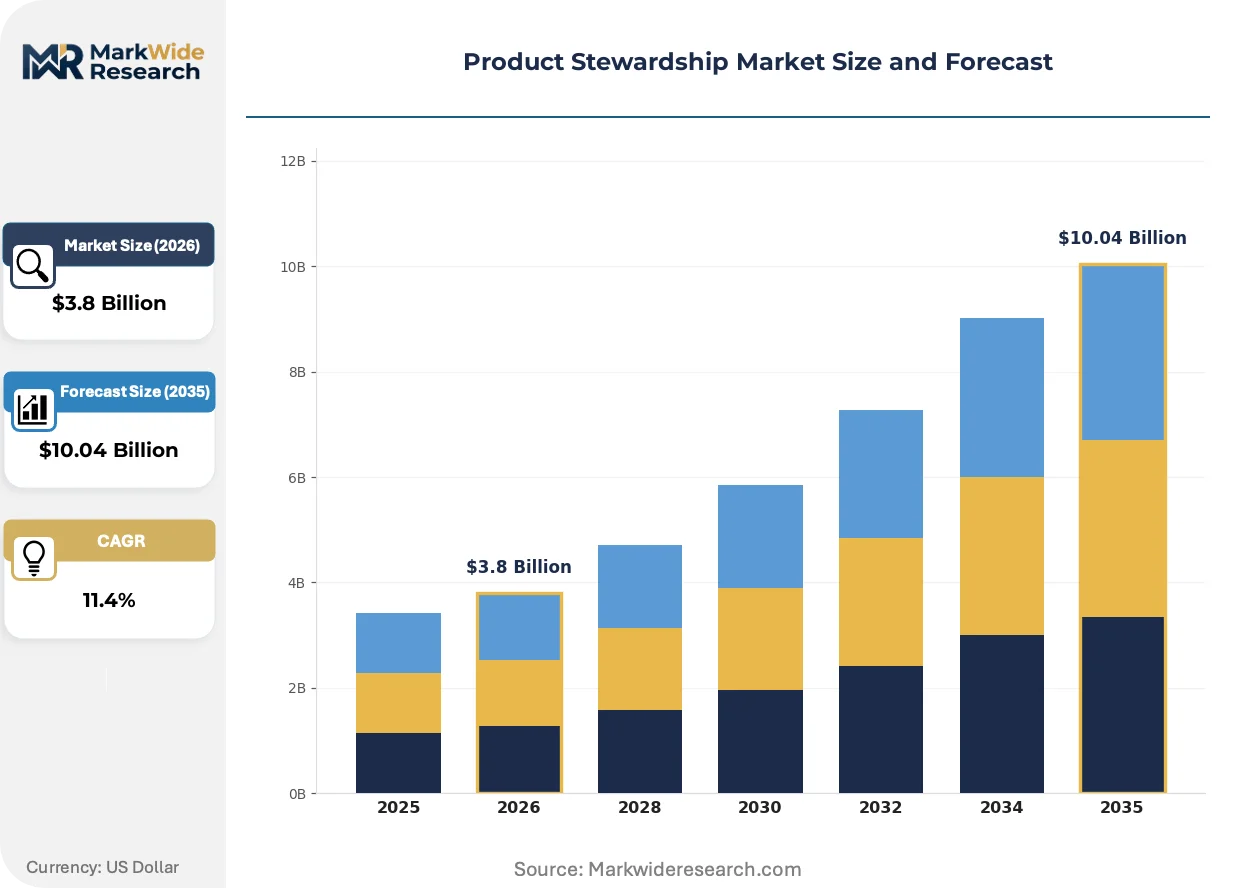
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Compliance Management, Educational Programs, Waste Management Industry Vertical: Consumer Goods, Electronics, Pharmaceuticals, Automotive End User: Manufacturers, Retailers, Wholesalers, Service Providers Packaging Type: Recyclable, Biodegradable, Multi-material, Reusable |
| Companies Covered | ERM Group, Sphera, SAP SE, Gensuite, ENVIANCE, CGI Inc., Enablon, UL LLC, Verisk Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Stewardship Market Strategic Shifts
Digital traceability infrastructure is compressing the gap between regulatory disclosure and real-time operational control, embedding compliance verification into supply chain transaction flows rather than treating it as retrospective documentation.
Blockchain-anchored material provenance systems are decomposing traditional batch-based chain-of-custody documentation. Electronics recyclers in Germany and Japan deploy distributed ledger verification for conflict mineral and rare earth sourcing. This architecture collapses audit timelines from months to minutes, enabling dynamic compliance scoring that determines supplier tiering.
REACH SCIP database disclosure requirements for articles containing candidate list substances have triggered mandatory supplier data collection protocols. Automotive and electronics manufacturers now require full material composition declarations from tier-three suppliers. The obligation cascades through contract terms, with German OEMs imposing penalty clauses for nondisclosure.
Retailer-led take-back program consolidation is displacing fragmented municipal collection infrastructure. French and Belgian supermarket chains operate integrated reverse logistics for packaging and small electronics, capturing customer traffic while meeting producer responsibility quotas. This channel shift concentrates volume with retail incumbents equipped for scale logistics.
Product Stewardship Market Segmentation
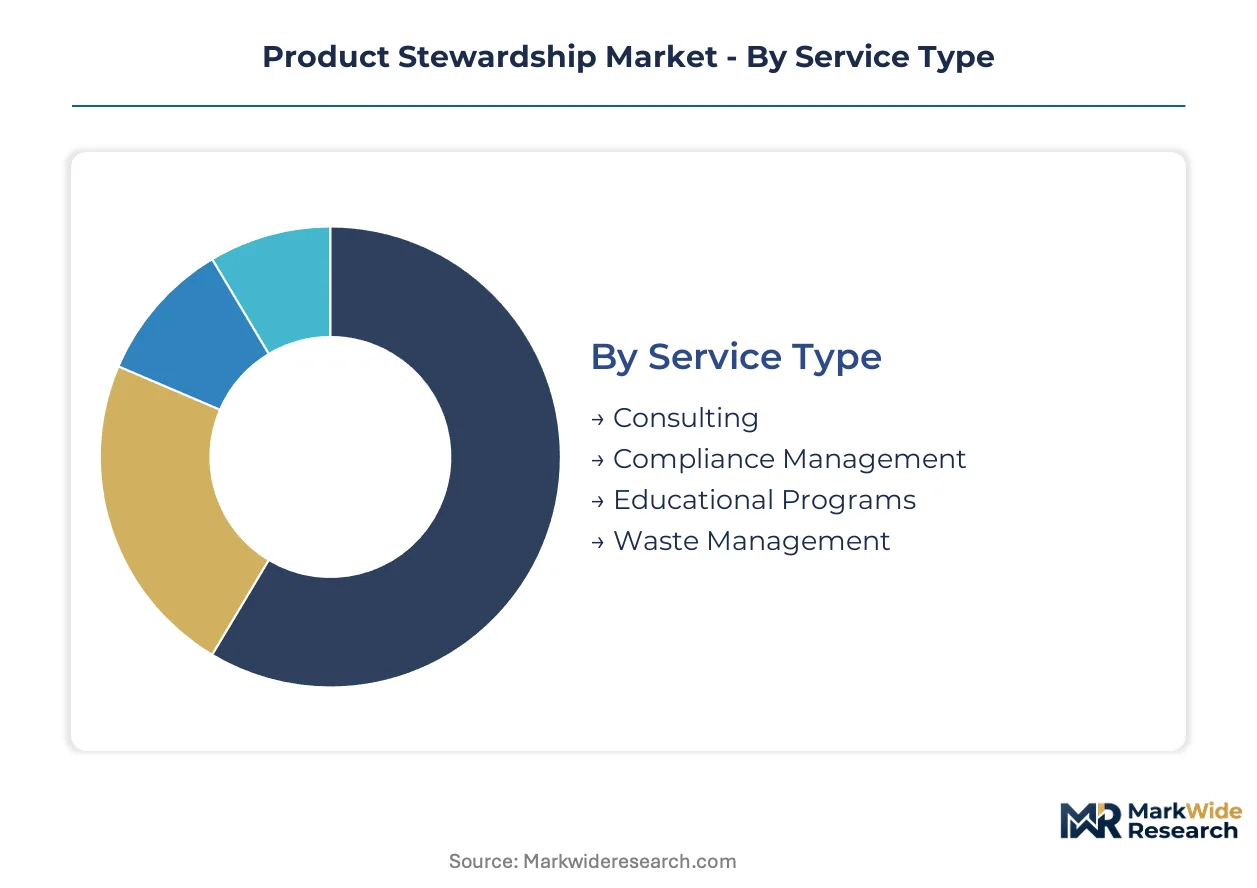
Product stewardship segmentation reveals how compliance obligations fragment across service modalities and supply chain positions. Margin pools concentrate where regulatory complexity intersects with technical execution risk.
Service Type:
Consulting commands premium pricing where substance notification requirements multiply across REACH, TSCA, and emerging digital passport mandates.
- Consulting:Toxicologists and regulatory specialists deliver chemical hazard classification, lifecycle assessment modeling, and jurisdiction-specific filing preparation. German electronics manufacturers and US chemical distributors absorb the highest service intensity as dual-registration obligations expand.
- Compliance Management:Continuous monitoring systems track regulatory deadline calendars, substance volume thresholds, and disclosure database submissions. Automotive OEMs in Stuttgart and Wolfsburg deploy dedicated teams to manage ELV Directive and battery passport parallel obligations.
- Educational Programs:Workforce certification modules address emerging digital traceability requirements and supplier audit protocols.
- Waste Management:Post-consumer collection infrastructure and material recovery facility coordination.
Consulting holds installed capacity. Compliance Management is rotating up the share rankings.
Industry Vertical:
Electronics and automotive absorb disproportionate compliance spending due to material restriction lists and circularity mandates.
- Electronics:WEEE Directive recovery rate targets and conflict mineral sourcing rules demand integrated design-for-disassembly engineering. Dutch and Japanese facilities invest in automated rare earth reclamation to meet tightening material recovery thresholds.
- Automotive:Battery passport data infrastructure and ELV Directive recyclability requirements embed stewardship into platform architecture. German and French OEMs reconfigure supplier contracts to cascade material composition disclosure obligations through tier-three vendors.
- Consumer Goods:Packaging ordinance compliance and single-use plastic restriction navigation.
- Pharmaceuticals:Active pharmaceutical ingredient environmental fate assessment and manufacturing waste characterization.
Automotive holds installed capacity. Electronics is climbing the fastest.
End User:
Retailers are capturing margin pools as extended producer responsibility frameworks shift collection liability downstream.
- Retailers:French and Belgian supermarket chains operate integrated reverse logistics for packaging and small electronics, converting compliance obligation into customer traffic and data capture. Carrefour and Colruyt systems demonstrate scale economics unavailable to fragmented municipal collection.
- Manufacturers:Original equipment producers retain design-phase liability for material selection and end-of-life recyclability. German packaging and electronics producers face direct ordinance enforcement through producer responsibility organization fee structures.
- Wholesalers:Intermediate distribution position creates split liability exposure across upstream sourcing and downstream collection.
- Service Providers:Third-party logistics and recycling contractors executing physical collection and processing.
Manufacturers hold installed capacity. Retailers is gaining share fastest.
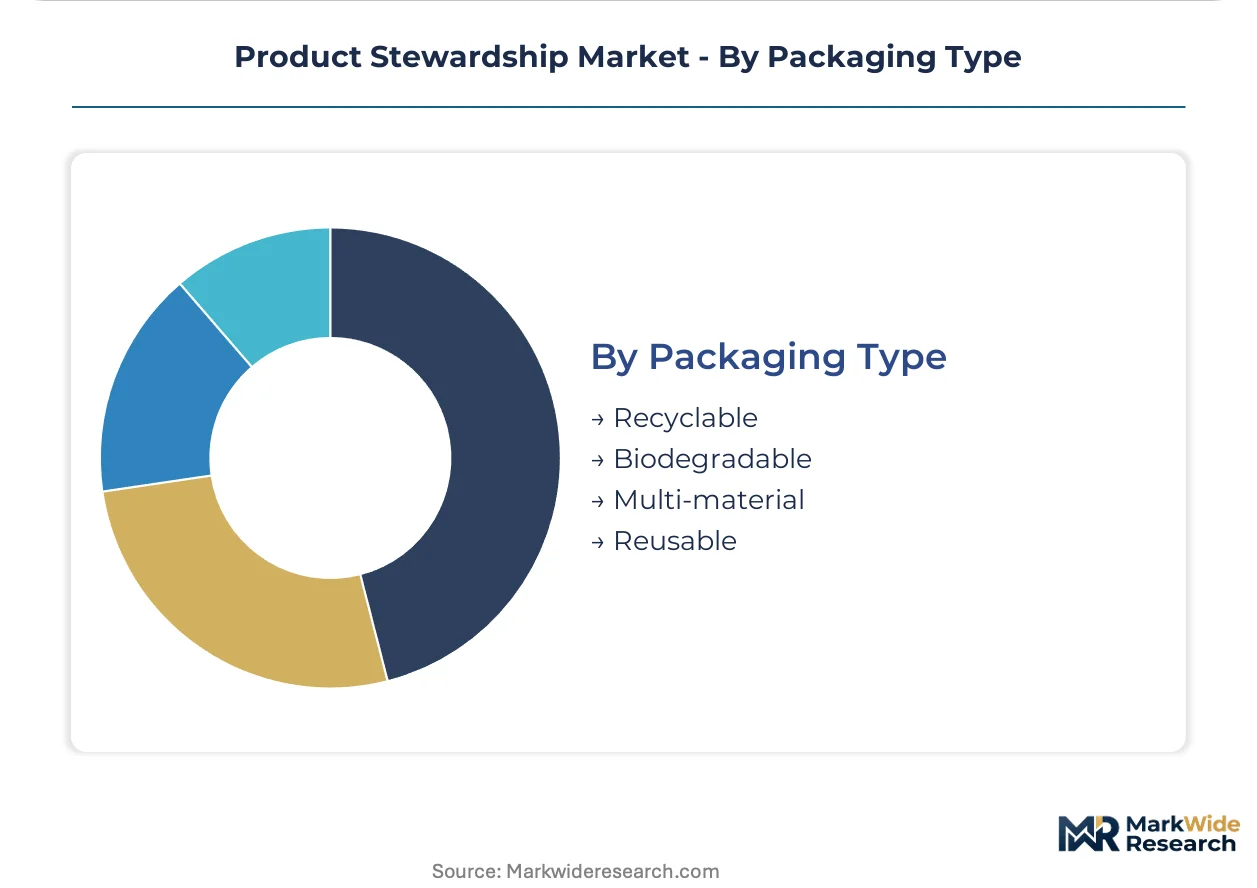
Packaging Type:
Biodegradable formats attract capital as industrial composting infrastructure scales in Northern Europe.
- Biodegradable:Polymer feedstocks certified for industrial composting per EN 13432 and home composting per OK Compost HOME. Dutch and Austrian facilities seek verified supply chains for food-contact applications displacing conventional plastics under single-use bans.
- Recyclable:Mono-material designs achieving closed-loop circulation through established mechanical recycling infrastructure. German dual-system operators dominate volume through Green Dot licensing and sorting facility networks.
- Multi-material:Barrier-functional combinations complicating mechanical separation and reducing effective recovery rates.
- Reusable:Returnable transport packaging and deposit-return container systems.
Recyclable holds installed capacity. Biodegradable is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance infrastructure concentrates in jurisdictions with mature extended producer responsibility enforcement and dense industrial clustering. Germany, the United States, Japan, China, and the Netherlands absorb disproportionate service spending as regulatory complexity intersects with manufacturing scale.
Germany
Packaging ordinance enforcement through producer responsibility organizations drives consulting demand. The country's central environmental authority enforces dual-system licensing fees that scale with material tonnage. Stuttgart and Wolfsburg automotive clusters embed battery passport data infrastructure into supplier contract terms.
United States
Electronics manufacturers face TSCA chemical reporting and state-level e-waste take-back mandates. The national environmental agency administers RCRA hazardous waste rules requiring cradle-to-grave tracking. California and Texas host the densest compliance service provider networks serving chemical distributors and semiconductor fabricators.
Japan
Home appliance recycling law revisions tighten material recovery rate thresholds for air conditioners and televisions. The ministry of economy, trade and industry oversees industrial standards for rare earth reclamation. Osaka and Nagoya electronics manufacturing corridors invest in automated disassembly infrastructure.
China
Solid waste import prohibitions reorient global material recovery pathways toward domestic processing capacity. The ministry of ecology and environment implements GB standard compliance for hazardous substance restrictions in electrical products. Yangtze River Delta industrial zones build circular economy infrastructure for post-consumer electronics processing.
Netherlands
Industrial composting facility expansion attracts biodegradable polymer feedstock certification demand. The national environmental agency enforces packaging waste fund contributions scaling with market placement volume. Rotterdam and Eindhoven logistics clusters integrate reverse supply chain infrastructure for retailer-led collection programs.
Product Stewardship Market Competitive Environment
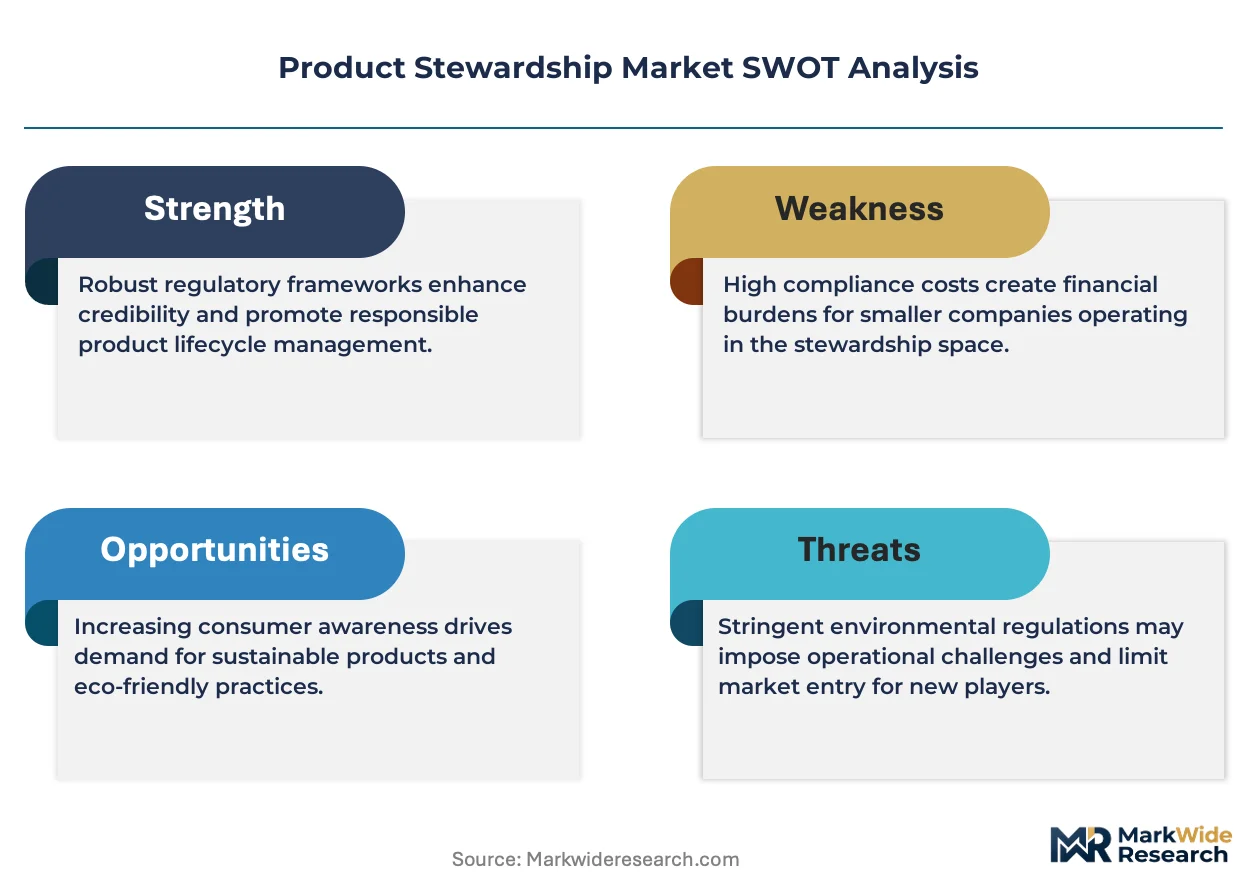
Concentration sits with diversified consulting conglomerates and enterprise software incumbents. The vendor base stratifies across three tiers: global professional services networks, specialized environmental compliance platforms, and embedded ERP module providers. Strategic moves center on lifecycle assessment software integration and producer responsibility organization partnership formation.
Among consulting-rooted service providers, ERM Group and Sphera exemplify the technical advisory archetype, while SAP SE occupies a position within the enterprise software tier. These entities represent contrasting pathways to stewardship capability deployment—external advisory engagement versus internal system embedding.
| Leading Market Players |
|---|
| ERM Group |
| Sphera |
| SAP SE |
| Gensuite |
| ENVIANCE |
| CGI Inc. |
| Enablon |
| UL LLC |
| Verisk Analytics |
| Others |
Value Chain & Pricing Dynamics
Long-term consulting retainer contracts with automotive and electronics manufacturers lock in multi-year revenue visibility while capping rate escalation exposure. These arrangements concentrate pricing power with established advisory firms serving German OEMs and Dutch packaging producers navigating REACH and WEEE compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale engagements from mid-market project scopes. Subscription-based lifecycle assessment software anchors premium tiers, while per-audit compliance management dominates standard offerings. Price differentiation hinges on certification depth—ISO 14001 and REACH SCIP filing expertise commands 40-60% premiums over baseline environmental consulting. Pricing pressure intensifies in waste management services as municipal budget constraints compress collection fees. Mid-tier automotive suppliers exhibit highest price sensitivity due to battery passport infrastructure costs, whereas German packaging ordinance enforcement renders large manufacturers relatively inelastic.
Supply Chain Analysis
Rare earth reclamation facility licensing in Germany and Japan creates chokepoints for electronics recycling throughput. The supply chain draws from China for rare earth processing equipment, Belgium for industrial composting certification standards, and the Netherlands for reverse logistics infrastructure. Single-source vulnerability concentrates in blockchain-tracked material provenance software providers serving EU battery passport mandates. Distribution runs through producer responsibility organizations in Germany and France, with retailer-led collection programs in Belgium and the Netherlands gaining volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Product stewardship sits in early-cycle expansion as digital product passport mandates penetrate automotive and electronics supply chains. Regulatory adoption accelerates faster than enterprise infrastructure deployment, creating temporary capability gaps.
For Market Incumbents: Shield consulting revenue streams by embedding lifecycle assessment tools directly into SAP and Oracle ERP ecosystems before specialized software vendors capture integration contracts. Acquire toxicology talent pools in Stuttgart and Wolfsburg to defend against recruitment competition from battery passport specialists. Certification depth in REACH SCIP filing represents the critical defensive lever.
For New Entrants and Emerging Players: Anchor in India's formalizing e-waste sector where producer responsibility organization partnerships capture informal recycler volume. Target mid-tier automotive suppliers lacking capital for in-house battery passport infrastructure. A compliance-as-a-service model with pay-per-submission pricing reduces adoption friction for capital-constrained tier-two vendors.
For Investors and Strategic Acquirers: Specialized environmental data platforms with pre-built ECHA and EPA regulatory filing modules offer the strongest acquisition profile. Long-term viability rests on recurring revenue attachment rates to enterprise software renewal cycles. Watch for EU battery regulation enforcement intensity as the inflection signal—accelerated penalty issuance would trigger rapid compliance spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Assessment Software Integration | Embedding stewardship modules into SAP ecosystems captures recurring enterprise subscription revenue. |
| Producer Responsibility Organization Partnership | Formal recycler alliances in India and Southeast Asia secure volume under tightening e-waste enforcement. |
| Rare Earth Reclamation Capacity Buildout | Automated disassembly investment in Germany and Japan satisfies WEEE Directive recovery thresholds. |
| Blockchain Material Provenance Deployment | Distributed ledger verification collapses audit timelines for conflict mineral compliance in electronics. |
| Toxicology Talent Acquisition | REACH and TSCA dual-registration specialists command 12-18 month recruitment cycles in tight labor pools. |
Study Parameters
A standing panel of regulatory affairs directors, EHS compliance officers, producer responsibility organization managers, and lifecycle assessment software engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA substance registration databases, EPA TSCA filing records, EU WEEE Directive implementation reports, and automotive OEM supplier contract disclosures. Bottom-up service provider revenue estimates triangulated against top-down compliance spending allocations by vertical.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled service type, industry vertical, end-user category, and packaging format dimensions alongside regional regulatory cluster intensity. CAGRs derived from segmented growth rate reconciliation with macroeconomic elasticity assumptions. Battery passport mandate timelines and packaging ordinance enforcement trajectories served as key forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in EU battery regulation penalty issuance or WEEE Directive revision scope would warrant model refresh. Practitioners should keep alternative scenarios live as digital product passport technical standards and cross-jurisdictional data synchronization protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Marine Waste Handling Equipment Market
Environment & Sustainability
Enriched Biochar Market
Environment & Sustainability
Mexico Water Consumption Market
Environment & Sustainability
Electrocoagulation Market
Environment & Sustainability
Global Automated Marine Debris Collection Equipment Market
Environment & Sustainability
Global Biological Wastewater Treatment Market
Environment & Sustainability
Green Technology and Sustainability Market
Environment & Sustainability
Industrial Waste Management Market
Environment & Sustainability
Sustainable Palm Oil Market
Environment & Sustainability
Electronic Scrap Recycling Market
Environment & Sustainability
Sustainable Construction Market
Environment & Sustainability
Middle East and Africa Solar Panel Recycling Market
Environment & Sustainability
Smart Water Management Market
Environment & Sustainability
Nutrient Recycling Market
Environment & Sustainability
GCC Industrial Waste Management Market
Environment & Sustainability
Solar Panel Recycling Management Market