
 Bangladesh Freight and Logistics Market | 2026-2036
Bangladesh Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Freight and Logistics Market Outlook
Buyer concentration among ready-made garment exporters is repositioning contract terms toward volume-based logistics agreements. DHL Group leverages its bonded warehouse network to serve Dhaka's apparel clusters. A.P. Moller - Maersk anchors container throughput at Chittagong Port with dedicated feeder services. A.H. Khan and Co. competes through overland connectivity to India and Nepal.
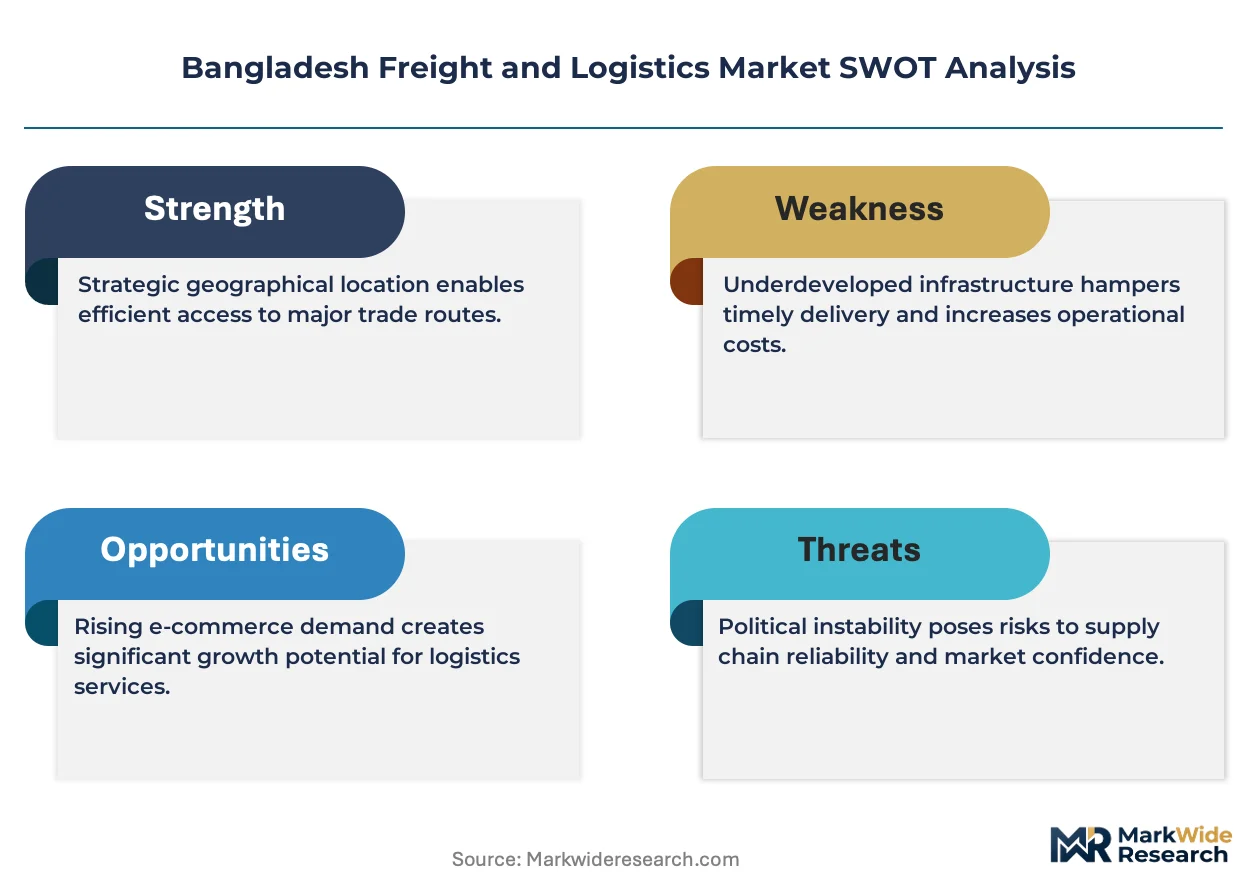
Bangladesh freight and logistics encompasses the multimodal movement of containerized and breakbulk cargo across road, rail, air, and ocean corridors, with road freight handling approximately 70% of domestic tonnage through a network of approximately 22,000 kilometers of paved highways. The sector's primary commercial purpose is to bridge manufacturing zones in Dhaka, Gazipur, and Narayanganj with the Port of Chittagong and international shipping lanes. Road freight dominates service type revenue due to last-mile dependency and limited rail infrastructure, while ocean freight carries the highest absolute cargo volume through Chittagong and Mongla ports. Technology segments show warehouse management systems penetrating large third-party logistics providers first, with GPS tracking diffusing fastest among long-haul trucking fleets seeking fuel optimization.
Bangladesh Road Transport Authority regulations govern commercial vehicle fitness and driver licensing, while Bangladesh Inland Water Transport Authority oversees riverine cargo standards on the Padma and Meghna systems. The National Digital Commerce Policy shapes online business logistics requirements through data localization and consumer protection mandates. Stakeholders must monitor Padma Bridge rail link completion and its redistribution of cargo flows between Dhaka and southwestern manufacturing zones.
Market Dynamics
The Padma Bridge rail link completion is redistributing cargo flows between Dhaka and southwestern manufacturing zones, compressing transit times and altering corridor economics for road-dominant freight operators.
Growth Catalysts
- Ready-made garment export volume:Apparel clusters in Gazipur and Narayanganj are expanding bonded warehouse requirements, pulling dedicated container services toward Chittagong Port feeder networks.
- Bangladesh Road Transport Act enforcement:Digital fitness certification and automated weighbridge deployment are reducing checkpoint delays on the Dhaka-Chittagong corridor.
- Inland waterway rehabilitation:Bangladesh Inland Water Transport Authority dredging on the Meghna system is restoring draft capacity for bulk cement and fertilizer movements.
Market Restraints
- Diesel price volatility:Long-haul trucking fleets absorb fuel cost swings directly due to thin margin structures and limited fuel surcharge pass-through mechanisms.
- Chittagong Port berth congestion:Container vessel waiting times create inventory carrying cost burdens for apparel exporters operating on letter-of-credit timelines.
- Rail gauge incompatibility:Bangladesh Railway's meter-gauge network prevents seamless container transfer with Indian broad-gauge lines, forcing transloading at border points.
Strategic Opportunities
- Sylhet-Dhaka corridor development:Tea and agro-processing clusters in northeastern districts lack integrated cold chain infrastructure, creating white space for temperature-controlled road services.
- National Digital Commerce Policy compliance:Data localization mandates for e-commerce platforms are spawning demand for last-mile fulfillment centers in secondary cities.
- Cross-border Nepal connectivity:Overland routes through Burimari and Banglabandha offer alternative corridors for Indian northeast cargo, bypassing the congested Siliguri chicken neck.
Industry Challenges
- Commercial driver certification gaps:Bangladesh Road Transport Authority licensing backlogs and simulator training shortages extend onboarding timelines for fleet expansion.
- Legacy warehouse management system integration:Family-owned logistics operators face capital constraints and technical debt when migrating from paper-based inventory tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Freight and Logistics Market |
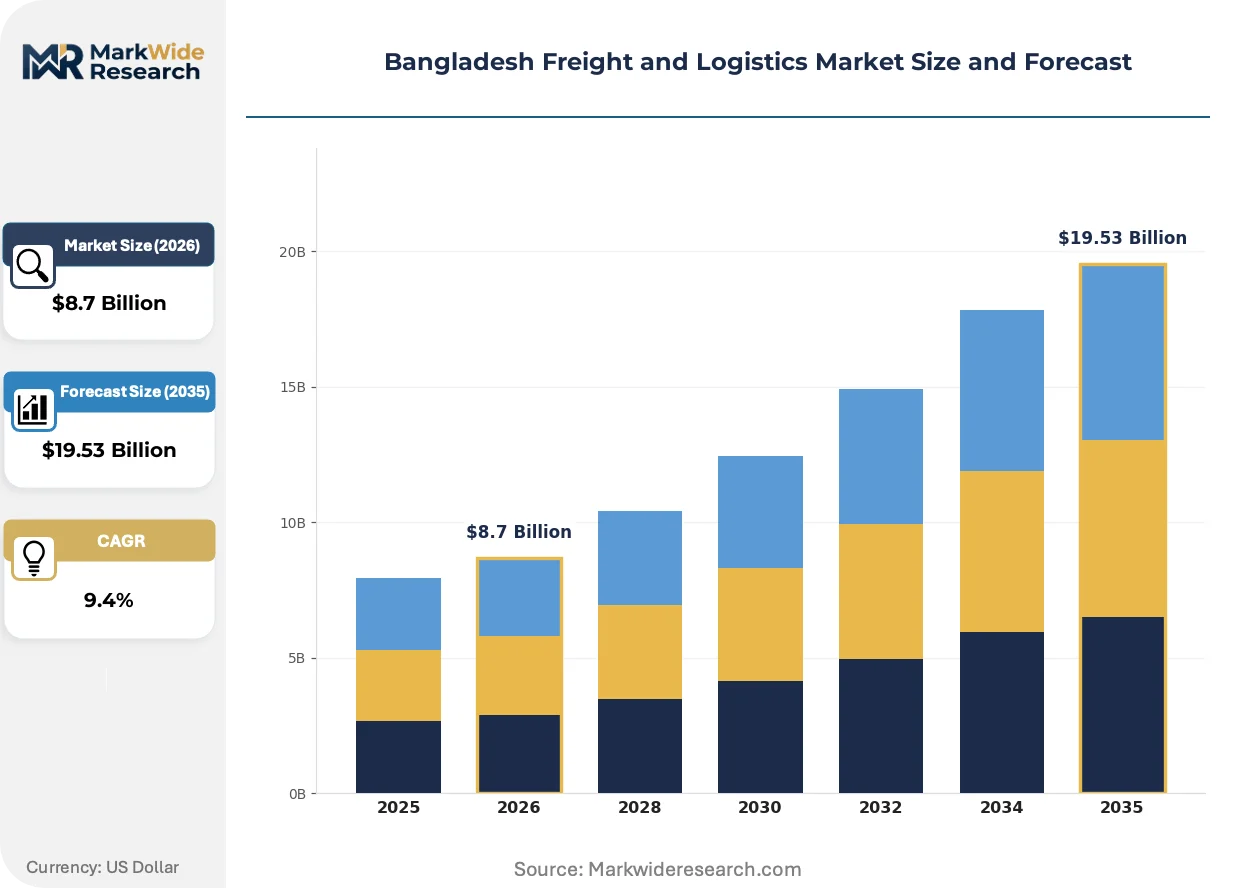
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Ocean Freight Customer Type: Manufacturers, Retailers, Wholesalers, Online Businesses Technology: Warehouse Management System, Transportation Management System, RFID, GPS Tracking Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Brokers |
| Companies Covered | DHL Group, DSV A/S, A.P. Moller - Maersk, Kuehne + Nagel, FedEx, CMA CGM Group, A.H. Khan and Co., Bolloré Logistics, Nippon Express Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Freight and Logistics Market Strategic Shifts
Digital freight platforms are compressing broker margins and consolidating spot market liquidity, while regulatory pressure on emissions and safety standards accelerates fleet renewal cycles.
Telematics and GPS tracking is unifying dispatch operations across fragmented owner-operator trucking networks. Large garment exporters and third-party logistics providers are mandating real-time visibility as a contract precondition. This technology compression is squeezing traditional broker commissions and forcing intermediaries toward value-added customs brokerage.
Bangladesh Road Transport Authority regulations governing commercial vehicle fitness certification are tightening emission and safety inspection protocols. Fleet operators face accelerated replacement schedules for pre-2010 chassis. Dhaka-based container hauliers are responding by consolidating into larger fleet pools to amortize compliance costs across higher asset turnover.
Volume-based logistics agreements are displacing transactional spot contracting among ready-made garment exporters. Large apparel manufacturers are negotiating annual rate contracts with guaranteed capacity provisions. This procurement consolidation is most advanced in Dhaka's Uttara and Tejgaon industrial zones where buyer concentration among European fast-fashion retailers drives contract standardization.
Bangladesh Freight and Logistics Market Segmentation
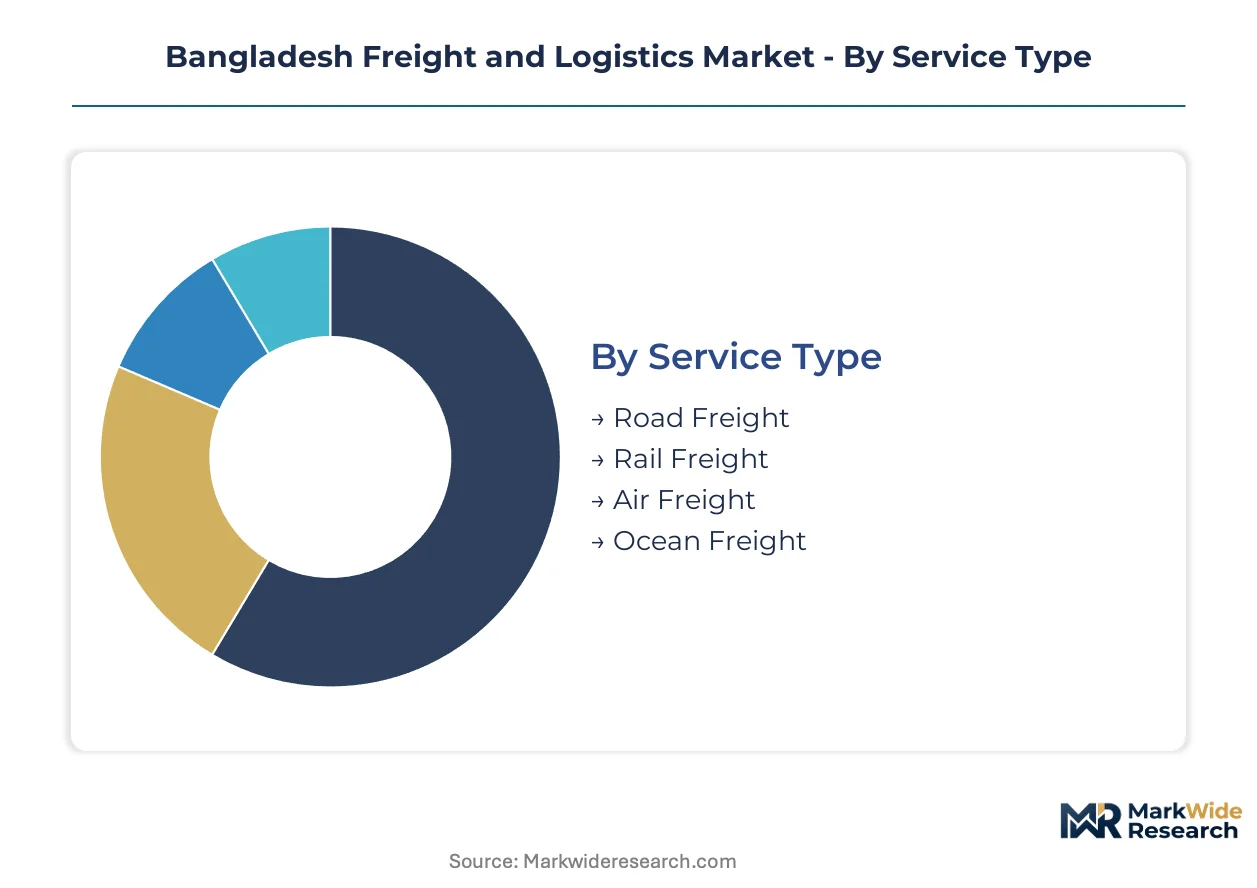
Segmentation in Bangladesh freight and logistics reveals how service capabilities align with the country's export-driven manufacturing base and infrastructure constraints. Each dimension captures distinct procurement patterns among garment exporters, e-commerce platforms, and third-party logistics providers operating across the Dhaka-Chittagong corridor.
Service Type:
Road freight operators concentrate capacity along the Dhaka-Chittagong corridor where garment exporters demand scheduled container movements, while rail and waterborne alternatives compete on bulk cargo economics.
- Road Freight:Handles approximately 70% of domestic tonnage through a network of approximately 22,000 kilometers of paved highways. Dhaka's apparel clusters in Gazipur and Narayanganj drive demand for bonded warehouse-linked container haulage, though diesel price volatility compresses fleet margins.
- Ocean Freight:Carries the highest absolute cargo volume through Chittagong and Mongla ports, with feeder services connecting to transshipment hubs in Singapore and Colombo. Container vessel waiting times at Chittagong Port berth congestion create inventory carrying cost burdens for letter-of-credit-timed exports.
- Rail Freight:Operates on Bangladesh Railway's meter-gauge network, preventing seamless container transfer with Indian broad-gauge lines and forcing transloading at border points.
- Air Freight:Serves time-sensitive apparel samples and high-value electronics through Hazrat Shahjalal International Airport, constrained by limited cargo terminal capacity and customs clearance bottlenecks.
Today's leader: Road Freight. Tomorrow's challenger: Ocean Freight.
Customer Type:
Procurement sophistication varies sharply across customer categories, with large manufacturers negotiating annual rate contracts while smaller retailers remain exposed to spot market volatility.
- Manufacturers:Ready-made garment exporters in Dhaka's Uttara and Tejgaon industrial zones are consolidating procurement through volume-based logistics agreements with guaranteed capacity provisions. European fast-fashion retailers drive contract standardization among large apparel manufacturers.
- Online Businesses:E-commerce platforms spawn demand for last-mile fulfillment centers in secondary cities, with National Digital Commerce Policy data localization mandates shaping warehouse location decisions.
- Retailers:Brick-and-mortar chains in Dhaka and Chittagong rely on fragmented distributor networks with limited real-time visibility.
- Wholesalers:Traditional traders in commodity markets prefer transactional spot contracting with minimal technology integration.
Manufacturers command pricing power through scale. Online Businesses are expanding most quickly through policy tailwinds.
Technology:
Technology adoption diffuses unevenly, with large third-party logistics providers leading warehouse automation while long-haul trucking fleets prioritize fuel optimization through GPS tracking.
- GPS Tracking:Unifies dispatch operations across fragmented owner-operator trucking networks, with large garment exporters mandating real-time visibility as a contract precondition. This technology compression squeezes traditional broker commissions.
- Warehouse Management System:Penetrates large third-party logistics providers first, though family-owned operators face capital constraints and technical debt migrating from paper-based inventory tracking.
- Transportation Management System:Consolidates spot market liquidity on digital freight platforms, compressing broker margins.
- RFID:Tracks container movements through Chittagong Port yards, adoption limited by implementation costs among smaller customs brokers.
GPS Tracking dominates current deployment. Warehouse Management System holds the steepest expansion trajectory as bonded warehouse requirements intensify.
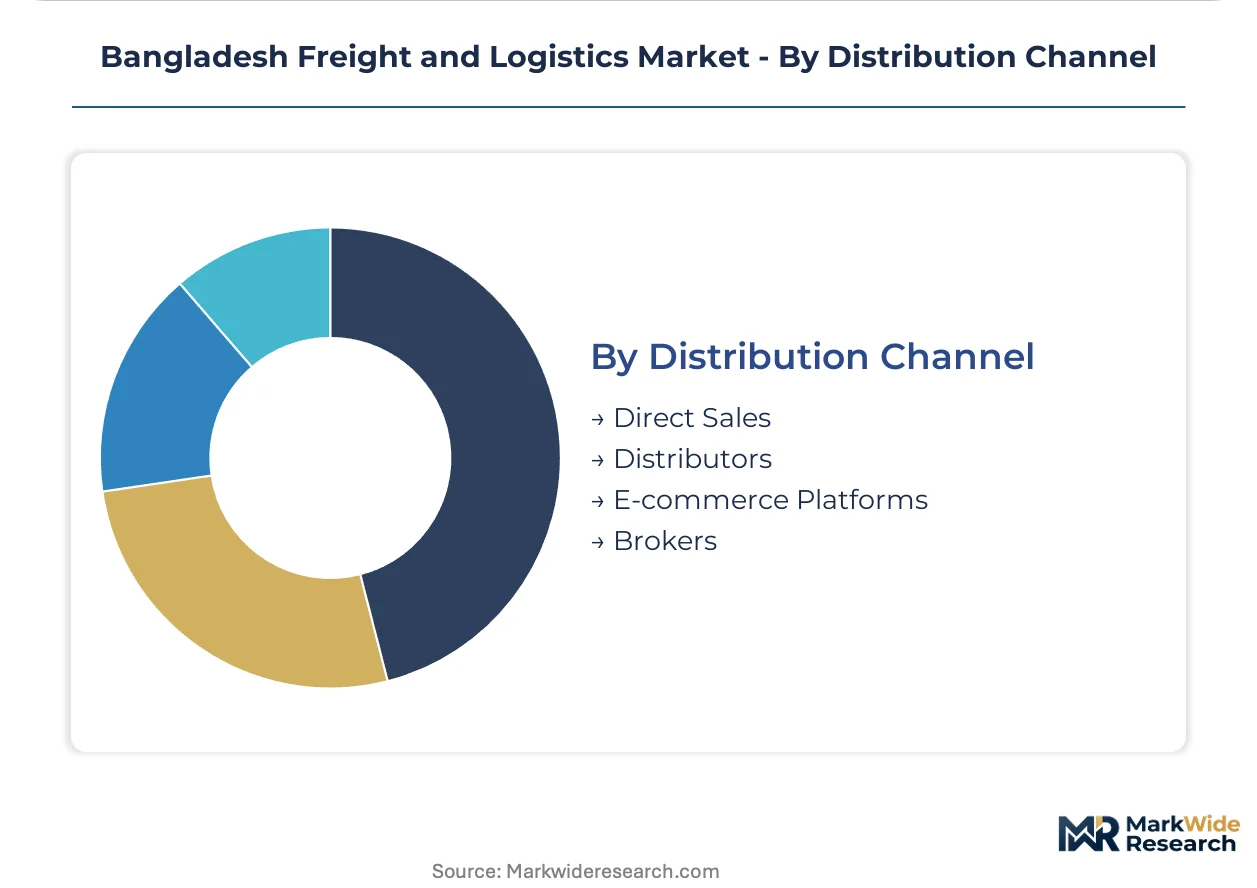
Distribution Channel:
Channel structure reflects the tension between direct control over customer relationships and the reach advantages of intermediary networks in Bangladesh's fragmented geography.
- Brokers:Traditional intermediaries face margin pressure as digital freight platforms consolidate spot market liquidity, forcing migration toward value-added customs brokerage.
- Direct Sales:Large fleet operators and third-party logistics providers pursue direct relationships with garment exporters to secure annual rate contracts.
- Distributors:Maintain last-mile reach into secondary cities and industrial zones outside the Dhaka-Chittagong corridor.
- E-commerce Platforms:Integrate logistics as a competitive differentiator, with some platforms developing captive fulfillment networks.
Brokers retain transaction volume. Direct Sales gains share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Truck driver density concentrates along the Dhaka-Chittagong corridor, anchoring Bangladesh's freight labor pool. Warehouse operatives cluster in Gazipur and Narayanganj apparel zones. Port logistics specialists dominate Chittagong's maritime workforce.
Dhaka Division
Ready-made garment exporters in Uttara and Tejgaon industrial zones drive bonded warehouse demand. Bangladesh Road Transport Authority fitness certification requirements tighten emission standards for commercial fleets. Gazipur's apparel clusters pull dedicated container services toward Chittagong Port feeder networks.
Chittagong Division
Port logistics operators handle transshipment cargo through Singapore and Colombo feeder connections. Bangladesh Inland Water Transport Authority oversees dredging operations on the Karnaphuli River. Chittagong Port's berth congestion creates inventory carrying cost burdens for letter-of-credit-timed garment exports.
Khulna Division
Mongla Port serves southwestern manufacturing zones with bulk cargo handling capacity. Padma Bridge rail link completion redistributes cargo flows between Dhaka and southwestern industrial areas. Jessore's agro-processing clusters lack integrated cold chain infrastructure for temperature-sensitive movements.
Sylhet Division
Tea and agro-processing clusters in northeastern districts generate demand for specialized logistics services. National Digital Commerce Policy data localization mandates shape warehouse location decisions for e-commerce fulfillment. Sylhet-Dhaka corridor development creates white space for temperature-controlled road services.
Rajshahi Division
Cross-border trade through Burimari and Banglabandha land ports offers alternative corridors for Indian northeast cargo. Bangladesh Railway's meter-gauge network forces transloading at border points with Indian broad-gauge lines. Bogra's commodity markets rely on fragmented distributor networks with limited real-time visibility.
Bangladesh Freight and Logistics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Bangladesh's freight and logistics sector. The market structure shows tiered consolidation with global integrators commanding bonded warehouse networks alongside family-owned domestic operators. Three strategic archetypes dominate: multinational freight forwarders with regional hub operations, domestic road hauliers with corridor-specific density, and port-centric maritime service providers. Competitive moves center on procurement consolidation through annual rate contracts and fleet pooling to amortize compliance costs.
Among multinational logistics integrators, DHL Group and A.P. Moller - Maersk occupy positions reflecting distinct strategic emphases. DHL Group represents the integrated forwarding and warehousing archetype with bonded warehouse network presence. A.P. Moller - Maersk anchors the maritime-centric service provider tier through container throughput relationships. A.H. Khan and Co. exemplifies the domestic corridor specialist model with overland connectivity positioning. These three companies collectively illustrate the competitive spectrum spanning global network reach, port-centric operations, and sub-regional road dominance.
| Leading Market Players |
|---|
| DHL Group |
| DSV A/S |
| A.P. Moller - Maersk |
| Kuehne + Nagel |
| FedEx |
| CMA CGM Group |
| A.H. Khan and Co. |
| Bolloré Logistics |
| Nippon Express Holdings |
| Others |
Value Chain & Pricing Dynamics
Digital freight platform penetration is compressing traditional broker commissions while simultaneously concentrating pricing power among fleet operators with bonded warehouse networks, reshaping both cost structures and supplier consolidation incentives across the Dhaka-Chittagong corridor.
Pricing Analysis
Bundled annual rate contracts with guaranteed capacity provisions dominate procurement among large ready-made garment exporters, while unbundled spot market transactions persist for smaller wholesalers with limited volume leverage. Price differentiation rests on real-time visibility technology integration and Bangladesh Road Transport Authority fitness certification compliance tier. Pricing pressure intensifies downward as diesel price volatility absorbs directly into thin fleet margins without effective fuel surcharge pass-through mechanisms. Small family-owned logistics operators exhibit highest price sensitivity due to capital constraints blocking technology migration, while multinational integrators with captive bonded warehouse networks command premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Chittagong Port container throughput, where berth congestion creates cascading inventory carrying cost burdens for letter-of-credit-timed apparel exports. Geographic supply concentration draws from China for container equipment, India for cross-border rail connectivity, and Singapore for transshipment hub feeder services. Raw material dependencies center on diesel fuel procurement, commercial vehicle chassis imports, and bonded warehouse construction materials. Supply chain risk hinges on Padma Bridge rail link completion timelines redistributing cargo flows. Distribution runs through fragmented owner-operator trucking networks consolidated by digital freight platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh freight and logistics represents a late-cycle quality story as ready-made garment exporters consolidate procurement toward premium specifications mandating real-time visibility and bonded warehouse integration.
For Market Incumbents: Extend bonded warehouse network coverage into Gazipur and Narayanganj apparel clusters to capture volume-based logistics agreement consolidation. Accelerate fleet renewal schedules to preempt Bangladesh Road Transport Authority emission standard tightening. Vertical integration into customs brokerage services defends margin position against digital freight platform disintermediation. For New Entrants and Emerging Players: Begin with temperature-controlled road services targeting Sylhet-Dhaka corridor tea and agro-processing clusters lacking integrated cold chain infrastructure. National Digital Commerce Policy data localization mandates create penetrable white space for last-mile fulfillment centers in secondary cities. Direct sales relationships with mid-tier e-commerce platforms bypass entrenched broker networks. For Investors and Strategic Acquirers: Roll-up economics work for domestic corridor specialists because family-owned operators face technical debt barriers blocking warehouse management system migration. Five-to-ten year viability favors platforms with integrated visibility technology and bonded warehouse assets. Acquisition target archetype: meter-gauge rail-connected overland operators with India-Nepal cross-border positioning. Signal to watch: Bangladesh Railway gauge standardization announcements affecting transloading economics at border points.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Network Expansion | Captures volume-based contracts from European fast-fashion retailers consolidating procurement. |
| Digital Freight Platform Integration | Compresses broker margins while consolidating spot market liquidity for fleet operators. |
| Fleet Renewal and Compliance Investment | Preempts Bangladesh Road Transport Authority pre-2010 chassis phase-out mandates. |
| Cross-Border Rail Connectivity Development | Bypasses Chittagong Port congestion through Burimari and Banglabandha alternative corridors. |
| Cold Chain Infrastructure Buildout | Serves Sylhet tea and Jessore agro-processing clusters with temperature-controlled capacity. |
Study Parameters
Bottom-up ready-made garment export volume modeling reconciled against top-down container throughput tracking at Chittagong and Mongla ports forms the analytical core. Primary interviews with fleet operators, bonded warehouse managers, Bangladesh Road Transport Authority officials, and apparel exporter procurement heads combined with secondary validation from Bangladesh Inland Water Transport Authority dredging records, National Board of Revenue customs data, and Bangladesh Railway freight statistics.
Input-output matrices map service type penetration against customer type procurement sophistication across road, rail, ocean, and air freight segments. Segmentation dimensions include service modality, customer scale tier, technology adoption stage, and distribution channel structure. CAGRs derive from trend extrapolation of garment export growth rates, infrastructure completion timelines, and regulatory enforcement intensity throughout the forecast period. Industry-specific inputs incorporate Padma Bridge rail link capacity assumptions and digital platform adoption curves among owner-operator networks.
Several conditions sit outside the modeled scope, including geopolitical disruptions affecting India-Bangladesh trade corridors, currency devaluation scenarios impacting diesel import costs, and unannounced regulatory shifts beyond current Bangladesh Road Transport Authority and Bangladesh Inland Water Transport Authority frameworks. Forecasts reflect documented assumptions regarding infrastructure completion schedules and export demand continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Digital Freight Forwarder Market