

Supplier Collaboration and Inbound Logistics Control Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Supplier Collaboration and Inbound Logistics Control Tower Market Insights
Premium control tower deployments is decoupling from commodity supply chain visibility tools on the basis of multi-tier supplier API integration and predictive disruption modeling. SAP leverages deep ERP connectivity to anchor enterprise-grade deployments across complex manufacturing ecosystems. Oracle sustains competitive positioning through integrated cloud infrastructure spanning procurement through inbound logistics execution.
A supplier collaboration and inbound logistics control tower constitutes a centralized command layer that aggregates real-time data from tier-n suppliers, transportation modes, and warehouse nodes through EDI, API, and IoT telemetry feeds to enable exception-based orchestration of inbound material flows. Cloud-based deployment leads solution architecture as manufacturers prioritize elastic compute for demand-surge scenarios and distributed supplier onboarding. Inventory management and transportation management solution types capture concentrated margin pools where real-time SKU-level positioning and carrier scorecarding generate measurable working capital improvements.
FDA traceability mandates for pharmaceutical inbound chains and EPA emissions reporting requirements for freight movements shape control tower data architecture and supplier audit protocols. NHTSA automotive recall traceability standards and EU REACH chemical substance tracking obligations compel electronics manufacturers and automotive OEMs to invest in multi-tier supplier mapping capabilities. Stakeholders must weigh captive platform development against ecosystem interoperability as regulatory data granularity intensifies across jurisdictions.
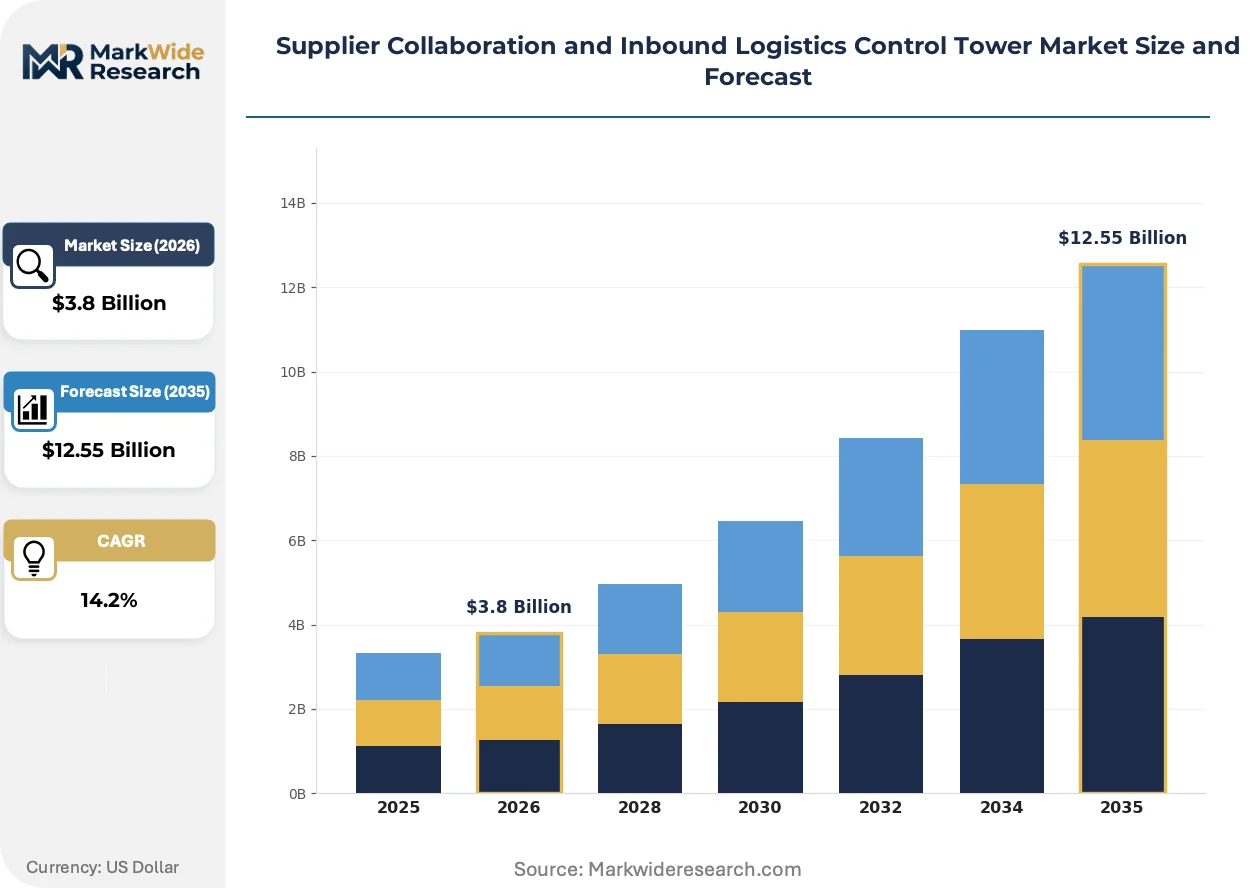
Market Dynamics
API-first architectures are displacing legacy EDI infrastructure as automotive OEMs demand real-time multi-tier supplier visibility to buffer against component shortages and geopolitical freight disruptions.
Growth Catalysts
- REACH substance tracking mandates:EU chemical disclosure requirements compel electronics manufacturers to deploy multi-tier supplier mapping for inbound component traceability.
- Automotive OEM demand surge:German automotive dense supplier networks require exception-based orchestration of inbound material flows to compress inventory cycles.
- Cloud elasticity:Elastic compute architectures enable manufacturers to onboard distributed supplier bases during demand-surge scenarios without capital-intensive infrastructure.
Market Restraints
- Legacy system integration costs:ERP migration and EDI-to-API conversion impose heavy professional services expenditure on mid-tier manufacturers.
- Supplier data fragmentation:Tier-n suppliers in emerging manufacturing corridors lack standardized telemetry feeds, creating visibility gaps.
- Freight emissions reporting friction:EPA greenhouse gas disclosure requirements for inbound logistics add audit protocol complexity and supplier compliance overhead.
Strategic Opportunities
- Pharmaceutical cold chain expansion:FDA traceability mandates for temperature-sensitive inbound biologics create specialized control tower deployment opportunities.
- IoT-telemetry convergence:Sensor networks and predictive analytics integration enable pre-emptive disruption modeling for semiconductor inbound flows.
- India manufacturing corridor penetration:PLI scheme incentives for electronics and automotive component production drive supplier collaboration platform demand.
Industry Challenges
- Multi-tier API standardization gaps:Absence of unified data exchange protocols between tier-1 and tier-3 suppliers forces custom integration workarounds.
- Predictive modeling talent scarcity:Shortage of supply chain data scientists capable of configuring machine learning models for disruption forecasting.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplier Collaboration and Inbound Logistics Control Tower Market Trends and Innovations
Control tower architectures are pivoting from passive visibility dashboards toward autonomous orchestration engines that trigger supplier and logistics interventions without human escalation.
Digital twin technology for inbound supply networks is converging with real-time transportation visibility platforms to compress exception response windows from hours to minutes. Automotive OEMs in Germany and the US Midwest are deploying these fused systems to simulate supplier disruption scenarios before they materialize. The structural consequence is a compression of safety stock requirements and working capital deployment across complex multi-tier supply bases.
NHTSA automotive recall traceability standards are mandating component-level digital records from point of manufacture through final assembly. Electronics manufacturers serving automotive verticals must now maintain immutable supplier audit trails spanning semiconductor foundries to module integrators. Tier-1 automotive suppliers in Michigan and Bavaria are responding by mandating API connectivity from all qualified suppliers as a condition of contract renewal.
Buyer procurement patterns are rotating from annual supplier scorecard reviews toward continuous performance monitoring with automated penalty and incentive triggers. Electronics contract manufacturers are replacing quarterly business reviews with real-time KPI dashboards that adjust payment terms based on inbound delivery precision. This behavioral shift is most pronounced in German automotive supply chains where OEMs penalize suppliers for ETA variance exceeding 15 minutes.
Supplier Collaboration and Inbound Logistics Control Tower Market Segmentation
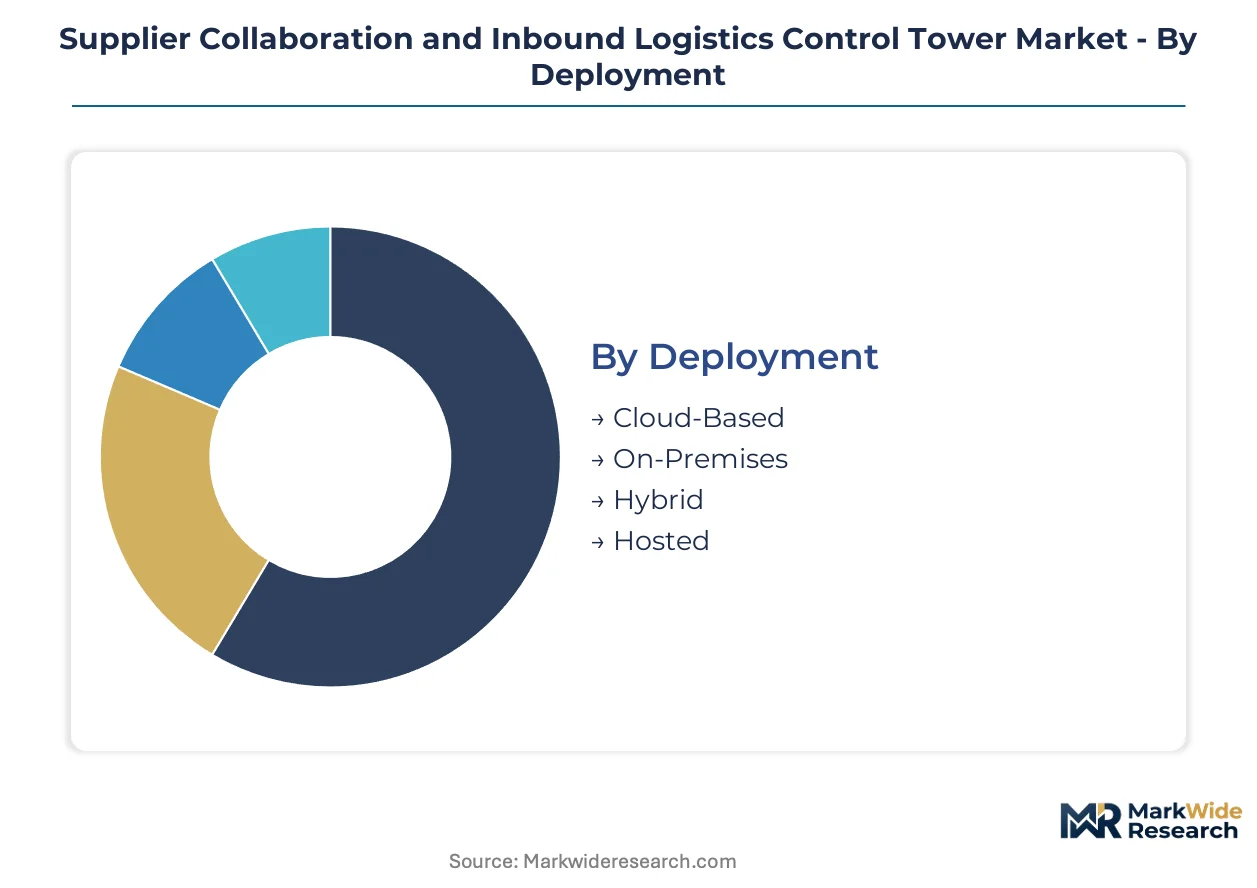
Control tower architectures fragment across deployment modes, solution depth, and vertical specialization. Each segmentation axis determines integration complexity, data sovereignty requirements, and supplier onboarding velocity.
Deployment:
Standardization ranges from fully managed SaaS to captive infrastructure, with hybrid models dominating compliance-sensitive verticals.
- Cloud-Based:Elastic compute architectures enable manufacturers to surge capacity during supplier onboarding waves without capital expenditure. German automotive OEMs prioritize these deployments for real-time multi-tier visibility across dense supplier networks.
- On-Premises:Captive infrastructure satisfies data residency mandates in defense-adjacent manufacturing and pharmaceutical cold chains. Electronics manufacturers in South Korea deploy these for semiconductor foundry integration where IP protection overrides cloud economics.
- Hybrid:Split architectures isolate sensitive supplier financial data on-premise while routing logistics telemetry through cloud analytics layers.
- Hosted:Managed private cloud instances serve mid-tier manufacturers lacking internal DevOps capabilities for control tower maintenance.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
Solution Type:
Margin pools concentrate where real-time data translates directly into working capital compression or risk reduction.
- Inventory Management:SKU-level positioning systems aggregate IoT telemetry from supplier warehouses and in-transit nodes. Consumer goods firms deploy these to compress safety stock across promotional demand cycles.
- Transportation Management:Carrier scorecarding and dynamic routing engines dominate where freight costs represent material COGS exposure. Food and beverage companies prioritize these for temperature-sensitive inbound flows with EPA emissions tracking requirements.
- Order Tracking:Exception-based alert systems flag supplier delivery deviations before production line disruption.
- Supplier Management:Qualification workflows and performance scorecards streamline tier-n onboarding.
- Demand Forecasting:Machine learning models ingest point-of-sale signals to project component requirements upstream.
Capturing the largest revenue share: Inventory Management. Steepest expansion trajectory: Transportation Management.
Application:
Use case maturity varies by inbound complexity and supplier network density.
- Manufacturing Coordination:Multi-tier orchestration platforms synchronize component arrivals with production schedules. Automotive OEMs in Michigan and Bavaria mandate these for just-in-sequence assembly operations.
- Retail Replenishment:Store-level demand signals trigger automated supplier purchase orders.
- Wholesale Distribution:Bulk inbound consolidation optimizes container utilization across fragmented supplier bases.
- E-Commerce Fulfillment:Direct-to-consumer velocity demands real-time supplier commitment tracking.
- Third-Party Logistics:Control towers aggregate visibility across contracted freight forwarders and warehouse operators.
Dominating current deployments: Manufacturing Coordination. Gaining share fastest: E-Commerce Fulfillment.
End User:
Vertical specialization drives feature differentiation, particularly around regulatory telemetry and supplier audit protocols.
- Automotive OEMs:NHTSA recall traceability mandates require component-level digital records from foundry to final assembly. These buyers demand API connectivity as a contract condition and penalize ETA variance exceeding 15 minutes.
- Electronics Manufacturers:EU REACH substance tracking compels multi-tier supplier mapping for semiconductor and component traceability. FDA traceability requirements for medical electronics add cold chain telemetry specifications.
- Consumer Goods Firms:Promotional demand volatility prioritizes elastic supplier onboarding capabilities.
- Food & Beverage Companies:Temperature-sensitive inbound flows require specialized IoT sensor integration.
- Apparel Brands:Distributed supplier bases across Southeast Asia demand multilingual platform interfaces.
Generating the highest solution spend: Automotive OEMs. Climbing the fastest: Electronics Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European control tower deployment density, where Bosch, Porsche, and Mercedes-Benz supplier networks demand real-time inbound orchestration across tier-n ecosystems.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate API connectivity as a contract condition for tier-1 suppliers. REACH substance tracking obligations under ECHA jurisdiction compel electronics manufacturers to deploy multi-tier supplier mapping. The Stuttgart-Munich corridor concentrates platform investment where OEMs penalize ETA variance exceeding 15 minutes.
United States
Michigan automotive clusters and Pacific Northwest technology manufacturers drive cloud-based control tower adoption for semiconductor inbound flows. NHTSA recall traceability standards require component-level digital records from foundry to final assembly. The Detroit-Windsor cross-border corridor generates concentrated demand for exception-based orchestration of just-in-sequence assembly operations.
China
MIIT industrial internet policies accelerate smart supply chain platform deployment across Yangtze River Delta manufacturing zones. Dual carbon goals under MEE jurisdiction impose freight emissions reporting requirements that shape control tower data architecture. Shanghai and Suzhou electronics manufacturers invest in IoT-telemetry convergence for semiconductor inbound visibility.
India
PLI scheme incentives for electronics and automotive component production drive supplier collaboration platform demand in Tamil Nadu and Karnataka. DGFT import compliance requirements intensify multi-tier supplier documentation needs. The Chennai-Bengaluru manufacturing corridor concentrates deployment activity where contract manufacturers demand real-time inbound material tracking.
South Korea
Semiconductor foundries in Gyeonggi Province deploy captive on-premises infrastructure for IP-protected supplier integration. MFDS pharmaceutical traceability mandates for temperature-sensitive biologics create specialized cold chain control tower opportunities. The Seoul Capital Area anchors electronics manufacturer demand where SAMR-equivalent data sovereignty requirements shape hybrid deployment architectures.
Supplier Collaboration and Inbound Logistics Control Tower Market Competitive Landscape
Premium-margin players sit above commodity-margin players across API integration depth and predictive analytics sophistication. The market structure consolidates around ERP-anchored incumbents, cloud-native visibility specialists, and IoT-telemetry convergence platforms. Three archetypes dominate: enterprise software extenders, best-of-breed logistics visibility providers, and supply chain planning optimizers. Strategic moves concentrate on multi-tier supplier network expansion and machine learning model acquisition for disruption forecasting.
Within the enterprise software extender archetype, SAP and Oracle occupy positions leveraging deep ERP connectivity to anchor complex manufacturing ecosystem deployments. Cloud-native visibility specialists include project44 and FourKites, which exemplify API-first architectures displacing legacy EDI infrastructure. These named players represent competitive positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| e2open |
| Blue Yonder |
| Kinaxis |
| FourKites |
| project44 |
| Locus |
| Manhattan Associates |
| Others |
Pricing and Supply Chain Analysis
API-integration depth bifurcates solution tiers sharply, with premium deployments commanding sustained margins through multi-tier supplier orchestration while commodity visibility tools face compression from cloud-native entrants. This divergence manifests in procurement patterns where German automotive OEMs pay for sub-15-minute ETA precision while mid-tier manufacturers default to standardized SaaS tiers with limited telemetry granularity.
Pricing Analysis
Value-based pricing anchored to working capital outcomes dominates enterprise deployments, with manufacturers paying against measurable inventory compression and disruption avoidance. Subscription tiers stratify across premium API-first orchestration, standard EDI-translation layers, and economy dashboard-only visibility. Price differentiation rests on predictive analytics sophistication and supplier network depth. Cost compression in the standard tier is intensifying because hyperscaler infrastructure commoditizes base telemetry aggregation. Mid-tier electronics manufacturers exhibit highest price sensitivity; automotive OEMs in Bavaria and Michigan show lowest sensitivity given regulatory traceability mandates.
Supply Chain Analysis
Single-source vulnerability sits with semiconductor component telemetry providers concentrated in Taiwan and South Korea, where foundry-level sensor integration capabilities remain captive to dominant electronics manufacturers. The supply chain draws from German automotive software engineering, US cloud infrastructure, and Indian system integration services. Tariff exposure runs through cross-border data sovereignty restrictions affecting EU-US telemetry flows. Distribution runs through direct enterprise sales for complex deployments and hyperscaler marketplaces for standardized SaaS tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics persist as machine learning model development for disruption forecasting outstrips qualified data science capacity, propping pricing for predictive analytics modules. Capacity bottlenecks in tier-n supplier API standardization reinforce this structure.
For Market Incumbents: Extend ERP-anchored control tower architectures into adjacent supplier financial services, embedding working capital solutions that deepen platform stickiness. Threat from cloud-native visibility specialists intensifying in mid-market segments demands accelerated API ecosystem expansion. Capacity addition in India for system integration delivery addresses margin pressure from professional services intensity. For New Entrants and Emerging Players: FDA traceability mandates in the United States open a window for specialized cold chain control tower modules targeting pharmaceutical inbound biologics. White-space concentration sits with mid-tier electronics contract manufacturers in Tamil Nadu and Karnataka underserved by incumbent complexity. Go-to-market leverage through PLI scheme compliance consulting bundled with platform deployment accelerates supplier onboarding velocity. For Investors and Strategic Acquirers: Re-rating potential sits with IoT-telemetry convergence platforms given NHTSA recall traceability standard enforcement tightening across automotive verticals. Long-term viability favors archetypes with demonstrated multi-tier supplier network effects and proprietary disruption prediction datasets. Signal to watch: automotive OEM procurement contract language mandating API connectivity as non-negotiable qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Tier API Ecosystem Expansion | REACH compliance in Germany demands supplier mapping depth that only integrated platforms deliver. |
| Predictive Analytics Module Acquisition | Machine learning talent scarcity makes proven disruption models strategic differentiators against commodity visibility. |
| Pharmaceutical Cold Chain Specialization | FDA traceability mandates create defensible vertical moats with specialized telemetry requirements. |
| India Manufacturing Corridor Penetration | PLI scheme incentives in Tamil Nadu concentrate electronics and automotive supplier onboarding demand. |
| Hybrid Deployment Architecture Development | South Korean data sovereignty requirements and German automotive IP protection needs favor split cloud-premise models. |
Research Methodology
Independent corroboration across supply chain technology vendors, automotive OEM procurement executives, and electronics contract manufacturer operations directors underwrites the qualitative findings. Primary interviews with platform engineers, ERP integration specialists, and tier-1 supplier logistics managers combined with secondary validation from SEC 10-K filings, EU ECHA substance tracking disclosures, and MIIT industrial internet policy documents. Bottom-up deployment sizing and top-down manufacturing output triangulation anchored volume estimates.
Rate-of-change decomposition across deployment mode, solution type, application use case, and end-user vertical shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cloud elasticity requirements, API integration complexity, regulatory telemetry granularity, and regional supplier network density. CAGRs derived from installed base growth curves and replacement cycle analysis, with semiconductor inbound flow volatility and automotive production schedule precision requirements as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous orchestration engine deployment would alter the outlook. Forecasts reflect documented assumptions about API standardization velocity and regulatory enforcement intensity. Deviation in NHTSA recall traceability audit frequency or ECHA REACH substance disclosure granularity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.