
 Multi-Axis Motion Controller Market | 2026-2036
Multi-Axis Motion Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Axis Motion Controller Market Intelligence
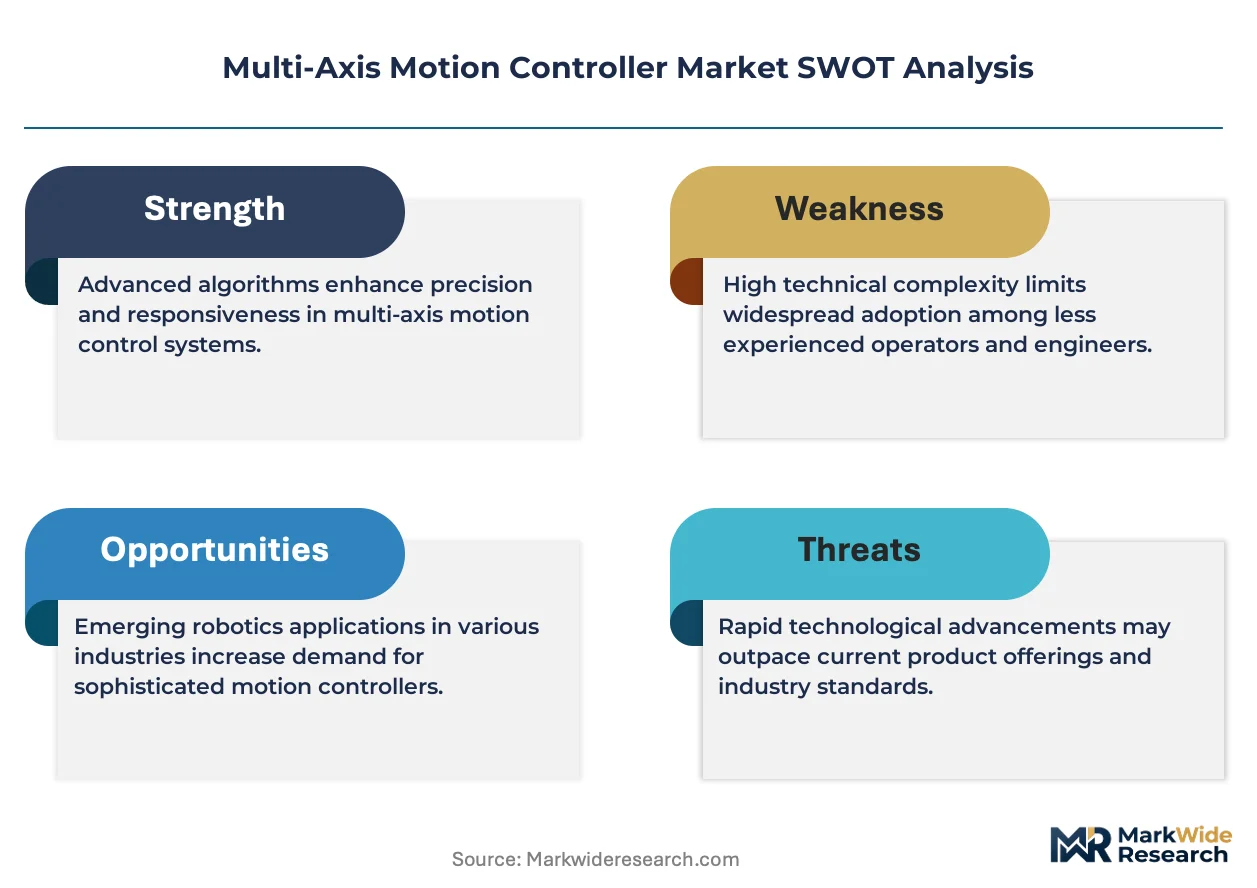
ISO 13849-1 functional safety certification is redrawing competitive boundaries for multi-axis motion controller suppliers. Siemens AG leverages its TÜV-certified safety-integrated platform to dominate high-risk robotics applications. Mitsubishi Electric Corporation anchors its position through captive semiconductor manufacturing in Japan and Taiwan, ensuring supply security for precision encoder components.
A multi-axis motion controller coordinates simultaneous movement across multiple servo or stepper motor axes through real-time interpolation algorithms, typically executing trajectory calculations at 1-8 kHz loop frequencies to maintain positional accuracy within ±1 micrometer in CNC machining centers. Servo controllers command the largest product segment by installed base, though motion control software captures expanding margin pools as manufacturers shift toward model-based design and digital twin integration. Digital control technology leads unit shipments while Ethernet/IP protocol adoption accelerates in packaging lines seeking single-cable architectures for reduced wiring complexity.
FDA 21 CFR Part 820 quality system regulations govern motion controller validation in medical device manufacturing, while EU Machinery Directive 2006/42/EC mandates CE-marked safety functions for automated systems deployed across European automotive plants. China's GB/T 12668 standards for variable speed drives create additional compliance layers for imported controllers. Stakeholders must weigh certification investment against the fragmentation emerging between regional safety protocol requirements as real-time deterministic networking standards compete for design wins.
Market Dynamics
EUV lithography systems in semiconductor fabrication demand nanometer-precision positioning, forcing controller suppliers to certify against tightening IEC 61800-5-2 safety standards while managing encoder component supply security.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:CE-marked safety function mandates in European automotive plants are accelerating replacement cycles for legacy controllers lacking integrated safety architecture.
- High-mix low-volume production:Contract electronics manufacturers in East Asian clusters require programmable motion coordination to handle rapid product changeovers without mechanical retooling.
- EUV lithography expansion:Semiconductor equipment builders in Taiwan and South Korea are scaling multi-axis controller procurement to support next-generation node transitions.
Market Restraints
- Precision encoder supply concentration:Captive manufacturing of optical encoder components in Japan and Taiwan creates bottleneck risk for non-integrated controller suppliers.
- China GB/T 12668 compliance layers:Variable speed drive standards for imported controllers add certification cost and timeline friction for foreign suppliers.
- Motion control software substitution:Model-based design platforms with embedded simulation capabilities are compressing hardware differentiation for mid-tier controller vendors.
Strategic Opportunities
- Digital twin convergence:Real-time controller data feeds combined with physics-based simulation tools are opening subscription revenue streams for predictive maintenance services.
- Single-cable Ethernet/IP architectures:Packaging line OEMs are consolidating sensor, power, and communication wiring to reduce installation labor and fault points.
- FDA 21 CFR Part 820 validation services:Medical device manufacturers require documented motion controller qualification, creating compliance consulting adjacencies for certified suppliers.
Industry Challenges
- ISO 13849-1 functional safety expertise:Controller firmware engineers with TÜV certification in safety-integrated systems command premium compensation and limited availability.
- Legacy fieldbus integration:Manufacturing sites with installed DeviceNet and PROFIBUS infrastructure resist full Ethernet migration due to rewiring capex and production downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Axis Motion Controller Market |
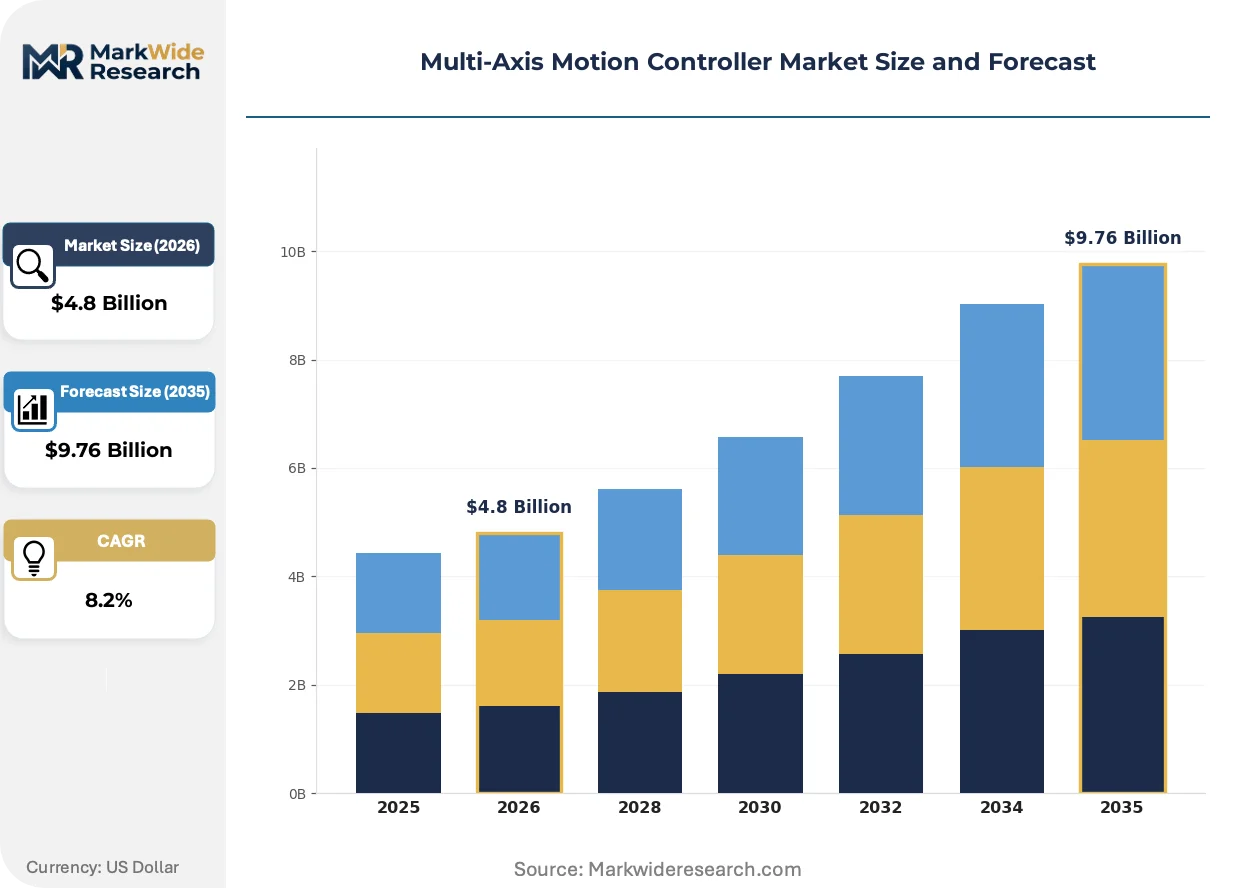
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
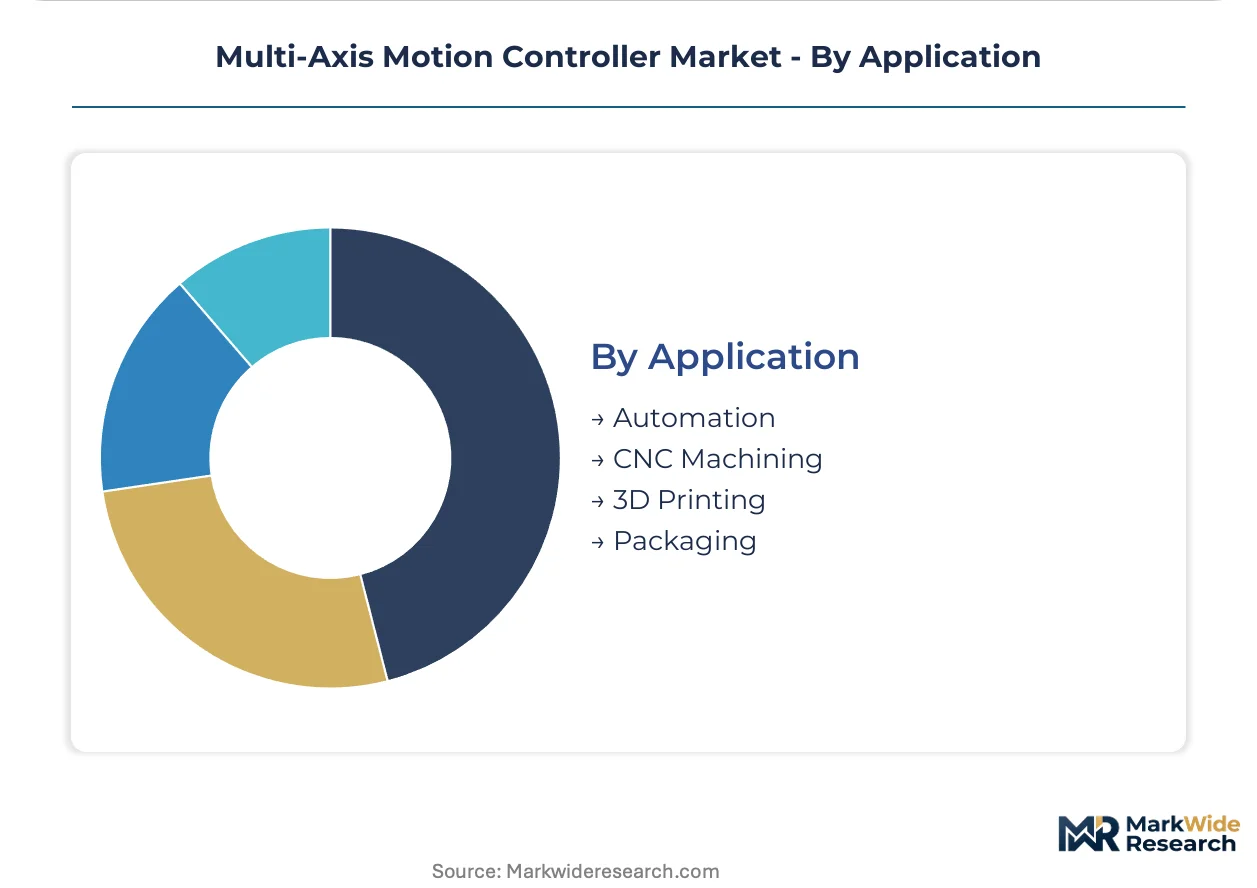
| Segmentation | Product Type: Stepper Controllers, Servo Controllers, Motion Control Software, Integrated Systems End User: Manufacturing, Robotics, Electronics, Aerospace Technology: Analog Control, Digital Control, Ethernet/IP, Fieldbus Application: Automation, CNC Machining, 3D Printing, Packaging |
| Companies Covered | Siemens AG, Mitsubishi Electric Corporation, ABB Ltd., Schneider Electric SE, Rockwell Automation, Parker Hannifin Corporation, Bosch Rexroth AG, Yaskawa Electric Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Axis Motion Controller Market Strategic Shifts & Innovations
Deterministic networking standards are competing for design wins across industrial automation, reshaping how motion controllers communicate with upstream PLCs and downstream servo drives in synchronized multi-axis applications.
Time-sensitive networking over standard Ethernet is decomposing the historical separation between motion control and factory IT infrastructure. Automotive tier-one suppliers are piloting TSN-enabled controllers at 4 kHz loop frequencies to merge machine control with quality data analytics. This convergence is compressing the market for dedicated motion fieldbuses while expanding attack surfaces requiring cybersecurity hardening.
REACH substance restrictions on lead-bearing solder alloys are forcing controller PCB redesigns across European supply chains. Industrial automation OEMs are qualifying silver-sintered die-attach processes and halogen-free laminates to maintain CE marking eligibility. High-reliability segments including semiconductor capital equipment are absorbing material cost premiums to preserve market access.
Buyer preference is pivoting toward motion control software licenses decoupled from dedicated hardware. Machine builders in packaging and material handling are deploying PC-based controllers with real-time Linux kernels to reduce bill-of-materials cost and enable over-the-air algorithm updates. This shift is most visible in German automotive component plants where engineering teams prioritize vendor-agnostic programming environments.
Multi-Axis Motion Controller Market Segmentation
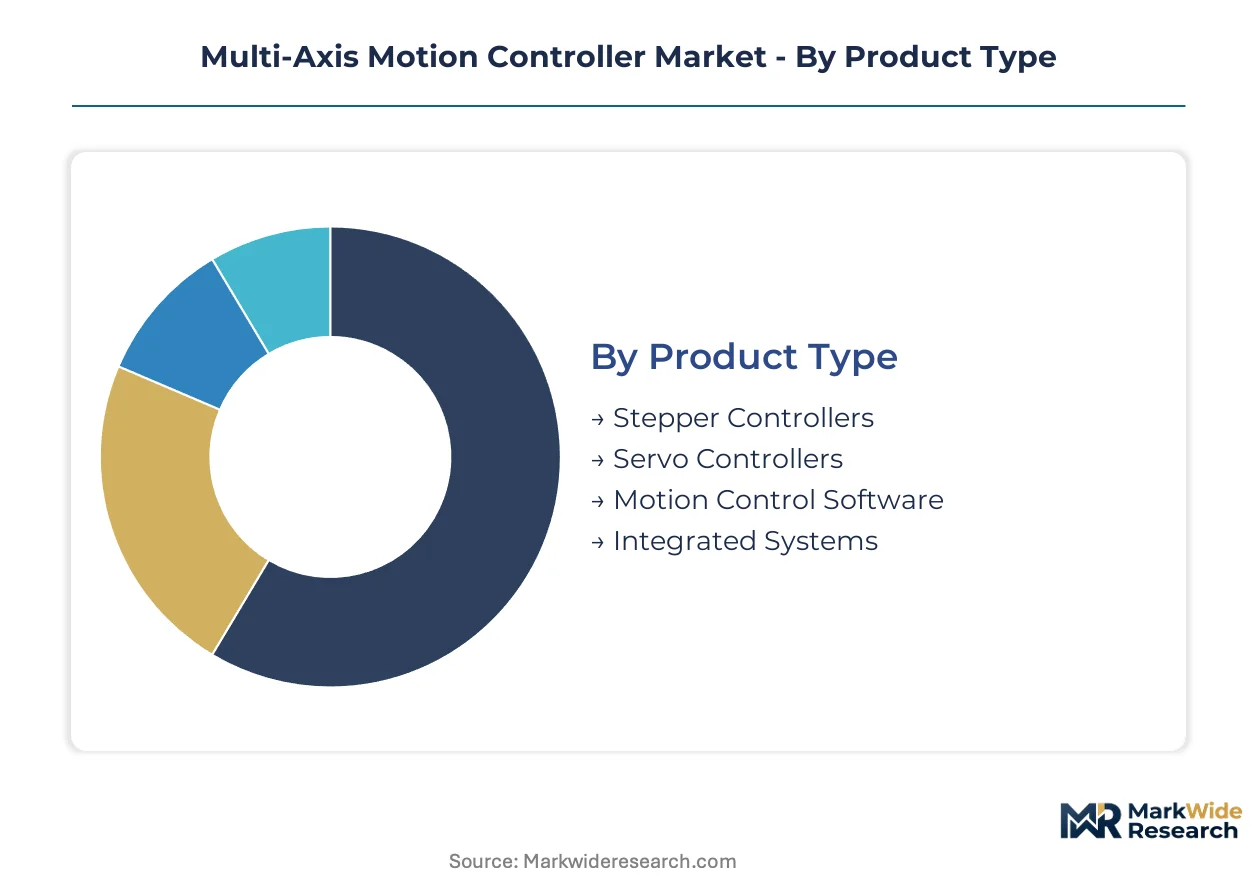
Multi-axis motion controller procurement patterns diverge sharply across product architectures, end-use requirements, and communication protocols. Semiconductor equipment builders prioritize servo precision for EUV lithography positioning, while packaging OEMs favor single-cable Ethernet/IP architectures to reduce installation complexity.
Product Type:
IEC 61800-5-2 safety certification requirements for adjustable speed electrical power drive systems create tiered compliance burdens across hardware and software controller categories.
- Servo Controllers:Closed-loop motor control systems execute trajectory calculations at 1-8 kHz loop frequencies to maintain positional accuracy within ±1 micrometer. Taiwan and South Korea semiconductor fabrication equipment builders scale procurement for EUV lithography nanometer-precision positioning, tightening encoder component supply security.
- Motion Control Software:Model-based design platforms with embedded simulation capabilities enable digital twin integration and over-the-air algorithm updates. German automotive component plants prioritize vendor-agnostic programming environments, compressing hardware differentiation for mid-tier controller vendors.
- Stepper Controllers:Open-loop positioning systems serve lower-precision automation tasks in material handling and basic packaging lines.
- Integrated Systems:Combined controller-drive-encoder modules reduce commissioning time for high-mix, low-volume production environments.
Established volume favors servo controllers; emerging adoption favors motion control software.
End User:
Cost tier differentiation separates safety-critical applications from standard automation deployments.
- Robotics:ISO 13849-1 functional safety certification mandates TÜV-certified safety-integrated architectures for collaborative and high-risk robotic cells. European automotive plants accelerate replacement cycles for legacy controllers lacking integrated safety functions under EU Machinery Directive 2006/42/EC.
- Electronics:Contract electronics manufacturers in East Asian clusters require programmable motion coordination for rapid product changeovers without mechanical retooling. High-mix, low-volume production lines demand flexible controller reprogramming.
- Manufacturing:General industrial automation spans material handling, assembly, and process control with varying precision requirements.
- Aerospace:Precision component machining and composite layup applications require deterministic motion profiles with extensive documentation trails.
Robotics commands premium pricing tiers; electronics drives highest unit velocity.
Technology:
Volume concentration reflects the migration from legacy fieldbus toward deterministic Ethernet architectures.
- Digital Control:Microprocessor-based architectures with real-time interpolation algorithms lead unit shipments across CNC machining centers and semiconductor capital equipment. Digital signal processing enables adaptive gain tuning and vibration suppression.
- Ethernet/IP:Single-cable architectures consolidating sensor, power, and communication wiring reduce installation labor and fault points in packaging lines. Time-sensitive networking pilots at 4 kHz loop frequencies merge machine control with quality data analytics.
- Analog Control:Legacy voltage-command systems persist in retrofit applications and cost-sensitive installations.
- Fieldbus:DeviceNet and PROFIBUS infrastructure resists full Ethernet migration due to rewiring capital expenditure and production downtime risk at established manufacturing sites.
Digital control anchors current installed base; Ethernet/IP claims steepest expansion trajectory.
Application:
Margin structure separates high-precision positioning from commodity automation tasks.
- CNC Machining:Multi-axis interpolation for toolpath execution demands sub-micrometer accuracy and high-bandwidth servo response. Medical device manufacturers require FDA 21 CFR Part 820 documented motion controller qualification, creating compliance consulting adjacencies.
- Automation:General-purpose motion coordination spans pick-and-place, conveyor synchronization, and assembly operations with moderate precision requirements.
- 3D Printing:Additive manufacturing systems require coordinated axis control for deposition path planning and build platform positioning.
- Packaging:High-speed carton forming, filling, and sealing operations prioritize throughput over absolute positioning accuracy.
CNC machining extracts highest margins per axis; automation delivers largest aggregate volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial policy incentives in East Asia and North America are accelerating multi-axis controller procurement for precision manufacturing, while European safety regulations reshape competitive requirements across automotive supply chains.
United States
FDA 21 CFR Part 820 quality system regulations govern motion controller validation in medical device manufacturing across Minnesota and Massachusetts clusters. The National Institute of Standards and Technology advances measurement science for nanometer-scale positioning systems. Boston-area robotics startups drive demand for ISO 13849-1 certified safety-integrated controllers in collaborative automation deployments.
Germany
EU Machinery Directive 2006/42/EC mandates CE-marked safety functions for automated systems in Stuttgart and Munich automotive plants. The country's national standards body, DIN, coordinates IEC 61800-5-2 implementation across industrial automation supply chains. Baden-Württemberg machine tool builders integrate TÜV-certified platforms into precision machining centers for export markets.
China
GB/T 12668 standards for variable speed drives create compliance layers for imported controllers in Yangtze River Delta manufacturing zones. The Ministry of Industry and Information Technology promotes domestic servo system development under industrial upgrading programs. Shenzhen contract electronics manufacturers scale programmable motion coordination for high-mix, low-volume consumer electronics production.
South Korea
Samsung and SK Hynix expansion of EUV lithography capacity drives nanometer-precision controller procurement in Gyeonggi Province. The Ministry of Trade, Industry and Energy backs semiconductor equipment localization initiatives. Seongnam and Suwon fabrication clusters require multi-axis interpolation systems for next-generation node transitions.
Japan
METI industrial competitiveness programs support precision encoder component manufacturing in Nagoya and Osaka regions. JIS standards for motion control equipment align with IEC safety protocols for export compatibility. Yokohama and Kawasaki industrial zones maintain captive production of optical encoder components for supply security.
Multi-Axis Motion Controller Market Key Industry Players
Listed leaders compete with private specialists across functional safety certification tiers, creating a bifurcated structure where TÜV-certified platforms command premium positioning in robotics and medical applications while cost-optimized alternatives capture volume in packaging and material handling. The vendor base organizes around three strategic archetypes: integrated automation conglomerates with captive semiconductor manufacturing, pure-play motion control specialists with software-centric offerings, and regional system integrators with localization advantages. Capacity expansion in East Asian encoder component manufacturing and strategic partnerships for digital twin software integration represent the dominant competitive moves reshaping supply security and service revenue models.
Among Germany-based industrial automation conglomerates, Siemens AG and Bosch Rexroth AG exemplify the integrated archetype combining safety-certified hardware platforms with model-based design software. Japanese specialists including Mitsubishi Electric Corporation and Yaskawa Electric Corporation occupy positions anchored by captive precision component manufacturing in domestic industrial zones. These companies represent the tier where backward integration into encoder supply and TÜV certification investment create defensive positioning against mid-tier software-centric challengers.
| Leading Market Players |
|---|
| Siemens AG |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Schneider Electric SE |
| Rockwell Automation |
| Parker Hannifin Corporation |
| Bosch Rexroth AG |
| Yaskawa Electric Corporation |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
Sixteen-week encoder lead times for optical components from Japanese suppliers concentrate pricing power among vertically integrated controller manufacturers while squeezing margin buffers for assembly-only vendors sourcing precision position feedback modules.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with TÜV-certified safety-integrated platforms commanding substantial premiums over uncertified alternatives in robotics and medical device applications. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13849-1 functional safety grade, volume scale, and after-sales service bundling. Cost compression in mid-tier servo controllers is intensifying because motion control software licenses decouple algorithm value from dedicated hardware. Contract electronics manufacturers in East Asian clusters exhibit highest price sensitivity, while semiconductor capital equipment builders prioritize supply security over unit cost.
Supply Chain Analysis
Japan and Taiwan anchor captive production of optical encoder components, with Nagoya and Yokohama industrial zones maintaining in-house manufacturing of precision position feedback modules for supply security. Controller assembly draws from silver-sintered die-attach materials, halogen-free PCB laminates, and real-time processor chipsets. Single-source vulnerability concentrates in optical grating manufacturing for nanometer-resolution encoders. Distribution runs through authorized industrial automation distributors and direct OEM relationships, with system integrators capturing value-added configuration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-axis motion controller procurement is shifting toward platform-centric purchasing where Ethernet/IP interoperability and digital twin software ecosystems determine vendor selection over hardware specifications alone.
For Market Incumbents: Consolidate encoder component supply through backward integration into optical grating manufacturing or exclusive supplier agreements with Japanese precision component specialists. Deepen TÜV certification investment in safety-integrated firmware to defend against PC-based controller substitution threatening mid-tier hardware margins. Priority focus: secure supply of nanometer-precision position feedback modules for EUV lithography equipment builders.
For New Entrants and Emerging Players: ISO 13849-1 functional safety fast-track certification opens white-space penetration in collaborative robotics and medical device manufacturing where incumbent lead times extend beyond buyer tolerance. Target packaging line OEMs in Germany seeking vendor-agnostic programming environments with single-cable Ethernet/IP architectures. Go-to-market angle: subscription-based motion control software with embedded simulation capabilities decoupled from proprietary hardware.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming motion control divisions lacking safety certification depth or digital twin software integration. Long-term viability favors suppliers with captive precision component manufacturing and recurring software revenue streams. Signal to watch: consolidation of real-time deterministic networking standards between Time-Sensitive Networking and competing industrial Ethernet protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encoder Manufacturing | Captive supply of optical grating components insulates against Taiwan-Japan supply bottlenecks for EUV lithography positioning systems. |
| TÜV Safety Certification Investment | ISO 13849-1 functional safety accreditation unlocks premium robotics and medical device segments under EU Machinery Directive mandates. |
| Digital Twin Platform Partnership | Real-time controller data feeds merged with physics-based simulation tools open subscription predictive maintenance revenue streams. |
| Single-Cable Ethernet/IP Architecture Launch | Consolidated sensor-power-communication wiring reduces installation labor and fault points for packaging line OEMs. |
| FDA 21 CFR Part 820 Validation Service | Documented motion controller qualification creates compliance consulting adjacencies in Minnesota and Massachusetts medical device clusters. |
Research Approach
Initial hypotheses were tested against primary input from semiconductor equipment procurement directors, robotics integration engineers, medical device manufacturing quality leads, and industrial automation distributor principals and refined through secondary validation against IEC 61800-5-2 regulatory filings, SEC 10-K disclosures from listed automation suppliers, Japanese Ministry of Economy Trade and Industry industrial statistics, and EU Machinery Directive implementation guidance. Bottom-up controller shipment estimates triangulated against top-down manufacturing value-add calculations.
Variance decomposition across product architecture, end-use application, communication protocol, and geographic manufacturing cluster shaped analytical framework outputs over the projection horizon. Segmentation dimensions modeled include servo versus software-centric controller types, safety-critical versus standard automation end-uses, digital versus Ethernet/IP technology platforms, and CNC machining versus packaging application categories. CAGRs derived from fitted growth curves incorporating EUV lithography capital expenditure cycles and automotive safety regulation replacement timelines.
Decision-makers should treat outputs as directional under sustained East Asian semiconductor equipment investment and stable IEC regulatory harmonization assumptions; material deviation in encoder supply concentration or deterministic networking standard consolidation would warrant model refresh. Recalibration cycles align with material shifts in EUV node transition schedules and functional safety certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Asia-Pacific Medical Automation Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
HMI Market
Industrial Automation
Global SCADA Market
Industrial Automation
Asia Pacific Warehouse Automation Market