
 Zero-Emission Aircraft Market | 2026-2036
Zero-Emission Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Zero-Emission Aircraft Market Analysis
Buyer concentration among regional carriers is pivoting as Nordic and Alpine operators consolidate fleet renewal commitments around hydrogen-electric platforms. Airbus SE leverages its ZEROe concept program to anchor European supply chain development for cryogenic hydrogen storage. ZeroAvia, Inc. competes through powertrain retrofit specialization on existing turboprop airframes. Rolls-Royce Holdings plc sustains turbine-to-electrification engineering pipelines across its UK facilities.
Zero-emission aircraft are aviation platforms engineered to eliminate carbon dioxide and NOx emissions during flight operations through hydrogen fuel cells, electric batteries, or hybrid architectures with specific energy densities exceeding 500 Wh/kg for viable commercial range. Their primary purpose is to satisfy tightening operational carbon limits while preserving sector connectivity. Hydrogen fuel cell systems occupy the highest-margin development tier due to energy density advantages for regional routes. Electric battery configurations dominate small aircraft and training flight segments where range requirements remain constrained. Hybrid systems are bridging technology gaps in narrow-body platforms where full electrification remains technically distant.
The EU Green Deal and ReFuelEU Aviation framework mandate progressive carbon intensity reductions for aviation fuel supplied at European airports, directly conditioning fleet procurement decisions. EASA certification pathways for novel propulsion architectures are reshaping product development timelines and market access conditions. The US FAA and EPA are advancing parallel standards through sustainable aviation fuel blending mandates and aircraft emission testing protocols. Stakeholders must monitor regulatory divergence between European performance-based mandates and US technology-neutral approaches when allocating platform development resources.
Market Dynamics
The EU Green Deal and ReFuelEU Aviation mandates are compressing fleet procurement timelines as regional carriers face binding carbon intensity thresholds for intra-European operations by mid-decade.
Growth Catalysts
- ReFuelEU Aviation:Binding carbon intensity reduction mandates for aviation fuel supplied at EU airports are forcing fleet renewal decisions toward certifiable zero-emission platforms.
- Hydrogen fuel cell systems:Energy density advantages above 500 Wh/kg enable viable commercial range for regional routes, attracting development investment from aerospace agencies.
- Nordic regional carriers:Consolidated fleet commitments around hydrogen-electric propulsion are creating concentrated demand clusters in Scandinavia.
Market Restraints
- Cryogenic hydrogen storage costs:Specialized containment systems require aerospace-grade materials and thermal management, elevating platform unit economics beyond current turboprop baselines.
- EASA certification pathway uncertainty:Novel propulsion architecture approval timelines remain undefined, extending product development cycles and deferring revenue recognition.
- Liquid hydrogen supply concentration:Production and liquefaction infrastructure clusters in industrial corridors of Germany and the Netherlands, creating geographic dependency for fleet operators.
Strategic Opportunities
- United Kingdom aerospace corridor:Public funding through the Aerospace Technology Institute targets certifiable zero-emission platforms, positioning UK facilities for powertrain engineering capture.
- Training aircraft electrification:Electric battery configurations with constrained range requirements match flight school operational profiles, opening a distinct procurement segment.
- Hybrid architecture convergence:Turbine-electric systems bridge narrow-body range gaps where full electrification remains distant, preserving connectivity on dense routes.
Industry Challenges
- Cryogenic systems engineering talent:Specialized expertise in hydrogen containment and fuel cell integration remains scarce across European aerospace labor pools.
- Dual certification burden:EASA and FAA divergence on performance-based versus technology-neutral standards forces parallel compliance investments.
- Legacy airframe integration complexity:Retrofit powertrain installation on existing turboprop structures requires structural reinforcement and weight redistribution analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero-Emission Aircraft Market |
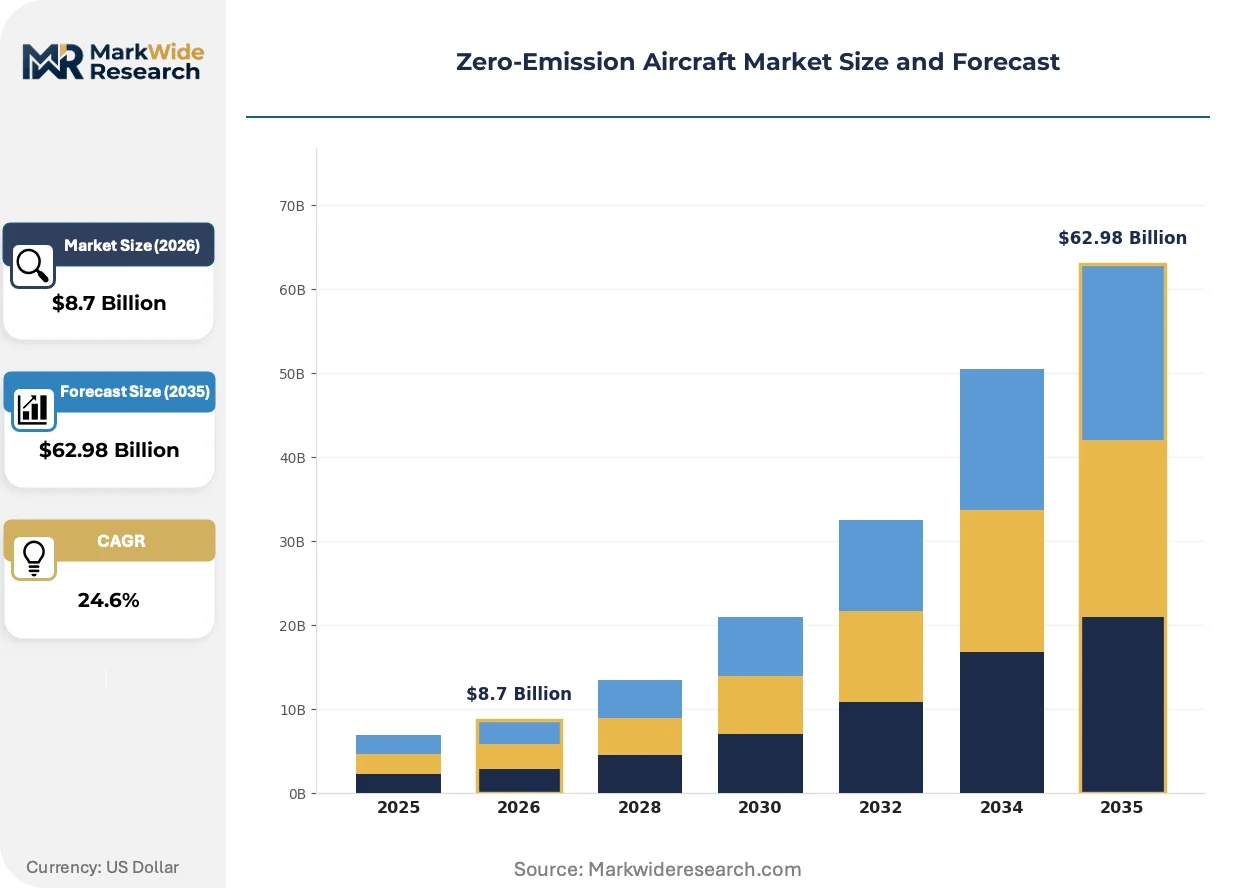
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydrogen Fuel Cells, Electric Batteries, Hybrid Systems, Solar Power End User: Commercial Aviation, Cargo Transport, Military, Private Aviation Size: Small Aircraft, Regional Aircraft, Narrow-Body Aircraft, Wide-Body Aircraft Application: Passenger Transport, Cargo Delivery, Training Flights, Aerial Surveys |
| Companies Covered | Airbus SE, The Boeing Company, ZeroAvia, Inc., Heart Aerospace AB, Rolls-Royce Holdings plc, MagNiX, Pipistrel, Embraer, Joby Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero-Emission Aircraft Market Emerging Trajectories
Propulsion architecture decisions are hardening around hydrogen-electric pathways as energy density requirements and regulatory thresholds converge, compressing technology evaluation windows for platform developers.
Cryogenic hydrogen storage systems are integrating composite pressure vessels with active thermal management to maintain liquid hydrogen at minus 253 degrees Celsius during flight operations. Regional carriers in Scandinavia are adopting these systems for 19-to-50-seat aircraft refurbishment programs. The technology is integrating fuel cell stacks with electric motors to eliminate turbine maintenance cycles and reduce per-flight-hour operating costs.
ReFuelEU Aviation mandates progressive carbon intensity reductions for fuel supplied at EU airports, conditioning fleet procurement on certifiable emission performance. Airlines operating intra-European routes must demonstrate compliance through documented fuel sourcing or platform substitution. Narrow-body operators face the steepest compliance gradient, accelerating hybrid architecture investment to preserve slot access at constrained hubs.
Carrier procurement committees now weight total cost of ownership over acquisition price, unbundling powertrain performance guarantees from airframe purchase agreements. Leasing companies are restructuring contracts to pass through carbon compliance penalties, shifting operational risk to lessees. This recalibration is most visible among French and German regional carriers negotiating renewal terms for turboprop fleets approaching retirement thresholds.
Zero-Emission Aircraft Market Segmentation
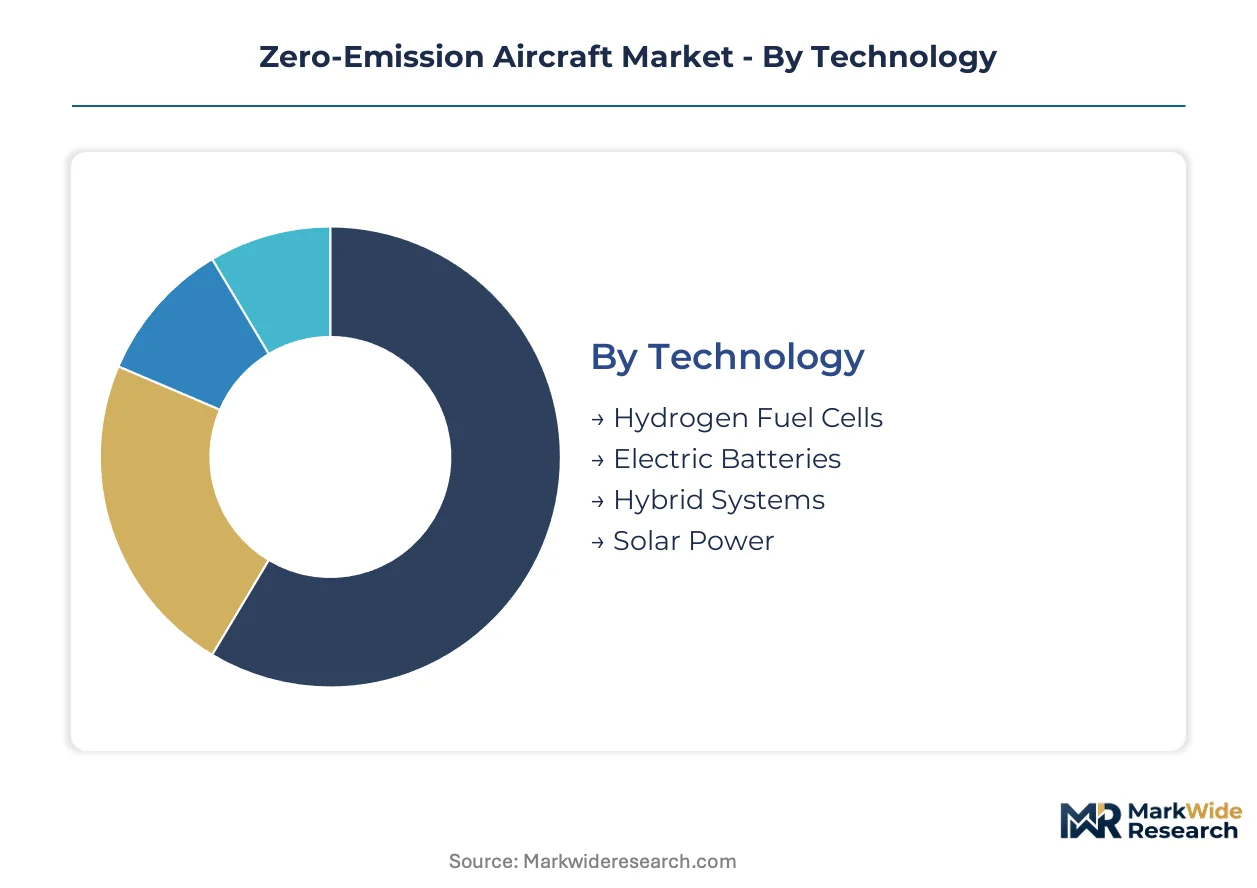
Zero-emission aircraft segmentation reveals how propulsion technology, operational scale, and mission profile intersect to determine platform economics. Each dimension conditions certification pathways, infrastructure requirements, and carrier procurement priorities differently.
Technology:
Hydrogen fuel cells command premium development investment due to energy density thresholds, while electric batteries anchor high-volume training and short-haul segments.
- Hydrogen Fuel Cells:Electrochemical conversion of liquid hydrogen delivers specific energy above 500 Wh/kg, enabling 500-800 nautical mile regional routes. Scandinavian carriers including SAS and Widerøe are consolidating fleet commitments around this architecture for 19-to-50-seat turboprop replacements, driven by EU Green Deal carbon intensity mandates for intra-European operations.
- Electric Batteries:Lithium-ion and solid-state configurations dominate sub-500 kg aircraft where range requirements stay below 150 nautical miles. German flight schools and UK aeroclubs are electrifying training fleets to eliminate hourly fuel costs and turbine maintenance cycles, constrained by battery weight penalties that exclude commercial passenger viability.
- Hybrid Systems:Turbine-electric architectures bridge range gaps in narrow-body platforms where full electrification remains distant.
- Solar Power:Photovoltaic integration on wing surfaces supplements propulsion for endurance unmanned platforms and experimental aircraft.
Mature deployment sits with electric battery systems in training applications. Newer deployment is concentrated in hydrogen fuel cell regional platforms.
End User:
Commercial aviation absorbs development investment through fleet renewal mandates, while cargo operators prioritize payload-range flexibility over passenger comfort specifications.
- Commercial Aviation:Scheduled passenger carriers face binding ReFuelEU Aviation carbon thresholds that compress procurement timelines toward certifiable zero-emission platforms. French and German regional operators are negotiating powertrain performance guarantees separate from airframe purchases to manage compliance risk.
- Cargo Transport:Express freight operators including DHL and Amazon Air are evaluating hydrogen-electric conversions for last-mile feeder routes where payload density permits fuel cell weight penalties. Night-time operations and hub-and-spoke networks align with current hydrogen refueling infrastructure clusters in the Netherlands and Germany.
- Military:Defense agencies are funding surveillance and trainer electrification through national aerospace technology programs.
- Private Aviation:Owner-operators and charter services are adopting electric light sport aircraft for 50-100 nautical mile leisure flights.
Procurement concentration is shifting from private aviation toward commercial regional operators as certification pathways mature.
Size:
Regional aircraft dimensions match current hydrogen storage engineering limits, while narrow-body scale demands hybrid bridging architectures.
- Regional Aircraft:19-to-50-seat configurations align with cryogenic hydrogen tank volumetric constraints and fuel cell stack power density. Alpine operators in Switzerland and Austria are retrofitting existing turboprop airframes through programs targeting EASA supplemental type certification.
- Small Aircraft:Sub-19-seat electric platforms are climbing fastest as flight schools replace aging piston trainers. The UK Civil Aviation Authority has streamlined microlight and light aircraft electrification approvals, accelerating fleet turnover at Oxford and Cranfield training centers.
- Narrow-Body Aircraft:100-to-180-seat platforms require hybrid turbine-electric systems where battery and hydrogen energy density fall short of commercial range requirements.
- Wide-Body Aircraft:Long-haul platforms remain dependent on sustainable aviation fuel blending pending breakthroughs in liquid hydrogen storage at scale.
Engineering validation concentrates on regional aircraft. Demonstration programs are expanding fastest in small aircraft segments.
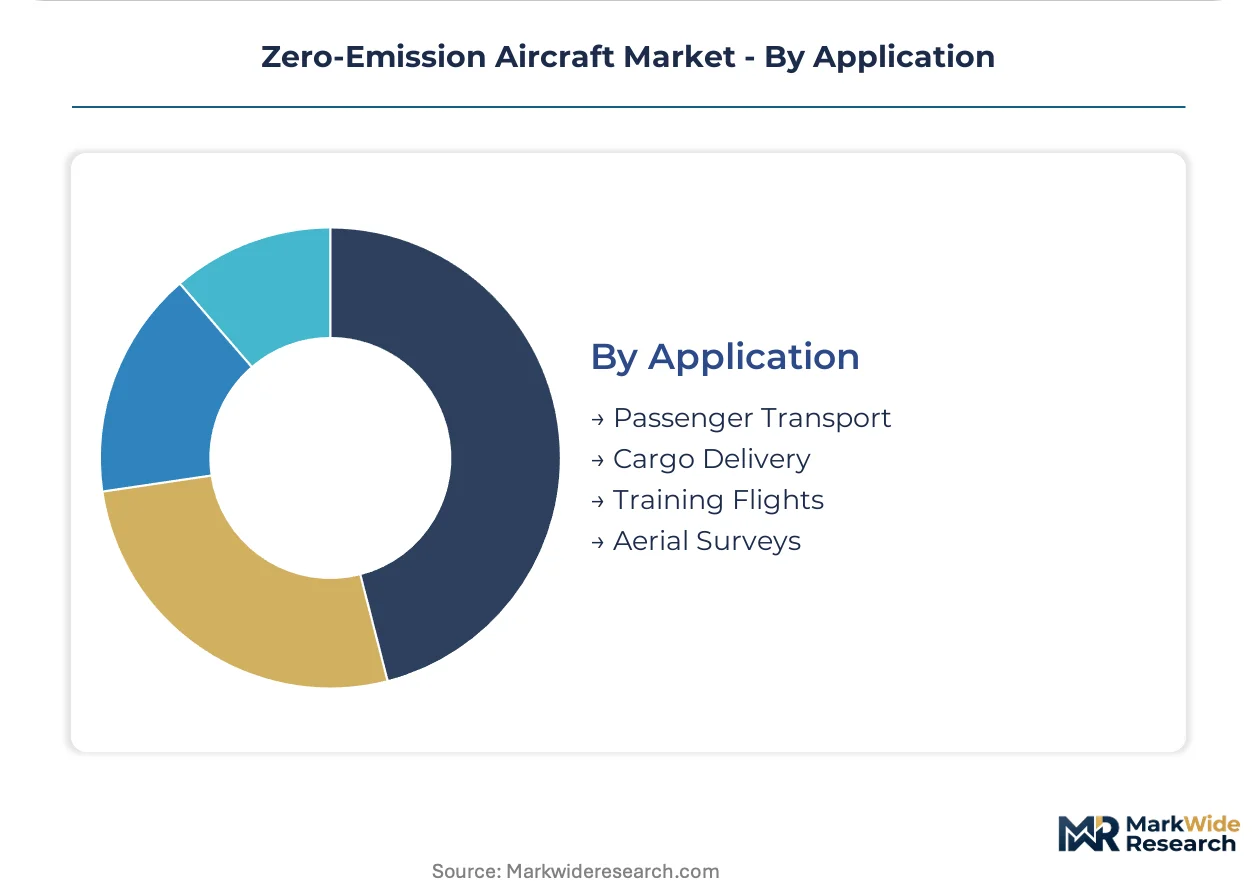
Application:
Passenger transport conditions airworthiness certification standards, while cargo delivery permits operational flexibility that accelerates technology proving.
- Passenger Transport:Scheduled service demands redundant propulsion systems and emergency descent capabilities that extend EASA certification timelines. Nordic regional carriers are accepting reduced range specifications on initial hydrogen-electric routes to secure operational experience before mandate deadlines.
- Training Flights:Repetitive pattern work and short duration missions match electric battery endurance limits without payload penalties. French écoles de pilotage are consolidating procurement around Pipistrel and Bye Aerospace platforms with documented operating cost reductions.
- Cargo Delivery:Uncrewed and short-haul freight applications are expanding through drone logistics networks in Germany and the Netherlands.
- Aerial Surveys:Low-speed endurance requirements favor solar-electric and hydrogen fuel cell endurance platforms for pipeline and environmental monitoring.
Regulatory maturity is deepest in passenger transport. Operational deployment is broadening fastest across training and survey applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier procurement committees in Germany, France, and the United Kingdom are channeling public funding toward certifiable zero-emission platforms as Nordic regional operators consolidate fleet commitments around hydrogen-electric propulsion.
Germany
DHL and Amazon Air are evaluating hydrogen-electric conversions for last-mile feeder routes where night-time operations align with current hydrogen refueling infrastructure clusters. The EU Green Deal and ReFuelEU Aviation mandates bind carbon intensity reduction thresholds for aviation fuel supplied at EU airports. Industrial corridors in North Rhine-Westphalia and Bavaria concentrate liquid hydrogen production and liquefaction capacity.
France
French regional carriers are negotiating powertrain performance guarantees separate from airframe purchases to manage compliance risk under tightening ReFuelEU Aviation thresholds. The country's national aerospace regulator contributes to EASA certification pathway development for novel propulsion architectures. The Île-de-France region hosts engineering facilities where hybrid turbine-electric systems bridge narrow-body range gaps.
United Kingdom
UK flight schools and aeroclubs are electrifying training fleets to eliminate hourly fuel costs, constrained by battery weight penalties that exclude commercial passenger viability. The Aerospace Technology Institute channels public funding through UK facilities targeting certifiable zero-emission platforms. Oxford and Cranfield training centers are accelerating fleet turnover under streamlined Civil Aviation Authority approvals for microlight and light aircraft electrification.
Sweden
SAS and other Scandinavian carriers are consolidating fleet commitments around hydrogen fuel cell architecture for 19-to-50-seat turboprop replacements. The EU Green Deal carbon intensity mandates for intra-European operations compress procurement timelines toward certifiable platforms. Stockholm-Arlanda and Gothenburg clusters anchor Nordic hydrogen-electric propulsion adoption as regional airlines accelerate fleet renewal programs.
Switzerland
Alpine operators are retrofitting existing turboprop airframes through programs targeting EASA supplemental type certification for regional aircraft configurations. Swissmedic and national aviation authorities coordinate with EASA on cryogenic hydrogen storage system approvals. Zurich and Geneva aerospace corridors concentrate engineering validation for hydrogen containment and fuel cell integration on 19-to-50-seat platforms.
Zero-Emission Aircraft Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue powertrain retrofit specialization and regional platform development. The vendor base stratifies across legacy airframe manufacturers, hydrogen-electric specialists, and powertrain engineering houses. Three archetypes dominate: integrated platform developers with cryogenic storage capabilities, retrofit powertrain installers on existing turboprop structures, and battery-electric trainers for flight school segments. Competitive moves concentrate on strategic partnerships for certification pathway navigation and vertical integration into hydrogen supply chain positioning.
Within the integrated platform tier, Airbus SE and The Boeing Company anchor European and North American supply chain development for novel propulsion architectures. ZeroAvia, Inc. occupies the retrofit specialization vector on existing turboprop airframes. Rolls-Royce Holdings plc sits within the powertrain engineering tier, sustaining turbine-to-electrification pipelines across UK facilities. These three exemplify how geographic clustering around regulatory hubs conditions competitive positioning.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| ZeroAvia, Inc. |
| Heart Aerospace AB |
| Rolls-Royce Holdings plc |
| MagNiX |
| Pipistrel |
| Embraer |
| Joby Aviation |
| Others |
Supply Flow & Price Mechanics
ReFuelEU Aviation mandates gate qualified supply and premium-tier pricing access by conditioning fleet procurement on certifiable zero-emission platform performance. Carbon intensity thresholds compress carrier procurement timelines while cryogenic hydrogen storage engineering scarcity elevates unit economics beyond conventional turboprop baselines.
Pricing Analysis
Volume concentrates in electric battery training aircraft while margins accrue to hydrogen fuel cell regional platforms. Three-tier pricing structure across certified, provisional, and developmental platforms separates EASA-approved configurations from supplemental type certification candidates and pre-certification prototypes. Pricing pressure stems from cryogenic containment material costs as aerospace-grade composites face extended lead times. Training flight schools exhibit highest price sensitivity while Nordic regional carriers absorb premiums for compliance-ready hydrogen-electric systems.
Supply Chain Analysis
Refurbishment flows for legacy turboprop airframes create reverse-logistics demand for powertrain retrofit specialists. Germany, France, and the United Kingdom concentrate cryogenic hydrogen storage engineering and fuel cell stack assembly. Supply draws from liquid hydrogen liquefaction capacity in the Netherlands and industrial gas corridors in North Rhine-Westphalia. Single-source vulnerability sits with aerospace-grade carbon fiber for pressure vessels. Distribution runs through national aerospace agencies channeling public funding toward certifiable platform development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic systems engineering talent scarcity props pricing power for qualified suppliers as carrier procurement committees face binding mandate deadlines.
For Market Incumbents: Acquire hydrogen containment engineering capabilities to defend against emerging retrofit specialists capturing regional carrier commitments. Airbus SE and Rolls-Royce Holdings plc should deepen backward integration into liquid hydrogen supply positioning. EASA certification pathway acceleration represents the critical defensive lever against FAA-aligned competitors. For New Entrants and Emerging Players: ReFuelEU Aviation in Europe opens a window for powertrain performance guarantee unbundling from airframe purchases. Training aircraft electrification in the United Kingdom presents the most penetrable segment given streamlined Civil Aviation Authority approvals. Partner with Oxford and Cranfield training centers for operational validation. For Investors and Strategic Acquirers: EASA supplemental type certification issuance for Alpine retrofit programs is the leading indicator that hydrogen-electric regional platforms are reaching investable maturity. Target powertrain engineering houses with demonstrated fuel cell integration capabilities. Monitor Nordic carrier fleet commitment announcements for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Storage Certification | EASA pathway completion validates commercial viability for 19-to-50-seat platforms. |
| Powertrain Retrofit Specialization | Existing turboprop airframe conversion accelerates fleet turnover without clean-sheet development. |
| Hydrogen Supply Integration | Backward integration into liquid hydrogen production secures feedstock for regional route operations. |
| Training Fleet Electrification | UK Civil Aviation Authority streamlining reduces certification barriers for flight school procurement. |
| Hybrid Architecture Development | Turbine-electric bridging preserves narrow-body connectivity where full electrification remains distant. |
Methodological Framework
Independent corroboration across EASA certification pathway documentation, ReFuelEU Aviation regulatory filings, and Nordic carrier fleet commitment announcements underwrites the qualitative findings. Primary interviews with aerospace engineering directors, regional airline procurement committees, hydrogen infrastructure planners, and EASA certification specialists combined with secondary validation from EU Green Deal policy databases, Aerospace Technology Institute funding disclosures, and liquid hydrogen production capacity reports. Bottom-up segment sizing and top-down market triangulation anchored the value estimates.
Comparable-period anchoring to historical aerospace platform development cycles informed the projection horizon calibration. The analytical framework modeled propulsion technology, aircraft size class, end-user segment, and application type across the analysis window. CAGRs derived from carrier procurement timeline compression under mandate deadlines and engineering validation progression rates. Forecast inputs incorporated hydrogen fuel cell energy density improvement curves and cryogenic storage system weight reduction trajectories.
Caveats apply where EASA-FAA regulatory divergence or liquid hydrogen infrastructure buildout delays could materially shift the outlook. Forecasts reflect assumptions on certification timeline acceleration and carrier compliance cost absorption capacity. Practitioners should monitor EASA supplemental type certification issuance velocity and Nordic carrier operational deployment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Firefighting Aircraft Market
Aircraft
Commercial Aircraft Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Supersonic Jet Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Aircraft Jack Market
Aircraft
North America Business Jet Market
Aircraft
Docking System Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Airplane Brackets Market
Aircraft
US Business Jet Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market