
 Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market | 2026-2036
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market Insights
A wide capital-intensity divergence between integrated systems houses and coating specialists is reorganizing competitive tiers in cockpit windshield thermal management. PPG Industries leverages its vertically integrated glass-and-coatings platform to control supply security for major airframers. GKN Aerospace anchors European supply through its electrothermal heater mat capabilities and airframe integration expertise. Saint-Gobain Aerospace sustains leadership in transparent armor and advanced glass substrates that form the structural foundation for multi-function ice-protection layers.
Cockpit windshield anti-icing and defogging layer technologies comprise thin-film conductive coatings, embedded electrothermal grids, and surface-engineered nanostructures bonded to laminated glass or polycarbonate transparencies, typically operating at power densities between 2 and 8 kW per square meter to maintain optical clarity across temperature differentials exceeding 60°C. These systems serve the primary industrial purpose of ensuring uninterrupted pilot visibility during atmospheric icing encounters and cabin humidity excursions that would otherwise compromise flight safety. Electrothermal systems dominate current installations due to mature certification pathways and predictable failure modes, while nanocoatings represent the fastest-growing segment as airframers pursue weight reduction and simplified maintenance cycles. Dual-function layers that combine anti-icing and defogging in single bond-line assemblies command premium positioning as OEMs seek to reduce part counts and installation labor.
FAA airworthiness standards for ice protection under Part 25, EASA CS-25 certification requirements for windshield thermal performance, and CAAC CCAR-25 provisions collectively dictate minimum heating capacity, optical transmission thresholds, and environmental test protocols that shape product development roadmaps and market access conditions. Military procurement through MIL-STD-810 and DEF STAN 00-35 adds further compliance layers for defense aviation applications. Stakeholders must monitor evolving sustainability mandates from regulators and OEM customers regarding coating chemistries and end-of-life transparency recycling as these constraints increasingly filter supplier qualification criteria.
Market Dynamics
Fleet modernization cycles at Boeing and Airbus assembly lines are compressing supplier lead times for heated windshield systems, forcing coating specialists to integrate upstream into glass lamination or risk displacement by vertically integrated systems houses.
Growth Catalysts
- FAA Part 25 ice protection mandates:Certification requirements for thermal performance in transport category aircraft create baseline demand for electrothermal heater mat systems across new-build commercial fleets.
- Polycarbonate substrate adoption:Weight-driven material substitution in regional jets and business aviation expands addressable surface area for conductive nanocoating applications.
- China's MRO hub concentration:Guangzhou, Beijing, and Shanghai maintenance facilities drive aftermarket replacement demand as domestic fleet age profiles mature.
Market Restraints
- Indium tin oxide supply concentration:Thin-film transparent conductor feedstock depends on Chinese rare earth processing capacity, exposing coating specialists to input cost volatility and export control risk.
- EASA CS-25 optical transmission thresholds:Certification friction for novel nanocoating chemistries extends qualification timelines beyond typical product development cycles.
- Electrothermal grid redundancy requirements:Mandatory dual-zone heating architectures add bond-line complexity and failure mode certification burden that nanocoating alternatives have not yet matched.
Strategic Opportunities
- Urban air mobility platforms:eVTOL OEMs in the United States and Germany seek simplified thermal management without pressurized bleed air, opening qualification pathways for solid-state heating layers.
- EU Green Deal sustainable chemistry incentives:Coating formulators eliminating perfluorinated compounds gain preferential supplier status with Airbus and Safran procurement frameworks.
- Aftermarket channel digitization:Predictive replacement scheduling via flight data analytics allows direct-to-operator coating refurbishment bypassing traditional distributor markup.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled thermal-optical-structural modeling for laminated transparency design requires specialized aerospace glass engineers concentrated at PPG, GKN, and Saint-Gobain.
- FAA-EASA harmonization delays:Divergent test protocols for environmental icing simulation force duplicate qualification campaigns for dual-certified products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market |
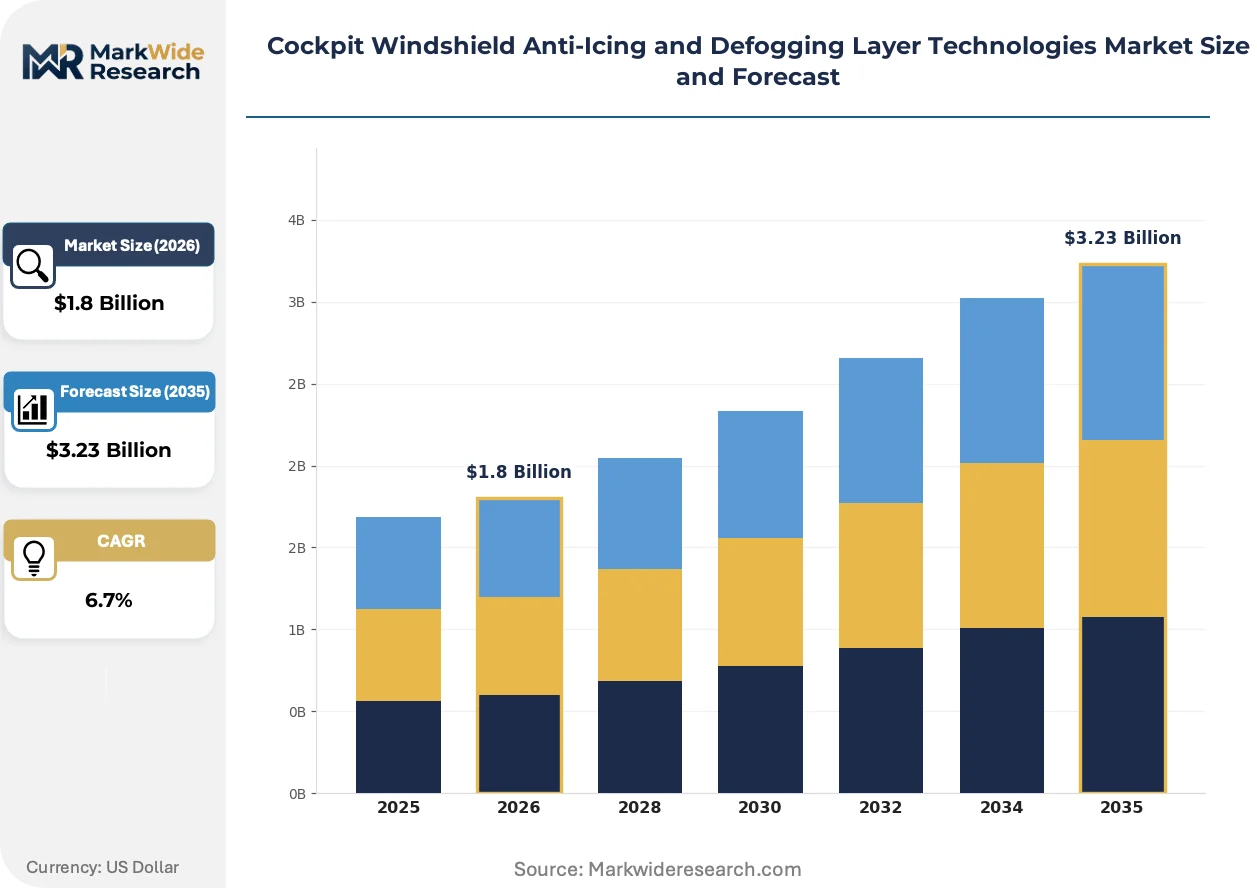
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydrophobic Coatings, Conductive Films, Electrothermal Systems, Photocatalytic Coatings, Nanocoatings Application: Commercial Aircraft, Private Jets, Military Aircraft, Unmanned Aerial Vehicles, Helicopters Product Type: Anti-Icing Layers, Defogging Layers, Dual-Function Layers, Replacement Films, Retrofit Kits End User: Airline Operators, Aircraft Maintenance Organizations, Defense Aviation, Private Operators, UAV Operators |
| Companies Covered | PPG Industries, GKN Aerospace, Saint-Gobain Aerospace, Gentex, The NORDAM Group, Liebherr, Hutchinson, Safran, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market Trends and Innovations
Material science advances in transparent conductors and substrate engineering are compressing the performance gap between established electrothermal systems and emergent solid-state alternatives, reshaping supplier competitive boundaries.
Graphene-based transparent conductive films are fragmenting the incumbent indium tin oxide supply base for defogging layer applications. Business jet OEMs in Wichita and Montreal are piloting these films for cabin humidity management in smaller aperture windshields. The technology is fragmenting procurement patterns as airframers dual-source between established coating houses and graphene specialists to mitigate supply concentration risk.
EASA F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing coating formulators to eliminate sulfur hexafluoride from plasma-enhanced chemical vapor deposition processes. Industrial consequence includes capital retooling toward physical vapor deposition chambers at European coating facilities. French and German transparency suppliers are responding fastest, with qualification submissions for fluorine-free nanocoating architectures accelerating through 2024-2025 certification windows.
Airline technical procurement teams are consolidating windshield replacement decisions into airframe-level power-by-the-hour contracts. Traditional component distributors lose direct OEM relationships as maintenance integrators like Lufthansa Technik and ST Engineering capture coating specification authority. This concentration is most visible in Southeast Asia, where low-cost carrier fleet standardization around single airframe types enables volume-based supplier consolidation at the airline group level.
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market Segmentation
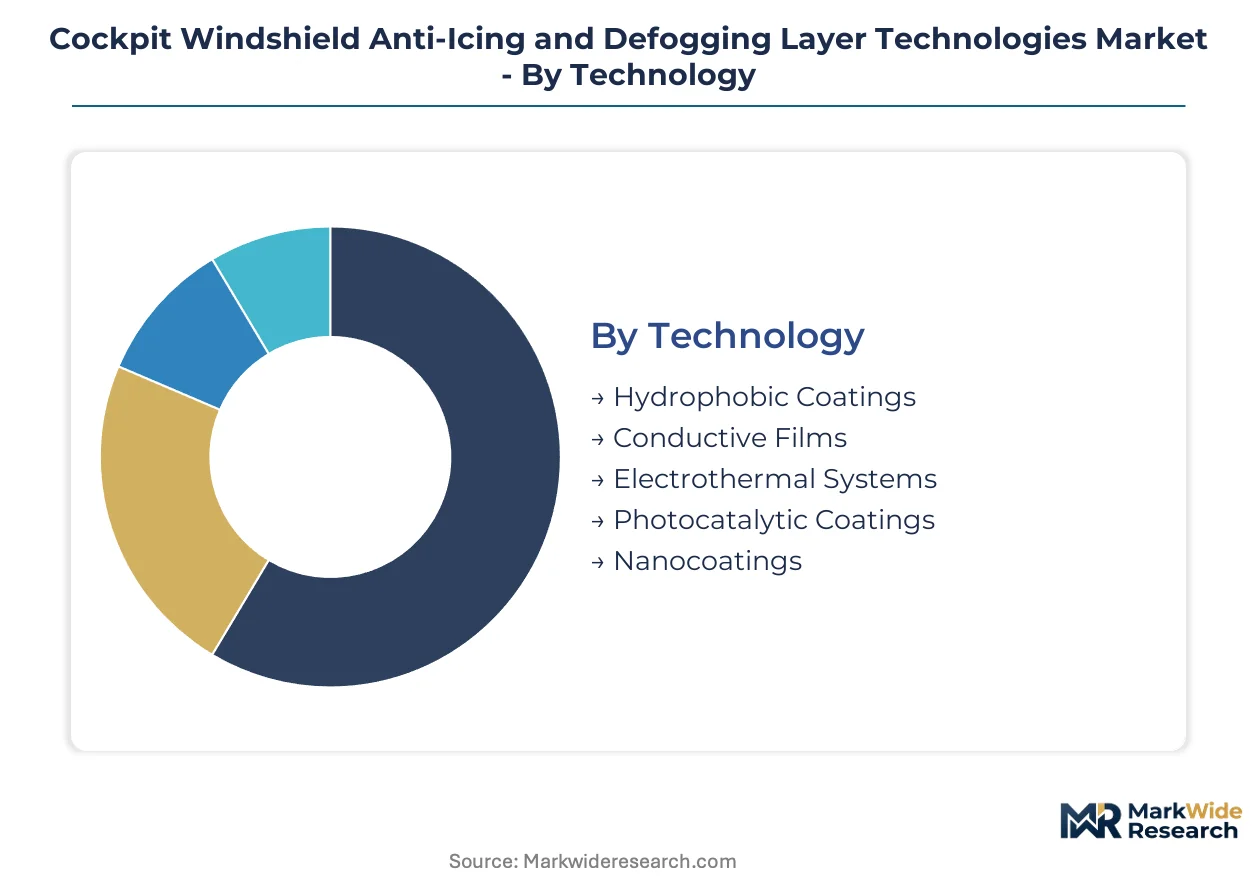
Segmentation in cockpit windshield thermal management reveals divergent procurement pathways across OEM airframe programs and aftermarket channels. Technology selection, application scope, and end-user type each impose distinct certification burdens and margin structures that reshape supplier positioning.
Technology:
Channel mix varies sharply by heating mechanism, with electrothermal systems flowing through airframe OEM contracts while nanocoatings penetrate regional jet retrofits and UAV platforms.
- Electrothermal Systems:Embedded metallic heater grids laminated between glass plies deliver predictable thermal output across temperature differentials exceeding 60°C. Demand concentrates at Boeing and Airbus final assembly lines in the United States and France where Part 25 certification pathways are mature and failure modes are well-characterized.
- Nanocoatings:Graphene and carbon nanotube conductive films bond to polycarbonate substrates at thicknesses below 100 nanometers, enabling weight reductions critical for eVTOL platforms. Wichita and Montreal business jet OEMs are piloting these films for cabin humidity management in smaller aperture windshields, fragmenting procurement patterns toward dual-sourcing strategies.
- Conductive Films:Indium tin oxide and silver nanowire transparent conductors serve defogging applications in regional aircraft where optical clarity requirements are less stringent than transport category mandates.
- Hydrophobic Coatings:Fluoropolymer surface treatments repel water droplets without active heating, finding niche adoption in helicopter and general aviation segments.
- Photocatalytic Coatings:Titanium dioxide layers activated by UV exposure break down organic contaminants, deployed primarily in military applications where maintenance intervals are extended.
Electrothermal systems dominate installed base. Nanocoatings are where expansion concentrates.
Application:
Cost tier separation is pronounced across airframe categories, with commercial transport commanding premium multi-layer assemblies and UAV platforms accepting simplified single-function coatings.
- Commercial Aircraft:Wide-body and narrow-body fleets require dual-zone electrothermal redundancy meeting FAA-EASA harmonized standards, with heated windshield systems specified at the airframe program level. Guangzhou, Beijing, and Shanghai MRO hubs drive aftermarket replacement demand as China's domestic fleet age profiles mature.
- Military Aircraft:Transparent armor integration with thermal management adds ballistic protection requirements under MIL-STD-810, constraining supplier qualification to defense-specialized transparency houses.
- Private Jets:Weight-driven polycarbonate substitution in light and mid-size business jets expands addressable surface area for conductive nanocoating applications.
- Helicopters:Large aperture requirements and vibration environments favor robust electrothermal grids over thin-film alternatives.
- Unmanned Aerial Vehicles:Power-constrained platforms seek solid-state heating layers without pressurized bleed air, opening qualification pathways for simplified thermal management architectures.
Commercial aircraft absorb majority procurement volume. Military and UAV segments are climbing the fastest.
Product Type:
Customer type dictates specification authority, with OEM engineering teams controlling new-build layer selection and airline technical procurement consolidating replacement decisions into power-by-the-hour contracts.
- Dual-Function Layers:Single bond-line assemblies combining anti-icing and defogging reduce part counts and installation labor, commanding premium positioning at Airbus and Boeing where line-fit integration minimizes downstream maintenance.
- Anti-Icing Layers:High-capacity electrothermal systems operating at 2-8 kW per square meter maintain optical clarity during atmospheric icing encounters, specified for flight-critical forward windshields.
- Defogging Layers:Lower-power conductive coatings address cabin humidity excursions in side windows and eyebrow panels.
- Replacement Films:Aftermarket refurbishment materials bypass traditional distributor markup as predictive replacement scheduling via flight data analytics enables direct-to-operator coating supply.
- Retrofit Kits:Supplementary heating layer packages for aging fleet upgrades, concentrated in Southeast Asia where low-cost carrier fleet standardization enables volume-based supplier consolidation.
Dual-function layers command highest margins. Replacement films are gaining share fastest.
End User:
Supply concentration aligns with procurement scale, with airline group-level contracts consolidating specification authority and fragmenting distributor relationships.
- Airline Operators:Technical procurement teams at Lufthansa, Delta, and Air China consolidate windshield replacement into airframe-level maintenance contracts, capturing coating specification authority previously held by component distributors.
- Aircraft Maintenance Organizations:Lufthansa Technik and ST Engineering capture specification authority as maintenance integrators, most visible in Southeast Asia where fleet standardization enables volume-based supplier consolidation.
- Defense Aviation:Military procurement through defense ministries adds compliance layers under MIL-STD-810 and DEF STAN 00-35, constraining supplier pools to cleared transparency houses.
- Private Operators:Fragmented demand across fractional ownership and charter fleets sustains distributor relationships for replacement film supply.
- UAV Operators:Emerging eVTOL OEMs in the United States and Germany seek simplified thermal management without pressurized systems, opening qualification pathways for solid-state heating specialists.
Airline operators concentrate procurement volume. UAV operators are where supplier qualification activity is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in China by margins reflecting FAA certification premiums and domestic OEM concentration. French suppliers capture value through EASA harmonization advantages in European aftermarket channels. Geographic clustering around final assembly lines and MRO hubs determines regional procurement leverage.
United States
Boeing's Renton and Everett assembly lines compress supplier lead times for heated windshield systems, forcing coating specialists toward glass lamination integration. FAA Part 25 ice protection mandates create baseline demand for electrothermal heater mat systems across new-build commercial fleets. Wichita business jet OEMs pilot graphene-based conductive films for cabin humidity management in smaller aperture windshields.
France
Airbus final assembly in Toulouse and Saint-Nazaire anchors European demand for dual-function anti-icing and defogging layers. EASA F-Gas Regulation restrictions force coating formulators to eliminate sulfur hexafluoride from plasma-enhanced chemical vapor deposition processes. French transparency suppliers accelerate qualification submissions for fluorine-free nanocoating architectures through 2024-2025 certification windows.
China
Guangzhou, Beijing, and Shanghai MRO hubs drive aftermarket replacement demand as domestic fleet age profiles mature. CAAC CCAR-25 provisions dictate minimum heating capacity and optical transmission thresholds shaping product development roadmaps. Indium tin oxide supply concentration exposes coating specialists to input cost volatility and export control risk from Chinese rare earth processing capacity.
Germany
Lufthansa Technik captures coating specification authority as maintenance integrators consolidate windshield replacement into airframe-level power-by-the-hour contracts. EU Green Deal sustainable chemistry incentives reward coating formulators eliminating perfluorinated compounds with preferential supplier status. German eVTOL OEMs seek simplified thermal management without pressurized bleed air, opening qualification pathways for solid-state heating layers.
United Kingdom
Defense aviation procurement through the Ministry of Defence adds compliance layers under DEF STAN 00-35, constraining supplier pools to cleared transparency houses. GKN Aerospace anchors European supply through electrothermal heater mat capabilities and airframe integration expertise. London-based airline technical procurement teams fragment distributor relationships as fleet standardization enables volume-based supplier consolidation.
Cockpit Windshield Anti-Icing and Defogging Layer Technologies Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in cockpit windshield thermal management, with integrated systems houses commanding certification premiums while coating specialists compete on material substitution economics. The vendor base organizes around three strategic archetypes: vertically integrated glass-and-coatings platforms, electrothermal heater mat specialists, and transparent armor substrate leaders. Dominant competitive moves include backward integration into glass lamination and strategic partnerships with eVTOL OEMs seeking simplified thermal architectures.
Among North American and European systems houses, PPG Industries, GKN Aerospace, and Saint-Gobain Aerospace exemplify the integrated platform archetype that controls supply security for major airframers. PPG Industries occupies a position representing vertically integrated glass-and-coatings capabilities. GKN Aerospace anchors European supply relationships through electrothermal expertise. Saint-Gobain Aerospace sits within the transparent armor and advanced glass substrate tier that forms structural foundations for multi-function ice-protection layers.
| Leading Market Players |
|---|
| PPG Industries |
| GKN Aerospace |
| Saint-Gobain Aerospace |
| Gentex |
| The NORDAM Group |
| Liebherr |
| Hutchinson |
| Safran |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
FAA Part 25 ice protection certification gates both supplier qualification and price differentiation simultaneously, with airframe OEMs commanding configured-to-order premiums while aftermarket channels face cost compression from maintenance integrators. The certification burden creates a bifurcated structure where dual-certified products capture sustained margin premiums.
Pricing Analysis
Configured-to-order pricing for line-fit electrothermal systems at Boeing and Airbus commands substantial premiums over standard aftermarket replacement films. Price differentiation hinges on certification grade—FAA-EASA dual certification versus single-jurisdiction approval—and volume scale tied to airframe program commitments. Cost compression in the aftermarket tier is intensifying because airline technical procurement teams consolidate replacement decisions into power-by-the-hour contracts. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while flag carriers in Europe and North America prioritize supply security over unit cost.
Supply Chain Analysis
Inbound logistics costs from Chinese rare earth processing centers through Shanghai and Tianjin ports expose coating specialists to container availability constraints on the Asia-North America trade lane. Manufacturing concentrates in the United States, France, and China where final assembly lines and MRO hubs cluster. Raw material dependencies center on indium tin oxide transparent conductors, silver nanowire feedstock, and specialized glass substrates. Single-source vulnerability in Chinese rare earth processing capacity constitutes the dominant structural risk. Distribution runs through airframe OEM contracts for new-build systems and maintenance integrators for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as airline group-level contracts and maintenance integrators displace traditional component distributors, fragmenting supplier relationships toward volume-based consolidation.
For Market Incumbents: Shield certification premiums by deepening backward integration into glass lamination to control supply security for major airframers. Accelerate qualification submissions for fluorine-free nanocoating architectures ahead of EASA F-Gas Regulation enforcement windows. The threat of graphene-based transparent conductive films from specialist entrants demands captive production of electrothermal heater mat capabilities to maintain airframe integration relationships. For New Entrants and Emerging Players: Lead with solid-state heating layer architectures targeting eVTOL OEMs in Germany and the United States where simplified thermal management without pressurized bleed air opens qualification pathways. The UAV segment represents the most penetrable application tier given power-constrained platform requirements and reduced certification friction. A direct-to-operator go-to-market angle leveraging predictive replacement scheduling via flight data analytics bypasses traditional distributor markup structures. For Investors and Strategic Acquirers: EASA F-Gas Regulation reshapes the acquisition landscape by rewarding coating formulators eliminating perfluorinated compounds with preferential supplier status at Airbus and Safran. Long-term viability over the projection horizon favors vertically integrated glass-and-coatings platforms over pure-play coating specialists exposed to indium tin oxide supply concentration. The signal to watch is qualification submission velocity for fluorine-free architectures through EASA certification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Lamination | Captures supply security for Boeing and Airbus heated windshield programs. |
| Fluorine-Free Nanocoating Qualification | Secures preferential supplier status under EU Green Deal procurement frameworks. |
| eVTOL Thermal Architecture Partnership | Opens qualification pathways with German and US urban air mobility OEMs. |
| Predictive Aftermarket Channel Digitization | Enables direct-to-operator coating refurbishment bypassing distributor markup. |
| Dual-Certification Investment | Commands premium positioning through FAA-EASA harmonized product portfolios. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline technical procurement directors, MRO facility managers at Guangzhou and Shanghai hubs, coating formulation chemists, and airframe OEM platform engineers. Secondary validation drew from FAA Part 25 certification databases, EASA CS-25 submission records, customs trade data on indium tin oxide imports, and SEC filings from publicly traded transparency suppliers. Bottom-up segment sizing triangulated against top-down fleet forecast models.
Across the analysis window, the forecasting framework modeled technology adoption curves, airframe production rates, and aftermarket replacement cycles segmented by heating mechanism, application scope, and end-user procurement authority. CAGRs were derived from fitted growth curves calibrated to fleet modernization timelines and regulatory mandate implementation schedules. Industry-specific inputs included Boeing and Airbus delivery forecasts and China's domestic fleet age profile maturation.
The analysis sits within stated boundaries; outcomes outside sustained commercial aviation production rates, stable rare earth processing capacity, or harmonized FAA-EASA certification pathways would require recalibration. Forecasts reflect documented assumptions regarding coating chemistry transitions and maintenance contract consolidation trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cockpit Systems
Cockpit Display Market
Aircraft Cockpit Systems
Digital Glass Military Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Glass Cockpit for Aerospace Market
Aircraft Cockpit Systems
Global Aircraft Cockpit Display System Market
Aircraft Cockpit Systems
Aviation Headsets Market
Aircraft Cockpit Systems
Aircraft Synthetic Vision System Market
Aircraft Cockpit Systems
Global Aerospace Helmet Mounted Display Market
Aircraft Cockpit Systems
Aircraft Glareshield Lighting Market
Aircraft Cockpit Systems
Cockpit Module Market
Aircraft Cockpit Systems
Aircraft Cockpit Systems Market
Aircraft Cockpit Systems
Aerospace Head Up Display Market