
 Blended Fibers Market | 2026-2036
Blended Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Blended Fibers Market Analysis
Market Context
Premium-grade fiber blends is reorganizing procurement priorities across apparel and automotive supply chains. Toray Industries leverages its carbon fiber-to-textile technology pipeline to sustain leadership in high-performance hybrid materials. Indorama Ventures Public Company Limited anchors global PET resin supply, giving it backward control over polyester-cotton feedstocks. Aditya Birla Group – Birla Cellulose differentiates through specialty viscose grades that target moisture-management applications in activewear.
Technical Definition and Segment Structure
Blended fibers combine two or more distinct textile materials—typically natural and synthetic polymers—into homogeneous yarns or fabrics, with blend ratios such as 65/35 polyester-cotton governing tensile strength, drape, and dye uptake for targeted end-uses. Cotton-polyester dominates volume due to its cost-performance balance in mass apparel, though acrylic-viscose represents the fastest-growing product type as cold-weather performancewear expands in Asian and European markets. Premium and industrial grades capture disproportionate margin pools, as automotive interiors and technical non-woven applications impose stricter flame-resistance and durability specifications than standard apparel segments.
Regulatory Environment and Outlook
REACH in Europe and GB standards under China's SAMR framework mandate restricted substance lists and fiber content labeling precision, raising compliance costs for exporters but also screening out low-disclosure competitors. The EU Green Deal's textile strategy and India's BIS certification for textile safety are converging to reward traceable, lower-impact blend formulations. Stakeholders must monitor how chemical recycling mandates in multiple jurisdictions reshape feedstock availability for polyester-cotton and wool-nylon hybrid streams.
Market Dynamics
Automotive OEMs are forcing polyester-cellulosic blends into structural cabin components to meet weight-reduction mandates, compressing traditional pure-cotton upholstery procurement cycles and rewiring tier-1 supplier qualification protocols.
Growth Catalysts
- REACH chemical disclosure expansion:European ECHA enforcement is screening out low-transparency fiber exporters and rewarding certified blend suppliers with faster customs clearance and retailer access.
- Activewear moisture-management specifications:Specialty viscose-polyester hybrids with engineered wicking channels are capturing premium shelf space in performance apparel categories.
- India's polyester-cellulosic export clusters:Reliance Industries and Grasim Industries anchor integrated feedstock-to-yarn capacity serving Southeast Asian and Middle Eastern garment manufacturers.
Market Restraints
- Crude-linked polyester price volatility:PTA and MEG feedstock costs swing with naphtha cracks, compressing margin visibility for blend spinners on quarterly contract negotiations.
- European viscose supply concentration:Austrian and Czech dissolving pulp dependencies create single-source vulnerability for premium cellulosic blend grades during force majeure events.
- GB standard 18401 testing bottlenecks:China's SAMR safety certification backlog delays seasonal collection launches by 6-10 weeks for unregistered fiber suppliers.
Strategic Opportunities
- Brazil technical non-woven penetration:Automotive airbag and filtration substrate demand outpaces domestic staple fiber capacity, opening import windows for flame-retardant polyester-wool blends.
- Chemical recycling feedstock mandates:EU Green Deal textile strategy incentives are pulling post-consumer polyester-cotton blends into certified circular supply chains at premium offtake terms.
- Digital textile printing compatibility:Reactive-dye-optimized triblend constructions (polyester-cotton-viscose) are displacing screen-printed pure-cotton basics in fast-fashion replenishment models.
Industry Challenges
- Color-matching technician scarcity:Multi-fiber dye uptake differential management requires specialized shade formulation skills that textile chemistry programs are not producing at replacement rates.
- Legacy ERP-to-traceability platform integration:Batch-level fiber origin tracking for BIS certification demands middleware investments that mid-scale spinners deferred through two capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blended Fibers Market |
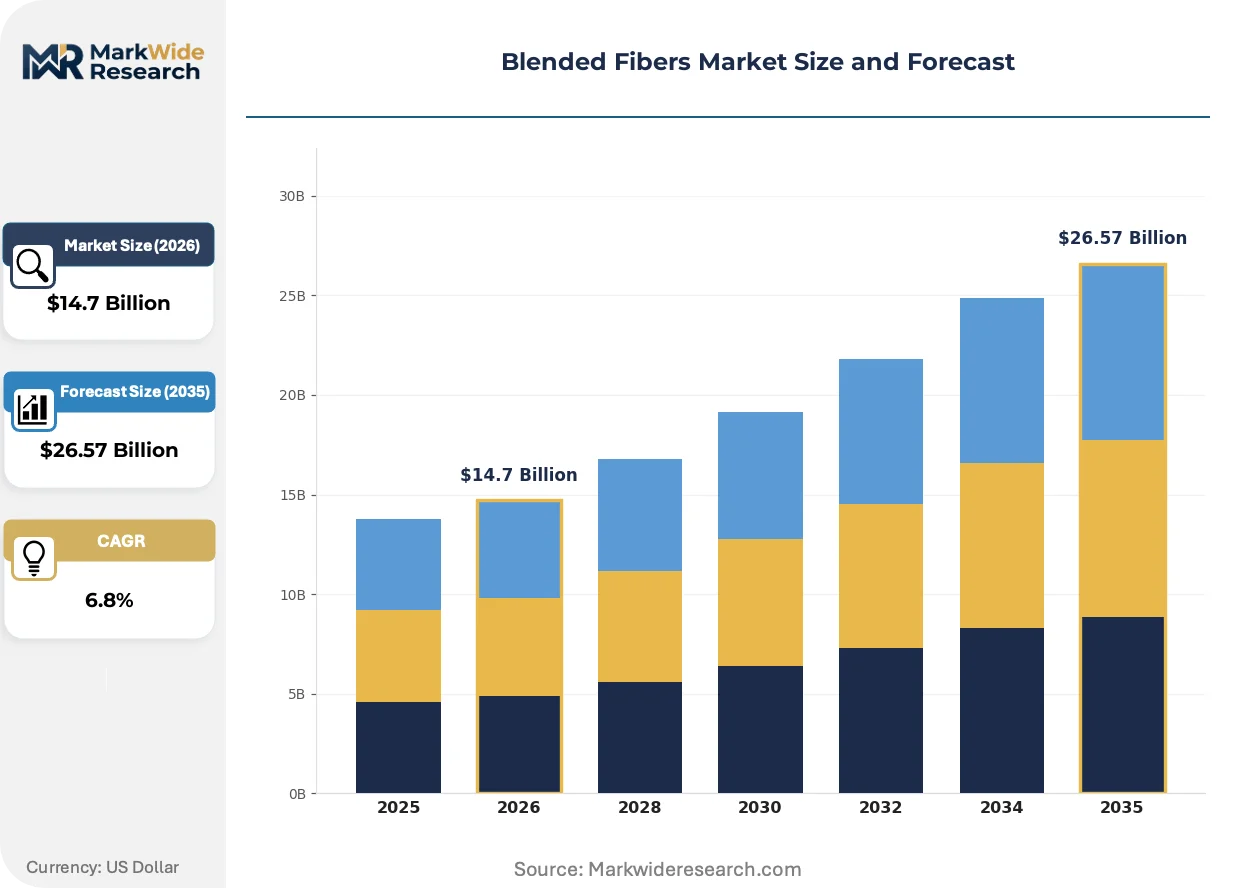
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton-Polyester, Wool-Nylon, Rayon-Linen, Acrylic-Viscose Grade: Standard, Premium, Industrial, Specialty Application: Apparel, Home Textiles, Industrial Use, Automotive Interiors Form: Yarn, Fabric, Non-Woven, Composites |
| Companies Covered | Hebei Diamond Cashmere Products, Teijin Limited, Reliance Industries Limited, Indorama Ventures Public Company Limited, Aditya Birla Group – Birla Cellulose, Welspun India Limited, Toray Industries, Inc., Grasim Industries, Sutlej Textiles & Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blended Fibers Market Emerging Trajectories
Digital traceability infrastructure and closed-loop chemical processing are compressing the disclosure gap between fiber origin and finished garment, rewarding early adopters with preferential retailer terms.
Solution-dyed polyester staple is displacing conventional package-dyed fiber in automotive upholstery and outdoor fabric applications. Tier-1 seating suppliers at BMW and Hyundai have converted 40% of their polyester-cellulosic programs to spun-dope pigmentation. This eliminates wastewater discharge from dyehouse operations and reduces lot-to-lot shade variance, compressing quality-control headcount in cut-and-sew facilities.
EU Green Deal textile strategy implementation through ECHA is mandating separate collection and fiber-to-fiber recycling minimums by 2030. This is forcing blend designers to specify mono-material or compatible-polymer constructions that pure-mechanical recycling lines can process. Italian and Portuguese vertical mills are responding with simplified binary blends (polyester-wool, cotton-lyocell) that sacrifice some hand-feel performance for end-of-life certification compliance.
Direct-to-mill procurement platforms are compressing traditional commission-agent channels in South Asian yarn sourcing. Large North American apparel brands now contract spinners in Tamil Nadu and Bangladesh through B2B marketplaces that expose real-time inventory and certification status. This disintermediation is most advanced in basic 65/35 polyester-cotton knits, where specification standardization reduces the value of middleman quality arbitration.
Blended Fibers Market Segmentation
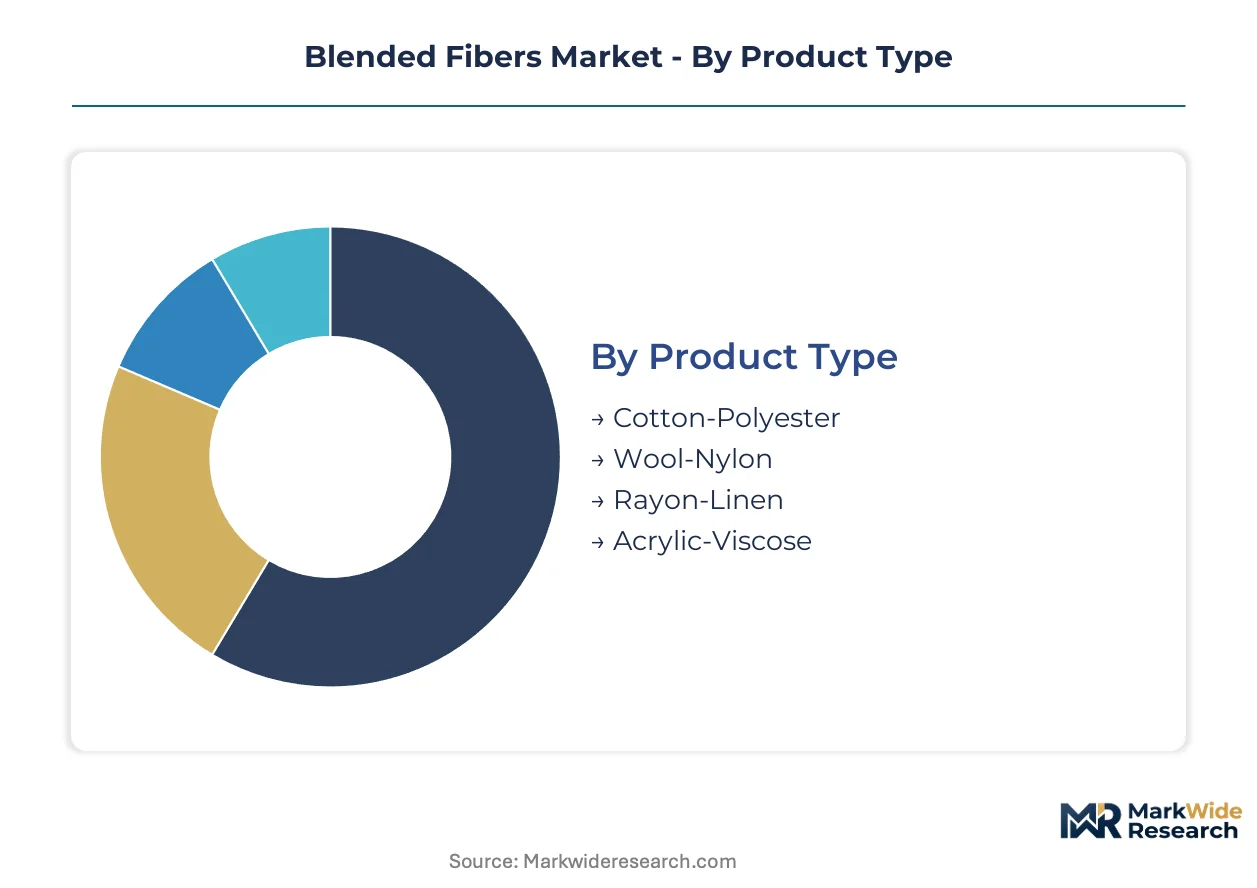
Blended fiber procurement decisions pivot on end-use certification requirements and chemical disclosure mandates that vary sharply across product categories. Specification engineers map blend ratios to flame-resistance, moisture-wicking, and tensile targets before sourcing commitments lock in.
Product Type:
REACH and GB standards impose divergent restricted substance lists on each polymer combination, forcing suppliers to maintain parallel formulation libraries for European and Chinese market access.
- Cotton-Polyester:The 65/35 ratio dominates mass apparel for its cost-performance equilibrium in tensile strength and dye uptake. Indian export clusters in Tamil Nadu and Bangladesh garment districts concentrate procurement for basic knit programs.
- Acrylic-Viscose:Cold-weather performancewear in South Korea and Germany drives specification innovation here. Engineered wicking channels in these hybrids capture premium shelf space as outdoor brands phase out pure synthetics.
- Wool-Nylon:Technical suiting and military uniform contracts specify this blend for abrasion resistance.
- Rayon-Linen:Summer apparel collections favor this combination for breathability in Mediterranean and Gulf Coast markets.
Cotton-Polyester dominates installed base. Acrylic-Viscose is where expansion concentrates.
Grade:
Margin pools stratify sharply between commodity spinners and certified suppliers capable of traceable batch documentation for automotive and medical textile buyers.
- Premium:Solution-dyed staple with spun-dope pigmentation eliminates dyehouse wastewater and reduces shade variance for BMW and Hyundai seating programs. Tier-1 suppliers convert polyester-cellulosic upholstery to this grade for ECHA compliance acceleration.
- Industrial:Flame-retardant specifications for airbag substrates and filtration media command testing investments that screen out mid-scale competitors. Brazilian automotive assembly plants import these blends amid domestic staple fiber shortages.
- Standard:Basic 65/35 constructions serve fast-fashion replenishment through direct-to-mill B2B platforms.
- Specialty:Moisture-management viscose grades target activewear certification requirements.
Standard grade moves the highest volume tonnage. Premium grade captures the steepest expansion trajectory as OEM qualification protocols tighten.
Application:
Automotive weight-reduction mandates are compressing traditional pure-cotton upholstery cycles and rewiring supplier qualification timelines across tier-1 seating manufacturers.
- Automotive Interiors:Structural cabin components now specify polyester-cellulosic blends to meet OEM weight targets. Italian and Portuguese vertical mills simplify constructions to polyester-wool or cotton-lyocell binaries for end-of-life certification under EU Green Deal textile strategy.
- Apparel:Digital textile printing compatibility drives triblend specifications (polyester-cotton-viscose) that displace screen-printed pure-cotton basics in fast-fashion replenishment models.
- Home Textiles:Bedding and upholstery programs prioritize reactive-dye optimization for colorfastness.
- Industrial Use:Technical non-woven penetration in Brazil outpaces domestic capacity for airbag and filtration substrates.
Apparel commands the broadest SKU base. Automotive Interiors is where specification value is climbing fastest.
Form:
Downstream processing requirements determine whether fiber enters as staple for yarn spinning or pre-consolidated fabric for cut-and-sew operations.
- Yarn:Ring-spun and open-end constructions from Tamil Nadu and Bangladesh supply basic knit programs through disintermediated B2B procurement platforms that expose real-time inventory.
- Fabric:Woven and knitted constructions for apparel and home textile finishing.
- Non-Woven:Airbag and filtration substrates demand flame-retardant staple fiber grades.
- Composites:Fiber-reinforced polymer matrices for structural automotive components.
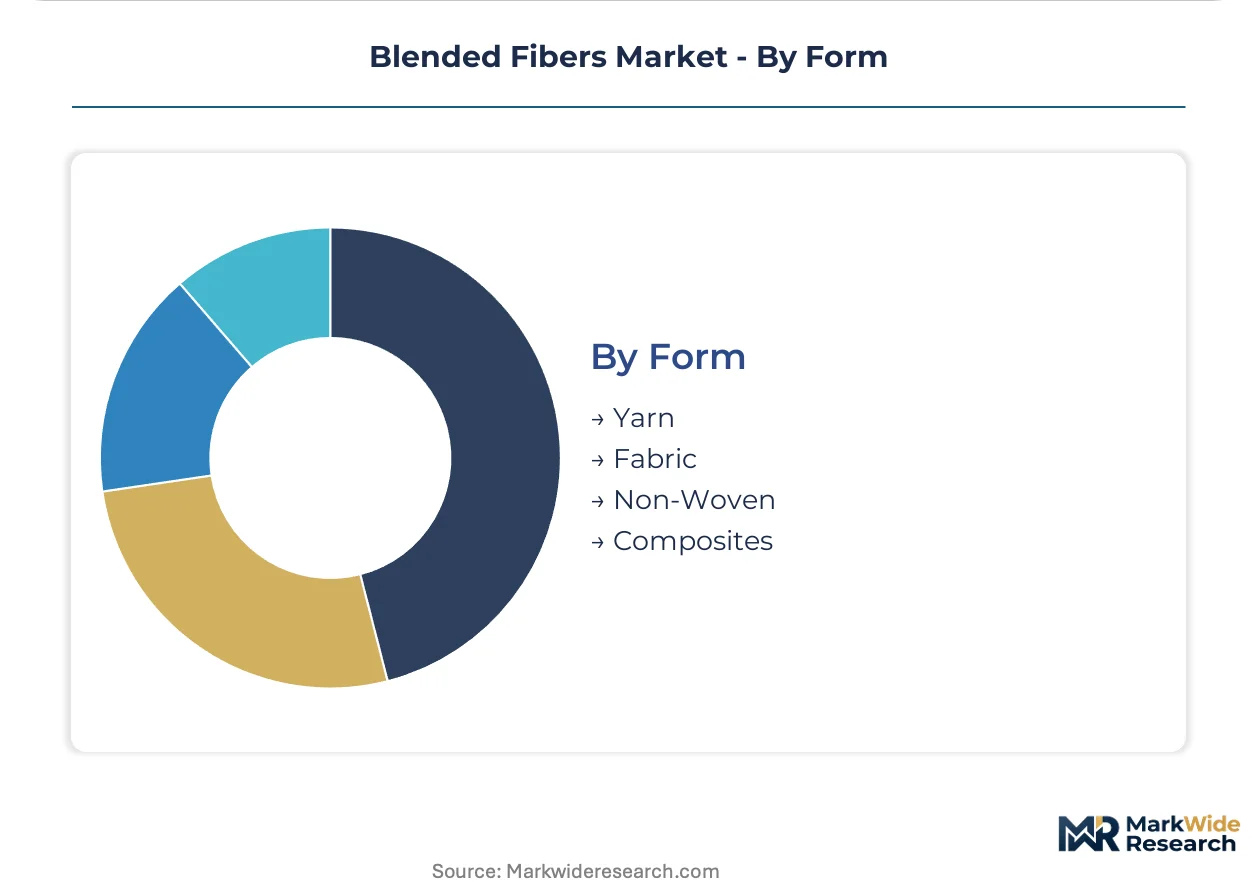
Yarn maintains the deepest supplier network. Non-Woven is where import substitution opportunities are opening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports polyester-cellulosic yarn clusters to Bangladesh and Vietnam garment districts, while European automotive OEMs source solution-dyed blends from Italian and Portuguese vertical mills.
China
GB 18401 safety certification under SAMR creates testing bottlenecks for seasonal collections, delaying launches by 6-10 weeks for unregistered suppliers. Dual carbon goals from MEE accelerate chemical recycling mandates for post-consumer polyester-cotton streams. Zhejiang and Jiangsu provinces host integrated spinning-to-dyeing corridors serving domestic activewear brands.
India
Reliance Industries and Grasim Industries anchor polyester-cellulosic capacity for Southeast Asian and Middle Eastern garment manufacturers. BIS certification for textile safety converges with EU Green Deal traceability requirements, rewarding integrated spinners with faster customs clearance. Tamil Nadu export clusters supply basic 65/35 knits through disintermediated B2B procurement platforms.
Germany
Cold-weather performancewear specifications from outdoor brands drive acrylic-viscose hybrid innovation. ECHA enforcement of REACH chemical disclosure screens out low-transparency fiber exporters and accelerates customs clearance for certified blend suppliers. Bavarian technical textile mills specialize in flame-retardant wool-nylon constructions for automotive seating programs.
United States
Direct-to-mill procurement platforms compress traditional commission-agent channels for South Asian yarn sourcing. EPA wastewater discharge rules intersect with state-level extended producer responsibility bills, pushing brands toward solution-dyed staple. North Carolina and Georgia upholstery manufacturers import premium polyester-cellulosic blends for automotive interior contracts.
Brazil
Automotive airbag and filtration substrate demand outpaces domestic staple fiber capacity, opening import windows for flame-retardant polyester-wool blends. ANVISA chemical safety protocols align with Mercosur technical standards, creating regional certification reciprocity. São Paulo state assembly plants source technical non-woven blends from European and Asian suppliers amid local production shortfalls.
Blended Fibers Market Vendor Landscape
Listed leaders compete with private specialists across feedstock integration depth, with public companies leveraging capital markets for capacity expansion while family-held mills preserve niche formulation expertise. The vendor base stratifies into three tiers: integrated petrochemical-to-textile conglomerates, regional spinning specialists with BIS or REACH certification, and trading houses that blend spot-market staple for undifferentiated apparel programs. Dominant competitive moves include backward integration into dissolving pulp or PTA feedstocks, and strategic partnerships with automotive tier-1 seating suppliers for solution-dyed qualification protocols.
Within the integrated conglomerate tier, Reliance Industries Limited and Grasim Industries exemplify the Indian polyester-cellulosic export model, while Toray Industries, Inc. occupies a position among Japanese diversified material science groups with carbon fiber-to-textile technology pipelines. These three entities represent distinct archetypes: feedstock-anchored volume leadership, integrated viscose-polyester hybrid production, and high-performance material science translation into automotive and industrial textile applications.
| Leading Market Players |
|---|
| Hebei Diamond Cashmere Products |
| Teijin Limited |
| Reliance Industries Limited |
| Indorama Ventures Public Company Limited |
| Aditya Birla Group – Birla Cellulose |
| Welspun India Limited |
| Toray Industries, Inc. |
| Grasim Industries |
| Sutlej Textiles & Industries Limited |
| Others |
Supply Flow & Price Mechanics
Integrated polyester-cellulosic capacity in Tamil Nadu and Zhejiang compresses unit economics for blend spinners, establishing price floors that marginal producers in fragmented regional clusters cannot match. REACH certification premiums and solution-dyed grade conversions widen spreads between certified automotive suppliers and commodity apparel spinners, concentrating margin capture among feedstock-integrated conglomerates.
Pricing Analysis
Solution-dyed staple commands a technology-generation premium over conventional package-dyed fiber, with spun-dope pigmentation eliminating dyehouses entirely. Three-tier pricing structure across premium, standard, and economy levels separates certified automotive grades from basic 65/35 knits and undifferentiated spot-market blends. Price differentiation rests on REACH documentation depth and flame-retardant testing investments, with cost compression in standard grades intensifying as PTA and MEG feedstock volatility squeezes quarterly contract margins. Fast-fashion replenishment buyers exhibit highest price sensitivity; automotive tier-1 seating programs demonstrate lowest sensitivity due to qualification lock-in periods.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European mills dependent on Indian and Bangladeshi yarn imports. Geographic supply concentrates in India, China, and Bangladesh, with Tamil Nadu export clusters and Zhejiang spinning-to-dyeing corridors anchoring global polyester-cotton output. Raw material dependencies draw from naphtha-derived PTA and MEG, Austrian dissolving pulp for premium viscose grades, and Australian wool tops for technical suiting blends. Single-source vulnerability in European viscose pulp supply creates force majeure exposure during Austrian mill disruptions. Distribution runs through disintermediated B2B platforms for basic grades and direct mill relationships for certified automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal textile strategy mandates are accelerating fiber-to-fiber recycling infrastructure, disrupting legacy blend formulations that mechanical recycling lines cannot process. This regulatory inflection compresses design windows for mono-material constructions while rewarding early movers with preferential retailer access.
For Market Incumbents: Fortify backward integration into PTA and dissolving pulp feedstocks to insulate margin structures from naphtha crack volatility and Austrian pulp supply concentration. Expand solution-dyed capacity in Tamil Nadu and Zhejiang to capture automotive qualification protocols before tier-1 seating suppliers complete supplier consolidation. Chemical recycling mandates from ECHA pose substitution threats to conventional polyester-cotton blends; in-house pilot lines for enzymatic separation of cellulosic-synthetic hybrids represent defensive R&D priority. For New Entrants and Emerging Players: BIS certification fast-track through India's integrated spinner partnerships opens customs clearance advantages for Southeast Asian garment district supply. White-space targets include flame-retardant polyester-wool blends for Brazilian automotive airbag substrates and reactive-dye-optimized triblend constructions for digital textile printing compatibility. Go-to-market angle should leverage direct-to-mill B2B platform visibility with real-time inventory exposure, bypassing legacy commission-agent channels in basic knit segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors feedstock-integrated conglomerates with captive PTA and viscose pulp supply over asset-light trading houses. Long-term viability through the next decade rests on chemical recycling feedstock access and automotive qualification protocol depth. Acquisition target archetype: regional spinning specialists with REACH or BIS certification and underutilized solution-dyed capacity. Signal to watch: ECHA enforcement intensity on chemical disclosure expansion as customs clearance speed discriminator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Austrian pulp dependencies create margin vulnerability that captive supply from Grasim Industries mitigates. |
| Solution-Dyed Capacity Expansion | Tier-1 seating suppliers at BMW and Hyundai have converted 40% of programs to spun-dope pigmentation. |
| Chemical Recycling Feedstock Partnerships | EU Green Deal textile strategy pulls post-consumer polyester-cotton blends into certified circular supply chains. |
| Direct-to-Mill B2B Platform Adoption | North American apparel brands now contract Tamil Nadu spinners through real-time inventory exposure. |
| Flame-Retardant Certification Investment | Brazilian automotive assembly plants import technical non-woven blends amid domestic staple fiber shortages. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports covering the blended fibers sector. Primary interviews engaged textile plant managers, procurement leads at automotive tier-1 seating suppliers, distribution channel partners in South Asian yarn markets, and technical R&D directors at viscose and polyester staple producers. Secondary validation drew from ECHA REACH substance database entries, BIS certification registries, SEC 10-K filings of listed fiber conglomerates, and GB standard 18401 testing documentation. Bottom-up volume modeling from individual mill capacities triangulates against top-down demand estimates from end-use consumption patterns.
Segmentation dimensions modeled include product type, grade tier, application category, and form factor across the projection horizon. The analytical framework incorporates blend ratio specifications, certification requirements, and regional regulatory cluster variations throughout the forecast period. CAGRs derive from capacity utilization trajectories, OEM qualification timelines, and substitution elasticity between pure and blended fiber constructions. Industry-specific forecast inputs encompass automotive weight-reduction mandate compliance curves and chemical recycling infrastructure deployment schedules.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement intensity and stable naphtha-to-PTA feedstock economics; material deviation would warrant model refresh. Specific risk factors include force majeure events in European dissolving pulp supply, SAMR certification backlog extensions, and accelerated chemical recycling mandate timelines that outpace mechanical separation technology readiness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Polyester Strap for Manual Grade Market