
 Aramid Fiber Market | 2026-2036
Aramid Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Fiber Market Analysis
Performance-based maintenance contracts for ballistic vest lifecycle management is expanding the addressable revenue pool beyond raw fiber sales. DuPont de Nemours leverages its Kevlar brand equity and backward integration into polymer intermediates to sustain margin capture across the value chain. Teijin Limited anchors its position through Twaron production scale and dedicated aerospace qualification programs in Japan and Europe. Hyosung Corporation competes on cost-optimized meta-aramid output for industrial filtration and electrical insulation markets in Asia.
Aramid fibers are aromatic polyamide synthetic fibers characterized by high tensile strength-to-weight ratios, thermal stability exceeding 400°C decomposition thresholds, and inherent flame resistance without chemical treatment. These properties position the material as a critical input for ballistic protection systems, aerospace structural composites, and electrical insulation requiring dielectric integrity under thermal stress. Para-aramid commands the dominant value share due to its superior specific strength for armor and reinforcement applications, while meta-aramid captures stable demand from firefighter protective apparel and hot-gas filtration where thermal endurance outweighs modulus requirements. The filament form leads in aerospace prepreg and continuous fiber-reinforced thermoplastic processing, whereas chopped fiber grades penetrate automotive brake and clutch friction formulations where discontinuous reinforcement suffices.
OSHA workplace safety mandates in the United States and the EU PPE Regulation govern protective clothing certification, directly conditioning market access for aramid-based garments. China's GB standards for firefighter equipment and Japan's JIS certification for industrial safety textiles create layered compliance requirements that favor established producers with testing infrastructure. REACH chemical registration in Europe and evolving EPA guidelines on fiber handling protocols further shape product formulation and manufacturing site location decisions. Stakeholders must monitor the divergence between regional flame-resistance test methodologies and the accelerating substitution threat from ultra-high molecular weight polyethylene in select ballistic applications.
Market Dynamics
Defense procurement cycles for next-generation body armor and vehicle protection systems are compressing supplier qualification timelines while amplifying volume commitments to qualified aramid producers with established polymerization assets.
Growth Catalysts
- Ballistic modernization mandates:NATO member states and allied defense ministries are accelerating vest and helmet replacement programs. This creates sustained offtake for para-aramid grades qualified to NIJ and STANAG protocols.
- Industrial safety enforcement:OSHA's updated PPE standards for electrical utility workers and refinery operators mandate arc-rated garments. Aramid blends satisfy the 8 cal/cm² threshold without supplementary chemical treatment.
- Lightweighting imperatives in aerospace:Boeing and Airbus tier suppliers are qualifying thermoplastic composites with continuous aramid reinforcement for secondary structural components, displacing heavier metallics in cabin and cargo applications.
Market Restraints
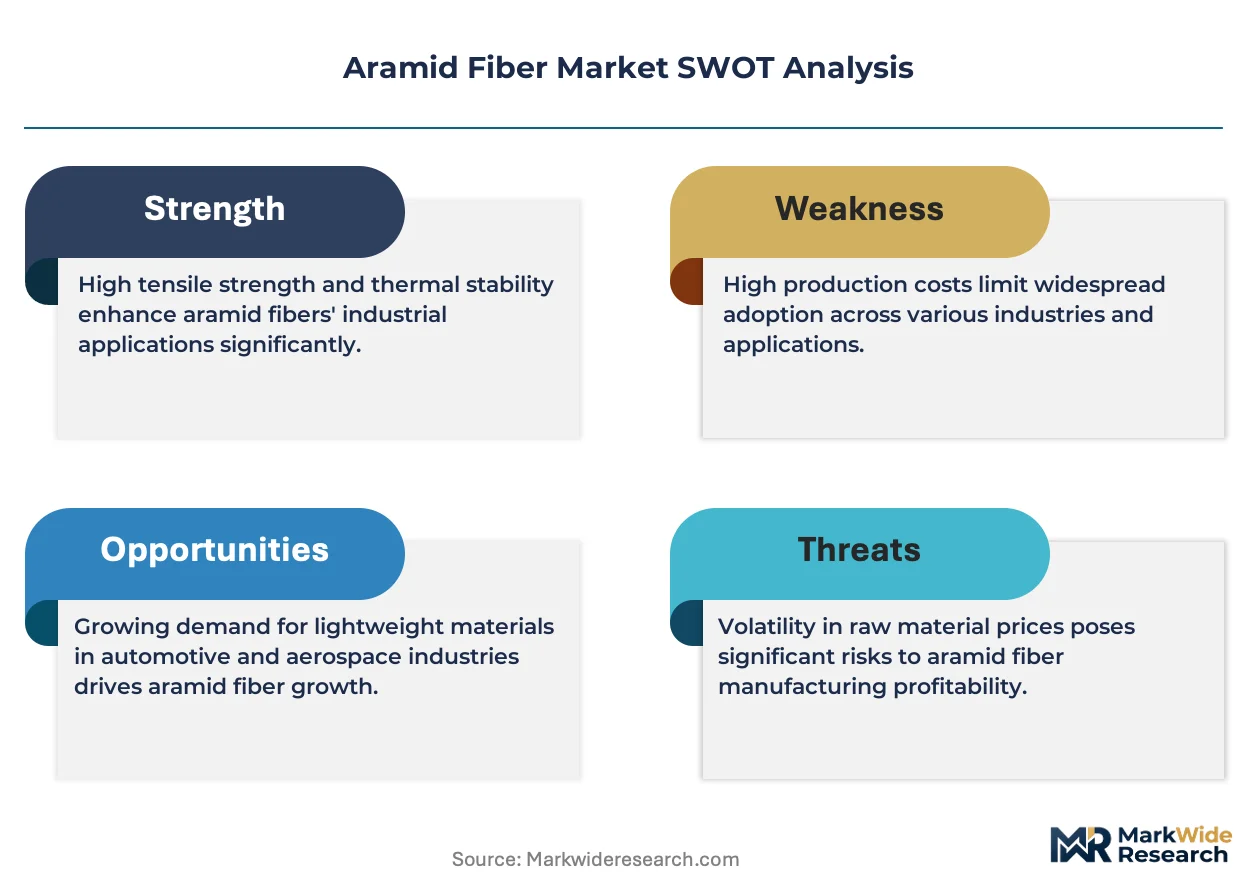
- Petrochemical feedstock volatility:Para-phenylenediamine and terephthaloyl chloride prices track benzene and chlorine derivatives, compressing spinneret-to-fiber margins during upstream commodity spikes.
- Concentrated polymerization capacity:Meta-aramid precursor synthesis clusters in Japan and the United States, exposing buyers to single-source risk during force majeure events at major polymer plants.
- Ultra-high molecular weight polyethylene substitution:Dyneema and Spectra fibers achieve comparable specific strength at lower areal density for select soft armor applications, threatening para-aramid volume in law enforcement procurement.
Strategic Opportunities
- India industrial safety expansion:BIS certification requirements for firefighter apparel and electrical worker protection are tightening under the 2020 National Building Code amendments, opening import substitution opportunities for qualified suppliers.
- Battery thermal runaway containment:Electric vehicle battery pack manufacturers are testing aramid nonwovens as cell-to-cell barriers and pack liners to delay propagation during thermal events, creating a new specification category.
- Green hydrogen infrastructure:High-pressure composite pressure vessels for hydrogen storage require filament-wound aramid overwrap layers to meet ISO 19881 burst requirements, linking fiber demand to energy transition capex.
Industry Challenges
- Polymer science talent scarcity:Aramid spinning requires expertise in liquid crystal polymer rheology and coagulation chemistry that resides at a handful of academic programs and incumbent producers, constraining new entrant hiring.
- Multi-jurisdiction certification backlog:Simultaneous pursuit of EU PPE Regulation (EU) 2016/425, OSHA NIOSH approval, and China's LA certification for a single product line extends time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Fiber Market |
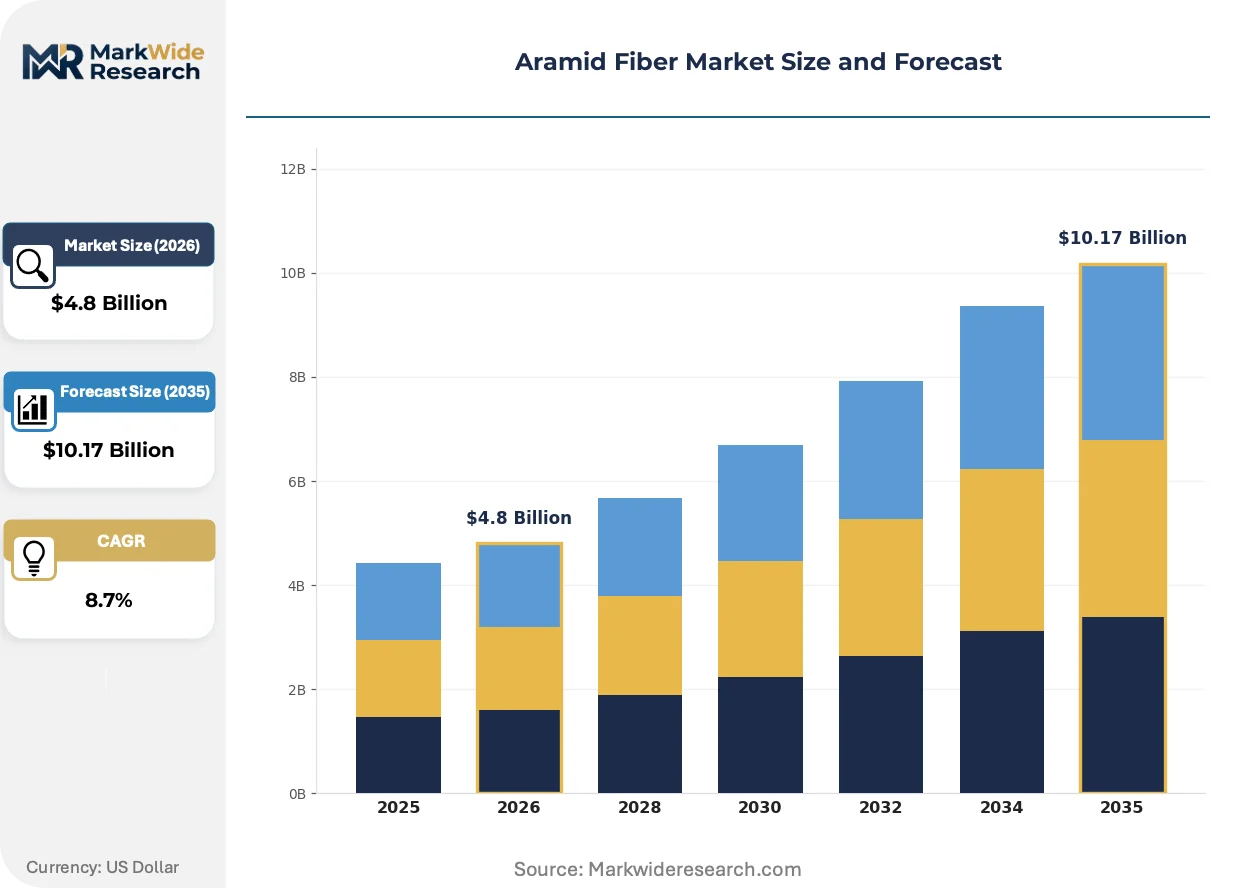
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Para-Aramid, Meta-Aramid, Blended Aramid, Others End User: Aerospace, Automotive, Construction, Electronics Application: Composites, Protective Clothing, Electrical Insulation, Fibers Form: Filament, Staple Fiber, Chopped Fiber, Others |
| Companies Covered | Hyosung Corporation, Kolon Industries, DuPont de Nemours, China National Bluestar Group, Kermel, Teijin Limited, Toray Industries, Huvis Corporation, Yantai Tayho Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Fiber Market Emerging Trajectories
Material science advances and procurement model evolution are compressing the traditional fiber-to-finished-goods value chain, enabling direct specification relationships between end-users and primary producers that bypass historical converter intermediaries.
Recycled aramid fiber recovery systems are integrating mechanical shredding and solvent reclamation processes to reclaim high-tenacity fibers from decommissioned ballistic vests and aerospace scrap. Defense logistics agencies in the United States and Germany are piloting closed-loop programs with qualified recyclers. This technology is integrating circular material flows into military procurement specifications, creating reserved supply pools that reduce virgin fiber dependence for non-critical applications.
REACH authorization requirements for residual monomer content in aramid intermediates are tightening detection thresholds and mandating supply chain documentation through SCIP database entries. ECHA enforcement actions against non-compliant importers have accelerated testing investments by Asian compounders. European aerospace tier suppliers now require full substance-of-very-high-concern screening certificates, conditioning market access on analytical infrastructure that smaller fiber converters cannot sustain.
Performance-based vest lifecycle contracts are replacing transactional bulk purchases among municipal police departments and federal law enforcement agencies. Armor assemblers now assume responsibility for inspection, refurbishment, and end-of-life recovery, bundling fiber costs into per-officer annual fees. This model concentrates buying power with integrators possessing logistics and field service networks, squeezing standalone fiber distributors in North American public safety channels.
Aramid Fiber Market Segmentation
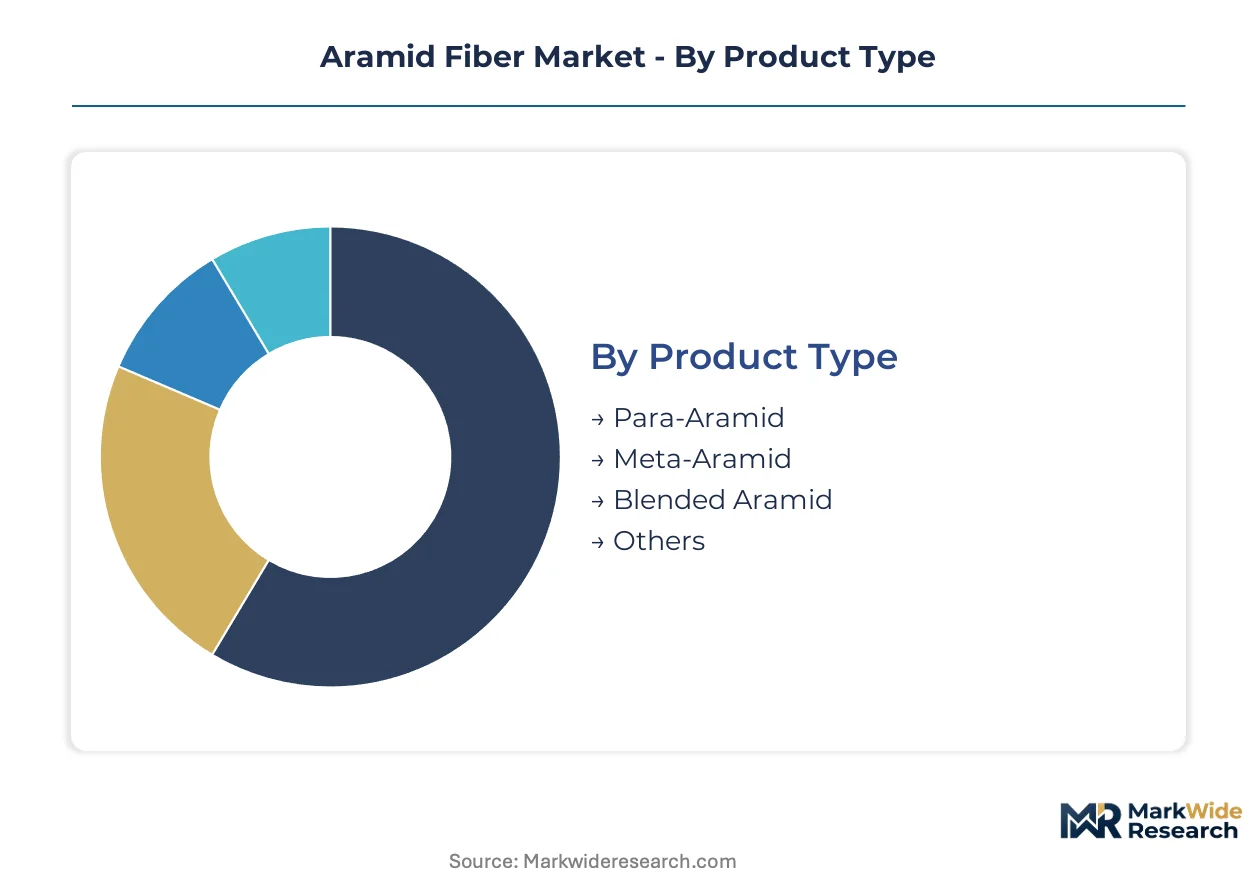
Aramid fiber procurement decisions hinge on thermal-mechanical trade-offs that vary sharply across end-use specifications. Segment boundaries increasingly blur as compounders engineer hybrid grades that straddle traditional para-meta divides.
Product Type:
Volume concentration sits with para-aramid for its specific strength premium, while meta-aramid commands stable margins through thermal endurance specialization.
- Para-Aramid:Liquid crystal polymer spinning yields fibers with tensile modulus exceeding 80 GPa and decomposition thresholds above 550°C. NATO ballistic vest programs and Boeing 787 secondary structures anchor demand in the United States and Japan. Price premiums compress during benzene feedstock spikes but recover through defense contract indexation clauses.
- Meta-Aramid:Isophthalic acid-based polymerization produces lower crystallinity fibers optimized for prolonged heat exposure rather than peak load bearing. Firefighter turnout gear in Germany and China's industrial safety procurement absorb consistent volumes. REACH SVHC screening requirements now condition European market access for all meta-aramid imports.
- Blended Aramid:Hybrid formulations with carbon or glass fiber target cost-optimized aerospace panels and automotive friction materials.
- Others:Experimental copolyaramids and modified spinning variants serve niche medical and filtration specifications.
Today's leader: Para-Aramid. Tomorrow's challenger: Blended Aramid.
End User:
Application pull concentrates in mobility sectors where mass reduction intersects with thermal protection mandates.
- Aerospace:Thermoplastic composite prepregs with continuous aramid reinforcement displace aluminum in cabin pressure bulkheads and cargo liners. Airbus tier suppliers in France and Germany qualify filament-wound pressure vessels for hydrogen storage systems. FAA certification timelines for novel resin matrices extend qualification cycles.
- Automotive:Chopped fiber grades penetrate brake pad formulations and clutch facings where discontinuous reinforcement suffices. Electric vehicle battery pack manufacturers test aramid nonwovens as cell-to-cell thermal barriers. NHTSA crashworthiness standards indirectly drive aramid composite adoption in structural energy absorption zones.
- Construction:Concrete reinforcement and geotextile applications absorb staple fiber volumes for crack resistance and soil stabilization.
- Electronics:Dielectric substrates and cable insulation exploit meta-aramid's thermal stability under electrical stress.
Aerospace captures the steepest expansion trajectory. Automotive offers the deepest volume pool.
Application:
Functional requirements fragment procurement between structural load-bearing and protective barrier specifications.
- Composites:Prepreg and filament winding processes dominate aerospace and pressure vessel fabrication. Boeing and Airbus qualification programs lock in supplier relationships for multi-year production blocks. Filament form commands premium pricing against chopped alternatives.
- Protective Clothing:Arc-rated garments for electrical utility workers and refinery operators satisfy OSHA 1910.269 mandates without supplementary chemical treatment. EU PPE Regulation (EU) 2016/425 tightens certification thresholds for flame resistance testing.
- Electrical Insulation:Transformer paper and motor slot liners exploit dielectric integrity under thermal cycling.
- Fibers:Rope and cable applications in offshore mooring and mining haulage absorb high-tenacity para-aramid output.
Composites lead on value per kilogram. Protective clothing provides demand stability through regulatory mandates.
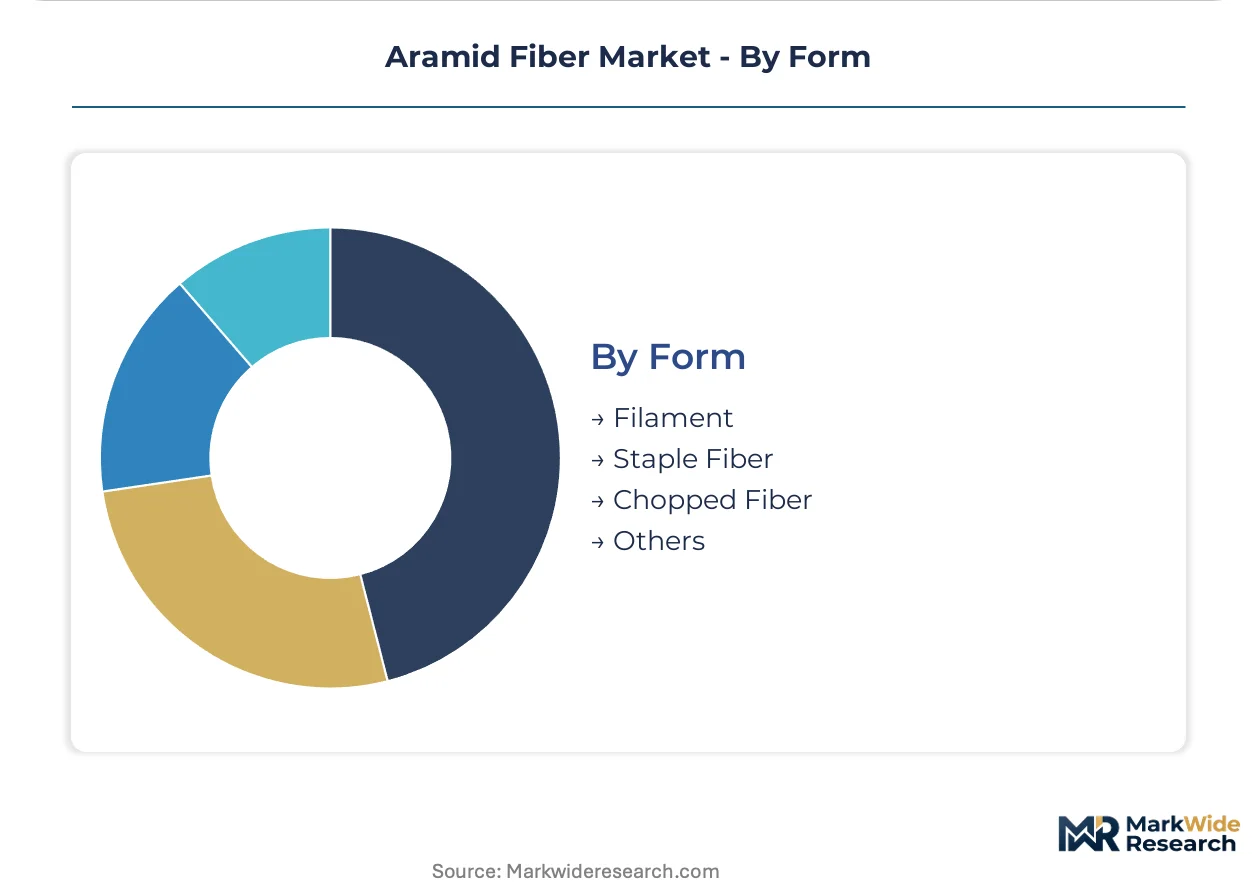
Form:
Processing economics separate continuous reinforcement from discontinuous compounding applications.
- Filament:Continuous fiber enables unidirectional prepreg and woven fabric production for aerospace primary and secondary structures. Surface treatment chemistry varies by resin system compatibility. Japan's aerospace qualification infrastructure favors domestic filament producers.
- Staple Fiber:Cut lengths for spun yarn production feed protective apparel and filtration media. Blending ratios with FR viscose or wool adjust cost-performance positioning.
- Chopped Fiber:Short-cut grades disperse in thermoset and thermoplastic matrices for automotive friction and general industrial composites.
- Others:Pulp and fibrid forms serve specialty paper and gasket applications.
Filament commands margin concentration. Chopped fiber scales through automotive contract volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting polymerization investments toward jurisdictions with streamlined chemical registration regimes. REACH compliance costs in Europe now exceed equivalent Asian certification by 40-60%, prompting capacity migration to integrated chemical parks with captive monomer supply.
United States
OSHA's updated 1910.269 arc-flash protection mandates drive electrical utility procurement of meta-aramid garments. The FAA certifies continuous filament prepregs for Boeing 787 secondary structures at facilities in Washington and South Carolina. DuPont's polymerization assets in Virginia and Tennessee anchor domestic para-aramid supply chains for defense vest programs.
Germany
ECHA enforcement of REACH SVHC screening restricts meta-aramid imports lacking SCIP database documentation. The KBA certifies aramid-reinforced hydrogen pressure vessels for automotive OEMs in Stuttgart and Munich. BASF's Ludwigshafen chemical complex hosts specialized polymer intermediate production serving European aerospace tier suppliers.
China
GB standards for firefighter equipment under the 2020 National Building Code amendments tighten BIS-equivalent certification requirements. MIIT's dual carbon goals accelerate electric vehicle battery thermal barrier testing at CATL and BYD facilities in Fujian and Guangdong. Yantai Tayho's Shandong production base scales cost-optimized meta-aramid for industrial filtration.
Japan
METI's JIS certification for industrial safety textiles conditions market access for protective apparel imports. Teijin's Matsuyama polymerization plant maintains dedicated aerospace qualification programs serving Airbus and Boeing tier suppliers in Nagoya and Hiroshima. Toray's Chiba facility develops hybrid aramid-carbon prepregs for next-generation aircraft interiors.
India
BIS certification requirements for firefighter apparel and electrical worker protection tighten under National Building Code amendments. The CEA mandates arc-rated garments for 33kV and above utility operations, opening import substitution opportunities. Gujarat's chemical corridor attracts filament winding operations for hydrogen infrastructure pressure vessels.
Aramid Fiber Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense and aerospace channels favoring established polymer producers while industrial filtration absorbs cost-optimized output from integrated chemical conglomerates. The market structure concentrates around three strategic archetypes: backward-integrated polymer science leaders, scale-driven Asian industrial fiber producers, and niche European thermal protection specialists. Competitive moves center on captive monomer supply security and multi-jurisdiction certification infrastructure rather than price-based volume capture.
Within the polymer science leader tier, DuPont de Nemours and Teijin Limited exemplify archetypes built on decades of liquid crystal spinning expertise and aerospace qualification relationships. Hyosung Corporation occupies a position among Korean industrial conglomerates leveraging integrated petrochemical feedstocks for cost-optimized meta-aramid production. These three anchors demonstrate how geographic clustering of polymerization assets and regulatory compliance infrastructure creates defensible positions across distinct end-use specifications.
| Leading Market Players |
|---|
| Hyosung Corporation |
| Kolon Industries |
| DuPont de Nemours |
| China National Bluestar Group |
| Kermel |
| Teijin Limited |
| Toray Industries |
| Huvis Corporation |
| Yantai Tayho Advanced Materials |
| Others |
Supply Flow & Price Mechanics
Filament-wound hydrogen pressure vessel qualification programs are compressing spinneret-to-fiber lead times while concentrating polymerization investments in integrated chemical parks with captive monomer supply. This manufacturing-method transition simultaneously elevates capital barriers for new entrants and anchors pricing power with backward-integrated producers possessing in-house para-phenylenediamine synthesis.
Pricing Analysis
Distributor margins for standard-grade meta-aramid staple compress under 15% as direct-to-OEM contracts for aerospace filament bypass converter intermediaries entirely. Three-tier pricing structure across defense-qualified, industrial-certified, and commodity filtration grades separates NIJ-certified para-aramid from REACH-compliant meta-aramid from unbranded Asian industrial output. Cost compression in the commodity tier intensifies because benzene derivative volatility erodes spinneret-to-fiber margins during upstream petrochemical spikes. Municipal police departments exhibit acute price sensitivity through performance-based vest lifecycle contracts, whereas Boeing and Airbus tier suppliers prioritize qualification security over unit cost.
Supply Chain Analysis
NIJ and STANAG certification gating restricts qualified para-aramid supply to polymerization assets in the United States, Japan, and the Netherlands, creating effective supply rationing for defense vest programs. The supply chain draws from para-phenylenediamine and terephthaloyl chloride precursors whose prices track benzene and chlorine derivatives, exposing margin stability to commodity volatility. Single-source vulnerability concentrates at Teijin's Matsuyama and DuPont's Richmond polymerization facilities, where force majeure events would disrupt NATO ballistic procurement. Distribution runs through aerospace tier suppliers and defense logistics agencies rather than open-market chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aramid fiber hinges on captive monomer supply security and the shift toward performance-based lifecycle contracts that bundle fiber costs into annual per-officer fees rather than transactional volume sales.
For Market Incumbents: Deepen backward integration into para-phenylenediamine synthesis to insulate spinneret-to-fiber margins from benzene derivative volatility. Expand filament-winding qualification programs for hydrogen pressure vessel applications at facilities in Germany and Japan to capture energy transition capex. Lock in multi-year defense procurement contracts with NATO member states before Dyneema substitution accelerates in law enforcement soft armor segments.
For New Entrants and Emerging Players: Launch via direct specification relationships with electric vehicle battery pack manufacturers testing aramid nonwovens for cell-to-cell thermal barriers, bypassing established aerospace qualification backlogs. Target India's industrial safety expansion under BIS certification requirements for firefighter apparel and electrical worker protection. Pursue cost-optimized meta-aramid output for industrial filtration markets where thermal endurance outweighs modulus requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Asian fiber producers with integrated petrochemical feedstocks but lacking multi-jurisdiction certification infrastructure. Long-term viability favors assets with captive monomer supply and established SCIP database documentation for REACH compliance. Watch for inflection in hydrogen infrastructure deployment timelines as filament-wound pressure vessel demand links fiber consumption to energy transition capital commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive para-phenylenediamine supply insulates DuPont and Teijin from benzene price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous EU PPE Regulation, OSHA NIOSH, and China's LA approval extends market access. |
| Hydrogen Pressure Vessel Qualification | ISO 19881 certification for filament-wound aramid overwrap links fiber demand to energy transition. |
| Closed-Loop Fiber Recovery Systems | Mechanical shredding and solvent reclamation from decommissioned vests reduces virgin fiber dependence. |
| Performance-Based Lifecycle Contracts | Armor assemblers bundle inspection, refurbishment, and recovery into per-officer annual fees. |
Methodological Framework
Multiple input streams — primary interviews with polymerization plant managers, aerospace tier supplier procurement leads, and defense logistics agency contract officers; secondary validation through customs/trade data, SEC 10-K filings, and ECHA SCIP database disclosures — were reconciled through bottom-up and top-down triangulation. Conversations with technical R&D directors at filament-winding operations and distribution channel partners in industrial filtration markets provided demand-side calibration. Regulatory documentation from OSHA, ECHA, and China's MIIT supplied compliance-cost modeling inputs.
Historical volume trajectories were cross-referenced against panel input from qualified industry participants to derive expansion rates across the projection horizon. Segmentation dimensions modeled include para-aramid versus meta-aramid grade tier, aerospace versus automotive versus defense end-use industry, and filament versus staple versus chopped fiber form. CAGRs were derived from demand elasticity analysis against defense procurement cycles, industrial safety enforcement timelines, and electric vehicle battery thermal barrier adoption curves. Feedstock price indices for benzene derivatives and chlorine-based intermediates informed margin compression scenarios.
Several conditions sit outside the modeled scope, including force majeure events at concentrated polymerization facilities, abrupt substitution acceleration from ultra-high molecular weight polyethylene in soft armor, and divergence in regional flame-resistance test methodologies that fragment specification requirements. Forecasts reflect assumptions about sustained NATO ballistic modernization mandates and continued REACH enforcement stringency. A model refresh is warranted upon material change in hydrogen infrastructure deployment schedules or defense procurement indexation clause structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Textile Fibers Market
Synthetic Fibers
Polyethylene Terephthalate (PET) Fiber Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Long Fiber Thermoplastics Market