
 France Aluminium Pigments Market | 2026-2036
France Aluminium Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
France Aluminium Pigments Market Foresight
Specialized metallurgical engineering talent is unwinding capacity constraints across French aluminium pigment production. ALTANA leverages its integrated European R&D network to sustain formulation leadership in high-performance coatings. Toyal Europe anchors regional supply through its proximity to downstream automotive clients in eastern France. RADIOR France SAS differentiates via localized technical service and rapid batch customization for domestic paint manufacturers.
France aluminium pigments comprise thin lamellar aluminium particles manufactured through ball milling, stamping, or vacuum metallization, typically ranging from 5 to 100 micrometers in diameter, valued for their metallic luster, light reflectivity, and corrosion resistance in protective and decorative applications. Flake pigments dominate volume owing to their established use in automotive and industrial coatings, while paste pigments command premium positioning where dispersion consistency and solvent compatibility determine formulation outcomes. Coatings applications absorb the largest share of domestic output, though cosmetics-grade specifications are gaining traction as French beauty products makers pursue differentiated metallic effects.
ANSM monitors cosmetic-grade aluminium pigment safety under France's reinforced national framework, while REACH registration requirements administered by ECHA govern chemical substance authorization and restrict hazardous additive use. The country's central bank and industrial policy bodies channel innovation funding toward green chemistry transitions, pressuring manufacturers to eliminate solvent-heavy paste formulations. Stakeholders must weigh compliance investment against specialty segment premiums as regulatory thresholds tighten across both industrial and consumer-facing applications.
Market Dynamics
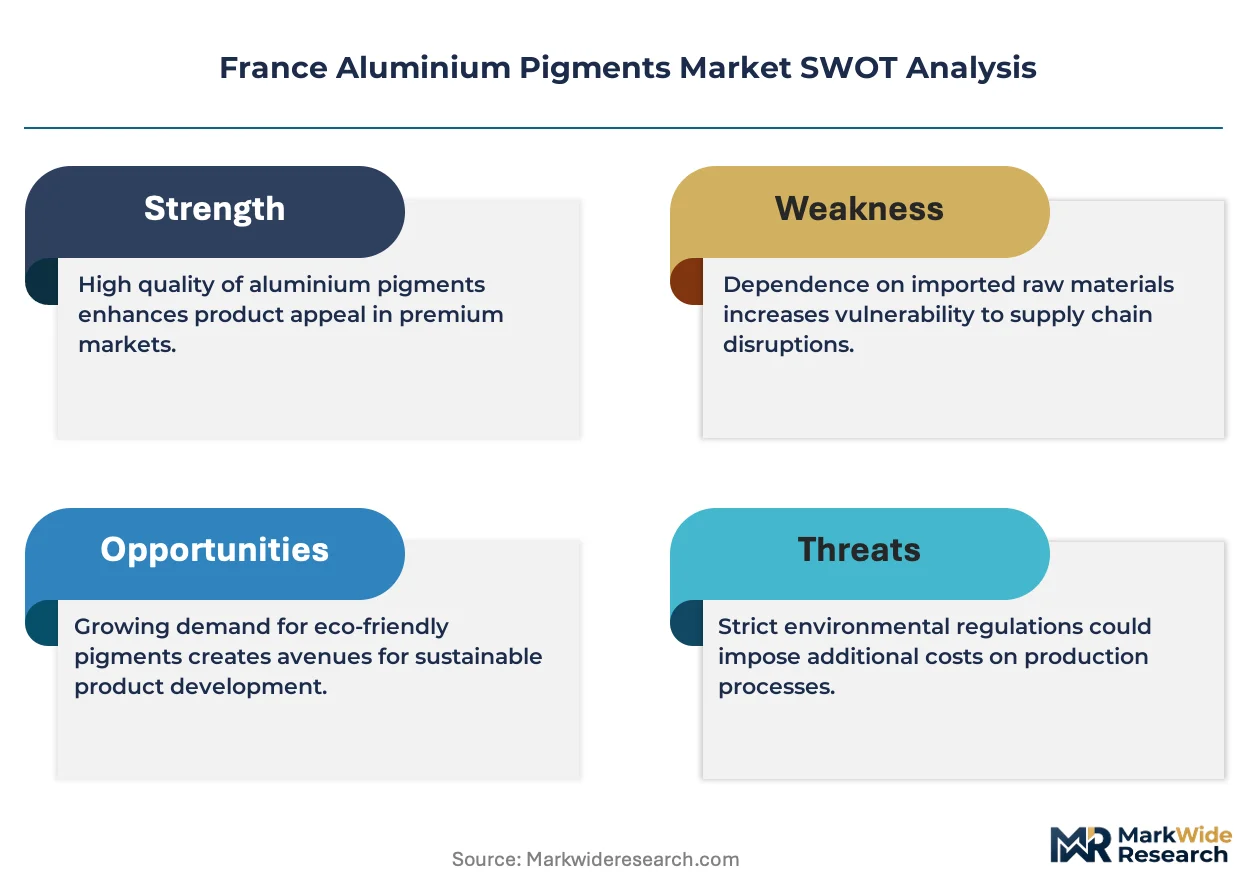
REACH registration deadlines are compressing formulation timelines for French aluminium pigment manufacturers, forcing simultaneous purity upgrades and solvent-system redesigns across the supply base.
Growth Catalysts
- Automotive refinishing demand:Premium metallic finishes in vehicle repair networks across Île-de-France and Rhône-Alpes are expanding flake pigment volumes as collision centers standardize on waterborne basecoats.
- ANSM cosmetic-grade pathways:France's national safety agency is clarifying aluminium pigment specifications for eye-area cosmetics, enabling domestic beauty manufacturers to launch compliant metallic product lines ahead of EU harmonization.
- Vacuum metallization advances:Thin-film deposition techniques are reducing particle thickness variability, improving optical consistency in high-end decorative coatings for architectural applications.
Market Restraints
- Aluminium ingot price volatility:Raw material cost swings tied to LME pricing and energy-intensive smelting economics compress margin predictability for domestic milling operations.
- Solvent-dependent paste formulations:REACH restrictions on volatile organic compounds are rendering legacy solvent-based dispersion technologies structurally obsolete before water-compatible alternatives achieve parity.
- Ball milling capacity concentration:Production equipment for lamellar particle generation remains concentrated among a limited set of European mechanical engineering suppliers, constraining domestic expansion timelines.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur cosmetics corridor:Grasse-based fragrance and color cosmetics manufacturers represent an underpenetrated demand pocket for cosmetic-grade aluminium pigments with differentiated particle geometries.
- EU Green Deal chemistry funding:French industrial policy bodies are channeling innovation grants toward bio-based dispersion media, creating first-mover advantages for paste manufacturers eliminating petroleum-derived solvents.
- Digital color-matching integration:Spectrophotometry-linked formulation software is enabling made-to-order pigment blending services for small-batch architectural coatings producers.
Industry Challenges
- Metallurgical engineering recruitment:Specialized talent for particle size distribution control and surface oxidation management is scarce in French technical universities, lengthening R&D cycle times.
- REACH dossier maintenance costs:Ongoing substance evaluation fees and toxicological testing requirements are diverting capital from process equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Aluminium Pigments Market |
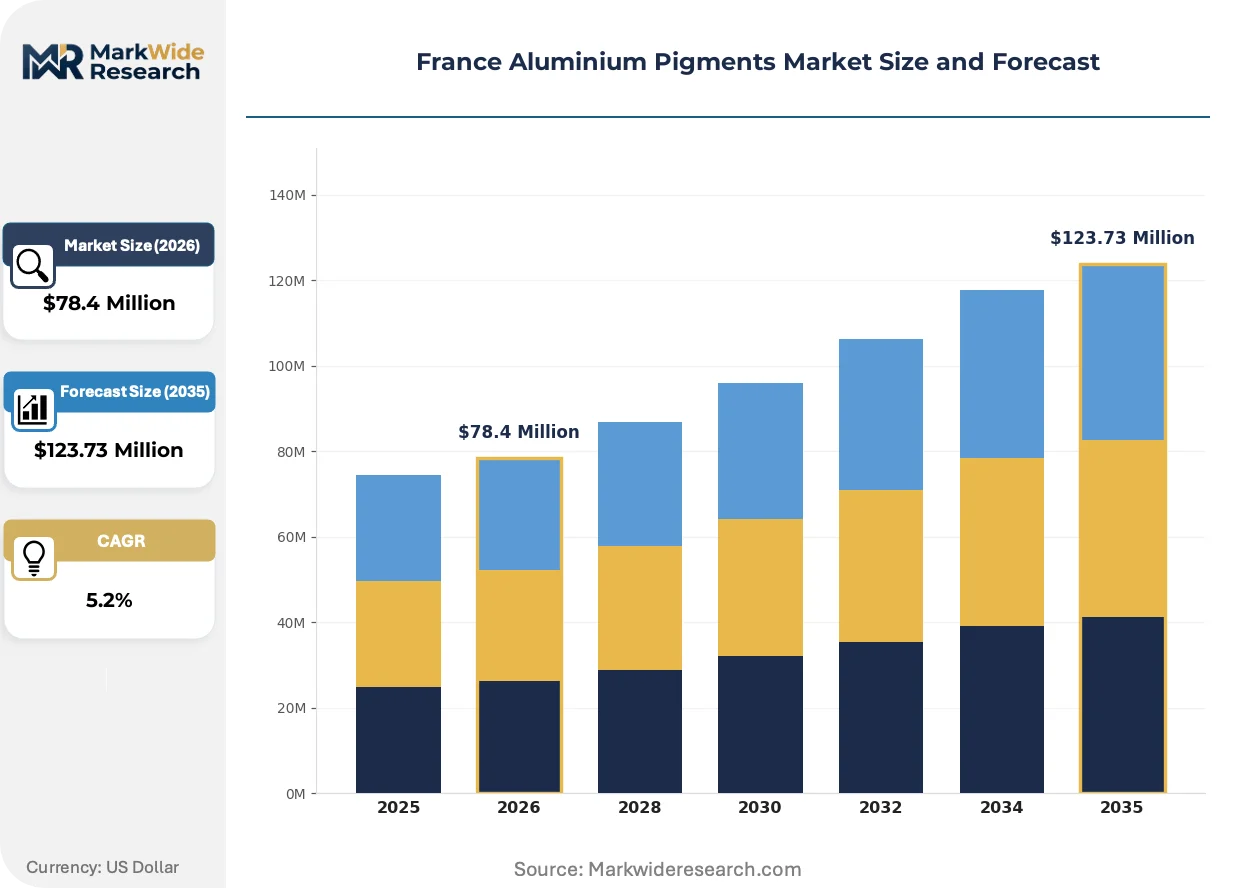
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake Pigments, Powder Pigments, Paste Pigments, Micaceous Pigments Application: Coatings, Plastics, Cosmetics, Inks, Automotive Finishes End User: Paint Manufacturers, Plastic Producers, Beauty Products Makers, Printing Ink Suppliers Packaging Type: Drums, Bags, Bottles, Bulk Containers |
| Companies Covered | Carl Schlenk AG, METAFLAKE Ltd, ALTANA, Silberline Manufacturing Co., Inc., RADIOR France SAS, AVL Metal Powders n.v., Carlfors Bruk, Toyal Europe, Bodo Moller Chemie GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Aluminium Pigments Market Shifts & Advancements
Waterborne dispersion technologies are disrupting solvent-locked legacy systems across French coatings manufacturing, while regulatory pressure on chemical hazard profiles accelerates substitution timelines.
Vacuum metallized aluminium pigments with controlled oxide layers is supplanting conventional stamped flakes in automotive OEM clearcoat applications. Tier-one suppliers in eastern France are adopting these materials for their superior flop index consistency and reduced solvent demand. The technology is compressing the performance gap between premium and mid-tier coating lines, forcing reformulation investments across the supply chain.
France's reinforced national framework under ANSM is tightening purity thresholds for cosmetic-grade aluminium pigments ahead of broader EU alignment. Domestic manufacturers must now submit expanded toxicological dossiers for eye-area applications, elevating compliance costs for smaller batch producers. The cosmetics segment is responding by consolidating supplier relationships toward integrated European pigment houses with established regulatory affairs capabilities.
Architectural coatings procurement is migrating toward specification-driven consolidated purchasing through national distributor networks. Regional paint manufacturers in northern France are abandoning spot-market aluminium flake sourcing in favor of annual framework agreements with technical service guarantees. This concentration is most visible in the Grand Est region, where infrastructure refurbishment programs are standardizing metallic finish specifications across public building portfolios.
France Aluminium Pigments Market Segmentation
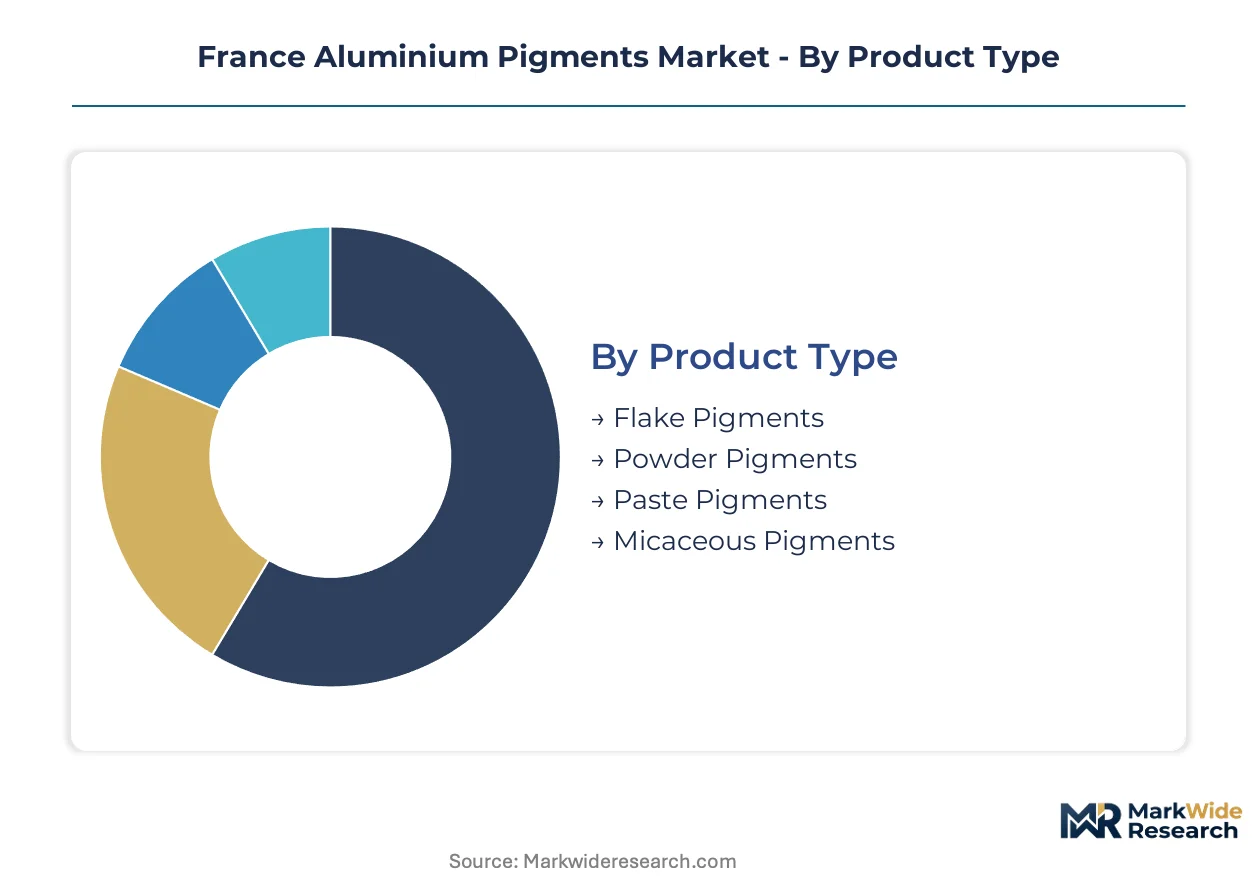
Segmentation in the France Aluminium Pigments Market reveals how regulatory pressure and end-use specifications fragment supply requirements. Formulation complexity varies sharply across cosmetic, automotive, and industrial channels, forcing manufacturers to maintain parallel production lines with distinct purity protocols.
Product Type:
REACH registration tiers and solvent-content thresholds differentiate product categories more than particle geometry alone.
- Flake Pigments:Lamellar aluminium particles produced through ball milling or stamping, typically 5-100 micrometers in diameter with controlled aspect ratios. Demand concentrates in automotive refinishing networks across Île-de-France and Rhône-Alpes, where collision centers standardize on metallic waterborne basecoats requiring consistent flop index performance.
- Paste Pigments:Aluminium flakes dispersed in petroleum-derived or bio-based carriers, commanding premium positioning where dispersion consistency determines formulation outcomes. ANSM cosmetic-grade specifications and ECHA solvent restrictions are compressing legacy petroleum-based formulations while opening first-mover advantages for bio-compatible alternatives.
- Powder Pigments:Dry aluminium particles with surface oxidation layers for corrosion resistance in powder coating applications.
- Micaceous Pigments:Aluminium-coated mica substrates combining metallic luster with substrate-driven color travel effects in decorative coatings.
Established volume favors flake pigments; emerging adoption favors paste pigments with bio-based reformulation.
Application:
End-use concentration in eastern France automotive clusters and Provence cosmetics corridors shapes regional supply patterns.
- Coatings:Protective and decorative formulations absorbing the largest share of domestic output, spanning architectural, industrial, and automotive refinish segments. Procurement is migrating toward specification-driven consolidated purchasing through national distributor networks, particularly visible in Grand Est infrastructure refurbishment programs standardizing metallic finishes across public building portfolios.
- Cosmetics:Eye-area and decorative applications where ANSM's reinforced national framework tightens purity thresholds ahead of broader EU alignment. Grasse-based fragrance and color cosmetics manufacturers in the Provence-Alpes-Côte d'Azur corridor represent expanding demand for differentiated particle geometries with expanded toxicological dossiers.
- Automotive Finishes:OEM and refinish clearcoats where vacuum metallized pigments with controlled oxide layers are supplanting conventional stamped flakes for superior optical consistency.
- Plastics:Masterbatch integration for consumer goods and packaging applications requiring thermal stability during polymer processing.
- Inks:Gravure and flexographic printing applications where metallic effects differentiate premium packaging.
Coatings anchor current volume; cosmetics applications are climbing the fastest under regulatory clarification.
End User:
Customer scale and technical service requirements stratify procurement relationships across integrated pigment houses versus spot-market sourcing.
- Paint Manufacturers:Regional producers in northern France abandoning spot-market aluminium flake sourcing in favor of annual framework agreements with technical service guarantees. ALTANA and Toyal Europe capture consolidated demand through integrated European R&D networks and proximity to downstream automotive clients.
- Beauty Products Makers:Domestic cosmetics houses consolidating supplier relationships toward integrated European pigment houses with established regulatory affairs capabilities as ANSM dossier requirements escalate.
- Plastic Producers:Masterbatch compounders serving consumer goods and packaging converters with thermal stability specifications.
- Printing Ink Suppliers:Gravure and flexographic formulators sourcing for premium packaging metallic effects.
Paint manufacturers command established procurement volume; beauty products makers are gaining share fastest through regulatory-driven supplier consolidation.
Packaging Type:
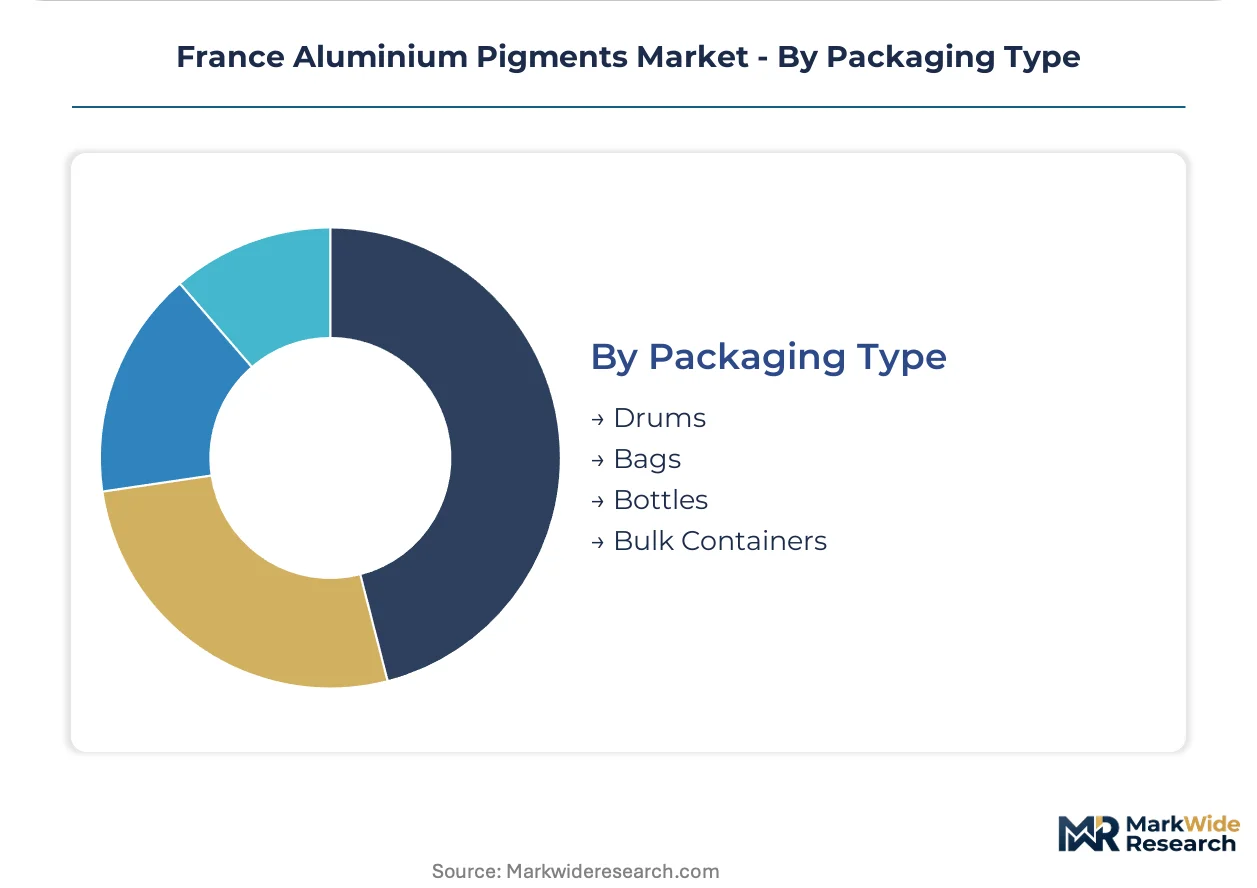
Volume scale and handling automation determine packaging selection across drum-based artisan supply versus bulk-container industrial flows.
- Drums:Standard 25-200 liter steel containers for solvent-based paste pigments and flake shipments to mid-scale coatings producers.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for high-volume automotive and architectural coatings manufacturers in the Île-de-France industrial corridor.
- Bags:Multi-layer laminated sacks for dry powder pigments requiring moisture barrier protection.
- Bottles:Small-format packaging for cosmetic-grade and sample quantities serving beauty products makers and specialty ink formulators.
Bulk containers dominate automotive supply chains; bottles serve the steepest expansion trajectory in cosmetic-grade sampling and small-batch customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration requirements govern chemical substance authorization across France, compressing formulation timelines and reshaping supplier qualification standards throughout the national market.
Île-de-France
Automotive refinishing networks and collision centers across the Paris metropolitan area are expanding flake pigment volumes as waterborne basecoat standardization accelerates. ANSM monitors cosmetic-grade safety under France's reinforced national framework, tightening purity thresholds ahead of broader EU alignment. The industrial corridor concentrates bulk-container procurement for high-volume coatings manufacturers serving infrastructure refurbishment programs.
Auvergne-Rhône-Alpes
Vacuum metallization advances are reducing particle thickness variability for OEM clearcoat applications around Lyon. ECHA solvent restrictions under REACH are rendering legacy petroleum-based dispersion technologies structurally obsolete. The coatings cluster anchors regional supply through proximity to downstream automotive clients in eastern France.
Provence-Alpes-Côte d'Azur
Grasse-based fragrance and color cosmetics manufacturers represent expanding demand for cosmetic-grade aluminium pigments with differentiated particle geometries. ANSM's clarified specifications for eye-area applications enable domestic beauty manufacturers to launch compliant metallic product lines. The cosmetics corridor is consolidating supplier relationships toward integrated European pigment houses with established regulatory affairs capabilities.
Grand Est
Regional paint manufacturers are abandoning spot-market aluminium flake sourcing in favor of annual framework agreements with technical service guarantees. EU Green Deal chemistry funding channels innovation grants toward bio-based dispersion media for paste manufacturers. Infrastructure refurbishment programs are standardizing metallic finish specifications across public building portfolios throughout the region.
France Aluminium Pigments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier structure where scale advantages in regulatory compliance separate consolidated players from fragmented domestic formulators. The upper tier commands consolidated purchasing relationships through integrated European R&D networks and proximity to downstream clients. Three archetypes define the competitive set: integrated multinational pigment houses, regional mechanical milling specialists, and localized technical service providers. Dominant competitive moves include strategic partnerships for bio-based formulation development and geographic anchoring through proximity to automotive and cosmetics clusters.
Within the integrated multinational tier, ALTANA leverages its European R&D network to sustain formulation leadership, while Toyal Europe anchors regional supply through eastern French automotive corridor positioning. RADIOR France SAS occupies a position exemplifying the localized technical service archetype, with rapid batch customization capabilities for domestic paint manufacturers. These three entities represent the strategic positioning spectrum from global scale to regional responsiveness.
| Leading Market Players |
|---|
| Carl Schlenk AG |
| METAFLAKE Ltd |
| ALTANA |
| Silberline Manufacturing Co., Inc. |
| RADIOR France SAS |
| AVL Metal Powders n.v. |
| Carlfors Bruk |
| Toyal Europe |
| Bodo Moller Chemie GmbH |
| Others |
Supply & Pricing Matrix
Bio-based carrier substitution for petroleum-derived solvents in paste pigment formulations is redrawing procurement geography toward EU Green Deal funding recipients while compressing margin structures for legacy formulators. This input transition simultaneously elevates technical service premiums for compliant suppliers and erodes spot-market competitiveness of solvent-locked inventory.
Pricing Analysis
Price spreads between Île-de-France bulk-container deliveries and Provence-Alpes-Côte d'Azur small-batch cosmetic shipments reflect divergent service intensity. Three-tier pricing structure across REACH-registered premium grades, standard industrial flakes, and economy powder tiers tracks certification burden and particle geometry complexity. Pricing pressure stems from LME-linked aluminium ingot volatility feeding raw material cost unpredictability into milling operations. Spot-market buyers in northern France exhibit highest price sensitivity; ANSM-registered cosmetic houses absorb premium dispersion costs for regulatory certainty.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive coatings procurement through eastern France corridors, while cosmetic-grade pigment buyers maintain strategic stockpiles against ANSM dossier approval delays. Primary aluminium supply concentrates in Norway, Iceland, and domestic French smelters drawing from hydroelectric power. Ball milling equipment depends on German and Italian mechanical engineering suppliers. Single-source vulnerability runs through vacuum metallization technology providers. Distribution runs through national coatings distributor networks consolidating regional paint manufacturer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's aluminium pigment market operates as a substitution defense against waterborne dispersion technologies and bio-based carrier alternatives that threaten solvent-dependent incumbents. Incumbents must navigate reformulation investment cycles that favor integrated European pigment houses with established regulatory affairs infrastructure.
For Market Incumbents: Compound technical service capabilities around ANSM cosmetic-grade dossier preparation to capture beauty product maker consolidation toward integrated suppliers. Deepen backward integration into vacuum metallization equipment partnerships to reduce particle thickness variability for automotive OEM clearcoat specifications. Defend against bio-based paste entrants by locking multi-year framework agreements with Grand Est infrastructure refurbishment contractors. For New Entrants and Emerging Players: Differentiate on rapid batch customization for Grasse-based cosmetics manufacturers seeking differentiated particle geometries with expanded toxicological documentation. Target the Provence-Alpes-Côte d'Azur corridor's underpenetrated demand pocket for cosmetic-grade aluminium pigments ahead of broader EU regulatory harmonization. Deploy spectrophotometry-linked formulation software to enable made-to-order pigment blending services for small-batch architectural coatings producers. For Investors and Strategic Acquirers: The market sits at a regulatory-clarification phase that favors integrated European pigment houses with established REACH dossier maintenance capabilities. Long-term viability over the next decade hinges on green chemistry transition execution and bio-based dispersion media development. Acquisition targets should demonstrate proximity to downstream automotive or cosmetics clusters with technical service infrastructure. The signal to watch is EU Green Deal chemistry funding disbursement velocity as inflection indicator for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Metallization Equipment | Reduces particle thickness variability for Lyon-based automotive OEM clearcoat suppliers. |
| ANSM Cosmetic-Grade Certification Investment | Captures Grasse beauty product maker consolidation toward compliant metallic pigment sources. |
| Bio-Based Dispersion Media Development | Positions paste manufacturers for EU Green Deal innovation grants eliminating petroleum carriers. |
| Long-Term Framework Agreement with Grand Est Contractors | Locks specification-driven procurement for infrastructure refurbishment metallic finish standardization. |
| Spectrophotometry-Linked Formulation Software Deployment | Enables rapid batch customization for northern France small-batch architectural coatings producers. |
Research Methodology
A standing panel of coatings formulators, cosmetic product development chemists, automotive refinish procurement managers, and ANSM regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA REACH registration databases, French customs trade statistics, SEC filings of listed pigment houses, and Cefic chemical industry reports. Bottom-up volume estimates triangulated against top-down market sizing from national coatings production data.
Consistency checks validated model outputs against external benchmarks including automotive production registrations from eastern France clusters and cosmetic export volumes from Provence-Alpes-Côte d'Azur. The analytical framework segmented by product type, application, end user, and packaging format across the projection horizon. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory phase-in effects. Forecast inputs incorporated REACH registration deadline impacts and EU Green Deal funding allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained ANSM regulatory clarity or aluminium ingot price stability would require recalibration. Forecasts reflect documented assumptions regarding waterborne basecoat adoption rates and bio-based carrier technology maturation. Revision becomes warranted when EU harmonization timelines for cosmetic-grade specifications cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market