
 Asia-Pacific Airport Passenger Screening Systems Market | 2026-2036
Asia-Pacific Airport Passenger Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airport Passenger Screening Systems Market Outlook
Southeast Asia's airport infrastructure expansion is fragmenting procurement patterns across national carriers and private terminal operators. Nuctech Company Limited dominates domestic manufacturing scale across Chinese installations, while Smiths Detection leverages its European R&D base to compete for premium automated lanes in Singapore and Australia. Leidos, Inc. anchors North American-origin contracts through security consulting relationships with government agencies in Japan and South Korea.
Asia-Pacific airport passenger screening systems encompass electromagnetic and ionizing-radiation detection equipment engineered to identify metallic and non-metallic threats concealed on persons or within carry-on baggage, typically operating at frequencies between 24-30 GHz for millimeter-wave units or 140-180 keV for dual-view X-ray tunnels. These systems serve the primary commercial purpose of maintaining aviation security compliance while minimizing passenger processing friction at high-throughput checkpoints. Millimeter-wave body scanners capture expanding share as privacy-compliant alternatives to backscatter X-ray, while AI-based threat detection algorithms reshape software margin pools away from hardware-centric revenue. Fixed installation types retain dominance in primary screening lanes, though portable units gain traction for temporary event security and remote airstrip deployments.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces checkpoint performance standards that mandate detection rates for ceramic and liquid threats, directly shaping R&D priorities for domestic suppliers and importers alike. Australia's Department of Home Affairs aligns aviation security regulations with ICAO Annex 17 guidelines, creating harmonized certification pathways for multinational equipment vendors. China's MIIT publishes GB standards for radiation emission limits that constrain X-ray system designs for domestic deployment. Stakeholders must monitor evolving biometric integration mandates from civil aviation authorities, as facial recognition linkage to boarding passes threatens to obsolete screening architectures that lack modular software interfaces.
Market Dynamics
Millimeter-wave body scanners are compressing passenger processing times at Asia-Pacific aviation hubs while India's Bureau of Civil Aviation Security mandates stricter checkpoint protocols that accelerate hardware replacement cycles.
Growth Catalysts
- Regulatory Mandates:India's Bureau of Civil Aviation Security enforces stricter checkpoint protocols that accelerate replacement of legacy metal detectors with advanced screening equipment.
- Infrastructure Expansion:Southeast Asian airport operators are expanding procurement of automated screening lanes to handle rising passenger throughput at major aviation hubs.
- Technology Substitution:Millimeter-wave body scanners capture expanding market share as privacy-compliant alternatives to backscatter X-ray systems across Chinese tier-one airports.
Market Restraints
- Input Cost Volatility:Semiconductor component shortages and rare earth magnet price fluctuations constrain production scaling for electromagnetic detection subsystems.
- Supply Concentration Risk:Domestic manufacturing scale for Chinese installations concentrates with limited qualified suppliers certified under MIIT radiation emission standards.
- Technical Limitation:Current millimeter-wave units operating at 24-30 GHz frequencies struggle with consistent detection of low-density ceramic threats in layered clothing configurations.
Strategic Opportunities
- Underpenetrated Geography:Vietnam and Indonesia present white space for automated lane deployment as passenger volumes at secondary aviation hubs outgrow manual screening capacity.
- Technology Convergence:AI-based threat detection algorithms converging with biometric boarding pass linkage create modular software interface requirements that favor adaptable architectures.
- Distribution Innovation:Security-as-a-service leasing models are emerging as procurement alternatives to capital-intensive equipment purchases among budget-conscious regional carriers.
Industry Challenges
- Certification Timeline Compression:Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates detection rate standards for ceramic and liquid threats that extend product validation cycles.
- Legacy System Integration:Australia's Department of Home Affairs alignment with ICAO Annex 17 guidelines forces reconfiguration of existing checkpoint layouts to accommodate new detection tunnel geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airport Passenger Screening Systems Market |
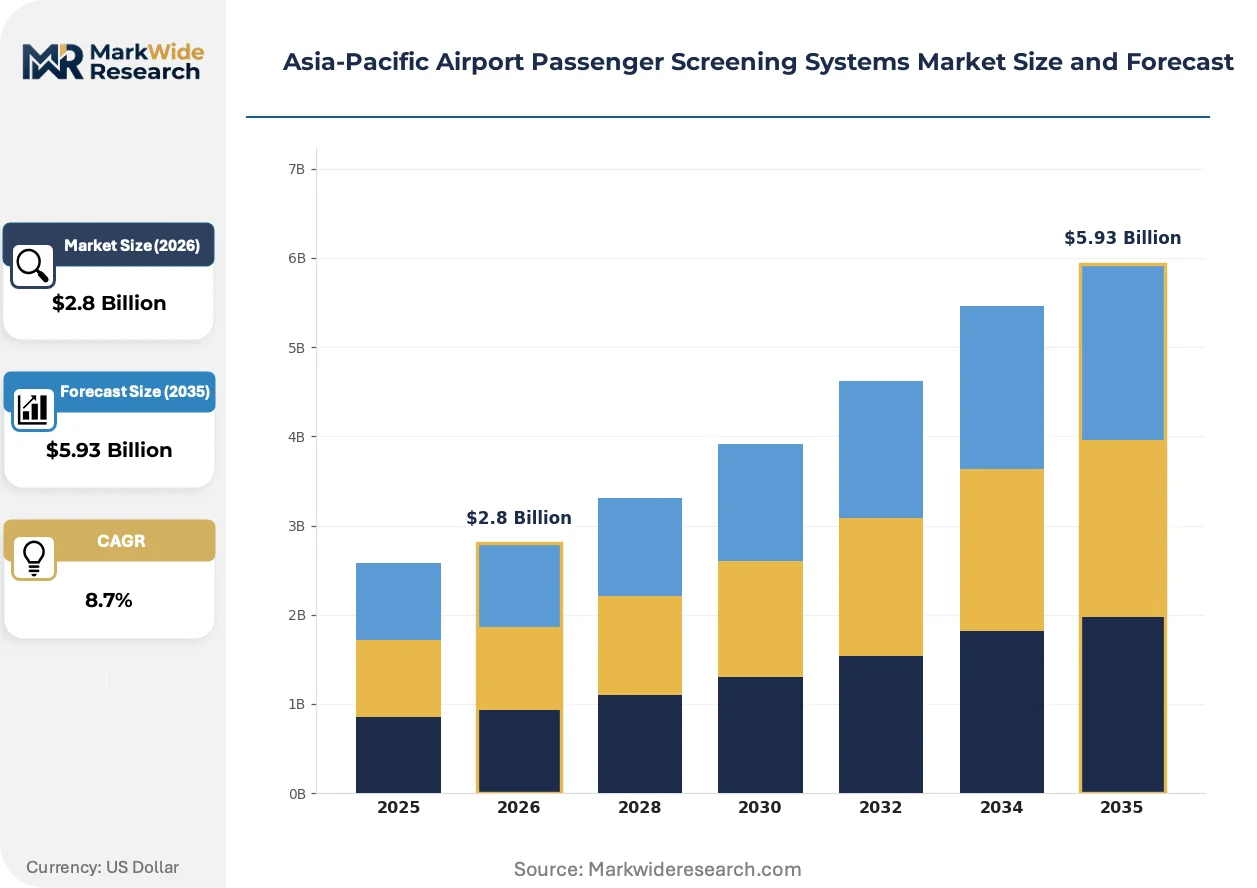
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Millimeter Wave, X-ray, Body Scanner, Explosive Trace Detector End User: Airlines, Airports, Government Agencies, Security Firms Installation Type: Fixed, Portable, Mobile, Self-Service Technology: AI-based, Biometrics, Traditional Screening, Automated Threat Detection |
| Companies Covered | Analogic Corporation, OSI Systems, Inc., Garrett Electronics Inc., Leidos, Inc., Smiths Detection, Nuctech Company Limited, Rapiscan Systems, L3Harris Technologies, Thales Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airport Passenger Screening Systems Market Strategic Shifts
AI-integrated baggage inspection systems are reconfiguring software margin pools away from hardware-centric revenue models across Asia-Pacific aviation security procurement.
Millimeter-wave body scanners operating at 24-30 GHz frequencies are capturing primary screening lane deployment at Beijing Capital and Shanghai Pudong. Chinese tier-one aviation hubs are adopting these units at accelerated pace to comply with MIIT radiation emission standards. The technology is digitizing threat detection workflows by converting analog signal processing into algorithmic pattern recognition that reduces false alarm rates.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces checkpoint performance standards mandating detection rates for ceramic and liquid threats. These requirements directly shape R&D priorities for domestic suppliers and importers targeting Japanese aviation security contracts. Millimeter-wave and dual-view X-ray tunnel manufacturers are responding by reconfiguring sensor arrays to meet the specified performance thresholds.
Airport operators across Southeast Asia are fragmenting procurement patterns across national carriers and private terminal operators. Traditional single-vendor relationships are yielding to competitive tendering that separates hardware, software, and maintenance contracts. This behavioral shift is most visible in Singapore and Thailand, where government-owned airport authorities now mandate open-architecture specifications to prevent vendor lock-in.
Asia-Pacific Airport Passenger Screening Systems Market Segmentation
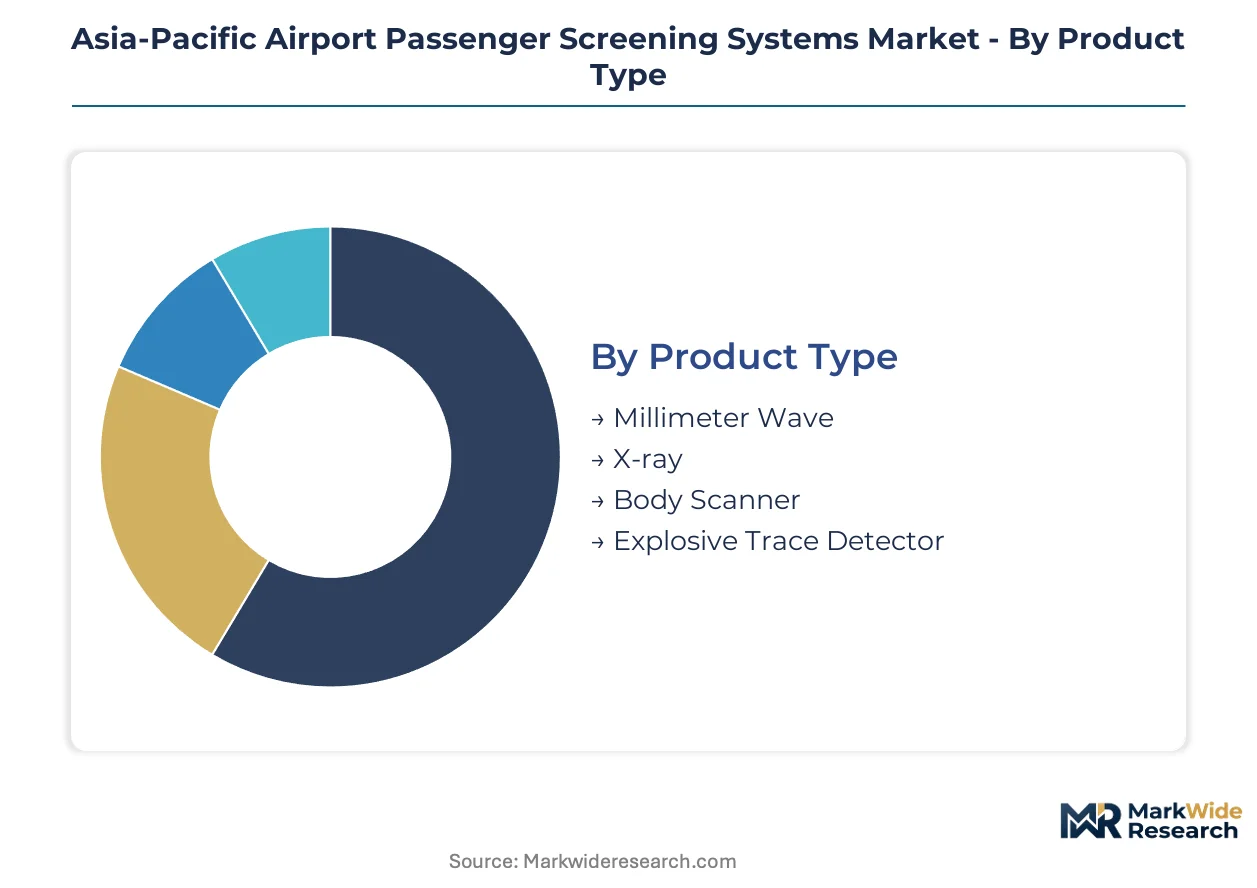
Segmentation across Asia-Pacific airport passenger screening systems reveals divergent replacement cycles that reshape procurement timing and vendor contract structures. Hardware categories with longer depreciation schedules compete against software modules that refresh on compressed timelines.
Product Type:
Millimeter-wave units turn over fastest as MIIT radiation standards force accelerated refresh cycles, while X-ray tunnels depreciate across decade-long amortization schedules.
- Millimeter Wave:These systems operate at 24-30 GHz frequencies to detect metallic and non-metallic threats without ionizing radiation. Beijing Capital and Shanghai Pudong drive procurement volume as Chinese tier-one hubs replace backscatter units with privacy-compliant alternatives. India's Bureau of Civil Aviation Security mandates accelerate replacement timelines for legacy metal detectors with these electromagnetic systems.
- X-ray:Dual-view tunnel systems at 140-180 keV penetration levels remain embedded in primary baggage screening lanes. Australia's Department of Home Affairs certification requirements under ICAO Annex 17 guidelines extend validation cycles for these capital-intensive installations. Semiconductor component shortages constrain production scaling for detector array subsystems.
- Body Scanner:Privacy-compliant millimeter-wave configurations displace backscatter units across Southeast Asian hub airports.
- Explosive Trace Detector:Swab-based and walk-through portal configurations serve secondary screening protocols at Japanese aviation facilities.
X-ray anchors the volume base while millimeter-wave gains share at the steepest rate.
End User:
Procurement authority concentrates with airport operators holding capital budgets, while security firms deliver operational flexibility on service contracts.
- Airlines:Legacy carriers at Singapore Changi and Hong Kong International maintain captive screening infrastructure for premium cabin passengers. Procurement concentrates on automated lanes that compress processing friction for business travelers.
- Airports:Government-owned authorities across Thailand and Indonesia control master concession agreements that dictate vendor selection for terminal-wide deployments. Fragmented tendering separates hardware, software, and maintenance contracts to prevent lock-in.
- Government Agencies:Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces performance standards that shape R&D priorities for domestic suppliers.
- Security Firms:Leasing models emerge among budget-conscious regional carriers seeking to avoid capital-intensive equipment purchases.
Airports anchor the volume base while security firms expand most quickly through as-a-service procurement alternatives.
Installation Type:
Fixed infrastructure dominates capital allocation, though portable units address temporary demand surges that fixed geometries cannot accommodate.
- Fixed:Primary screening lanes at Chinese tier-one aviation hubs deploy permanent millimeter-wave and X-ray tunnel configurations. MIIT radiation emission standards constrain system designs for domestic deployment.
- Portable:Remote airstrip deployments and temporary event security drive demand for battery-powered screening units across Indonesia's archipelago geography.
- Mobile:Trailer-mounted configurations serve construction-phase terminals and seasonal capacity expansion at Vietnamese secondary hubs.
- Self-Service:Automated credential verification gates integrate with biometric boarding pass linkage at Singapore and Australian facilities.
Fixed installations anchor the volume base while portable configurations climb the fastest on remote infrastructure demand.
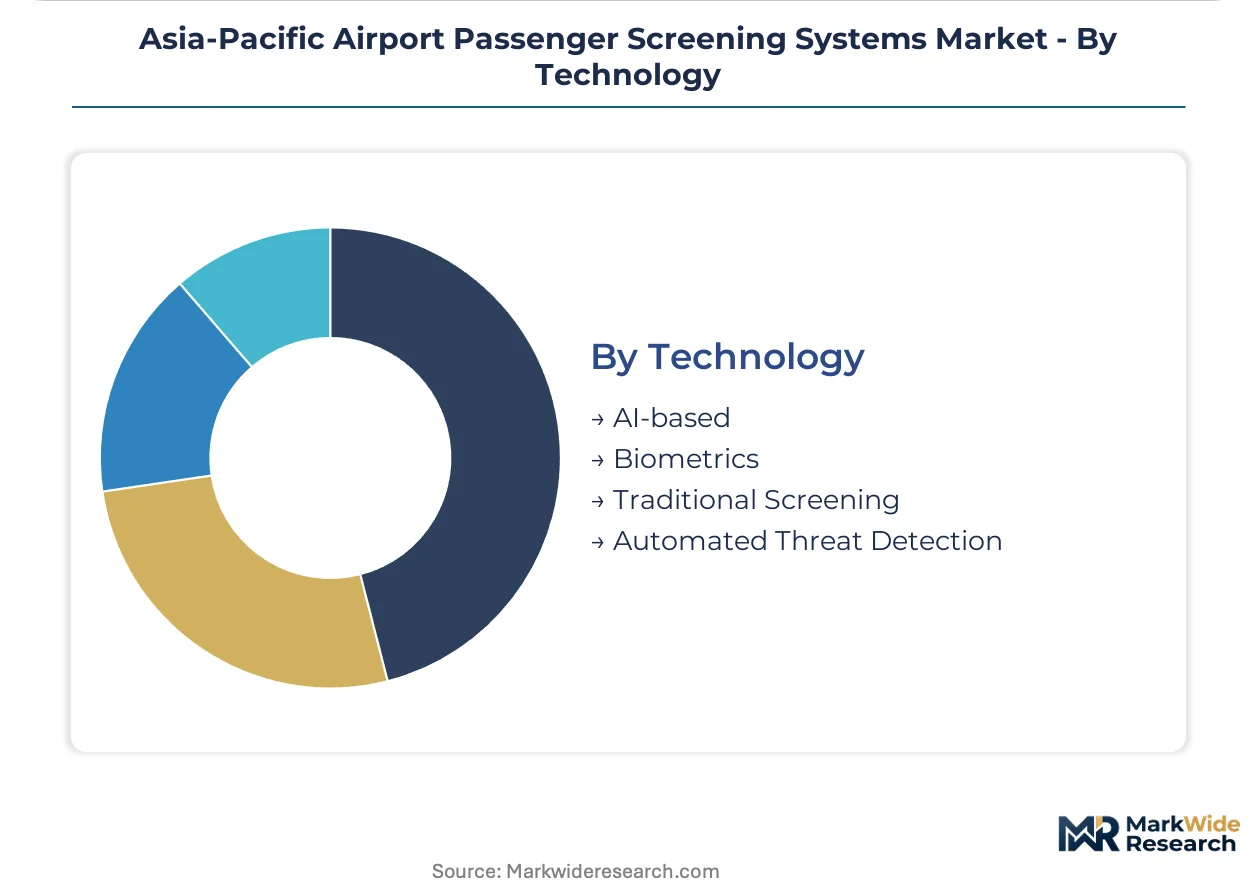
Technology:
Margin pools shift from hardware-centric revenue toward software modules that refresh on algorithmic improvement cycles rather than physical depreciation schedules.
- AI-based:Threat detection algorithms convert analog signal processing into pattern recognition that reduces false alarm rates. China's tier-one hubs digitize workflows through machine learning integration with millimeter-wave sensor arrays.
- Biometrics:Facial recognition linkage to boarding passes threatens to obsolete screening architectures lacking modular software interfaces. Japan's checkpoint performance standards mandate detection rate thresholds that biometric-integrated systems must satisfy.
- Traditional Screening:Legacy metal detector configurations persist at secondary aviation hubs with constrained capital budgets across Vietnam and the Philippines.
- Automated Threat Detection:Software-defined analysis layers deploy over existing hardware footprints to extend useful life without full system replacement.
Traditional screening anchors the volume base while AI-based platforms gain share at the steepest rate on software margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT radiation emission standards anchor procurement decisions across Chinese tier-one aviation hubs, while Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces detection rate mandates that reshape supplier R&D priorities throughout the region.
China
Beijing Capital and Shanghai Pudong drive bulk orders for millimeter-wave body scanners as domestic hubs replace legacy backscatter units. MIIT GB standards constrain X-ray system designs for radiation emission limits. The Yangtze River Delta cluster concentrates manufacturing scale for electromagnetic detection subsystems serving both domestic deployment and regional export.
Japan
Osaka Kansai and Tokyo Narita facilities upgrade checkpoint infrastructure to satisfy ceramic and liquid threat detection thresholds. The Ministry of Land, Infrastructure, Transport and Tourism extends product validation cycles through performance-based certification requirements. Domestic suppliers and importers reconfigure sensor arrays to meet specified detection rate standards.
India
Delhi Indira Gandhi International and Mumbai Chhatrapati Shivaji Maharaj airports accelerate hardware replacement timelines. The Bureau of Civil Aviation Security mandates stricter checkpoint protocols that displace legacy metal detector configurations. Maharashtra and Delhi-NCR aviation clusters concentrate procurement authority with government-owned airport operators holding capital budgets.
Australia
Sydney Kingsford Smith and Melbourne Tullamarine align checkpoint layouts with ICAO Annex 17 guidelines enforced by the Department of Home Affairs. Certification harmonization creates pathways for multinational equipment vendors. The southeastern corridor dominates procurement volume as automated screening lanes compress passenger processing friction for business travelers.
Singapore
Changi Airport Authority fragments tendering across hardware, software, and maintenance contracts to prevent vendor lock-in. Government-owned airport authorities mandate open-architecture specifications. The city-state's hub status concentrates premium-tier demand for automated lanes serving premium cabin passenger segments.
Asia-Pacific Airport Passenger Screening Systems Market Competitive Environment
Domestic-scale manufacturers and European-heritage specialists split the market across procurement tiers. Vendor concentration varies by national certification regime, with Chinese installations favoring locally certified suppliers and premium-tier hubs in Singapore and Australia accepting broader import competition. Two strategic archetypes dominate: scale-driven domestic fabricators optimized for volume deployment, and technology-integrated specialists competing on software-defined threat detection capabilities. Competitive moves center on geographic certification expansion and modular architecture development to accommodate biometric integration mandates.
Within the domestic-scale tier, Nuctech Company Limited and Smiths Detection occupy positions reflecting divergent geographic anchoring—Beijing-based manufacturing scale versus European R&D heritage. Leidos, Inc. represents the consulting-anchored archetype, leveraging security advisory relationships with government agencies in Japan and South Korea. These three entities exemplify how competitive positioning fragments across procurement authority structures: state-linked airport operators, privatized terminal management, and civil aviation regulatory frameworks.
| Leading Market Players |
|---|
| Analogic Corporation |
| OSI Systems, Inc. |
| Garrett Electronics Inc. |
| Leidos, Inc. |
| Smiths Detection |
| Nuctech Company Limited |
| Rapiscan Systems |
| L3Harris Technologies |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
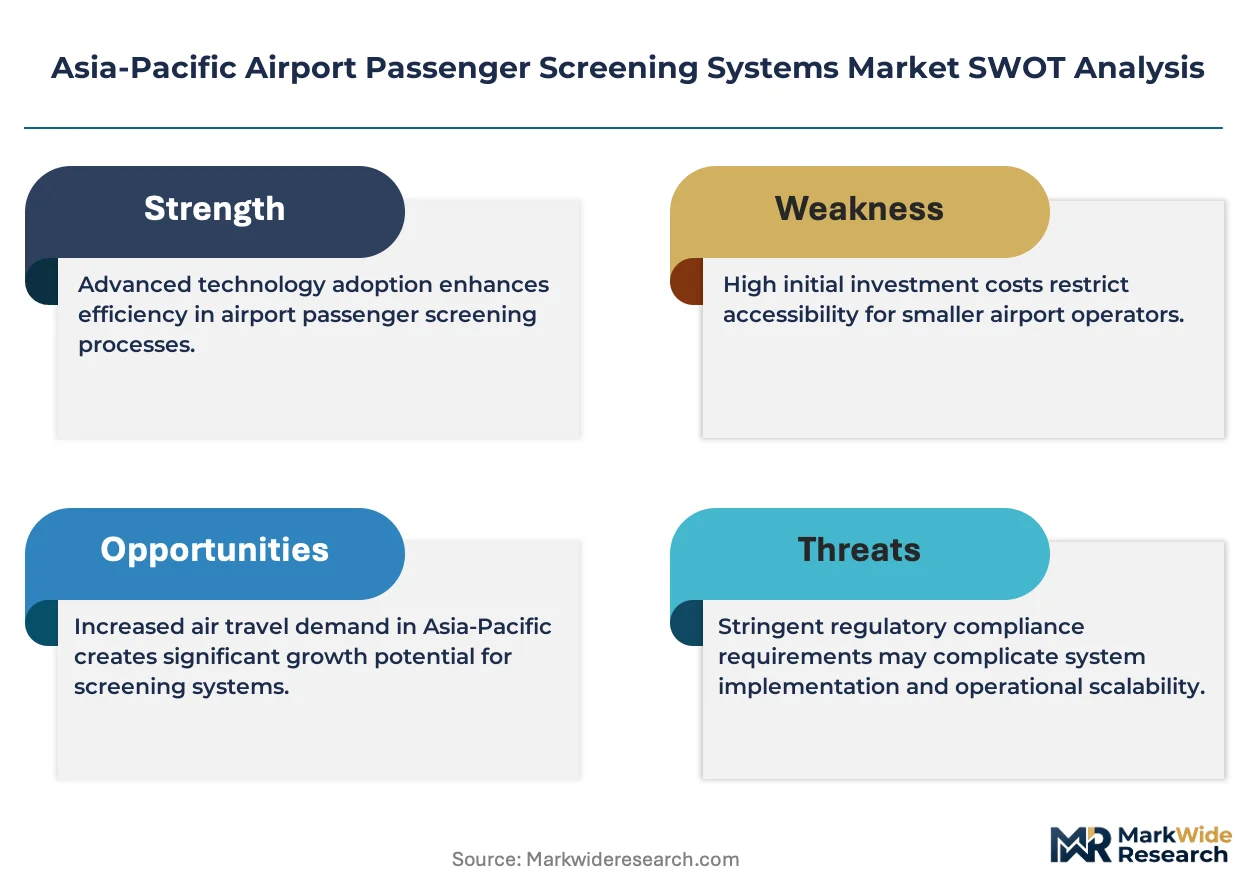
The Yangtze River Delta freight corridor's containerized logistics costs compress procurement economics for electromagnetic detection subsystems, concentrating price-setting power among domestic-scale fabricators while forcing tiered pricing stratification across premium MIIT-certified and standard-grade installations.
Pricing Analysis
Price spreads between Chinese domestic tenders and Singapore-Australia premium deployments exceed factor ranges driven by certification grade differentiation and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with AI-integrated software modules commanding recurring subscription premiums. Pricing pressure stems from semiconductor component shortages constraining detector array production. Budget-conscious regional carriers in Vietnam and Indonesia exhibit highest price sensitivity, while government-owned airport authorities in Japan and South Korea prioritize detection performance over unit economics.
Supply Chain Analysis
Rare earth magnet feedstock and gallium arsenide semiconductor wafers anchor upstream dependencies for millimeter-wave transmitter modules. Manufacturing concentrates in China, South Korea, and Japan, with Yangtze River Delta and Seoul metropolitan clusters dominating electromagnetic subsystem fabrication. Single-source vulnerability persists for MIIT-certified radiation shielding components. Distribution runs through government procurement frameworks and security integrator channels rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific airport passenger screening systems sit in early-cycle expansion as biometric boarding pass mandates force modular architecture refreshes across legacy checkpoint infrastructures.
For Market Incumbents: Build certification moats around MIIT radiation emission standards and Japan's ceramic-liquid detection thresholds to lock out unqualified competitors. Deepen backward integration into gallium arsenide wafer supply through captive foundry arrangements in South Korea. Anchor maintenance revenue streams through open-architecture software interfaces that prevent disintermediation by AI-native entrants. For New Entrants and Emerging Players: Build out security-as-a-service leasing models targeting Indonesia's remote airstrip network and Vietnam's secondary hub expansion. White space concentrates in portable battery-powered units for temporary event deployment. Go-to-market leverage rests on bypassing capital budget cycles through operational expenditure structures that appeal to budget-conscious regional carriers. For Investors and Strategic Acquirers: AI-native software specialists with modular threat detection architectures represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on algorithmic improvement velocity outpacing hardware depreciation schedules. Watch for biometric integration mandate acceleration from Japan's Ministry of Land, Infrastructure, Transport and Tourism as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Open-Architecture Certification Investment | MIIT and Japan MLIT compliance creates vendor lock-in protection for airport operators. |
| Security-as-a-Service Leasing Launch | Operational expenditure models bypass capital budget constraints at Indonesian and Vietnamese carriers. |
| AI Threat Detection Module Integration | Machine learning layers extend hardware useful life while capturing software margin pools. |
| Backward Integration into Semiconductor Supply | Captive gallium arsenide sourcing mitigates detector array production bottlenecks. |
| Biometric Boarding Pass Linkage Development | Modular interfaces accommodate civil aviation authority mandates before obsolescence risk materializes. |
Study Parameters
A standing panel of airport security directors, civil aviation regulatory affairs officers, checkpoint systems procurement managers, and security integrator technical leads provided ongoing calibration against secondary validation through customs import records, MIIT certification databases, ICAO Annex 17 implementation reports, and airport authority tender documents. Bottom-up installation forecasts triangulated against top-down aviation security spending projections.
Scenario-bracketing framed demand trajectories across conservative, baseline, and accelerated biometric integration pathways over the projection horizon. Segmentation dimensions spanned product type, end-user authority structure, installation permanence, and technology integration depth. CAGRs derived from equipment replacement cycle analysis and passenger throughput elasticity modeling. Forecast inputs incorporated semiconductor supply constraints and regulatory mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by Chinese domestic-scale fabricators or accelerated AI-native software displacement would shift outcomes beyond modeled ranges. Cross-checking against ICAO member state security spending disclosures and national aviation authority procurement bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
C5ISR Market
Aerospace & Defense
Satellite Communication System Market
Aerospace & Defense
Aviation Refueling Market
Aerospace & Defense
Aircraft Door Market
Aerospace & Defense
AI in Modern Warfare Market
Aerospace & Defense
Commercial Aircraft in-Flight Entertainment System Market
Aerospace & Defense
Italy Space Electronics Market
Aerospace & Defense
Aviation Carpet Market
Aerospace & Defense
Southeast Asia Defense Market
Aerospace & Defense
North America Drones Market
Aerospace & Defense
Global Smartphone Controlled Drone Market
Aerospace & Defense
AI in Aviation Market
Aerospace & Defense
Smart War Weapon Market
Aerospace & Defense
Military Aircraft Market
Aerospace & Defense
Asia-Pacific Aircraft Health Monitoring System Market
Aerospace & Defense
Commercial Aircraft Manufacturing Market