
 Aircraft Cargo Handling Equipment Market | 2026-2036
Aircraft Cargo Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cargo Handling Equipment Market Outlook
Airport procurement channels for cargo handling equipment is tilting toward long-term service contracts bundled with hardware. Oshkosh Aerotech LLC leverages its vertical integration in firefighting and military vehicle platforms to cross-sell specialized cargo solutions. Konecranes Oyj anchors its position through crane technology transfer into airside logistics. TLD Group differentiates via dedicated ground support manufacturing scale across European and Asian production sites.
Aircraft cargo handling equipment encompasses motorized and non-motorized ground support apparatus designed to transfer, lift, and position unit load devices between aircraft cargo holds and terminal facilities, typically operating at load ratings exceeding 7,000 kg and integrating hydraulic lift mechanisms for main-deck and lower-hold compatibility. Container-based systems command the largest installed base among equipment types due to standardized ULD interchange across wide-body fleets, while automated guided vehicle segments attract capital as labor costs escalate at major cargo hubs. Ground handling applications generate the most recurring equipment demand because turnaround-time contracts penalize mechanical failure, whereas freight forwarding end users increasingly specify telematics-enabled pallet dollies for real-time asset tracking.
The FAA mandates periodic inspection and recertification of powered cargo loaders under 14 CFR Part 139 standards, while EASA's CS-25 airworthiness criteria indirectly shape equipment interface dimensions through aircraft manufacturer compliance. China's CAAC implements GB standards for ground support equipment safety that foreign suppliers must meet for airport tender eligibility. Stakeholders must weigh electrification roadmaps against residual value risk in fossil-fuel fleets as regulatory deadlines tighten without universal alignment across jurisdictions.
Market Dynamics
Fleet electrification timelines and the FAA's updated ground support equipment safety mandates are compressing replacement cycles while reshaping procurement specifications across major cargo hubs.
Growth Catalysts
- Airport infrastructure investment in China:CAAC's GB standards for ground support equipment safety are mandating equipment upgrades at tier-one cargo hubs, creating tender opportunities for certified suppliers.
- E-commerce logistics fleet modernization:Express parcel carriers are retrofitting legacy cargo loaders with telematics-enabled pallet dollies to meet real-time asset tracking requirements.
- FAA 14 CFR Part 139 inspection mandates:Periodic recertification requirements for powered cargo loaders are accelerating replacement demand at US hub airports.
Market Restraints
- Residual value risk in fossil-fuel fleets:Uncertainty around electrification deadlines across jurisdictions is freezing secondary market liquidity for diesel-powered cargo loaders.
- Supply concentration in European and Asian production sites:Dedicated ground support manufacturing scale concentrates at limited facilities, creating vulnerability to regional logistics disruptions.
- Technical limitation in main-deck compatibility:Hydraulic lift mechanism specifications vary across wide-body aircraft types, fragmenting equipment interoperability and inflating spare parts inventory costs.
Strategic Opportunities
- Automated guided vehicle deployment at major cargo hubs:Labor cost escalation in North American and European ground handling operations is creating white space for autonomous ULD transport systems.
- Long-term service contracts bundled with hardware:Airport procurement channels are tilting toward performance-based agreements that lock in recurring revenue streams for equipment vendors.
- Crane technology transfer into airside logistics:Industrial lifting expertise from port and warehouse applications is migrating into aircraft cargo handling through specialized loader designs.
Industry Challenges
- Certification timeline compression:EASA's CS-25 airworthiness criteria and CAAC's GB standards require concurrent compliance testing, stretching engineering resources across multiple approval pathways.
- Integration complexity with legacy fleet management systems:Telematics-enabled equipment must interface with existing airport IT infrastructure, creating deployment friction at older facilities.
- Specialized technician scarcity:Maintenance of hydraulic lift mechanisms and automated guidance systems demands skills that outpace vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cargo Handling Equipment Market |
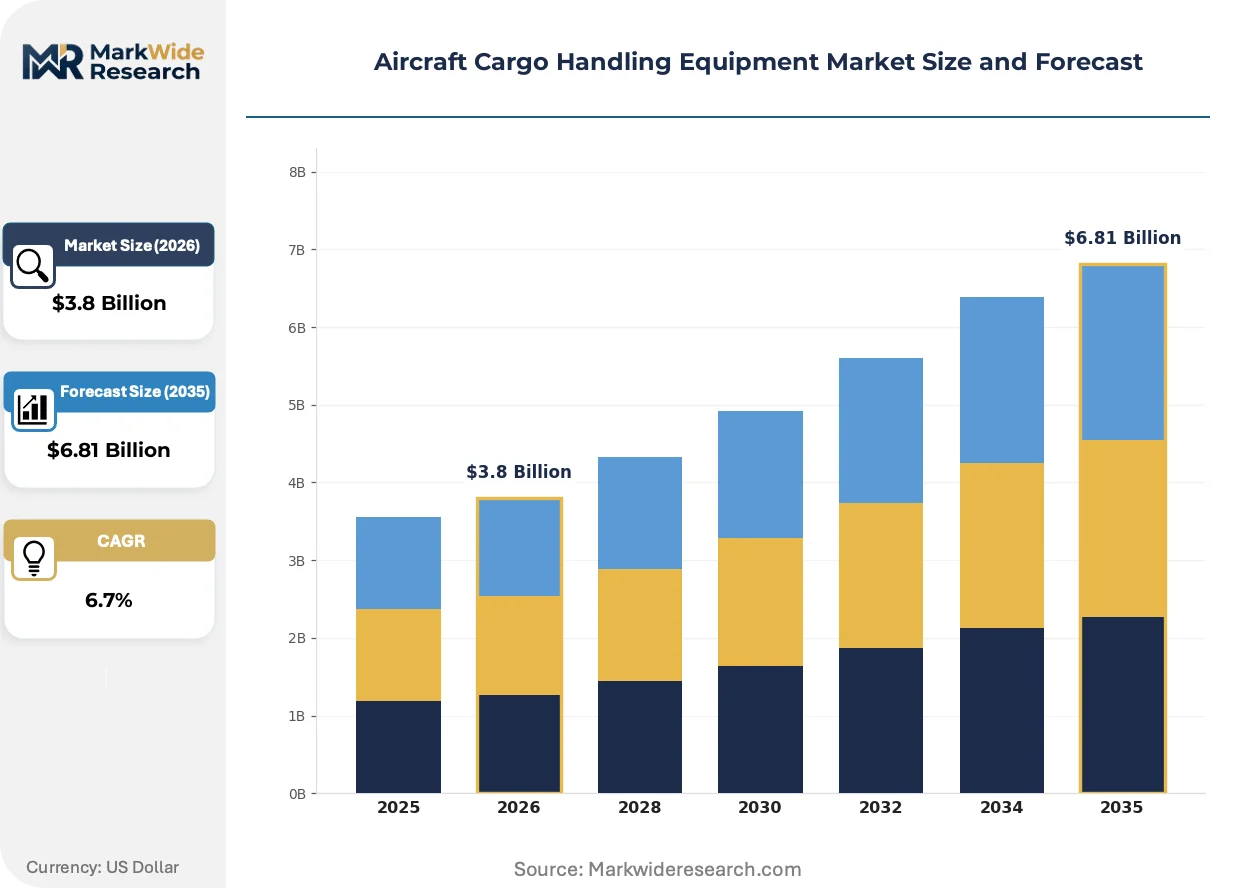
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Containers, Pallet Dollies, Forklifts, Loaders Application: Airport Operations, Ground Handling, Freight Forwarding, Maintenance End User: Airlines, Logistics Companies, Ground Handlers, Government Agencies Technology: Automated Systems, Manual Handling, Hybrid Solutions, Tracking Systems |
| Companies Covered | Oshkosh Aerotech LLC, Konecranes Oyj, TLD Group, Weihai Guangtai Airport Equipment Co Ltd, Daifuku Co., Ltd., JBT AeroTech, Cargotec Oyj, China International Marine Containers (Group) Co Ltd, Textron GSE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cargo Handling Equipment Market Strategic Shifts
Electrification roadmaps, autonomous material handling, and bundled service contracting are converging to redefine equipment lifecycle economics and competitive positioning in airside logistics.
Battery-electric propulsion systems are migrating from niche demonstration projects to mainstream procurement specifications at tier-one cargo hubs. Ground handling operators facing penalty clauses for turnaround-time failures are prioritizing equipment with reduced mechanical complexity and predictive maintenance capability. This technology shift is compressing the residual value premium historically commanded by proven diesel platforms.
Europe's F-Gas Regulation is accelerating phase-out schedules for hydrofluorocarbon-based hydraulic fluids in ground support equipment. Aircraft cargo loader manufacturers must reformulate lift mechanism specifications to comply with lower-global-warming-potential alternatives. Asian production facilities serving European export markets are retooling fluid systems ahead of enforcement deadlines to maintain tender eligibility.
Airlines and freight forwarders are consolidating vendor relationships around integrated fleet management platforms that combine hardware, maintenance, and data analytics. Long-term service agreements are displacing transactional equipment purchases at major cargo hubs in Germany and the United Arab Emirates. This behavioral shift concentrates purchasing power with vertically integrated suppliers capable of underwriting performance guarantees across multi-year contracts.
Aircraft Cargo Handling Equipment Market Segmentation
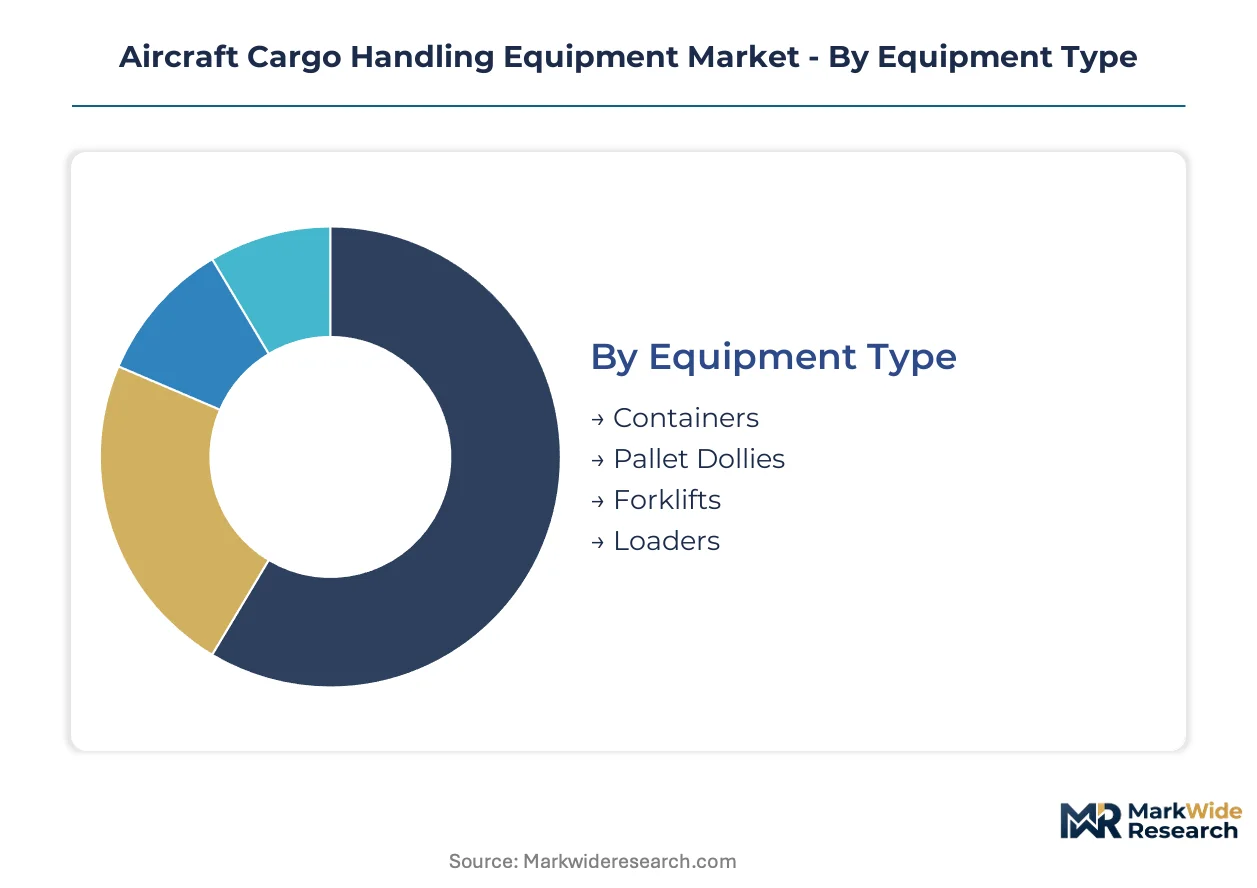
Equipment specifications in aircraft cargo handling diverge sharply across operational environments. Procurement patterns cluster around turnaround-time reliability at major hubs versus cost efficiency at secondary airports.
Equipment Type:
Cost tier differentiation separates standardized container systems from specialized loader platforms requiring hydraulic complexity.
- Containers:Standardized ULD interchange formats dominate wide-body fleet compatibility. Demand concentrates at Chinese tier-one cargo hubs where CAAC GB standards mandate equipment uniformity.
- Pallet Dollies:Non-motorized ground support apparatus for ULD positioning across apron distances. Freight forwarding end users in Germany and the United Arab Emirates increasingly specify telematics-enabled variants for real-time asset tracking.
- Forklifts:Counterbalance designs adapted for airside weight distribution limits.
- Loaders:Powered cargo loaders with hydraulic lift mechanisms for main-deck and lower-hold access.
Containers command the established base. The steepest expansion runs through pallet dollies.
Application:
Operational intensity varies by contract structure — penalty clauses for mechanical failure reshape equipment specifications.
- Airport Operations:Terminal-side cargo transfer infrastructure supporting passenger and freighter aircraft. Chinese infrastructure investment outpaces other markets, creating tender concentration at Beijing and Shanghai hubs.
- Ground Handling:Turnaround-time contracts penalize equipment failure, driving demand for predictive maintenance capability. North American and European operators face labor cost escalation that accelerates automation interest.
- Freight Forwarding:Third-party logistics asset ownership for dedicated cargo flows.
- Maintenance:Scheduled overhaul and component replacement cycles for installed equipment fleets.
Ground handling captures the highest recurring demand intensity. Freight forwarding shows the fastest technology refresh rate.
End User:
Customer type determines procurement channel access and contract duration preferences.
- Airlines:Fleet modernization programs prioritize electrification roadmaps against residual value risk in fossil-fuel equipment. US carriers navigate FAA 14 CFR Part 139 recertification mandates that compress replacement cycles.
- Logistics Companies:E-commerce parcel carriers retrofit legacy infrastructure with telematics integration. Express networks in China and the United States lead capital deployment for automated guided vehicle trials.
- Ground Handlers:Independent service providers operating under airline contract.
- Government Agencies:Military and postal service procurement with specialized security requirements.
Airlines anchor the premium equipment segment. Logistics companies are gaining share fastest in automation procurement.
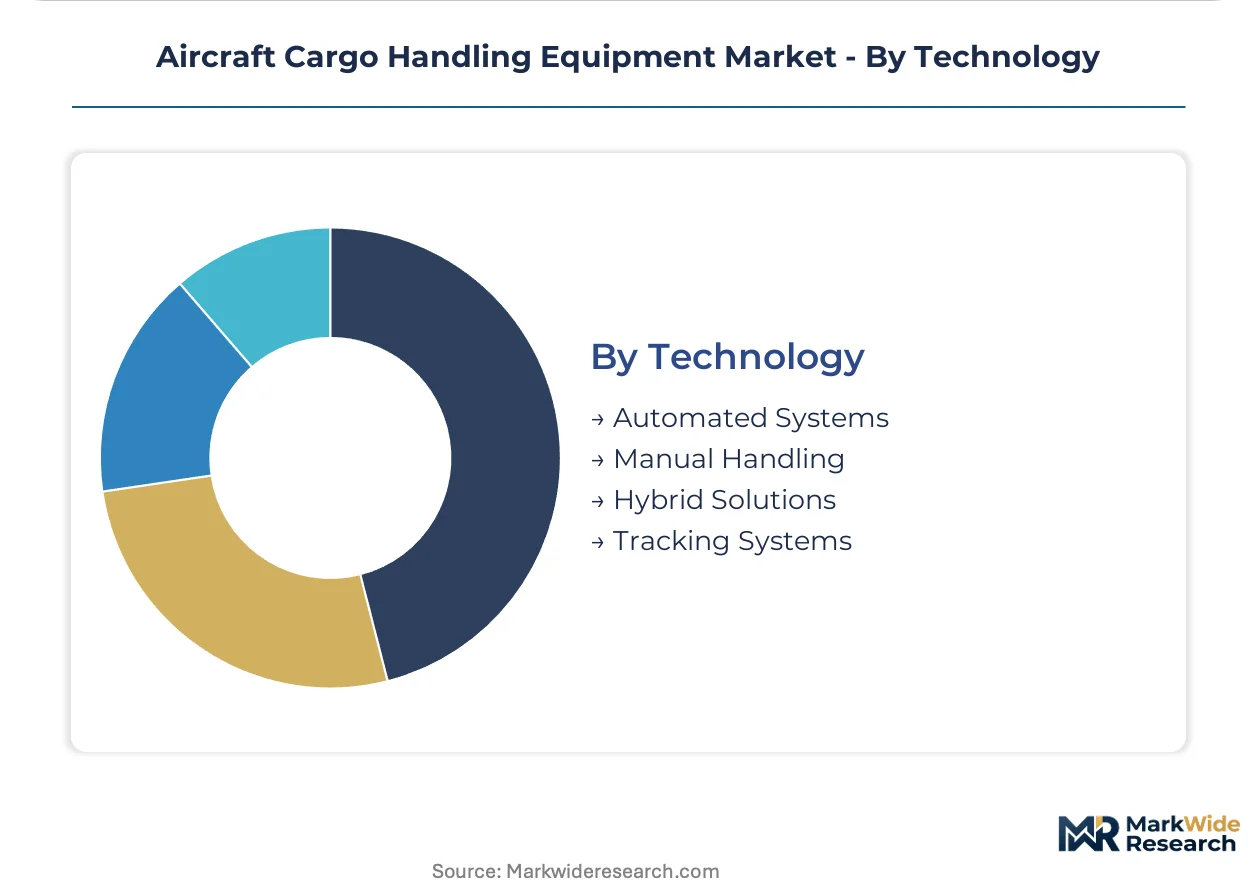
Technology:
Technology maturity separates proven mechanical systems from emerging autonomous platforms.
- Automated Systems:Autonomous guided vehicles for ULD transport across cargo aprons. Labor cost pressures at European and North American hubs create deployment white space for vendor consolidation.
- Manual Handling:Conventional non-powered equipment with lowest capital barrier. Secondary airports in developing markets retain this tier for cost containment.
- Hybrid Solutions:Battery-electric propulsion with diesel range extension for operational flexibility.
- Tracking Systems:Telematics hardware and fleet management software integration.
Manual handling retains the largest installed base. Automated systems are climbing the fastest as labor economics shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese procurement premiums exceed North American pricing by margins that reflect infrastructure urgency and certification barriers. European operators face F-Gas Regulation compliance costs that reshape equipment economics. Middle Eastern hubs exploit tax-advantaged positioning to capture fleet modernization flows.
United States
FAA 14 CFR Part 139 recertification mandates compress replacement cycles at Atlanta, Chicago O'Hare, and Memphis cargo hubs. Ground handlers face penalty clauses for turnaround-time failures that prioritize predictive maintenance capability. Dallas-Fort Worth and Los Angeles anchor the premium equipment segment as airlines electrify legacy fleets.
China
CAAC GB standards for ground support equipment safety mandate uniform tender specifications at Beijing Capital and Shanghai Pudong. Airport infrastructure investment outpaces other markets, creating concentrated demand at tier-one cargo hubs. Pearl River Delta manufacturing clusters supply domestic certification requirements while retooling for European F-Gas compliance.
Germany
EASA CS-25 airworthiness criteria shape equipment interface dimensions through aircraft manufacturer compliance. Frankfurt and Leipzig-Halle cargo hubs consolidate vendor relationships around integrated fleet management platforms. Industrial lifting expertise from port applications migrates into specialized loader designs through crane technology transfer.
United Arab Emirates
Dubai and Abu Dhabi airports displace transactional equipment purchases with performance-based multi-year contracts. Tax-advantaged positioning attracts fleet modernization investment from European and Asian carriers. Ground handling operators specify telematics-enabled pallet dollies for real-time asset tracking across desert climate conditions.
Japan
METI industrial policy supports battery-electric propulsion demonstration projects at Narita and Kansai cargo hubs. Precision manufacturing clusters in Aichi Prefecture supply hydraulic lift mechanism components for main-deck compatibility requirements. Aging technician workforce accelerates automation interest in autonomous guided vehicle deployment.
Aircraft Cargo Handling Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in hydraulic and guidance subsystems. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with aerospace divisions, dedicated ground support equipment manufacturers, and port-logistics equipment specialists extending into airside applications. Competitive moves concentrate on backward integration into hydraulic component production and geographic expansion through Asian production facilities.
Within the diversified industrial tier, Oshkosh Aerotech LLC and Konecranes Oyj exemplify platform breadth strategies. TLD Group occupies a position among dedicated ground support specialists with European and Asian manufacturing scale. Weihai Guangtai Airport Equipment Co Ltd represents Chinese fabrication capabilities serving domestic certification requirements.
| Leading Market Players |
|---|
| Oshkosh Aerotech LLC |
| Konecranes Oyj |
| TLD Group |
| Weihai Guangtai Airport Equipment Co Ltd |
| Daifuku Co., Ltd. |
| JBT AeroTech |
| Cargotec Oyj |
| China International Marine Containers (Group) Co Ltd |
| Textron GSE |
| Others |
Value Chain & Pricing Dynamics
Overcapacity at European production facilities for hydraulic lift components is compressing supplier margins and accelerating consolidation negotiations. This utilization gap feeds directly into pricing posture, as manufacturers extend payment terms to defend market share while buyers exploit tender leverage at Chinese tier-one cargo hubs.
Pricing Analysis
The customization-premium spread between configured-to-order cargo loaders and standard pallet dollies spans three performance tiers tied to CAAC GB certification levels. Contract-based long-term offtake agreements dominate procurement at major hubs, with price differentiation hinging on hydraulic complexity and telematics integration depth. Cost compression in the standard equipment tier is intensifying because Pearl River Delta fabricators are absorbing margin erosion to maintain tender eligibility. Freight forwarding end users in Germany and the United Arab Emirates exhibit the lowest price sensitivity, prioritizing real-time asset tracking over unit economics.
Supply Chain Analysis
Extended payment terms from Chinese fabricators are restructuring working capital requirements across the supplier base. Manufacturing capacity concentrates in China, Germany, and France, with hydraulic lift mechanism components drawing from specialized steel forging clusters in Aichi Prefecture and precision machining networks in Baden-Württemberg. Single-source vulnerability in main-deck compatibility subsystems creates exposure to certification timeline compression. Distribution runs through airport procurement channels that are tilting toward bundled hardware-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as electrification roadmaps splinter procurement specifications across jurisdictions, creating niche openings for specialized subsystem suppliers. E-commerce logistics fleet modernization is fragmenting demand into distinct performance tiers.
For Market Incumbents: Harden aftermarket service networks against emerging autonomous guided vehicle entrants by locking in multi-year performance contracts at Dubai and Abu Dhabi hubs. Backward integration into hydraulic component production reduces exposure to Aichi Prefecture supply bottlenecks. Prioritize CAAC GB certification investment to defend tender access at Beijing Capital and Shanghai Pudong.
For New Entrants and Emerging Players: Establish a beachhead in telematics-enabled pallet dollies for German freight forwarders, where real-time asset tracking specifications outpace incumbent refresh cycles. Automated guided vehicle deployment at North American hubs represents the most penetrable white space, with labor cost escalation creating procurement urgency. Pursue crane technology licensing from port logistics specialists to accelerate airside credibility.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric propulsion subsystems as tier-one hubs mandate electrification compliance. Five-to-ten year viability favors vertically integrated platform vendors with captive hydraulic production and Asian manufacturing scale. Watch for FAA 14 CFR Part 139 enforcement acceleration as the signal for replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Captive production of lift mechanisms insulates against Aichi Prefecture supply bottlenecks and certification delays. |
| Multi-Year Service Contract Bundling | Performance-based agreements at Dubai and Abu Dhabi airports lock in recurring revenue and displace transactional competitors. |
| CAAC GB Certification Investment | Meeting China's ground support equipment safety standards unlocks tender eligibility at tier-one cargo hubs in Beijing and Shanghai. |
| Automated Guided Vehicle Deployment | Autonomous ULD transport systems address labor cost escalation at European and North American ground handling operations. |
| Crane Technology Licensing | Industrial lifting expertise from port applications accelerates airside credibility for specialized main-deck loader designs. |
Study Parameters
A spread of perspectives from ground handling operations directors, airport procurement managers, OEM platform engineers, and aftermarket service heads converged on the working assumptions. Primary interviews combined with secondary validation against FAA 14 CFR Part 139 filings, EASA CS-25 airworthiness criteria documentation, CAAC GB standards publications, and customs trade data for ground support equipment. Bottom-up equipment unit economics triangulated against top-down airport infrastructure investment flows.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include equipment type, application intensity, end-user procurement channel, and technology maturity tier. CAGRs derived from equipment replacement cycle analysis and infrastructure investment trajectories. Forecast inputs incorporated EASA F-Gas Regulation compliance cost absorption and METI battery-electric demonstration project scalability.
Sensitivities concentrate around electrification deadline alignment across jurisdictions and hydraulic fluid reformulation timelines. Forecasts reflect documented assumptions on fleet modernization program pacing and certification pathway concurrency. Macroeconomic deviation in airport infrastructure investment, regulatory enforcement acceleration, or autonomous guidance technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
India Aviation Infrastructure Market