
 Europe AI Orchestration Market | 2026-2036
Europe AI Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Europe AI Orchestration Market Analytics
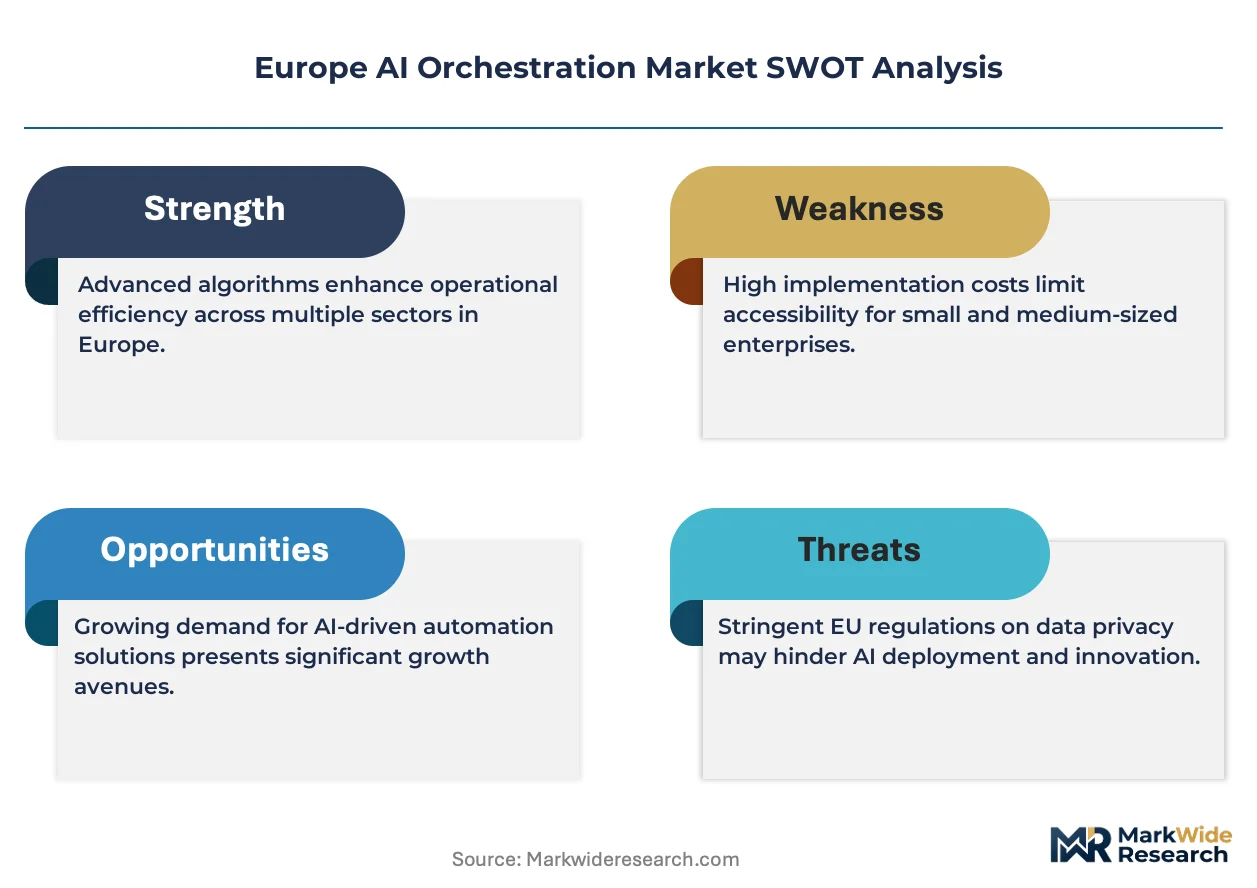
CE marking under the EU AI Act is rotating vendor eligibility across the Europe AI Orchestration Market, forcing platform providers to demonstrate conformity with risk-management protocols before accessing public-sector procurement channels. SAP SE leverages its entrenched ERP footprint to embed orchestration layers within existing enterprise stacks across DAX-listed manufacturers. Fujitsu Limited anchors its competitive position through specialized edge-to-cloud coordination tools designed for latency-sensitive industrial workloads.
AI orchestration denotes the automated coordination, scheduling, and lifecycle management of heterogeneous machine-learning models, data pipelines, and compute resources across distributed infrastructure, typically governed by API-driven control planes and policy-based resource allocators that enforce service-level objectives for inference latency and model drift. The technology serves industrial and commercial purposes by eliminating manual intervention in model deployment, enabling continuous retraining loops, and ensuring consistent performance across hybrid environments. Cloud-based deployment dominates current spending as enterprises prioritize elastic scaling for training workloads, while edge configurations represent the fastest-expanding segment due to manufacturing demand for localized inference in Germany and Italy. Managed services capture disproportionate margin pools because European buyers lack internal MLOps expertise and prefer outcome-based contracts with explicit uptime guarantees.
The EU AI Act, GDPR, and CE marking framework collectively reshape product requirements, mandating traceability logs, human oversight mechanisms, and documented risk classifications for high-risk AI applications before market authorization. EMA guidelines for AI-enabled drug discovery tools further tighten validation standards in healthcare deployments. Stakeholders must monitor evolving national implementation timelines for the EU AI Act across member states, as divergent enforcement calendars will fragment procurement readiness and create first-mover advantages for vendors pre-certified in early-adopter jurisdictions.
Market Dynamics
CE marking requirements under the EU AI Act are fragmenting vendor eligibility across European procurement channels, forcing platform providers to demonstrate conformity with risk-management protocols before accessing public-sector contracts.
Growth Catalysts
- EU AI Act compliance mandates:High-risk AI applications now require documented traceability logs and human oversight mechanisms, creating mandatory upgrade cycles for legacy orchestration stacks in healthcare and financial services.
- Automotive edge inference demand:Germany's precision engineering corridor requires real-time model coordination across multi-cloud environments, pulling specialized orchestration tools into manufacturing facilities.
- MLOps talent scarcity:European enterprises lack internal expertise to manage distributed machine-learning lifecycles, accelerating reliance on managed service providers with explicit uptime guarantees.
Market Restraints
- GPU compute cost volatility:Training workload elasticity ties orchestration platform economics to NVIDIA supply allocation and cloud provider pricing tiers, compressing margins for mid-market buyers.
- Regulatory fragmentation risk:Divergent national implementation timelines for the EU AI Act across member states will fragment procurement readiness and delay multi-country deployments.
- Hybrid integration complexity:Legacy ERP systems from entrenched vendors create technical debt that slows API-driven control plane adoption in DAX-listed manufacturers.
Strategic Opportunities
- Italian manufacturing automation:Northern industrial clusters lag German orchestration penetration, presenting first-mover advantages for edge-to-cloud coordination tools in latency-sensitive production lines.
- Healthcare validation standards:EMA guidelines for AI-enabled drug discovery tools tighten compliance requirements, opening specialized workflow engine demand in pharmaceutical R&D.
- GDPR-CSRD convergence:Sustainability reporting mandates intersect with data governance frameworks, enabling unified audit trails that serve dual compliance objectives across financial services.
Industry Challenges
- CE marking timeline compression:Conformity assessment procedures for high-risk AI systems extend 12-18 months, delaying revenue recognition for platform providers targeting public-sector procurement.
- Multi-cloud API standardization gaps:Inconsistent control plane implementations across AWS, Azure, and GCP fracture policy-based resource allocation in enterprise hybrid environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe AI Orchestration Market |
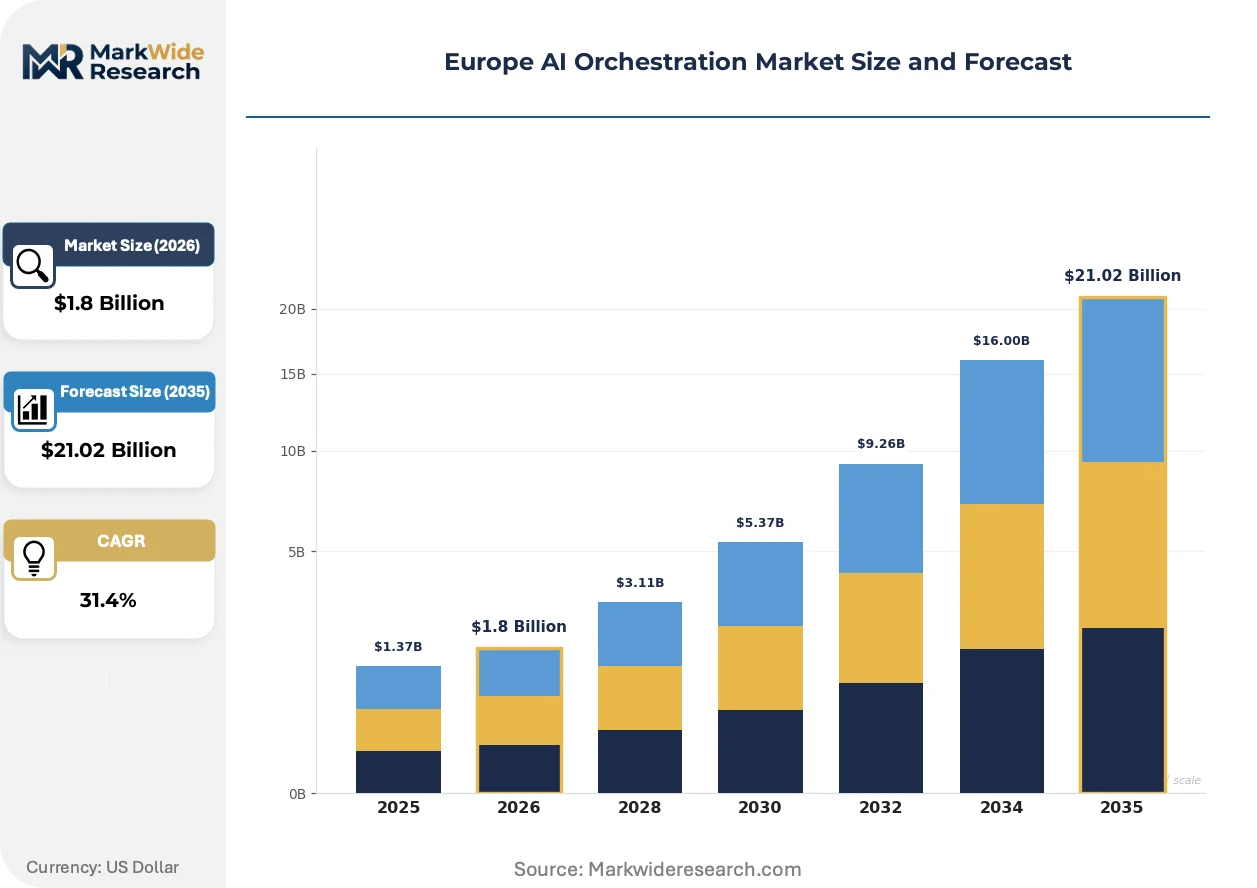
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $21.02 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Edge End User: Information Technology, Manufacturing, Healthcare, Retail Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Bare Metal Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Oracle Corporation, SAP SE, Fujitsu Limited, Cisco Systems, Inc., IBM Corporation, Hewlett-Packard Enterprise Company, Tibco Software, Inc., General Electric Company, Wipro Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe AI Orchestration Market Evolving Landscape
Workflow engine architectures are pivoting toward explainable inference pipelines as European buyers prioritize auditability over raw performance metrics in procurement decisions.
API-driven control planes are fragmenting across vendor-specific implementations, complicating multi-cloud resource allocation for enterprises running heterogeneous machine-learning stacks. Automotive manufacturers in Stuttgart and Munich are adopting specialized edge coordination layers fastest, compressing time-to-inference for quality-control computer vision. This fragmentation is forcing buyers toward abstraction layers that normalize policy enforcement across incompatible provider ecosystems.
GDPR Article 22 provisions on automated decision-making are tightening documentation requirements for high-risk AI applications, mandating human-in-the-loop checkpoints within orchestration workflows. Industrial consequence includes mandatory audit trail retention and explainability modules that increase platform engineering overhead. Healthcare deployments face the strictest interpretation, with EMA validation standards requiring documented model drift monitoring in pharmaceutical discovery pipelines.
Buyer preference is rotating toward outcome-based service contracts with explicit uptime guarantees, displacing traditional license-plus-maintenance pricing in enterprise procurement. Managed service providers capture disproportionate margin pools as European buyers trade capital expenditure for operational predictability. France and Germany show the strongest contract restructuring, with automotive and financial services verticals leading the shift from perpetual licenses to consumption-aligned arrangements.
Europe AI Orchestration Market Segmentation
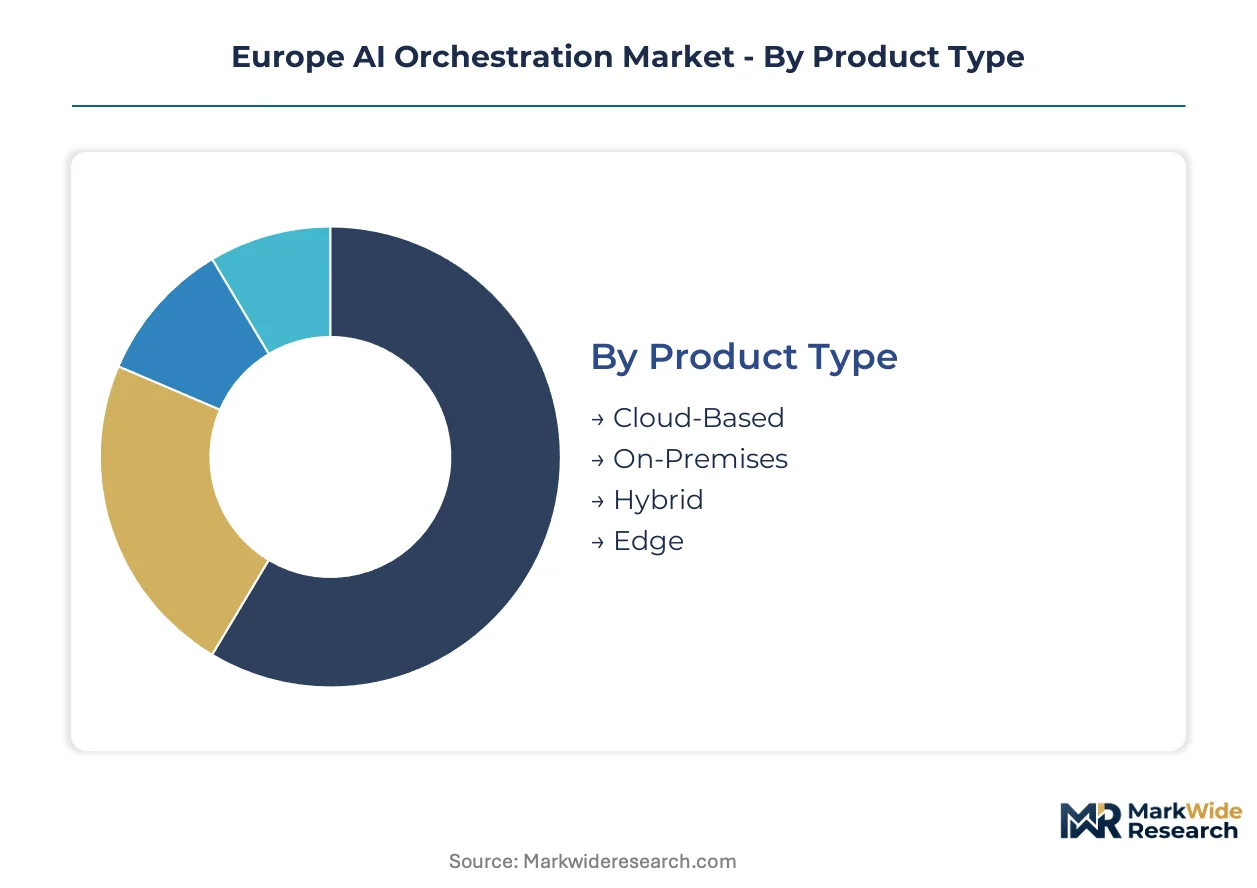
Segmentation in Europe AI Orchestration Market reveals divergent procurement patterns across regulatory environments and infrastructure maturity. German automotive buyers prioritize edge-native configurations, while French financial services concentrate spending on compliance-ready managed services.
Product Type:
Domestic demand clusters in Germany and France favor on-premises and edge configurations for data sovereignty, while cloud-based solutions serve export-oriented enterprises with distributed operations.
- Cloud-Based:Elastic compute pools orchestrate training workloads across distributed GPU clusters, with hyperscaler API integration enabling policy-based resource allocation. Demand concentrates in Amsterdam and Dublin data center corridors serving pan-European financial services firms under GDPR constraints.
- Edge:Latency-optimized inference engines deploy directly on factory floors in Stuttgart and Munich manufacturing clusters. German precision engineering sectors require sub-10ms coordination for quality-control computer vision, pulling specialized orchestration layers into production facilities.
- On-Premises:Air-gapped control planes serve defense and pharmaceutical R&D facilities in Switzerland and France with strict data residency mandates.
- Hybrid:Bridge architectures normalize policy enforcement across AWS, Azure, and GCP environments for DAX-listed manufacturers with legacy ERP integration requirements.
Cloud-based configurations command the established base. The steepest expansion runs through edge deployments.
End User:
Cost tier differentiation separates premium compliance-grade deployments in regulated verticals from standard configurations in commercial IT.
- Manufacturing:Real-time model coordination across multi-cloud environments serves automotive and precision engineering sectors in Germany's industrial corridor. Stuttgart and Munich facilities demand localized inference for predictive maintenance and defect detection.
- Healthcare:EMA-validated workflow engines enforce traceability logs and human oversight checkpoints for AI-enabled drug discovery tools. Pharmaceutical R&D clusters in Basel and Cambridge require documented model drift monitoring.
- Information Technology:Managed service consumption dominates as European enterprises trade capital expenditure for operational predictability in MLOps talent-scarce environments.
- Retail:Demand personalization pipelines coordinate recommendation engines across hybrid infrastructure, with French luxury goods houses leading edge-to-cloud adoption.
Manufacturing anchors revenue concentration. Healthcare gains share fastest on regulatory tailwinds.
Deployment Model:
Volume distribution skews toward multi-cloud and private configurations as buyers mitigate vendor lock-in and satisfy EU AI Act data governance requirements.
- Multi-Cloud:Abstraction layers normalize API-driven control planes across incompatible provider ecosystems, enabling policy-based resource allocation in heterogeneous machine-learning stacks. German automotive manufacturers lead adoption to avoid single-hyperscaler dependency.
- Private Cloud:Dedicated infrastructure serves high-risk AI applications requiring CE marking conformity and documented risk classifications before public-sector procurement eligibility.
- Public Cloud:Elastic scaling for training workloads concentrates in Ireland and Netherlands data center regions serving fintech clusters.
- Bare Metal:GPU-dense configurations support foundation model training for research consortia with specialized latency requirements.
Multi-cloud configurations capture disproportionate strategic investment. Private cloud maintains premium pricing power.
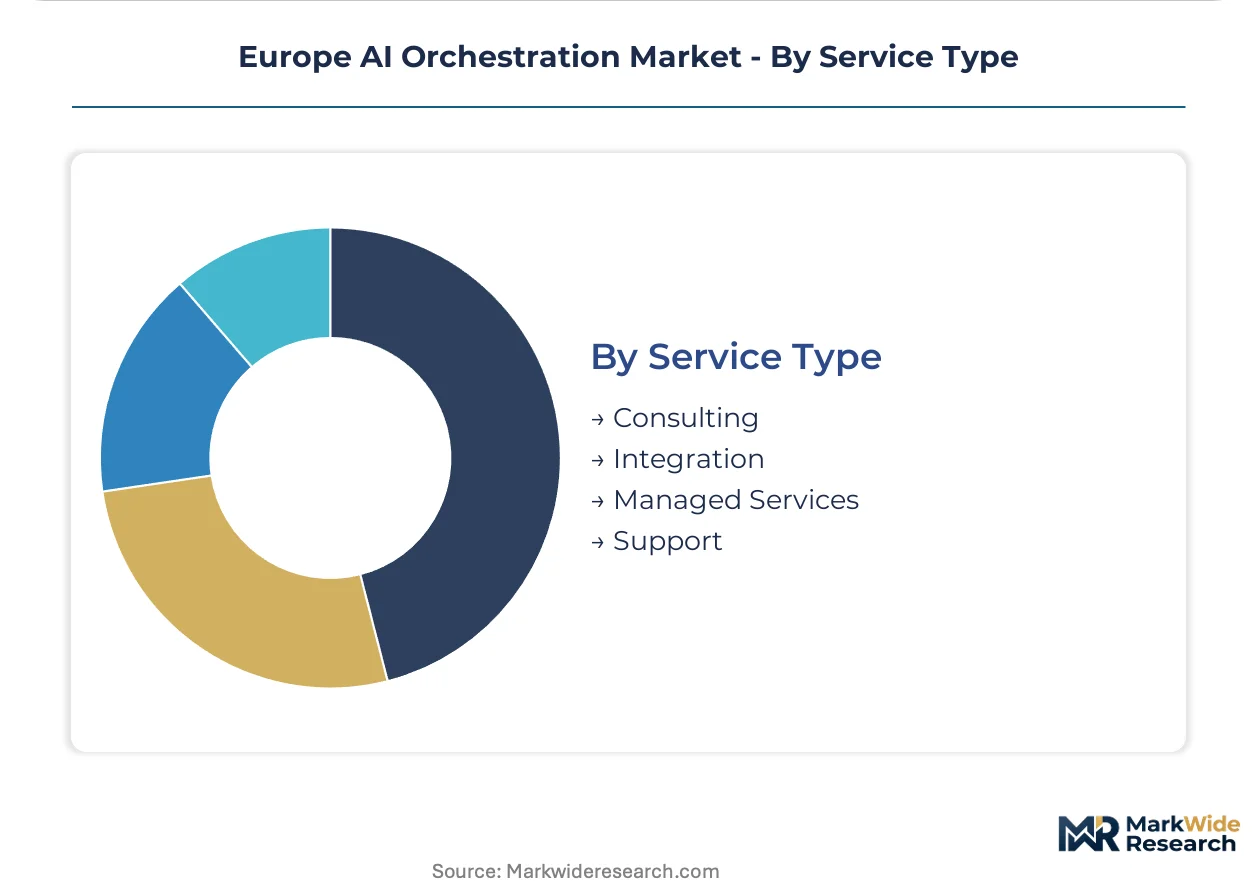
Service Type:
Customer type stratification separates outcome-based contracts with explicit uptime guarantees from discrete project engagements.
- Managed Services:European buyers lacking internal MLOps expertise prefer operational predictability over capital expenditure, with France and Germany showing strongest contract restructuring. Providers capture disproportionate margin pools through consumption-aligned arrangements.
- Integration:Legacy ERP system connectivity from SAP SE entrenched bases creates technical debt that slows API-driven control plane adoption, requiring specialized middleware development.
- Consulting:EU AI Act readiness assessments and CE marking preparation guide high-risk AI system deployments through 12-18 month conformity assessment timelines.
- Support:Tiered response commitments serve manufacturing facilities requiring 24/7 inference uptime for continuous production lines.
Managed services command margin expansion. Integration services face pricing pressure from talent scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement in Europe clusters around automotive manufacturers in Germany and financial services firms in France, with compliance-driven buyers in Switzerland and Italy expanding edge deployments fastest.
Germany
Automotive and precision engineering sectors in Stuttgart and Munich drive demand for sub-10ms edge inference coordination. KBA vehicle safety standards intersect with EU AI Act high-risk system classifications for autonomous driving applications. The Baden-Württemberg industrial corridor hosts the densest concentration of factory-floor orchestration deployments.
France
Luxury goods houses and banking consortia in Paris prioritize GDPR-compliant managed service contracts with explicit uptime guarantees. ANSM pharmaceutical guidelines and CNIL data protection rulings tighten documentation requirements for AI-enabled drug discovery workflows. Île-de-France financial services clusters lead the shift from perpetual licenses to consumption-aligned arrangements.
United Kingdom
Pharmaceutical R&D facilities in Cambridge and London fintech clusters demand EMA-validated workflow engines with documented model drift monitoring. The Medicines and Healthcare products Regulatory Agency enforces traceability log retention for clinical decision-support systems. Cambridge biotech corridors anchor healthcare-specific orchestration penetration.
Switzerland
Air-gapped control planes serve defense and pharmaceutical R&D facilities in Basel and Zurich with strict data residency mandates. Swissmedic validation standards exceed EMA baselines for AI-enabled therapeutic development tools. Basel pharmaceutical clusters require documented risk classifications before procurement authorization.
Italy
Northern industrial clusters in Lombardy and Piedmont lag German orchestration penetration, presenting first-mover opportunities for edge-to-cloud coordination tools. CE marking timelines under national implementation of the EU AI Act compress vendor eligibility windows. Turin automotive suppliers accelerate localized inference adoption for quality-control computer vision.
Europe AI Orchestration Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with entrenched enterprise relationships, creating a tiered structure where ERP-embedded vendors hold procurement advantages in manufacturing verticals. Three archetypes dominate: hyperscaler-aligned platform providers, specialized edge-to-cloud coordination specialists, and legacy enterprise software vendors with orchestration layer extensions. Competitive moves concentrate on CE marking pre-certification racing and managed service contract restructuring toward outcome-based pricing.
Within the legacy enterprise tier, SAP SE leverages its entrenched ERP footprint across DAX-listed manufacturers, while Oracle Corporation and IBM Corporation occupy positions as diversified technology providers with API-driven control plane offerings. Fujitsu Limited exemplifies the edge-specialist archetype through its focus on latency-sensitive industrial workloads. These three anchors represent distinct competitive vectors: ERP integration depth, multi-cloud abstraction capability, and factory-floor coordination expertise.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Fujitsu Limited |
| Cisco Systems, Inc. |
| IBM Corporation |
| Hewlett-Packard Enterprise Company |
| Tibco Software, Inc. |
| General Electric Company |
| Wipro Limited |
| Others |
Value Network & Pricing Analysis
Hyperscaler GPU allocation economics concentrate supply-side leverage among three cloud providers, compressing price floors for mid-market buyers while elevating premium tiers for latency-guaranteed edge deployments. This scale concentration forces European orchestration vendors to absorb input cost volatility through fixed-fee managed service contracts rather than pass-through pricing.
Pricing Analysis
Cost-plus contracts with NVIDIA GPU indexation dominate enterprise procurement, with hyperscaler pricing tiers resetting quarterly based on foundry allocation. Three-tier pricing structure across premium compliance-grade, standard multi-tenant, and economy self-managed configurations separates buyers by CE marking readiness and uptime guarantee requirements. Pricing pressure stems from MLOps talent scarcity forcing buyers toward outcome-based consumption models with explicit SLA penalties. Financial services firms in France show lowest price sensitivity due to regulatory compliance mandates, while Italian manufacturing SMEs face acute budget constraints.
Supply Chain Analysis
NVIDIA H100 transit through Taiwan Semiconductor Manufacturing chokepoints underpins supply security for training-optimized orchestration stacks. Hardware concentration in Taiwan, South Korea, and USA combines with software dependency on open-source Kubernetes and proprietary hyperscaler APIs. Single-source vulnerability in advanced GPU foundry capacity exposes deployment timelines to 12-18 month lead time extensions. Distribution runs through hyperscaler marketplaces and direct enterprise licensing, with managed service providers capturing downstream margin pools through outcome-based contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service attach rates are expanding faster than platform licensing as European buyers trade capital expenditure for operational predictability in MLOps-scarce environments.
For Market Incumbents: Consolidate ERP-embedded orchestration layers through deeper SAP SE integration partnerships, defending against hyperscaler-native workflow engines. Prioritize CE marking pre-certification racing in Germany and France to lock out unqualified competitors from public-sector procurement channels. Vertical integration into specialized edge hardware partnerships secures sub-10ms latency guarantees for Stuttgart automotive clusters. For New Entrants and Emerging Players: Lead with Italian manufacturing automation white space, where northern industrial clusters lag German orchestration penetration by 24-36 months. Target pharmaceutical R&D facilities in Basel and Cambridge with EMA-validated workflow engines as the most penetrable compliance-driven segment. Go-to-market through GPO-affiliated systems integrators with existing healthcare validation credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among edge-to-cloud coordination specialists with factory-floor deployment expertise. Long-term viability hinges on regulatory moat depth rather than raw technical differentiation. Acquisition targets should demonstrate CE marking readiness in at least two EU member states. Watch for EU AI Act national implementation timeline divergence as inflection signal for first-mover advantage windows.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification | Unlocks public-sector procurement eligibility under EU AI Act high-risk system classifications. |
| Managed Service Contract Restructuring | Captures margin expansion as French automotive buyers shift from perpetual licenses to consumption-aligned arrangements. |
| Edge-to-Cloud Platform Integration | Addresses German precision engineering demand for sub-10ms inference coordination across multi-cloud environments. |
| Strategic Partnership with Hyperscaler | Secures GPU allocation priority for training workload elasticity in Amsterdam and Dublin data center corridors. |
| Acquisition of MLOps Specialist Firm | Addresses European enterprise talent scarcity through embedded expertise and outcome-based service delivery. |
Research Methodology
The analysis maps cloud-based, edge, on-premises, and hybrid deployment configurations, each validated through platform engineering directors, IT procurement officers, MLOps team leads, and compliance officers at DAX-listed manufacturers. Primary interviews combined with secondary validation against hyperscaler capex disclosures, EU AI Act implementation timelines, EMA guideline documents, and hospital procurement databases. Bottom-up deployment counts triangulated against top-down addressable spend estimates across Germany, France, United Kingdom, Switzerland, and Italy.
Consistency checks validated volume and value outputs against external benchmarks including cloud infrastructure spending reports and enterprise software licensing databases. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, integration complexity with legacy ERP systems, and regional regulatory adoption pattern. CAGRs derived from fitted growth curves anchored to documented procurement pipeline visibility. Industry-specific forecast inputs include CE marking assessment queue lengths and GPU supply allocation forecasts from foundry partners.
Forecasts assume regulatory continuity in EU AI Act implementation across member states; material policy shifts or divergent national enforcement calendars would require re-modeling procurement readiness timelines. Scenario analysis incorporated alternative trajectories for GPU supply normalization and MLOps talent market development. Practitioners should keep alternative scenarios live as EMA validation standards and KBA vehicle safety interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market