
 AI Industrial Defect Detection Market | 2026-2036
AI Industrial Defect Detection Market Size, Share, and Industry Trends Forecast 2026-2036
AI Industrial Defect Detection Market Insights
Asset-light leasing models for machine vision hardware are narrowing the competitive field for mid-sized manufacturers seeking zero-CAPEX deployment. Cognex Corporation leverages its embedded vision software stack to sustain recurring revenue through subscription-based platform licensing. Keyence Corporation anchors its position through direct sales engineering teams that control technical specification conversations with automotive Tier-1 suppliers.
AI industrial defect detection encompasses automated systems that apply convolutional neural networks and spectral imaging to identify surface anomalies, dimensional deviations, and subsurface flaws in manufactured components with resolution thresholds below 50 microns. These systems execute real-time classification of defect severity to trigger sorting, rework routing, or line shutdown decisions before non-conforming parts propagate downstream. Visual inspection systems dominate current installed bases across electronics assembly lines where PCB solder joint verification demands sub-millimeter accuracy. Edge computing deployments are expanding fastest in metal casting facilities requiring sub-10 millisecond latency for hot crack detection during continuous pouring operations. SaaS platforms are capturing emerging margin pools among quality assurance laboratories serving distributed supplier networks with centralized model retraining services.
The EU AI Act imposes conformity assessment obligations on high-risk industrial AI applications including aerospace component inspection systems deployed within European Economic Area member states. FDA's Quality System Regulation and ISO 9001:2015 frameworks mandate documented validation protocols for automated inspection equipment serving pharmaceutical production and medical device manufacturing. China's SAMR technical standards for intelligent manufacturing equipment are accelerating domestic certification requirements for imported vision systems. Stakeholders must monitor divergence between regional AI governance frameworks when architecting unified product platforms for multinational deployment.
Market Dynamics
Edge-based inference architectures are compressing latency thresholds below 10 milliseconds, forcing equipment suppliers to redesign hardware-software stacks for continuous casting lines and PCB assembly operations.
Growth Catalysts
- EU AI Act Conformity Requirements:High-risk manufacturing applications now face mandatory third-party assessment, creating replacement demand for legacy inspection systems lacking documented validation protocols.
- Electronics Foundry Retrofit Cycles:China's Yangtze River Delta manufacturing corridor is replacing manual optical inspection stations with automated vision systems to meet sub-50 micron solder joint verification standards.
- Hyperspectral Imaging Integration:Metal casting facilities are deploying short-wave infrared sensors to detect subsurface porosity in aluminum die-cast components during active pouring sequences.
Market Restraints
- GPU Supply Concentration:Inference accelerator procurement depends on Taiwan-based foundry capacity, exposing vision system OEMs to lead time volatility for edge computing modules.
- Validation Documentation Burden:FDA Quality System Regulation and ISO 9001:2015 frameworks require extensive protocol records, extending deployment timelines for pharmaceutical packaging inspection lines.
- Manual Inspection Substitution Ceiling:Complex cosmetic defect categories in luxury automotive interiors still require human tactile assessment, limiting full automation penetration.
Strategic Opportunities
- India PLI Scheme Incentives:Electronics manufacturing subsidies are attracting component suppliers needing automated quality assurance for smartphone assembly export compliance.
- SaaS Model Retention Pools:Quality assurance laboratories serving distributed supplier networks can capture recurring revenue through centralized model retraining and drift monitoring services.
- 5G-Enabled Distributed Inspection:Ultra-reliable low-latency connectivity allows cloud-based inference for facilities lacking on-premise compute infrastructure.
Industry Challenges
- Computer Vision Engineer Scarcity:Defect classification model development requires specialized expertise in convolutional neural network architecture optimization, constraining deployment velocity for mid-sized manufacturers.
- Legacy MES Integration Friction:Brownfield production lines running proprietary manufacturing execution systems demand costly middleware development to enable real-time defect data routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Industrial Defect Detection Market |
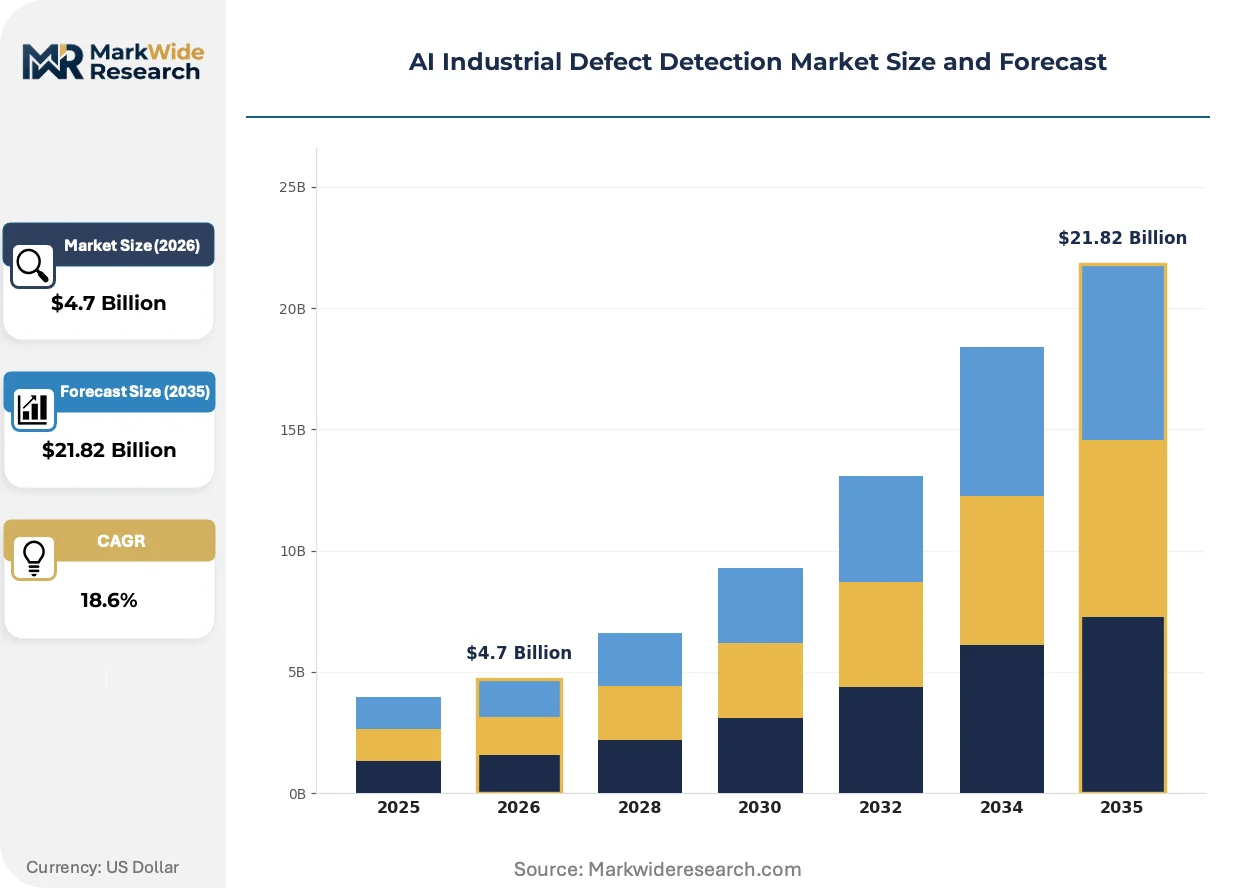
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visual Inspection Systems, Ultrasonic Detectors, Infrared Scanners, X-ray Sensors, Acoustic Emission Devices Deployment: On-Premise, Cloud-Based, Edge Computing, Hybrid Solutions, SaaS Platforms Application: Metal Casting, Electronics Assembly, Textile Manufacturing, Food Packaging, Pharmaceutical Production, Aerospace Component Inspection End User: OEMs, Tier-1 Suppliers, Quality Assurance Laboratories, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Cognex Corporation, Keyence Corporation, Omron Corporation, Teledyne Technologies, Basler AG, SICK AG, Siemens AG, ABB, ZEISS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Industrial Defect Detection Market Trends and Innovations
Inspection technology is bifurcating between hyper-specialized edge devices and cloud-native training platforms, with deployment economics favoring hybrid architectures that partition inference and model refinement.
Digital twin environments are virtualizing defect simulation workflows, allowing quality engineers to generate synthetic training datasets for rare failure modes without halting production lines. Automotive OEMs in Germany and Japan are adopting these virtual validation pipelines to compress new model deployment cycles. This capability is virtualizing the traditional hardware-in-the-loop testing phase, reducing capital requirements for system qualification.
The EU AI Act's high-risk system classification is mandating conformity assessment procedures for aerospace component inspection equipment deployed within European Economic Area member states. Equipment suppliers must now maintain technical documentation and quality management systems subject to third-party audit. Vision system vendors are responding by establishing dedicated regulatory affairs functions and pre-certifying platforms through notified bodies.
Leasing structures for machine vision hardware are displacing traditional capital purchase models among automotive Tier-1 suppliers seeking operational expenditure treatment. Asset-light procurement is concentrating supplier relationships with platform vendors offering embedded software subscriptions. Germany's automotive supply base exhibits the fastest migration toward per-inspection pricing arrangements.
AI Industrial Defect Detection Market Segmentation
Segmentation in AI industrial defect detection reveals how technology choices map to operational constraints across manufacturing environments. Deployment architecture and inspection modality decisions directly determine latency thresholds, capital requirements, and regulatory compliance pathways for quality assurance operations.
Product Type:
Use-case spectrum spans surface anomaly detection through subsurface flaw identification, with spectral range and penetration depth defining technical suitability across material categories.
- Visual Inspection Systems:Convolutional neural networks process high-resolution optical feeds to classify surface defects at sub-50 micron resolution. Electronics foundries in China's Yangtze River Delta deploy these for PCB solder joint verification where dimensional tolerances are tightest.
- Ultrasonic Detectors:Piezoelectric transducers emit high-frequency acoustic pulses to detect internal voids and delaminations in composite materials. Aerospace component manufacturers leverage this modality for carbon fiber layup validation where X-ray penetration risks material degradation.
- Infrared Scanners:Thermal imaging identifies heat signature anomalies indicating material inconsistencies or electrical faults. Metal casting facilities integrate short-wave infrared for hot crack detection during continuous pouring sequences.
- X-ray Sensors:Computed tomography systems generate volumetric reconstructions for sealed component inspection. Pharmaceutical packaging lines deploy these for fill-level verification and foreign particle detection in parenteral containers.
- Acoustic Emission Devices:Piezoelectric sensors capture stress-wave signals from propagating cracks in structural components. Pressure vessel manufacturers monitor these emissions during hydrostatic testing protocols.
The dominant share belongs to Visual Inspection Systems, while Infrared Scanners are closing the gap fastest through hyperspectral integration in metal casting applications.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operational-expenditure cloud and SaaS alternatives, with latency requirements dictating hybrid architecture prevalence.
- On-Premise:Dedicated server infrastructure hosts inference workloads within facility firewalls, satisfying data sovereignty requirements. Pharmaceutical manufacturers subject to FDA Quality System Regulation prefer this model for audit trail control.
- Cloud-Based:Centralized compute resources execute model training and batch inference for non-time-critical applications. Quality assurance laboratories serving distributed supplier networks leverage this for centralized model retraining services.
- Edge Computing:Embedded accelerators process inference locally with sub-10 millisecond latency for real-time process control. Continuous casting lines require this architecture for hot crack detection before defects propagate through solidifying metal.
- Hybrid Solutions:Partitioned workloads run inference at the edge while model refinement occurs in cloud environments. Automotive OEMs in Germany deploy this architecture to balance latency constraints with centralized algorithm updates.
- SaaS Platforms:Subscription-based access to inspection software and model management tools eliminates hardware procurement. Mid-sized manufacturers seeking zero-CAPEX deployment increasingly select this procurement model.
Edge Computing commands the largest installed base among high-volume manufacturers, though SaaS Platforms are expanding most quickly among quality assurance laboratories and smaller component suppliers.
Application:
Volume concentration tracks manufacturing output intensity, with electronics and automotive component production generating the highest inspection station density per facility.
- Metal Casting:Real-time defect detection during pouring and solidification prevents scrap generation in aluminum and steel foundries. Subsurface porosity identification through thermal imaging is displacing destructive testing protocols.
- Electronics Assembly:SMT lines require micron-level solder joint inspection at throughput rates exceeding 100,000 components per hour. China's contract electronics manufacturers retrofit manual optical inspection stations with automated vision systems.
- Textile Manufacturing:Machine vision identifies weave irregularities, color variations, and foreign fiber contamination in continuous fabric production. High-speed line scan cameras process material moving at 200 meters per minute.
- Food Packaging:Hyperspectral imaging detects seal integrity failures and foreign material contamination in sealed pouches and trays. EU hygiene regulations mandate documented inspection protocols for ready-to-eat product lines.
- Pharmaceutical Production:Automated inspection of vials, syringes, and blister packs verifies particle contamination, fill accuracy, and label placement. FDA computer-assisted device guidance requires validation documentation for these systems.
- Aerospace Component Inspection:Multi-modal defect detection across turbine blades, structural fasteners, and composite panels demands traceable certification records. EU AI Act conformity assessment obligations apply to high-risk aerospace applications.
Electronics Assembly maintains the dominant deployment volume, while Pharmaceutical Production exhibits the steepest expansion trajectory driven by regulatory validation requirements and serialization mandates.
End User:
Customer type determines specification authority and procurement modality, with OEMs controlling design requirements while Tier-1 suppliers absorb deployment economics.
- OEMs:Original equipment manufacturers specify inspection standards and validate supplier quality systems. Germany's automotive OEMs mandate machine vision deployment for weld seam verification across their supply bases.
- Tier-1 Suppliers:Component manufacturers integrate inspection stations to meet customer quality agreements and reduce warranty exposure. Direct sales engineering relationships with vision system vendors control technical specification conversations.
- Quality Assurance Laboratories:Independent testing facilities provide certification services for supplier networks and regulatory submissions. Centralized model retraining and drift monitoring services generate recurring revenue streams.
- Aftermarket Providers:Refurbishment and remanufacturing operations inspect returned components for reuse eligibility. Circular economy regulations in Europe expand demand for secondary market quality verification.
- Vehicle Assemblers:Final assembly plants perform incoming inspection of critical safety components before integration. Real-time defect data routing to manufacturing execution systems enables immediate supplier feedback.
Tier-1 Suppliers represent the largest addressable population, though Quality Assurance Laboratories are gaining share fastest through SaaS platform adoption and distributed supplier network services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and tightening AI governance frameworks are redirecting manufacturing investment toward automated quality assurance infrastructure across major industrial economies.
Germany
Automotive OEMs mandate machine vision deployment for weld seam verification across supplier networks. The EU AI Act imposes conformity assessment obligations on high-risk industrial AI applications including aerospace component inspection. Manufacturing clusters in Bavaria and Baden-Württemberg retrofit production lines with edge-based defect detection systems.
China
Electronics foundries in the Yangtze River Delta manufacturing corridor replace manual optical inspection with automated vision systems. SAMR technical standards for intelligent manufacturing equipment accelerate domestic certification requirements for imported vision systems. Contract manufacturers in Shenzhen and Suzhou deploy sub-50 micron solder joint verification at throughput rates exceeding 100,000 components per hour.
United States
Pharmaceutical manufacturers subject to FDA Quality System Regulation prefer on-premise deployment for audit trail control. FDA computer-assisted device guidance mandates documented validation protocols for automated inspection equipment serving medical device production. Boston and Research Triangle Park quality assurance laboratories capture recurring revenue through centralized model retraining services.
Japan
Automotive Tier-1 suppliers absorb deployment economics for machine vision hardware through operational expenditure treatment. METI industrial standards support precision manufacturing quality benchmarks. Nagoya and Osaka manufacturing bases exhibit accelerated migration toward per-inspection pricing arrangements.
India
Electronics manufacturing subsidies under the PLI scheme attract component suppliers needing automated quality assurance for smartphone assembly export compliance. BIS certification requirements shape procurement specifications for imported inspection systems. Tamil Nadu and Karnataka industrial corridors integrate vision systems into new assembly capacity.
AI Industrial Defect Detection Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier structure. Direct sales engineering relationships dominate specification conversations with automotive Tier-1 suppliers. Three archetypes prevail: embedded vision software platforms, hardware-integrated system vendors, and subscription-based SaaS providers. Competitive moves concentrate on strategic partnerships for regulatory pre-certification and geographic expansion through localized sales engineering.
Within the embedded software tier, Cognex Corporation and Keyence Corporation occupy anchor positions. Cognex leverages subscription-based platform licensing to sustain recurring revenue streams. Keyence anchors its market presence through direct sales engineering teams that control technical specification conversations. Both exemplify the shift toward asset-light procurement models displacing traditional capital purchase arrangements among automotive suppliers.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Omron Corporation |
| Teledyne Technologies |
| Basler AG |
| SICK AG |
| Siemens AG |
| ABB |
| ZEISS |
| Others |
Pricing and Supply Chain Analysis
Taiwan's semiconductor foundry capacity dynamics directly shape downstream pricing power for edge computing modules powering defect detection systems, with GPU accelerator lead times stretching procurement timelines and compressing margins for vision system OEMs serving automotive and electronics manufacturers.
Pricing Analysis
Certification level creates the primary spread across deployment tiers, with FDA-grade and EU AI Act-conformant systems commanding substantial premiums over uncertified alternatives. Subscription-based SaaS licensing is displacing perpetual hardware sales among mid-sized manufacturers seeking zero-CAPEX procurement. Price differentiation hinges on validation documentation depth and embedded software capability tiers. Margins are tightening in the standard hardware segment due to Taiwan foundry capacity constraints inflating accelerator costs. Quality assurance laboratories exhibit lowest price sensitivity given their centralized model retraining revenue models, while commodity electronics assemblers face acute cost pressure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure procurement relationships between automotive Tier-1 suppliers and vision system vendors, with 90-day cycles becoming standard. Manufacturing concentration centers on Taiwan for inference accelerators, Germany for precision optics, and Japan for industrial camera sensors. Component dependencies include CMOS image sensors, short-wave infrared detectors, and FPGA-based processing units. Single-source vulnerability in Taiwan-based GPU foundry exposure presents acute disruption risk for edge computing deployments. Distribution runs through direct sales engineering teams controlling specification conversations with automotive OEMs and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from low-code vision platforms and commoditized open-source detection models that threaten to erode proprietary software value capture across mid-market manufacturing segments.
For Market Incumbents: Build regulatory certification moats by pre-qualifying platforms through EU notified bodies and FDA QSR pathways before competitors complete documentation cycles. Anchor customer relationships through embedded software subscriptions that increase switching costs. Deepen backward integration into edge accelerator design to reduce Taiwan foundry dependency exposure. Prioritize direct sales engineering presence in Germany's automotive supply base where specification authority concentrates.
For New Entrants and Emerging Players: Build out SaaS-based model retraining services targeting quality assurance laboratories serving distributed supplier networks, the most penetrable segment given incumbent underinvestment in recurring revenue architectures. Target India's PLI-subsidized electronics manufacturing corridors where automated inspection demand outpaces established vendor coverage. Pursue channel partnerships with regional system integrators lacking in-house AI development capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical software play because embedded vision platforms with regulatory pre-certification and subscription revenue streams command durable competitive positioning. Target acquisition candidates with established EU AI Act conformity documentation and direct sales engineering relationships in automotive supply chains. Monitor GPU foundry capacity utilization rates as the critical inflection signal for margin compression timing across hardware-integrated vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EU AI Act conformity documentation accelerates deployment timelines for aerospace and automotive OEMs. |
| Embedded Software Subscription Migration | Recurring revenue models displace capital sales among automotive Tier-1 suppliers seeking operational expenditure treatment. |
| Edge Accelerator Backward Integration | In-house FPGA and ASIC design reduces Taiwan foundry dependency for inference module procurement. |
| Quality Assurance Laboratory SaaS Targeting | Centralized model retraining services capture margin pools in distributed supplier network certification. |
| India PLI Corridor Geographic Expansion | Electronics manufacturing subsidies create automated inspection demand exceeding incumbent vendor coverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quality assurance directors at automotive Tier-1 suppliers, machine vision system engineers at electronics foundries, regulatory affairs specialists at pharmaceutical manufacturers, and procurement leads at contract electronics manufacturers. Secondary validation drew from FDA computer-assisted device guidance documents, EU AI Act implementing acts, SAMR technical standards filings, SEC 10-K disclosures from listed vision system vendors, and customs trade data for industrial camera imports. Bottom-up segment sizing triangulated against top-down manufacturing output intensity metrics across the analysis window.
Calibration against historical deployment trajectories in electronics assembly and automotive component inspection anchored the analytical framework. Segmentation dimensions modeled include inspection modality, deployment architecture, manufacturing application, and end-user procurement authority. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs encompassed semiconductor capital expenditure cycles, regulatory compliance deadline schedules, and automotive platform refresh timelines.
Practitioners should monitor GPU foundry capacity utilization, EU AI Act enforcement precedence, and PLI scheme disbursement velocity for early signals of forecast deviation. Forecasts reflect assumptions regarding continued regulatory tightening, sustained electronics manufacturing migration to India and Southeast Asia, and stable Taiwan semiconductor supply. Macroeconomic contraction in capital equipment procurement, abrupt GPU supply disruption, or harmonized global AI regulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market