
 Emotion AI Software Market | 2026-2036
Emotion AI Software Market Size, Share, and Industry Trends Forecast 2026-2036
Emotion AI Software Market Insights
The EU AI Act is hardening compliance thresholds for biometric emotion recognition systems deployed in workplace and educational settings. Microsoft leverages its Azure cloud infrastructure to anchor enterprise-grade sentiment analysis services across regulated industries. Google competes through deep integration of facial affect detection within its video conferencing and collaboration stack. Amazon extends its reach by embedding emotion analytics into Alexa developer tools and customer service automation workflows.
Emotion AI software comprises computational systems that infer human emotional states from multimodal inputs including facial micro-expressions, vocal prosody, physiological signals, and linguistic patterns, typically processing data through convolutional neural networks or transformer architectures to output categorical or dimensional affect labels. The primary commercial purpose centers on enhancing human-machine interaction quality, optimizing customer experience workflows, and enabling real-time behavioral adaptation in safety-critical environments such as automotive cockpits and clinical mental health monitoring. Cloud-based deployment dominates current revenue flows due to scalability advantages for enterprise video and voice analytics, while edge computing configurations grow fastest where latency constraints govern automotive and wearable use cases. Healthcare applications command premium pricing for diagnostic support and patient engagement, whereas retail sentiment tracking matures into a commoditized layer within broader customer data platforms.
The US Food and Drug Administration evaluates clinical decision-support tools incorporating emotion recognition for mental health screening, while the Federal Trade Commission scrutinizes claims around biometric data handling under Section 5 unfair practices authority. The European Medicines Agency and national data protection authorities coordinate on whether affective computing outputs constitute protected health information under GDPR and MDR frameworks. Stakeholders must decide whether to architect compliance-first systems for transatlantic deployment or pursue region-specific product variants that trade interoperability for faster certification pathways.
Market Dynamics
The EU AI Act's biometric identification restrictions are compressing deployment timelines for workplace emotion recognition systems, forcing vendors to re-architect cloud-to-edge data flows and consent mechanisms before the 2026 enforcement window closes.
Growth Catalysts
- Automotive Safety Mandates:Driver monitoring systems detect fatigue and distraction through facial micro-expression analysis. EU vehicle safety regulations now require such systems in new passenger car models.
- GDPR Article 9 Processing Frameworks:Affective computing outputs in clinical settings gain clearer lawful basis for processing special category data. Healthcare providers in Germany and France accelerate procurement of diagnostic support tools.
- Convolutional Neural Network Compression:Edge-optimized architectures enable real-time inference on automotive SoCs and wearable processors. Latency constraints in safety-critical cockpits drive silicon-level integration partnerships.
Market Restraints
- Annotated Training Data Scarcity:Cross-cultural emotional expression databases remain concentrated in Western populations. Model performance degrades significantly for East Asian and African demographic segments.
- Biometric Data Storage Costs:GDPR and state-level privacy laws mandate encrypted retention with strict purpose limitation. Enterprise cloud storage expenditures for voice and video archives scale non-linearly with deployment breadth.
- Physiological Signal Substitution:Wearable heart rate variability and galvanic skin response devices provide discrete emotional state proxies without facial processing. Privacy-conscious buyers in Scandinavian markets prefer sensor-based alternatives.
Strategic Opportunities
- Brazilian Mental Health Infrastructure:ANVISA regulatory pathways for software-as-medical-device remain less congested than FDA or EMA routes. Domestic telehealth platforms seek embedded screening tools for anxiety and depression.
- Transformer-Large Language Model Convergence:Multimodal architectures fuse linguistic sentiment with prosodic and visual cues in single inference graphs. Unified pipelines reduce integration complexity for enterprise contact center platforms.
- API-First Distribution Models:Emotion recognition capabilities embed as microservices within broader customer experience orchestration suites. Independent software vendors access affective computing without building proprietary models.
Industry Challenges
- Cross-Functional Talent Scarcity:Product teams require simultaneous expertise in affective neuroscience, edge optimization, and GDPR Article 35 data protection impact assessments. Compensation premiums for this intersection exceed standard machine learning engineering rates.
- ISO/IEC 27001 Certification Timelines:Enterprise buyers mandate information security management system accreditation for biometric data processors. Audit backlogs at accredited bodies extend vendor sales cycles by four to six months.
- Legacy Call Center Integration Friction:Real-time emotion analytics insertion into existing interactive voice response architectures requires custom middleware development. On-premise telephony estates in financial services resist cloud-native API substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emotion AI Software Market |
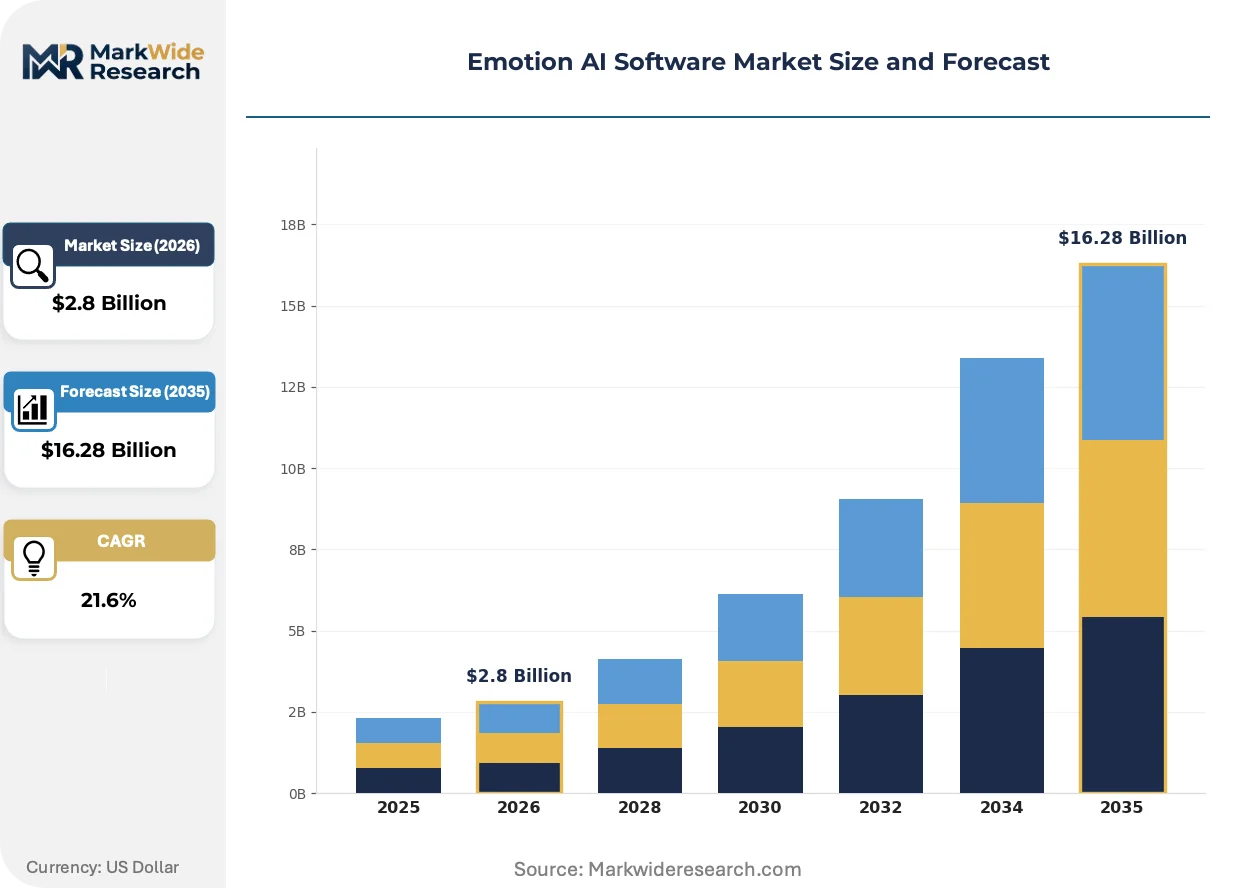
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Healthcare, Banking, Retail, Education End User: Enterprises, Developers, Researchers, Consumers Technology: Machine Learning, Natural Language Processing, Facial Recognition, Emotion Detection |
| Companies Covered | IBM, Microsoft, Google, Amazon, Smart Eye, Uniphore, Realeyes, Affectiva, Tobii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emotion AI Software Market Trends and Innovations
Multimodal transformer architectures are displacing single-modality convolutional pipelines as the dominant processing paradigm, compressing development cycles for vendors while raising inference compute requirements and reshaping cloud procurement patterns among enterprise buyers.
Edge-optimized emotion recognition SDKs are modularizing into discrete functional blocks for facial landmark detection, voice feature extraction, and fusion inference. Tier-1 automotive suppliers integrate these components into domain controller software stacks rather than sourcing monolithic solutions. This modularity is compressing supplier switching costs and enabling mixed-vendor cockpit architectures.
The EU AI Act's prohibition on emotion recognition in educational and workplace settings entered force in February 2025. Vendors serving European enterprise clients must implement technical measures preventing deployment in prohibited contexts. Healthcare and automotive safety applications receive explicit exemptions, concentrating vendor compliance investment on clinical decision support and driver monitoring product lines.
Subscription-based API consumption is displacing perpetual license models for enterprise sentiment analytics. Chief information officers prefer operational expenditure alignment with contact center volume fluctuations. This shift is most visible in United States financial services and telecommunications verticals, where seasonal call volume spikes render fixed-capacity licensing economically inefficient.
Emotion AI Software Market Segmentation
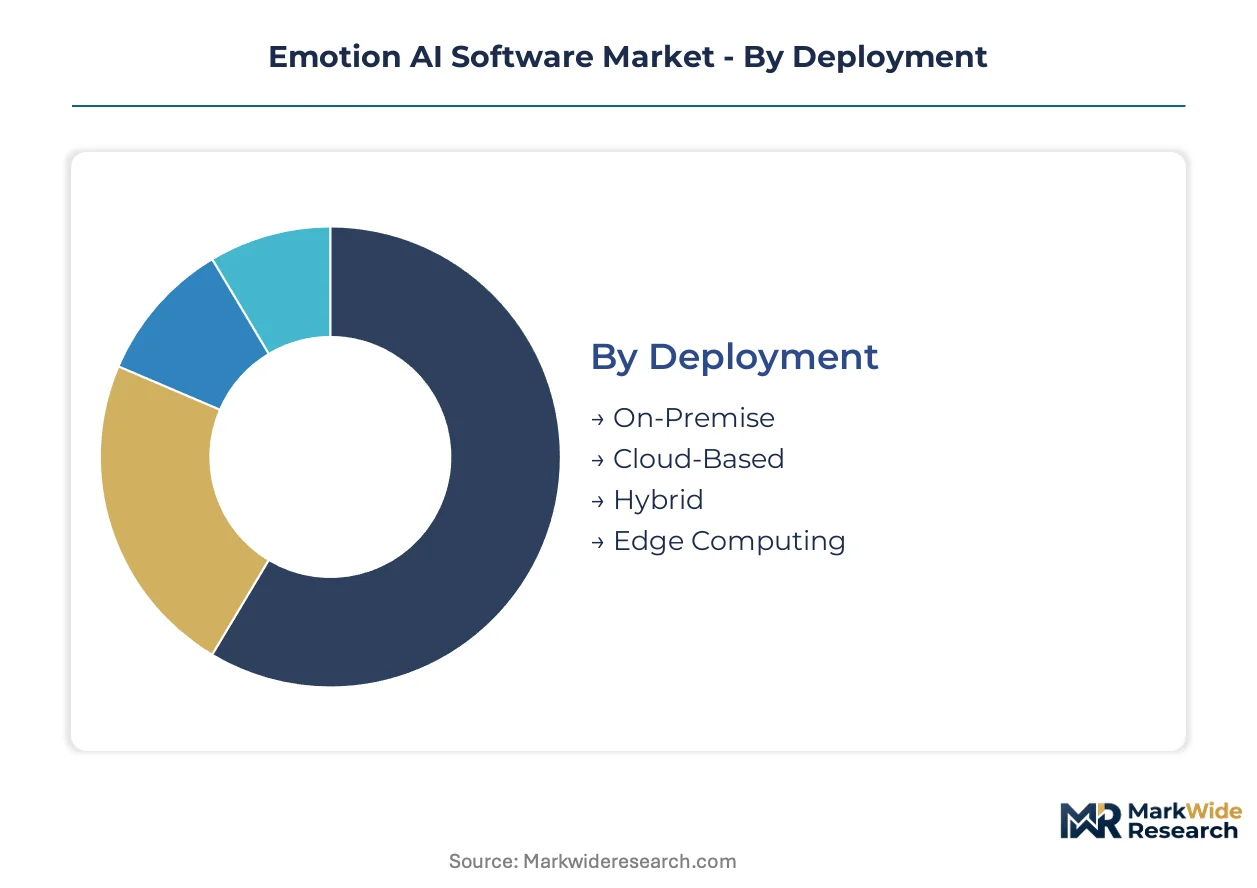
Emotion AI software architectures diverge sharply across deployment modalities, end-use contexts, and technical foundations. Each segmentation axis carries distinct regulatory exposure, margin profiles, and integration complexity that reshape vendor go-to-market strategies.
Deployment:
Customization versus standardization tensions peak in deployment architecture, where latency requirements collide with data sovereignty mandates and total cost of ownership constraints.
- On-Premise:Fully contained inference environments within enterprise data centers or colocation facilities. Financial services institutions in Frankfurt and Singapore favor this model for voice analytics archives subject to GDPR and Monetary Authority of Singapore data localization rules.
- Cloud-Based:Scalable API consumption through hyperscaler infrastructure with centralized model training pipelines. US contact center platforms dominate procurement, driven by seasonal volume elasticity and preference for operational expenditure alignment.
- Hybrid:Split architectures processing sensitive biometric data locally while leveraging cloud resources for model updates and aggregate analytics. German automotive manufacturers deploy this configuration to satisfy both EU AI Act edge-processing requirements and centralized fleet learning objectives.
- Edge Computing:Real-time inference on device-local silicon with sub-100 millisecond response guarantees. Leading the category by volume: Cloud-Based. Growing fastest: Edge Computing.
Edge Computing climbs the fastest as automotive safety mandates and wearable health monitoring compress latency tolerances below cloud round-trip thresholds.
Application:
Regulatory maturity and reimbursement pathways fragment commercial viability across vertical use cases, with clinical settings commanding premium pricing despite certification friction.
- Healthcare:Diagnostic support tools for mental health screening and patient engagement monitoring. FDA evaluation pathways for clinical decision-support applications create extended validation timelines that filter vendor participation to well-capitalized developers.
- Banking:Voice biometrics and sentiment analysis for fraud detection and customer service optimization. Brazilian retail banks accelerate procurement following Central Bank of Brazil open banking mandates that increase digital channel transaction volumes.
- Retail:In-store facial affect tracking and e-commerce sentiment analysis. Privacy litigation exposure in Illinois under Biometric Information Privacy Act constrains US deployment breadth.
- Education:Student engagement monitoring and adaptive learning systems. EU AI Act prohibitions on emotion recognition in educational settings force product line pivots toward jurisdictions without equivalent restrictions.
Healthcare captures the highest average contract value. Banking demonstrates the steepest expansion trajectory as open banking protocols proliferate across Latin America and Southeast Asia.
End User:
Technical sophistication and procurement authority concentrate demand patterns, with enterprise buyers prioritizing integration depth while developer segments drive API ecosystem expansion.
- Enterprises:Large-scale deployments across customer experience, workforce safety, and compliance monitoring functions. Tier-1 automotive suppliers and multinational telecommunications carriers represent the dominant procurement concentration.
- Developers:SDK and API consumption for embedded emotion recognition in third-party applications. Independent software vendors in India and Poland leverage these tools to accelerate product development without proprietary model investment.
- Researchers:Academic and clinical study applications requiring annotated datasets and experimental architectures. Funding from National Institutes of Health and European Research Council sustains demand despite limited commercial scale.
- Consumers:Direct-to-user applications in wellness coaching and personal productivity. Privacy-conscious Scandinavian markets show strongest adoption for sensor-based alternatives that bypass facial processing.
Enterprises account for the dominant revenue share. Developers gain share fastest as API-first distribution models lower technical barriers to entry.
Technology:
Processing paradigm selection determines computational requirements, training data dependencies, and explainability obligations under emerging algorithmic accountability frameworks.
- Machine Learning:Supervised and unsupervised learning pipelines for pattern recognition across multimodal inputs. Convolutional neural network compression techniques enable automotive SoC deployment while maintaining inference accuracy.
- Natural Language Processing:Linguistic sentiment extraction and prosodic feature analysis from text and voice data. Transformer-large language model convergence fuses textual and acoustic cues in unified inference graphs.
- Facial Recognition:Landmark detection and micro-expression classification from video streams. Illinois BIPA and EU GDPR Article 9 special category processing requirements impose consent and retention burdens that elevate compliance costs.
- Emotion Detection:Multimodal fusion architectures integrating physiological, vocal, and visual signal streams. ISO/IEC 27001 certification mandates from enterprise buyers extend sales cycles for biometric data processors.
Machine Learning holds the largest installed base. Natural Language Processing expands most quickly as contact center platforms demand unified sentiment pipelines across chat, voice, and email channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in California and Massachusetts concentrate venture deployment for affective computing startups. Tax-advantaged R&D credits in these jurisdictions accelerate commercialization timelines for multimodal emotion recognition platforms.
United States
FDA evaluation pathways for clinical decision-support tools drive healthcare procurement concentration. FTC Section 5 enforcement scrutinizes biometric data handling claims. Boston and San Francisco Bay Area clusters host the dominant share of venture-backed affective computing developers.
Germany
KBA automotive safety mandates require driver monitoring systems in new passenger vehicles. EU AI Act edge-processing requirements force re-architecting of cloud-to-edge data flows. Stuttgart and Munich industrial corridors concentrate Tier-1 supplier integration partnerships.
United Kingdom
Open banking protocols expand digital channel transaction volumes for voice analytics procurement. Information Commissioner's Office guidance on biometric data retention elevates compliance investment. London financial services sector dominates enterprise sentiment analytics adoption.
Japan
METI funding for human-machine interface research sustains academic-commercial partnerships. PMDA regulatory frameworks for software-as-medical-device create certification pathways for mental health screening tools. Tokyo and Osaka metropolitan areas concentrate automotive cockpit system development.
Brazil
ANVISA regulatory pathways for software-as-medical-device remain less congested than FDA or EMA routes. Central Bank of Brazil open banking mandates increase digital channel volumes for sentiment analytics. São Paulo telehealth platforms seek embedded screening tools for anxiety and depression.
Emotion AI Software Market Competitive Landscape
United States technology conglomerates anchor one tier; European automotive specialists and Asian semiconductor-integrated developers hold differentiated positions. The market structure consolidates around cloud infrastructure providers with multimodal AI capabilities, while niche vendors concentrate on edge-optimized automotive safety systems. Three archetypes dominate: hyperscaler platform operators, automotive Tier-1 embedded software suppliers, and API-first developer tool providers. Competitive moves center on strategic partnerships for silicon-level integration and geographic expansion into regulatory-favorable jurisdictions.
Within the hyperscaler tier, Microsoft leverages Azure infrastructure for enterprise sentiment services, Google integrates facial affect detection within collaboration platforms, and Amazon embeds emotion analytics into voice assistant developer tools. These three exemplify the platform-operator archetype, each anchoring distinct distribution vectors across cloud, productivity software, and consumer device ecosystems. European specialists including Smart Eye and Tobii occupy positions in automotive safety and attention-tracking segments, representing the embedded-systems archetype with direct Tier-1 supplier relationships.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon |
| Smart Eye |
| Uniphore |
| Realeyes |
| Affectiva |
| Tobii |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive suppliers and multinational contact center operators concentrate procurement authority, anchoring subscription-based SaaS pricing for cloud-deployed emotion analytics while edge-computing safety systems command project-based premiums for automotive integration.
Pricing Analysis
Short lead-time delivery for ISO/IEC 27001-certified edge SDKs commands 15-25% premiums over standard-cycle procurement, while surplus cloud API capacity trades at spot discounts during seasonal demand troughs. Pricing stratifies across premium, standard, and economy tiers differentiated by model training data breadth and GDPR Article 35 documentation depth. Cost compression in cloud-based sentiment analytics intensifies as hyperscaler platform competition erodes per-call margins. Developer segments exhibit highest price sensitivity, whereas healthcare diagnostic support buyers prioritize certification completeness over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and US financial services institutions require qualified secondary suppliers for facial landmark detection and voice feature extraction modules. Silicon design concentrates in Taiwan, South Korea, and the United States, while labeled training data annotation clusters in India, Poland, and the Philippines. The supply chain rests on GPU accelerator availability, specialized image sensor arrays, and cross-cultural emotional expression datasets. Single-source vulnerability in transformer model training infrastructure poses structural risk. Distribution runs through hyperscaler marketplaces, direct Tier-1 supplier integration, and API-first developer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's biometric prohibition framework erects a compliance moat that rewards pre-certified vendors with accelerated procurement access across European healthcare and automotive safety verticals.
For Market Incumbents: Acquire edge-optimized neural network compression IP to defend against silicon-integrated entrants from Asian semiconductor ecosystems. Pursue backward integration into automotive SoC design partnerships to lock in driver monitoring system sockets. Deepen GDPR Article 35 documentation capabilities to exploit certification backlogs that delay competitor sales cycles. For New Entrants and Emerging Players: Brazilian telehealth platforms and ANVISA-qualification pathways represent the most penetrable regulatory entry point for clinical decision-support tools. Target Scandinavian wearable sensor markets where privacy-conscious buyers reject facial processing modalities. Lead with API-first distribution through existing customer experience orchestration suites rather than building proprietary model infrastructure. For Investors and Strategic Acquirers: The window for entry favors edge-computing specialists with automotive Tier-1 supplier relationships and ISO 27001 accreditation already in place. Long-term viability hinges on multimodal transformer architecture ownership as convolutional pipelines face displacement. Watch for EU AI Act enforcement actions against non-compliant workplace emotion recognition deployments as the inflection signal for compliance-first vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EU AI Act and FDA pre-certification create defensible procurement access in healthcare and automotive verticals. |
| Silicon-Level Integration Partnership | Domain controller embedding with NVIDIA and Qualcomm automotive platforms locks in driver monitoring system volumes. |
| API-First Developer Platform Launch | Microservices distribution through hyperscaler marketplaces captures independent software vendor demand without direct sales investment. |
| Cross-Cultural Training Data Acquisition | East Asian and African emotional expression databases address model performance gaps that constrain geographic expansion. |
| Hybrid Cloud-Edge Architecture Deployment | Split processing configurations satisfy German automotive data sovereignty requirements while enabling centralized fleet learning. |
Research Methodology
Document review covered regulatory filings with the FDA, EMA, and ANVISA, complemented by interviews with emotion AI product executives, Tier-1 automotive supplier procurement leads, healthcare CIOs, and contact center platform engineers. Secondary validation drew from EU AI Act implementation guidance, SEC 10-K hyperscaler disclosures, and KBA automotive safety mandate documentation. Bottom-up deployment volume estimates triangulated against top-down cloud infrastructure capex allocations and edge computing silicon shipment data.
Historical revenue trajectories were cross-referenced against expert panel inputs from platform engineering directors and biometric data protection officers. The analytical framework modeled deployment modality, application vertical, end-user sophistication tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level elasticity analysis and technology substitution curve fitting. Forecast inputs incorporated automotive safety mandate compliance deadlines and open banking protocol proliferation rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and transformer model compute cost trajectories. Deviation in GDPR special category processing interpretations or FDA clinical decision-support classification thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market