
 Global Voice Assistant Application Market | 2026-2036
Global Voice Assistant Application Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voice Assistant Application Market Foresight
A shortage of conversational AI engineers is rotating talent competition toward platform-native specialists with dual expertise in linguistics and edge computing. Google LLC leverages its Tensor Processing Unit infrastructure to sustain low-latency inference at scale. Amazon Web Services anchors enterprise adoption through Alexa for Business integrations across hospitality and healthcare workflows. Apple Inc. differentiates by controlling on-device neural engine pipelines that limit cloud data exposure.
Voice assistant applications process spoken language through acoustic modeling, natural language understanding, and dialogue management layers to execute commands or retrieve information without manual input. Speech recognition accuracy thresholds above 95 percent in noisy environments now determine commercial viability for automotive and industrial deployments. Natural Language Processing occupies the largest technology investment pool as enterprises demand multi-turn contextual conversations rather than transactional command-response loops. Banking Assistants represent the fastest-expanding application segment as financial institutions replace interactive voice response systems with AI agents capable of authentication and transaction execution.
The Federal Communications Commission governs spectrum allocation for voice-enabled IoT devices in the United States, while the EU AI Act imposes risk-classification obligations on biometric identification and emotion recognition systems deployed through voice interfaces. China's Ministry of Industry and Information Technology enforces GB standards for speech data collection and algorithmic recommendation services, creating divergent compliance architectures for multinational platform providers. Stakeholders must monitor whether emerging national AI sovereignty frameworks fragment cloud deployment strategies or accelerate edge-native architectures that localize inference and data residency.
Market Dynamics
The EU AI Act's risk-classification obligations for biometric identification systems are forcing platform providers to rearchitect cloud deployment strategies around edge-native inference pipelines that localize data residency.
Growth Catalysts
- Automotive infotainment integration:Voice-enabled cabin control systems in electric vehicles are displacing physical interface layers. OEMs in Germany and the United States are mandating hands-free operation for safety compliance.
- FCC spectrum allocation:The Federal Communications Commission's prioritization of low-latency bands for voice-enabled IoT devices accelerates industrial deployment in warehouse automation and field service workflows.
- Banking IVR replacement:Financial institutions are retiring legacy interactive voice response infrastructure in favor of AI agents capable of real-time authentication and transaction execution.
Market Restraints
- Conversational AI engineer scarcity:The shortage of specialists combining linguistics and edge computing expertise concentrates hiring competition among platform-native providers.
- GB standard divergence:China's Ministry of Industry and Information Technology enforces speech data collection protocols that conflict with GDPR and EU AI Act requirements, fragmenting multinational compliance architectures.
- Noisy-environment accuracy thresholds:Speech recognition systems must achieve 95 percent accuracy in industrial acoustic conditions, a technical barrier that excludes lower-tier acoustic modeling approaches.
Strategic Opportunities
- Healthcare workflow penetration:HIPAA-compliant voice interfaces for clinical documentation remain underdeployed in United States ambulatory care settings.
- On-device neural engine convergence:The intersection of tensor processing units and localized inference pipelines enables privacy-preserving deployment in European markets subject to GDPR data minimization mandates.
- Hospitality service automation:Alexa for Business integrations in hotel operations represent a channel innovation expanding beyond enterprise headquarters into guest-facing service layers.
Industry Challenges
- Multi-turn dialogue management complexity:Enterprise buyers demand contextual conversation capabilities that exceed transactional command-response loops, stretching natural language understanding team capacity.
- Algorithmic transparency documentation:EU AI Act conformity assessments require technical documentation of emotion recognition system logic that many providers have not architected for auditability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voice Assistant Application Market |
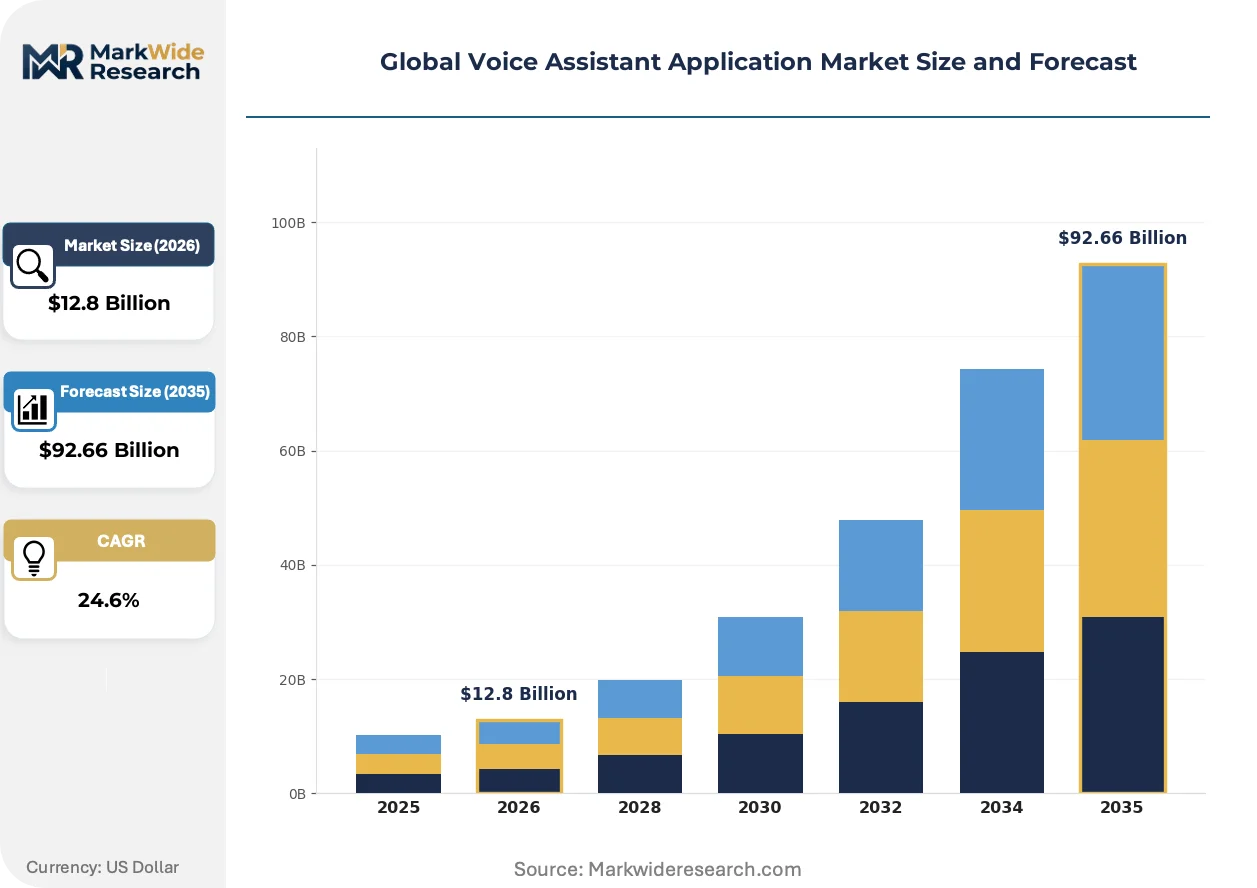
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $92.66 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Speech Recognition, Machine Learning, Text-to-Speech, Voice Biometrics Application: Smart Homes, Automotive Infotainment, Customer Support, Education, Banking Assistants End User: Individual Consumers, Enterprises, Government Agencies, Educational Institutions, Financial Services Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Google LLC, Amazon Web Services, Apple Inc., Microsoft Corporation, Baidu Inc., Samsung Electronics, IBM Corporation, Nuance Communications, Alibaba Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voice Assistant Application Market Shifts & Advancements
Natural language processing investment is rotating toward multi-turn contextual capabilities as enterprises reject transactional voice interfaces. Platform providers are competing on inference latency and data residency architecture rather than acoustic modeling accuracy alone.
Edge-native neural engine deployment is decomposing cloud-centric voice assistant architectures. Automotive OEMs and industrial equipment manufacturers are adopting on-device inference pipelines to eliminate network dependency. This technology shift compresses cloud infrastructure spending while enabling operation in bandwidth-constrained environments.
The EU AI Act's biometric identification risk classification is restructuring vendor compliance roadmaps. Providers must now maintain technical documentation and human oversight protocols for emotion recognition systems deployed through voice interfaces. European automotive and financial services verticals are prioritizing suppliers with pre-established conformity assessment frameworks.
Buyer procurement criteria are elevating data residency guarantees above feature parity. German automotive manufacturers and United States healthcare systems are specifying edge-only inference in RFP requirements. This specification shift favors platform providers with tensor processing unit infrastructure and captive silicon design capabilities.
Global Voice Assistant Application Market Segmentation
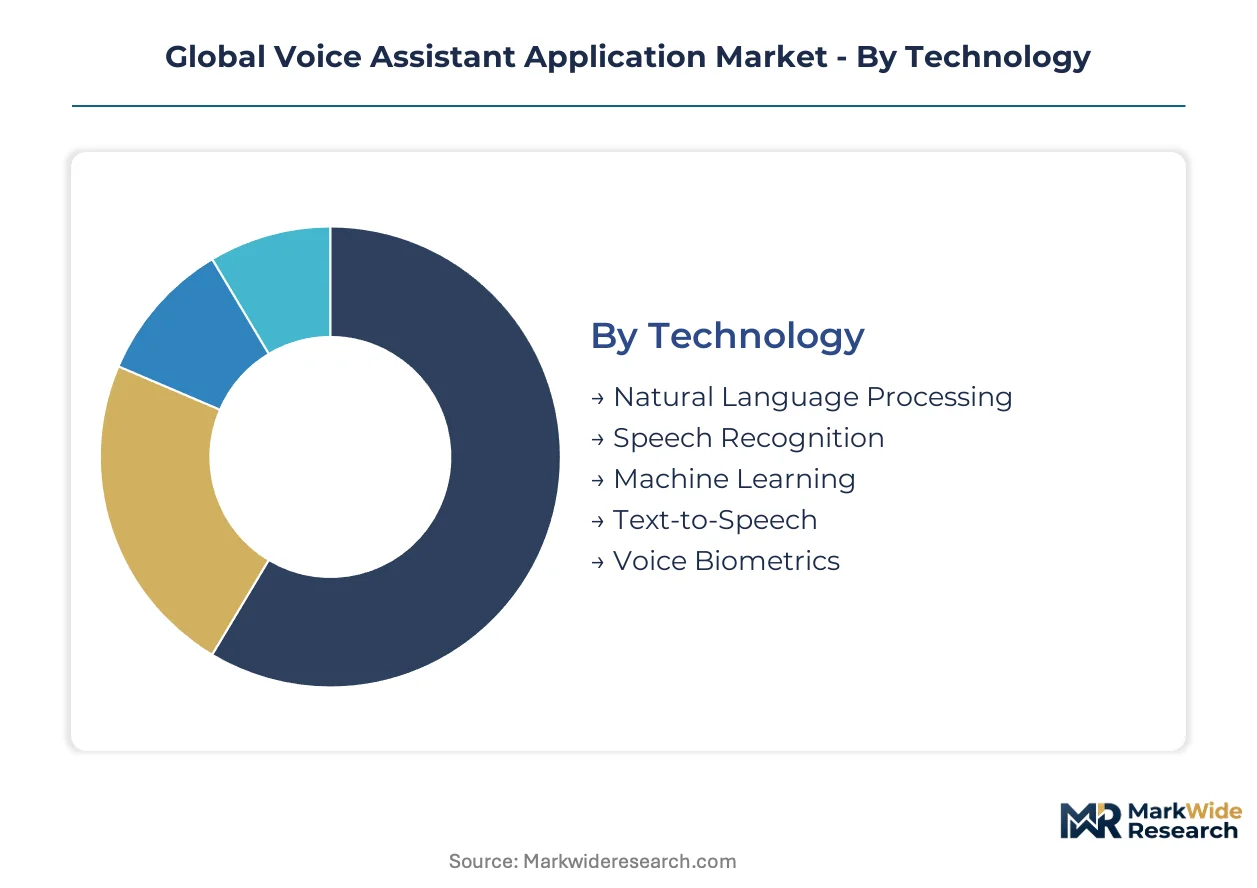
Segmentation in voice assistant applications reveals how technical architecture, deployment constraints, and end-use requirements fragment vendor strategies. Substitution pressures vary sharply across layers, with some technologies facing displacement from multimodal interfaces while others deepen moats through regulatory compliance.
Technology:
Natural Language Processing faces the most acute substitution threat as large language models commoditize foundational capabilities, while Voice Biometrics strengthens its defensive position through EU AI Act risk-classification requirements.
- Natural Language Processing:Core engine for intent classification, entity extraction, and dialogue state tracking. Demand concentrates in United States banking and German automotive verticals where multi-turn contextual conversations replace transactional command-response systems.
- Speech Recognition:Acoustic modeling pipeline converting audio signals to phonetic representations. United States warehouse automation and Japanese manufacturing workflows drive specifications above 95 percent accuracy in noisy environments.
- Machine Learning:Training infrastructure for model optimization and personalization.
- Text-to-Speech:Neural vocoder systems generating naturalistic voice output.
- Voice Biometrics:Speaker identification and verification through vocal characteristic analysis. EU AI Act biometric identification risk classification mandates technical documentation and human oversight protocols, creating compliance moats for established providers.
Natural Language Processing anchors the volume base while Voice Biometrics gains share at the steepest rate.
Application:
Cost tier stratification separates premium integrated cabin systems from commoditized smart home devices, with middleware pricing collapsing in the middle.
- Banking Assistants:AI agents replacing interactive voice response infrastructure with real-time authentication and transaction execution. United States financial institutions lead deployment as regulatory pressure mounts on legacy IVR security gaps.
- Automotive Infotainment:Hands-free cabin control systems mandated by German and United States safety regulations for electric vehicle platforms. OEM procurement specifies edge-only inference to eliminate cloud dependency during operation.
- Smart Homes:Consumer voice control for lighting, climate, and entertainment systems.
- Customer Support:Enterprise virtual assistants handling tier-one inquiry resolution.
- Education:Language learning and accessibility tools for institutional deployment.
Smart Homes anchors the volume base while Banking Assistants climbs the fastest as financial IVR replacement accelerates.
End User:
Customer type divergence splits procurement between consumer feature parity and enterprise compliance architecture, with government requirements tightening most rapidly.
- Financial Services:Institutions demanding HIPAA-grade data residency and SOC 2 Type II audit trails for voice-enabled transaction systems. United States regional banks and German cooperative banking networks specify on-premise or edge-only deployment.
- Government Agencies:National security and public service applications with classified data handling requirements. China's GB standards for speech data collection and the EU AI Act create incompatible compliance architectures for multinational vendors.
- Individual Consumers:Mass-market smart speaker and mobile assistant users.
- Enterprises:Cross-industry virtual assistant deployments for productivity and workflow automation.
- Educational Institutions:Campus-wide accessibility and administrative voice interfaces.
Individual Consumers anchors the volume base while Government Agencies expands most quickly through sovereign AI procurement mandates.
Deployment:
Supply concentration in tensor processing unit infrastructure favors cloud-native providers, though edge computing is fragmenting this dominance through automotive and industrial verticalization.
- Edge Computing:On-device neural engine pipelines localizing inference and data residency. German automotive manufacturers and United States healthcare systems specify edge-only architectures in RFP requirements to satisfy GDPR data minimization mandates.
- Cloud-Based:Centralized inference infrastructure leveraging hyperscale tensor processing unit deployments. Hospitality and retail workflows in the United States remain concentrated here due to lower latency sensitivity.
- Hybrid:Split architectures routing sensitive operations to edge and general queries to cloud.
- On-Premises:Captive infrastructure for classified or air-gapped environments.
Cloud-Based anchors the volume base while Edge Computing shows the steepest expansion trajectory as data residency guarantees dominate procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Voice assistant consumption patterns diverge sharply across geographies. United States buyers prioritize smart speaker density and enterprise virtual assistant deployment, while German automotive OEMs mandate edge-only inference architectures for cabin systems.
United States
Smart speaker penetration and enterprise Alexa for Business integrations drive demand in hospitality and healthcare workflows. The FCC governs spectrum allocation for voice-enabled IoT devices, enabling low-latency industrial deployment. Silicon Valley clusters anchor cloud-native infrastructure development while Boston healthcare systems specify HIPAA-compliant edge architectures.
Germany
Automotive infotainment mandates for hands-free electric vehicle operation concentrate procurement among OEMs. The EU AI Act imposes risk-classification obligations on biometric identification systems deployed through voice interfaces. Stuttgart and Munich manufacturing corridors specify edge-only inference to satisfy GDPR data minimization requirements.
China
Smart home device manufacturing and domestic platform development sustain volume demand. The Ministry of Industry and Information Technology enforces GB standards for speech data collection and algorithmic recommendation services. Shenzhen hardware ecosystems and Beijing AI research clusters drive localized supply chain concentration.
United Kingdom
Banking IVR replacement and customer service automation accelerate enterprise adoption. GDPR and emerging AI governance frameworks shape procurement compliance requirements. London financial services clusters and Manchester technology corridors drive regional deployment concentration.
Japan
Automotive voice interfaces and industrial warehouse automation sustain specialized demand. METI standards and JIS certification requirements structure vendor qualification protocols. Nagoya manufacturing belts and Tokyo enterprise technology markets anchor sub-regional adoption patterns.
Global Voice Assistant Application Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in voice assistant applications. Hyperscale cloud providers with captive silicon design capabilities control tensor processing unit infrastructure and low-latency inference pipelines. Specialist vendors concentrate in voice biometrics and automotive edge-native deployment. Dominant competitive moves include strategic partnerships with automotive OEMs and healthcare systems, plus portfolio diversification into on-device neural engine architectures.
Within the integrated platform tier, Google LLC and Amazon Web Services exemplify hyperscale infrastructure deployment, while Apple Inc. occupies a position emphasizing on-device privacy architecture. Chinese technology conglomerates including Baidu Inc. and Alibaba Group represent sovereign-market platform development. Samsung Electronics anchors consumer electronics integration across smart home and mobile device ecosystems.
| Leading Market Players |
|---|
| Google LLC |
| Amazon Web Services |
| Apple Inc. |
| Microsoft Corporation |
| Baidu Inc. |
| Samsung Electronics |
| IBM Corporation |
| Nuance Communications |
| Alibaba Group |
| Others |
Supply & Pricing Matrix
Tensor processing unit infrastructure concentration in hyperscale cloud facilities creates scale economies that compress price floors for voice assistant inference services while elevating barriers for second-tier acoustic modeling providers. German automotive OEMs and United States healthcare systems now specify edge-only deployment in procurement requirements, fragmenting pricing power between centralized cloud tiers and localized neural engine architectures.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement for banking and automotive verticals, while spot-based consumption persists in hospitality and retail workflows. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant edge deployments from cloud-native API tiers and open-source acoustic pipelines. Cost compression in mid-market cloud inference is intensifying because large language model commoditization erodes natural language processing differentiation. Financial services buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while smart home device manufacturers face acute margin pressure from commoditized smart speaker competition.
Supply Chain Analysis
Inventory lead times for tensor processing units extend 12-18 weeks, constraining capacity allocation among automotive OEMs and cloud hyperscalers competing for captive silicon. Supply concentrates in Taiwan semiconductor foundries, South Korea memory fabrication, and United States neural engine design houses. Raw material dependencies span advanced lithography equipment, high-bandwidth memory modules, and rare earth elements for magnetics in acoustic sensors. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure for edge-native inference chip production. Distribution runs through direct OEM partnerships for automotive and healthcare verticals, with channel partners handling smart home and retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Voice Assistant Application Market represents a high-growth disruption driven by EU AI Act biometric identification risk classifications that restructure vendor compliance roadmaps and procurement criteria simultaneously.
For Market Incumbents: Consolidate tensor processing unit infrastructure advantages through exclusive foundry partnerships in Taiwan and South Korea, while acquiring voice biometrics specialists to pre-position conformity assessment frameworks ahead of EU AI Act enforcement. Threat substitution from open-source large language models erodes natural language processing moats; defensive vertical integration into on-device neural engine design preserves margin structure in European automotive and United States healthcare verticals. For New Entrants and Emerging Players: Healthcare workflow penetration in United States ambulatory care settings offers a service-layer gap where HIPAA-compliant clinical documentation interfaces remain underdeployed relative to hospital system concentration. Target mid-tier regional banks with hybrid edge-cloud banking assistant deployments that incumbent cloud hyperscalers underserve with one-size-fits-all Alexa for Business templates. Go-to-market leverage rests on pre-certified GDPR data minimization architectures that accelerate procurement cycles in German cooperative banking networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-native silicon specialists with automotive design wins and established EU AI Act technical documentation capabilities. Long-term viability hinges on data residency architecture rather than acoustic modeling accuracy, privileging providers with captive tensor processing unit roadmaps over software-only natural language processing layers. Watch for German automotive OEM procurement specifications mandating edge-only inference as the inflection signal that compresses cloud infrastructure multiples while expanding on-device neural engine valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Neural Engine Development | Enables GDPR-compliant deployment for Stuttgart automotive OEMs and Boston healthcare systems. |
| EU AI Act Conformity Assessment Pre-Certification | Accelerates procurement cycles in German banking and French government agency verticals. |
| Automotive OEM Strategic Partnership | Locks in hands-free cabin control mandates for electric vehicle platforms in Germany and United States. |
| Voice Biometrics Specialist Acquisition | Consolidates biometric identification risk-classification expertise required by EU AI Act documentation. |
| Healthcare Workflow HIPAA Compliance Expansion | Captures underpenetrated ambulatory care settings beyond hospital system concentration. |
Research Methodology
A standing panel of conversational AI engineering directors, automotive OEM platform architects, healthcare IT procurement officers, and banking technology executives provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC spectrum allocation filings, EU AI Act technical documentation requirements, SEC hyperscaler capex disclosures, and MIIT GB standard enforcement notices. Bottom-up triangulation across deployment model segmentation and top-down consistency checks against tensor processing unit supply forecasts anchored volume estimates.
Consistency checks against external benchmarks validated model outputs against hyperscaler infrastructure spending patterns and automotive semiconductor procurement databases. The analytical framework modeled technology, application, end user, and deployment dimensions across the projection horizon, with natural language processing and voice biometrics investment pools tracked separately. CAGRs were derived from logistic adoption curves fitted to smart speaker penetration data and enterprise virtual assistant deployment rates, with edge computing trajectory sensitivity-tested against GDPR enforcement intensity assumptions.
Forecasts assume regulatory continuity in EU AI Act risk-classification regimes and FCC spectrum allocation priorities; material policy shifts in China's MIIT enforcement posture or United States healthcare data privacy legislation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market