
 Orchestration Tools Market | 2026-2036
Orchestration Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Orchestration Tools Market Analysis
GDPR enforcement is expanding the cost-of-entry calculus for orchestration vendors serving European enterprises. Microsoft Azure Data Factory leverages its compliance certifications to anchor deployments in regulated industries. Google Cloud Workflows competes through native integration with containerized environments. Ansible Automation Platform specializes in configuration management for hybrid infrastructure stacks.
Orchestration tools coordinate distributed computing tasks across heterogeneous environments through declarative configuration files and event-driven triggers. These platforms manage container lifecycles, API routing, and workflow dependencies to ensure reliable execution of complex data pipelines and application deployments. Cloud-based deployment leads adoption as enterprises exit capital-intensive data center commitments, while container orchestration commands the deepest engineering investment due to Kubernetes ecosystem maturation. Workflow automation captures expanding demand from business units seeking low-code integration without IT bottlenecks.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape product roadmaps for vendors operating in Europe. The Federal Risk and Authorization Management Program in the United States restricts federal cloud procurement to pre-certified orchestration stacks. ISO 27001 and SOC 2 Type II audits function as table stakes for enterprise sales cycles across all geographies. Stakeholders must evaluate whether their orchestration architecture can absorb emerging sovereignty mandates without fragmenting operational consistency.
Market Dynamics
The orchestration tools market faces structural pressure from the EU AI Act's algorithmic transparency mandates, which force vendors to re-engineer audit trails and data lineage capabilities for European deployments.
Growth Catalysts
- EU AI Act Compliance:Financial services firms in Germany and France accelerate procurement of orchestration platforms with built-in explainability features to satisfy algorithmic accountability requirements.
- Kubernetes Ecosystem Maturation:Container orchestration capabilities expand as engineering teams standardize on cloud-native deployment patterns, reducing operational friction for hybrid infrastructure management.
- India's Sovereign Cloud Push:Data localization mandates from the RBI and MeitY drive domestic enterprises toward orchestration stacks with certified in-country residency controls.
Market Restraints
- Specialized Talent Scarcity:Shortages of Site Reliability Engineers with Kubernetes and Terraform expertise inflate implementation costs and extend deployment timelines.
- Certification Fragmentation:Divergent compliance requirements between FedRAMP in the United States, GDPR in Europe, and sector-specific banking regulations create product roadmap conflicts.
- Legacy Integration Complexity:Mainframe and COBOL systems in established financial institutions resist API-native orchestration, forcing expensive middleware layers.
Strategic Opportunities
- Edge Computing Orchestration:Manufacturing and logistics operators in the United States deploy lightweight orchestration agents to coordinate IoT device fleets at distributed facilities.
- Healthcare Data Pipelines:HIPAA-compliant workflow automation captures demand from US hospital systems modernizing patient data exchange without violating privacy safeguards.
- AI Model Lifecycle Management:MLOps convergence with orchestration platforms creates new revenue streams as enterprises operationalize generative AI deployments.
Industry Challenges
- Multi-Cloud Skill Deficits:Engineering teams struggle to maintain operational consistency across AWS, Azure, and GCP environments simultaneously.
- Audit Trail Engineering:Building immutable logs for GDPR and EU AI Act compliance consumes 30-40% of platform development resources without direct revenue return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orchestration Tools Market |
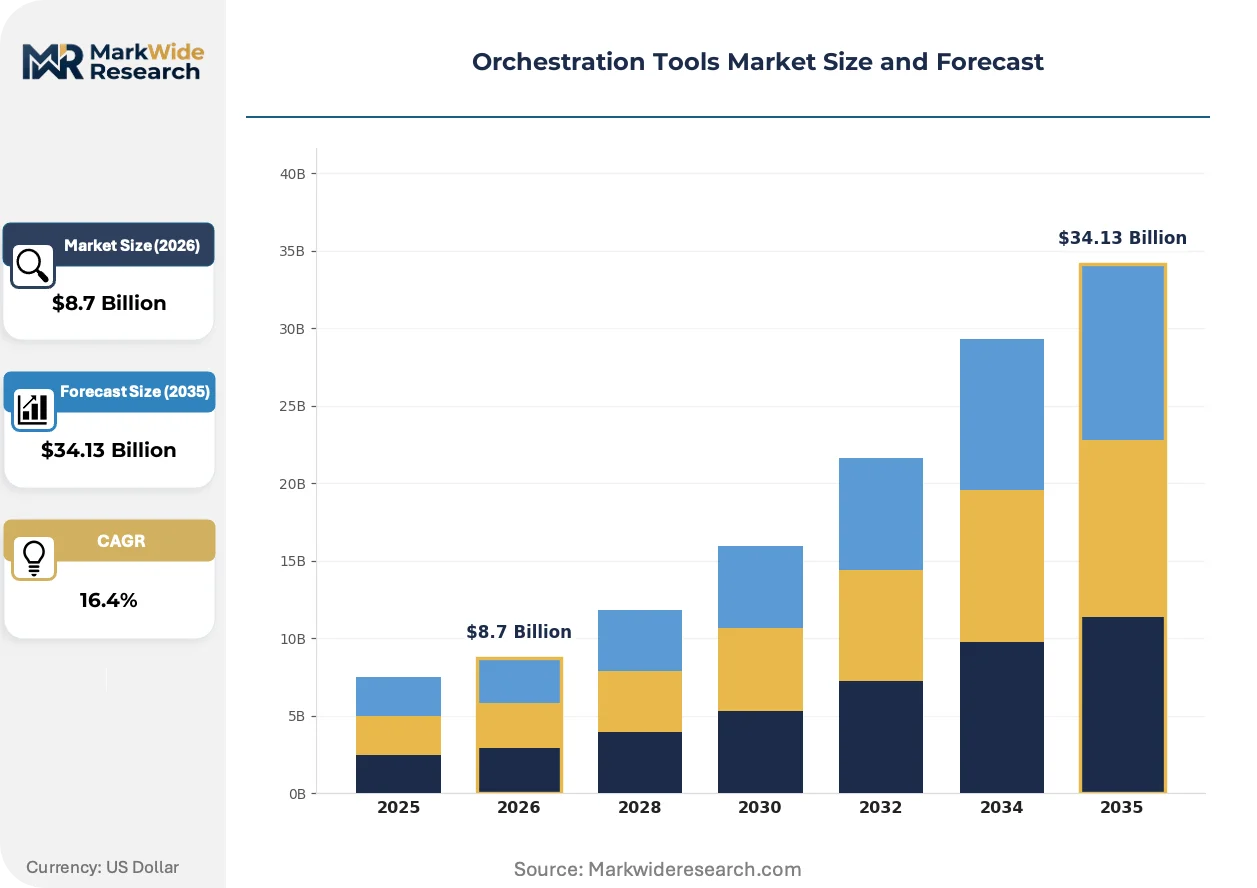
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: IT Departments, Managed Service Providers, Enterprises, Startups Feature: Automation, Monitoring, Configuration Management, Security Technology: Container Orchestration, Workflow Automation, API Management, Load Balancing |
| Companies Covered | Apache Airflow, Microsoft Azure Data Factory, Zapier, Ansible Automation Platform, Google Cloud Workflows, Prefect, Amazon Bedrock, Argo Workflows, LangChain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orchestration Tools Market Emerging Trajectories
Event-driven architecture patterns are displacing scheduled batch processing as the dominant workflow paradigm, compressing latency expectations and expanding real-time orchestration use cases.
GitOps methodologies are integrating infrastructure state management with version control systems, enabling platform engineering teams at SaaS providers to treat cluster configurations as declarative code. Financial services adopters in London and Singapore deploy these patterns to satisfy auditor demands for immutable change records. The approach is integrating compliance documentation directly into deployment pipelines, eliminating post-hoc audit preparation.
The EU AI Act's risk classification framework is forcing orchestration vendors to embed algorithmic impact assessments into product roadmaps. High-risk AI deployments in credit scoring and hiring automation now require documented human oversight mechanisms. German automotive manufacturers and French insurance groups are the earliest adopters of these governance-integrated platforms.
Platform engineering teams are consolidating procurement around internal developer portals that abstract orchestration complexity behind self-service interfaces. This behavior shift displaces direct Kubernetes console access for application developers at US technology firms and European retailers. The pattern is most visible in organizations with 500+ developers where ticket-based infrastructure requests created unacceptable deployment friction.
Orchestration Tools Market Segmentation
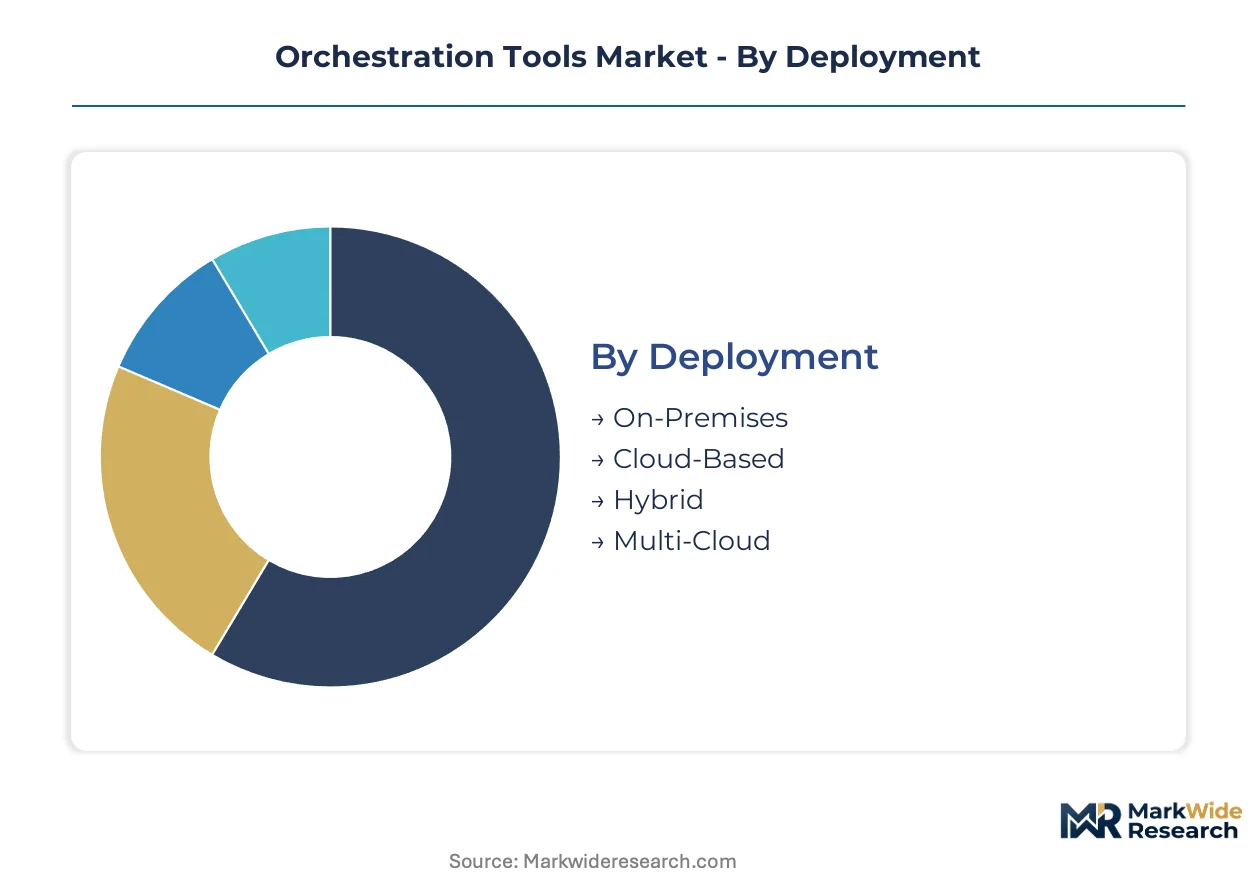
Orchestration tools segment along deployment topology, buyer sophistication, functional capability, and underlying infrastructure technology. Procurement patterns diverge sharply between regulated enterprises seeking sovereign controls and cloud-native startups prioritizing velocity over compliance.
Deployment:
Capital intensity and data residency requirements drive deployment-mode selection across buyer tiers.
- Cloud-Based:Public cloud orchestration eliminates data center capital commitments while enabling elastic scaling for variable workload patterns. Demand concentrates among US SaaS providers and European retailers exiting owned infrastructure, with GDPR Article 44 transfer mechanism assessments now mandatory for cross-border data flows.
- Hybrid:Split-stack orchestration maintains sensitive workloads on-premises while bursting compute-intensive tasks to public cloud. German automotive manufacturers and French insurance groups deploy these architectures to satisfy EU AI Act audit trail requirements without sacrificing cloud agility.
- On-Premises:Air-gapped orchestration serves defense contractors and national banks with sovereign cloud mandates.
- Multi-Cloud:Abstraction layers coordinate workloads across AWS, Azure, and GCP to prevent vendor lock-in.
Cloud-Based leads on scale; Multi-Cloud leads on momentum.
End User:
Organizational maturity and procurement authority shape feature requirements and pricing tolerance.
- Enterprises:Fortune 500 technology and financial services firms demand FedRAMP, ISO 27001, and SOC 2 Type II certifications as non-negotiable entry criteria. These buyers prioritize immutable audit logs and role-based access controls for compliance with SEC cybersecurity disclosure rules.
- IT Departments:Internal platform engineering teams at mid-market organizations seek self-service interfaces that abstract Kubernetes complexity from application developers. These units drive procurement of internal developer portals that consolidate orchestration tooling behind unified APIs.
- Managed Service Providers:Third-party operators resell orchestration capacity to client portfolios with standardized service level agreements.
- Startups:Venture-backed software companies prioritize velocity over governance, adopting managed container services with minimal configuration overhead.
Enterprises dominate current revenue; IT Departments are expanding most quickly.
Feature:
Functional modules align with distinct operational pain points across the infrastructure lifecycle.
- Automation:Declarative configuration management and event-driven triggers eliminate manual intervention in deployment pipelines. Site Reliability Engineering teams at US technology firms and Indian fintech operators invest heavily here to reduce mean time to recovery.
- Security:Policy-as-code enforcement and secrets management address expanding attack surfaces in containerized environments. HIPAA-covered entities and EU-regulated financial institutions mandate these capabilities for production deployments.
- Monitoring:Observability stacks correlate metrics, logs, and traces across distributed systems.
- Configuration Management:Infrastructure state synchronization ensures environment consistency.
Automation commands the deepest engineering investment; Security is gaining share fastest.
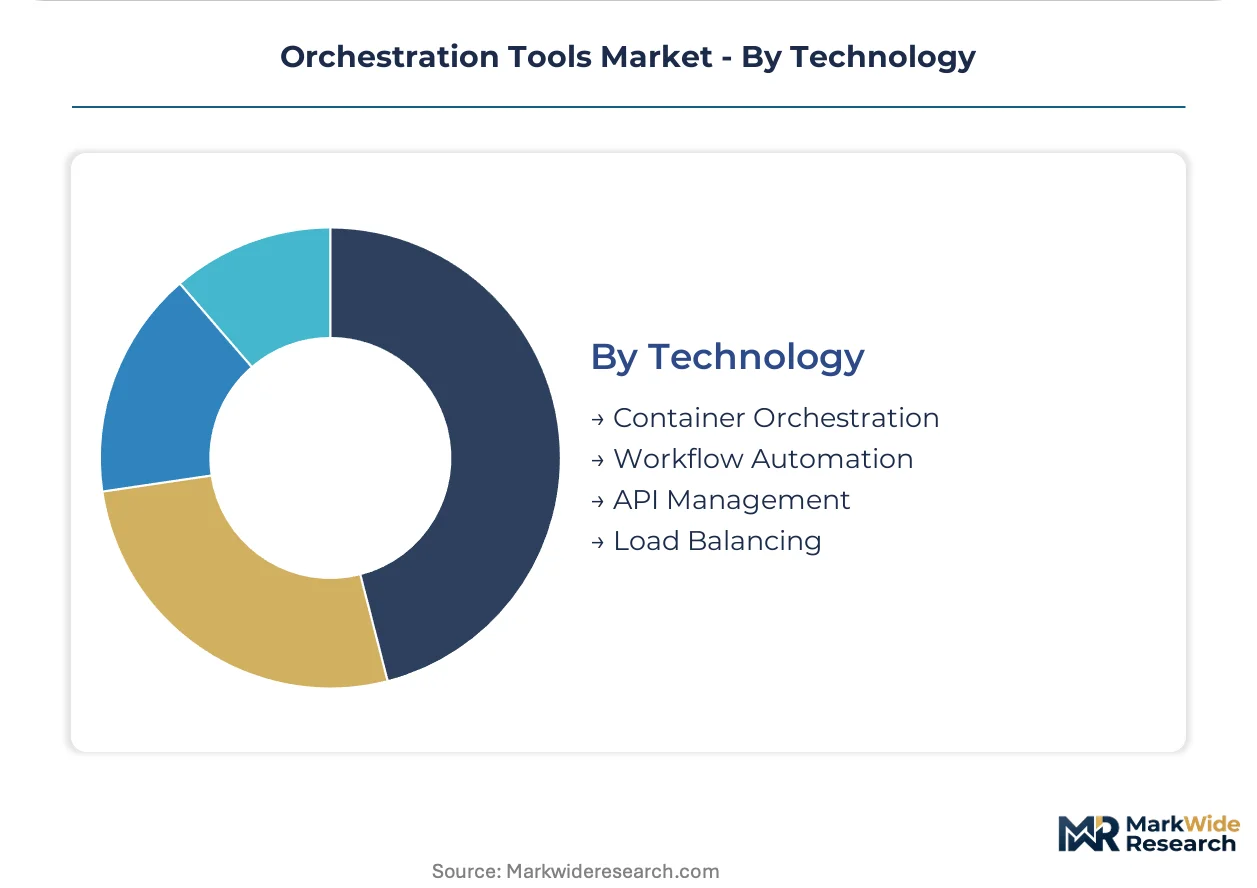
Technology:
Underlying architectural patterns determine integration complexity and talent requirements.
- Container Orchestration:Kubernetes-native platforms manage pod lifecycles, service discovery, and cluster autoscaling across heterogeneous infrastructure. Engineering teams in India and the United States standardize on these patterns for microservices deployments, though certified administrator scarcity inflates implementation costs.
- Workflow Automation:Low-code pipeline builders enable business units to construct data integrations without engineering bottlenecks. Healthcare systems in the United States deploy these tools for HIPAA-compliant patient data exchange modernization.
- API Management:Gateway and routing layers govern traffic flow between services.
- Load Balancing:Traffic distribution mechanisms ensure high availability across compute instances.
Container Orchestration anchors the largest installed base; Workflow Automation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Site Reliability Engineers cluster in Bangalore, Munich, and the San Francisco Bay Area, anchoring regional demand for orchestration platforms. These talent concentrations shape procurement patterns as enterprises compete for scarce Kubernetes expertise. Regulatory divergence across jurisdictions forces vendors to maintain parallel compliance roadmaps.
United States
Federal cloud modernization and healthcare data pipeline investments drive procurement velocity. FedRAMP certification restricts federal agency purchases to pre-approved orchestration stacks. Hospital systems in Boston and research institutions across the Research Triangle deploy HIPAA-compliant workflow automation for patient data exchange.
Germany
Automotive manufacturers and industrial conglomerates demand sovereign cloud capabilities with immutable audit trails. EU AI Act risk classifications force re-engineering of algorithmic decision systems in credit scoring and hiring automation. Engineering teams in Stuttgart and Munich lead adoption of GitOps patterns for compliance documentation.
India
Domestic fintech operators and IT service providers scale container orchestration for microservices deployments. RBI data localization mandates and MeitY sovereign cloud requirements steer enterprises toward certified in-country residency controls. Development centers in Bangalore and Hyderabad absorb the deepest engineering investment in Terraform and Kubernetes administration.
France
Insurance groups and banking conglomerates accelerate procurement of explainability-enabled platforms. CNIL enforcement of GDPR Article 44 transfer mechanisms complicates cross-border data flows for multinational deployments. Paris-based financial services firms pilot governance-integrated orchestration for high-risk AI use cases.
United Kingdom
Platform engineering teams at SaaS providers consolidate procurement around internal developer portals. FCA operational resilience requirements mandate immutable change records for critical infrastructure. London technology firms and Edinburgh fintech operators displace direct Kubernetes access with self-service abstraction layers.
Orchestration Tools Market Vendor Landscape
The competitive structure tilts toward hyperscale cloud providers with embedded orchestration services. Microsoft, Google, and Amazon anchor the premium tier through native integration with broader cloud ecosystems. Mid-market specialists compete on deployment velocity and low-code accessibility. Strategic moves concentrate on compliance certification accumulation and vertical workflow template libraries.
Among open-source workflow engines, Apache Airflow and Prefect exemplify the community-driven archetype with extensible plugin architectures. Microsoft Azure Data Factory and Google Cloud Workflows occupy positions within the hyperscale-integrated tier, leveraging pre-existing enterprise relationships. Ansible Automation Platform anchors the infrastructure-centric segment for hybrid configuration management. These representatives illustrate how vendor selection fractures across cloud-native, open-source, and legacy-integrated deployment patterns.
| Leading Market Players |
|---|
| Apache Airflow |
| Microsoft Azure Data Factory |
| Zapier |
| Ansible Automation Platform |
| Google Cloud Workflows |
| Prefect |
| Amazon Bedrock |
| Argo Workflows |
| LangChain |
| Others |
Supply Flow & Price Mechanics
Captive integration of compliance certification pipelines anchors vendor pricing power while constraining supply flexibility for buyers in regulated verticals. German automotive manufacturers and French banking conglomerates absorb premium tiers because FedRAMP and EU AI Act audit requirements eliminate unqualified suppliers from procurement shortlists.
Pricing Analysis
The bundled-vs-unbundled service split separates hyperscale-integrated orchestration from standalone workflow engines. Subscription tiers stratify across enterprise certification grade, with FedRAMP High and ISO 27001 bundles commanding substantial premiums over SOC 2-only configurations. Cost compression in mid-market SaaS tiers intensifies as Zapier and Prefect compete on seat-based economics. Startups exhibit highest price sensitivity; Fortune 500 technology firms prioritize audit immutability over unit cost.
Supply Chain Analysis
Regional distribution centers for cloud orchestration concentrate in Northern Virginia, Frankfurt, and Mumbai to satisfy data residency mandates. Engineering talent pipelines draw from Bangalore, Munich, and the San Francisco Bay Area, creating geographic dependency for implementation services. Single-source vulnerability runs through certified Kubernetes administrator scarcity, which extends deployment timelines. Distribution runs through hyperscale marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orchestration tools market represents a late-cycle quality story as procurement committees elevate compliance documentation above velocity metrics. Financial services firms in Germany and the United States now mandate immutable audit trails as table stakes.
For Market Incumbents: Deploy certification roadmapping as the primary defensive lever. Accelerate FedRAMP High and EU AI Act explainability module development before regulatory deadlines harden procurement criteria. Consolidate channel control through exclusive partnerships with systems integrators specializing in legacy mainframe integration, neutralizing emerging entrant attacks on hybrid infrastructure complexity. For New Entrants and Emerging Players: The price-point gap between premium certified tiers and economy self-service offerings creates white-space opportunity. Target mid-market healthcare systems in the United States seeking HIPAA-compliant workflow automation without enterprise-scale implementation overhead. Penetrate through vertical-specific template libraries that compress time-to-value for hospital data pipeline modernization. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance engineering costs exceed standalone revenue trajectories. Five-to-ten-year viability favors platforms with embedded governance modules over point-solution workflow engines. Monitor MLOps convergence signals as inflection indicators for generative AI operationalization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Accumulation | FedRAMP High and EU AI Act modules lock out unqualified competitors from regulated procurement. |
| Vertical Workflow Template Library | HIPAA-compliant healthcare pipelines accelerate time-to-value for US hospital system buyers. |
| Internal Developer Portal Integration | Self-service abstraction layers capture platform engineering budgets at 500+ developer organizations. |
| GitOps Methodology Embedding | Immutable change records satisfy FCA operational resilience and SEC cybersecurity disclosure requirements. |
| MLOps Convergence Development | AI model lifecycle management captures emerging generative AI operationalization budgets. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure spending tracking forms the analytical core of this study. Primary interviews with platform engineering directors, IT procurement officers, Site Reliability Engineers, and compliance audit specialists informed demand-side assumptions. Secondary validation drew from hyperscaler capex disclosures, SEC 10-K infrastructure software segments, and regulatory filing databases including FedRAMP authorization packages and EMA algorithmic system registrations.
Input-output matrices map orchestration workload volumes to certification tier adoption rates across deployment topologies. Segmentation dimensions include deployment mode, organization size, functional capability module, and underlying infrastructure technology. CAGRs derive from regression analysis of historical cloud spend elasticity and forward projection of regulatory mandate implementation timelines. Sovereign cloud policy announcements from RBI and MeitY inform India-specific trajectory assumptions.
Caveats apply where EU AI Act enforcement intensity or FedRAMP authorization delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Referral Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Software Construction Components Market
Software & Services
Office Software Market
Software & Services
Load Testing Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Middleware Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Batch Management Software Market
Software & Services
Collaboration Tools Market
Software & Services
Global Web Scraper Software Market
Software & Services
Human Identification Analysis Software Market