
 Global Augmented Intelligence Market | 2026-2036
Global Augmented Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Intelligence Market Foresight
The EU AI Act is recalibrating compliance costs for augmented intelligence vendors serving European enterprises. Microsoft Corporation leverages its Azure AI infrastructure to anchor hybrid deployment architectures across regulated industries. NVIDIA Corporation specializes in GPU-accelerated inference engines that sustain real-time decision support workloads. SAP SE dominates enterprise resource planning integrations where explainable AI modules compete for procurement budgets.
Augmented intelligence denotes human-AI collaborative systems that enhance cognitive performance through contextual recommendations, natural language interfaces, and adaptive learning loops operating at sub-second inference latency. Its primary commercial purpose centers on amplifying expert judgment in high-stakes domains while preserving human accountability for final decisions. Machine Learning and Natural Language Processing occupy the largest technology positions, though Computer Vision is accelerating fastest in manufacturing quality assurance. Cloud-Based deployment captures dominant enterprise spend, while Edge Computing concentrates margin pools in defense and autonomous systems where latency thresholds exclude centralized architectures.
The FDA governs clinical decision support software through its Software as a Medical Device framework, while the EU AI Act imposes conformity assessments on high-risk augmented intelligence applications in financial services and public administration. Japan's METI coordinates industrial AI standards that shape procurement criteria for smart factory implementations. Stakeholders must monitor divergent explicability requirements across jurisdictions to avoid fragmented product architectures that inflate development overhead.
Market Dynamics
The EU AI Act's conformity assessment mandates are forcing vendors to rearchitect product pipelines around explicability requirements, diverting engineering resources from feature development toward documentation and audit infrastructure.
Growth Catalysts
- Clinical diagnostic software:The FDA's Software as a Medical Device framework clarifies approval pathways for clinician-facing tools, accelerating hospital procurement cycles in the United States.
- EU AI Act compliance services:European enterprises require algorithmic transparency modules, creating sustained demand for explainable AI integrations in financial services and public administration.
- Smart factory standards:Japan's METI coordinates industrial AI procurement criteria that mandate human-in-the-loop architectures for manufacturing quality assurance systems.
Market Restraints
- GPU supply concentration:Inference engine production depends on Taiwan-based advanced semiconductor fabrication, exposing real-time decision support vendors to geopolitical supply disruptions.
- Cross-jurisdiction compliance costs:Divergent explicability requirements between the FDA, EU AI Act, and Japan's METI force fragmented product architectures that inflate development overhead.
- Edge hardware cost structure:Low-latency deployment in defense and autonomous systems requires specialized accelerators whose unit economics exclude mid-market buyers.
Strategic Opportunities
- German industrial AI procurement:Mittelstand manufacturers seek governed AI implementations for predictive maintenance, creating entry points for hybrid cloud-edge architectures.
- Convergence of NLP and computer vision:Multimodal interfaces that combine natural language queries with visual inspection data are penetrating pharmaceutical quality control workflows.
- India's BIS standards development:The Bureau of Indian Standards is formulating AI system certification frameworks that will shape procurement for domestic IT services exporters.
Industry Challenges
- Explainable AI talent scarcity:The intersection of machine learning engineering and regulatory documentation expertise remains underdeveloped, extending hiring timelines for compliance-critical roles.
- Legacy ERP integration complexity:SAP SE and Oracle environments require custom API development to embed adaptive learning loops, inflating implementation costs and failure rates.
- Sub-second latency certification:Safety-critical applications in autonomous systems demand deterministic inference benchmarks that current testing protocols inadequately validate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Intelligence Market |
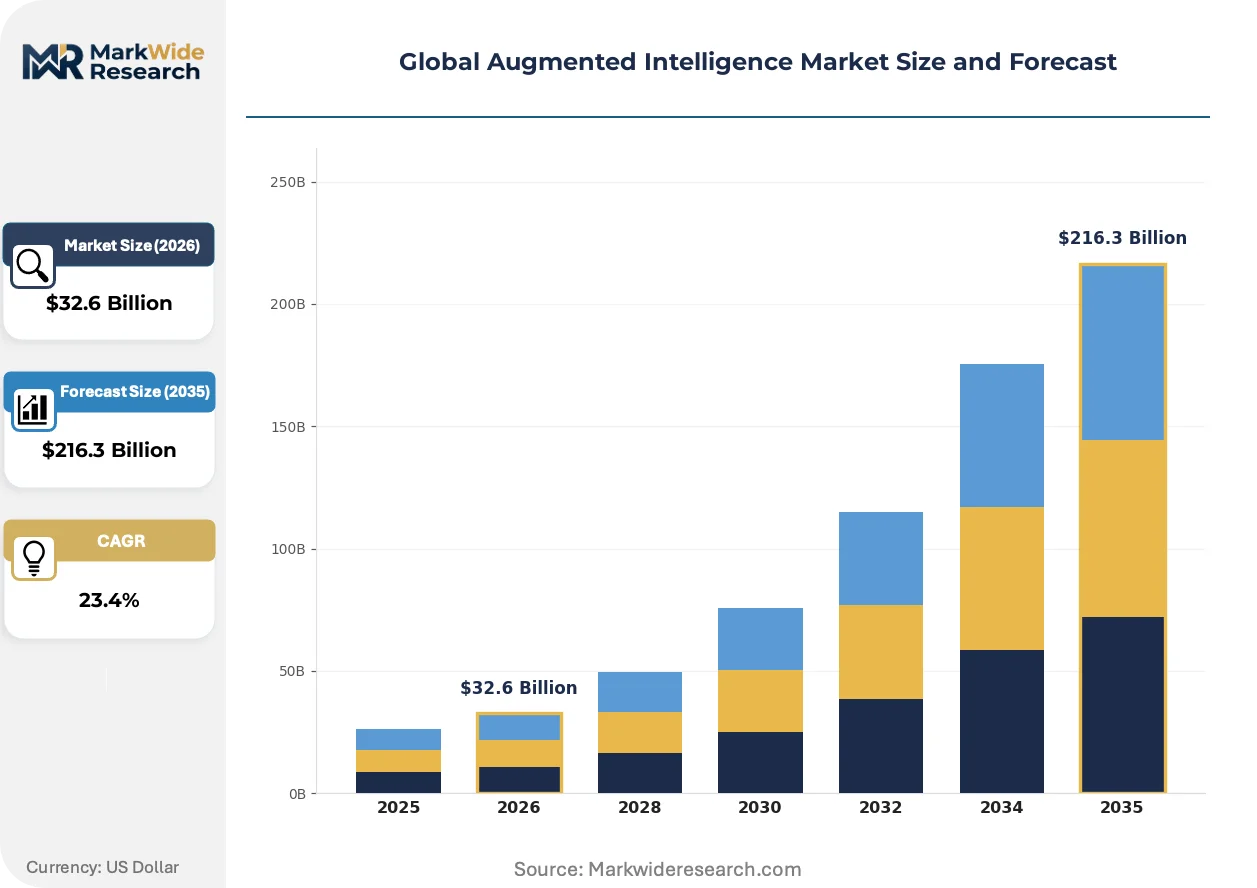
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $216.3 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Speech Recognition, Robotic Process Automation, Cognitive Computing Application: Fraud Detection, Customer Experience Management, Predictive Analytics, Risk Management, Supply Chain Optimization, Talent Acquisition Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Telecommunications, Financial Services, Manufacturing, E-Commerce, Government, Education |
| Companies Covered | International Business Machines Corporation, Microsoft Corporation, Alphabet Inc., Amazon Web Services, Inc., Salesforce, Inc., SAP SE, Oracle Corporation, NVIDIA Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Intelligence Market Shifts & Advancements
Foundation model architectures are fragmenting into specialized, domain-tuned systems that trade general capability for regulatory compliance and inference efficiency in high-stakes applications.
Retrieval-augmented generation is modularizing knowledge management for clinical decision support, allowing healthcare systems to ground large language model outputs in institutional evidence bases without retraining core parameters. Hospital IT departments in the United States are piloting these architectures to satisfy FDA documentation requirements while preserving diagnostic throughput. The approach compresses validation timelines by separating static knowledge bases from generative components that require less frequent regulatory review.
The EU AI Act's risk classification system is recalibrating vendor go-to-market strategies, forcing providers of high-risk applications to establish conformity assessment partnerships with notified bodies before commercial deployment. Financial services firms in Frankfurt and Amsterdam are demanding pre-certified algorithmic modules to accelerate internal procurement processes. This regulatory friction is advantaging incumbent platforms with existing quality management systems over emerging competitors lacking audit infrastructure.
Subscription-based AI copilot arrangements are displacing perpetual license models in enterprise software procurement, unbundling implementation services from ongoing capability access. Manufacturing buyers in Japan and Germany now expect usage-based pricing tied to measurable productivity gains rather than seat counts. This shift concentrates margin pressure on vendors unable to demonstrate quantified outcome attribution in smart factory deployments.
Global Augmented Intelligence Market Segmentation
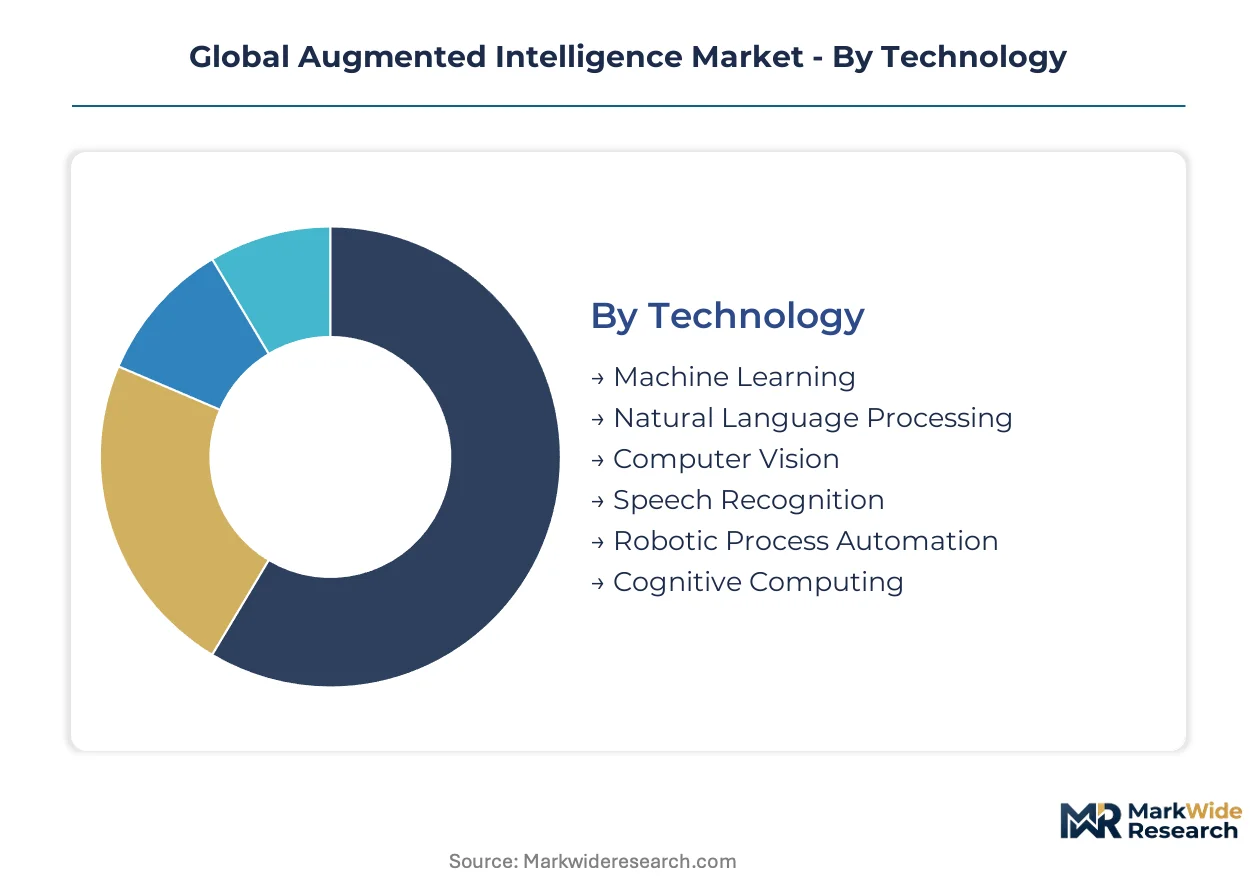
Augmented intelligence deployments fragment across technology stacks, application domains, and infrastructure models. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Technology:
Machine Learning and Natural Language Processing dominate enterprise procurement volumes, while Computer Vision commands premium pricing in quality assurance applications.
- Machine Learning:Statistical inference engines form the computational backbone of predictive analytics systems. Financial services firms in the United States deploy these modules for credit risk scoring under Federal Reserve supervisory guidance.
- Natural Language Processing:Semantic understanding systems enable clinician-facing documentation tools and customer service automation. German healthcare providers prioritize NLP interfaces that satisfy EU AI Act transparency mandates for high-risk medical applications.
- Computer Vision:Visual inspection algorithms accelerate defect detection in Japanese automotive manufacturing lines.
- Speech Recognition:Acoustic pattern matching supports hands-free industrial control interfaces and accessibility tools.
- Robotic Process Automation:Rule-based task automation bridges legacy ERP systems with modern AI orchestration layers.
- Cognitive Computing:Symbolic reasoning architectures address regulatory compliance scenarios requiring explicit decision audit trails.
Today's leader: Machine Learning. Tomorrow's challenger: Computer Vision.
Application:
Customer Experience Management absorbs the largest implementation budgets, though Fraud Detection delivers superior unit economics in regulated financial environments.
- Fraud Detection:Anomaly identification systems monitor transaction patterns in real-time. Japanese banks deploy these tools under FSA operational risk guidelines to satisfy Basel III liquidity monitoring requirements.
- Customer Experience Management:Personalization engines optimize engagement across digital touchpoints. E-commerce platforms in India leverage these systems to comply with BIS data localization standards while scaling recommendation throughput.
- Predictive Analytics:Forecasting models optimize inventory positioning and demand planning for manufacturing supply chains.
- Risk Management:Scenario simulation tools quantify operational and financial exposure for insurance underwriting workflows.
- Supply Chain Optimization:Network analytics reduce logistics costs through dynamic routing and supplier risk scoring.
- Talent Acquisition:Screening algorithms accelerate candidate matching while navigating EEOC anti-discrimination enforcement in US employment contexts.
Customer Experience Management currently captures dominant vendor attention. Fraud Detection exhibits the steepest expansion trajectory as real-time payment systems proliferate.
Deployment:
Cloud-Based architectures concentrate mid-market adoption, while Edge Computing margins reflect specialized hardware requirements and deterministic latency guarantees.
- Cloud-Based:Centralized inference services minimize capital expenditure for initial AI capability deployment. German Mittelstand manufacturers favor these models to avoid on-premise infrastructure investments while accessing scalable compute.
- Edge Computing:Distributed processing units execute inference locally for autonomous systems and defense applications. US Department of Defense procurement mandates sub-50ms latency thresholds that exclude cloud-only architectures.
- On-Premise:Captive infrastructure satisfies data sovereignty requirements in financial services and government sectors.
- Hybrid:Split architectures route sensitive workloads on-premise while leveraging cloud elasticity for batch processing.
Cloud-Based deployments lead current enterprise spend. Edge Computing is gaining share fastest as safety-critical applications multiply.
End User:
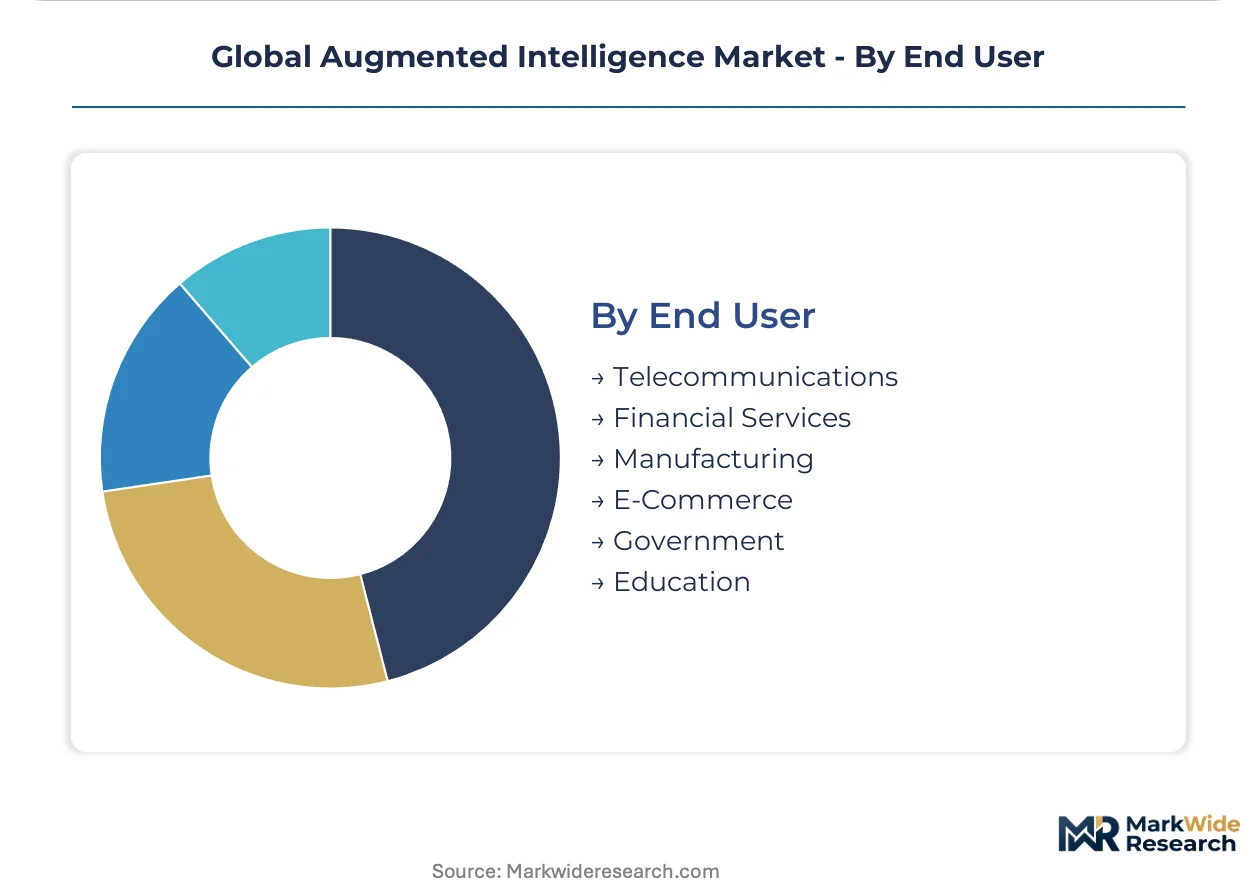
Financial Services and Manufacturing represent the deepest vertical expertise, with divergent procurement criteria around explainability and throughput optimization.
- Financial Services:Algorithmic trading and compliance monitoring demand deterministic audit trails. EU AI Act conformity assessments impose documentation burdens that favor established vendors with quality management infrastructure.
- Manufacturing:Predictive maintenance and quality control systems prioritize sub-second inference latency. Japan's METI smart factory standards mandate human-in-the-loop architectures that shape procurement specifications.
- Telecommunications:Network optimization and customer churn prediction drive AI infrastructure investments.
- E-Commerce:Recommendation engines and dynamic pricing systems compete for personalization technology budgets.
- Government:Public administration applications face heightened scrutiny under algorithmic accountability frameworks.
- Education:Adaptive learning platforms scale personalized instruction while navigating student data privacy regulations.
Financial Services anchors current revenue concentration. Manufacturing presents the most aggressive procurement expansion as industrial AI standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers cluster in Seattle, Bangalore, and Tel Aviv, anchoring regional capability centers for augmented intelligence development. Regulatory divergence across jurisdictions fragments deployment architectures. Procurement concentrates where compliance infrastructure and technical talent overlap.
United States
FDA's Software as a Medical Device framework accelerates hospital procurement of clinician-facing diagnostic tools. Federal Reserve supervisory guidance shapes credit risk scoring implementations in financial services. Seattle and San Francisco Bay Area host the densest concentrations of NLP and computer vision engineering talent.
Germany
Mittelstand manufacturers drive demand for predictive maintenance systems with human-in-the-loop architectures. EU AI Act conformity assessments impose documentation burdens favoring vendors with established quality management systems. Stuttgart and Munich industrial clusters prioritize governed AI implementations for smart factory deployments.
Japan
METI coordinates industrial AI procurement criteria mandating explainable modules for manufacturing quality assurance. FSA operational risk guidelines govern real-time fraud detection deployments in banking. Nagoya and Osaka manufacturing belts concentrate edge computing implementations for sub-second latency requirements.
India
BIS standards development shapes certification frameworks for domestic IT services exporters. RBI guidelines influence algorithmic transparency requirements in financial services procurement. Bangalore and Hyderabad host engineering centers developing retrieval-augmented generation architectures for healthcare documentation.
United Kingdom
FCA operational resilience requirements drive explainable AI adoption in algorithmic trading. NHS procurement frameworks prioritize FDA-aligned validation pathways for clinical decision support. London financial services cluster demands deterministic audit trails for compliance monitoring systems.
Global Augmented Intelligence Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment infrastructure, application software, and specialized hardware layers. Cloud hyperscalers anchor platform economics through subscription-based AI copilot arrangements displacing perpetual licenses. Three archetypes dominate: infrastructure providers with captive silicon supply, enterprise software vendors with ERP integration depth, and vertical specialists with domain-tuned model architectures. Competitive moves concentrate on conformity assessment partnerships with EU notified bodies and hybrid cloud-edge architecture development for manufacturing buyers.
Among infrastructure-centric players, Microsoft Corporation exemplifies the platform archetype through Azure AI deployment scale, while NVIDIA Corporation anchors GPU-accelerated inference specialization. SAP SE occupies a distinct position in enterprise resource planning integration where explainable AI modules compete for procurement budgets against Oracle Corporation offerings.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Microsoft Corporation |
| Alphabet Inc. |
| Amazon Web Services, Inc. |
| Salesforce, Inc. |
| SAP SE |
| Oracle Corporation |
| NVIDIA Corporation |
| Intel Corporation |
| Others |
Supply & Pricing Matrix
Machine learning engineers concentrated in Bangalore and Tel Aviv create labor-cost differentials that widen pricing-tier spreads between premium certified modules and economy-tier automation tools. European vendors absorb EU AI Act documentation overhead into higher service bundles, while Indian IT services exporters compete on standardized API pricing.
Pricing Analysis
Bundled implementation services versus unbundled capability access defines the dominant split. Subscription-based AI copilot arrangements displace perpetual licenses, with three-tier pricing structure across premium, standard, and economy levels separating FDA-validated clinical modules from generic productivity tools. Price differentiation rests on certification grade and after-sales service intensity. Cost compression in economy tiers intensifies as mid-market buyers demand outcome-based contracts. Financial services procurement committees show least price sensitivity, prioritizing deterministic audit trails over unit cost.
Supply Chain Analysis
EU AI Act conformity assessment partnerships with notified bodies gate vendor participation before commercial deployment. GPU fabrication concentrates in Taiwan and South Korea, with advanced packaging operations in the United States. Inference engine production draws from Taiwan-based semiconductor foundries, specialized memory modules from South Korean suppliers, and cloud orchestration software from US hyperscalers. Single-source vulnerability in advanced node fabrication exposes real-time decision support vendors to geopolitical disruption. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for legacy ERP embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Hospital procurement committees in the United States now prioritize FDA-aligned validation pathways over raw capability specifications.
For Market Incumbents: Hedge against foundation model commoditization by deepening explainable AI talent pools and pre-certifying algorithmic modules with EU notified bodies. Lock in manufacturing buyer relationships through hybrid cloud-edge architectures that satisfy Japan METI human-in-the-loop mandates. Vertical integration into specialized GPU supply buffers geopolitical exposure. For New Entrants and Emerging Players: Cloud-native deployment channels offer the lowest friction entry path. White-space concentrates in German Mittelstand predictive maintenance, where governed AI implementations face limited incumbent saturation. India's BIS standards development window creates certification-first positioning for domestic IT services exporters. Target outcome-based pricing models that tie fees to measurable productivity gains in smart factory deployments. For Investors and Strategic Acquirers: Enterprise software conglomerates with existing quality management systems are the most active acquirer in this space, advantaged by EU AI Act compliance infrastructure. Long-term viability favors vertical specialists with domain-tuned model architectures over generalist foundation model providers. Watch for inflection when subscription-based AI copilot arrangements displace perpetual licenses in manufacturing procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Conformity Assessment Partnership | EU AI Act mandates pre-certification with notified bodies before high-risk deployment. |
| Hybrid Cloud-Edge Architecture | German Mittelstand manufacturers demand governed AI with sub-second latency guarantees. |
| Retrieval-Augmented Generation Deployment | US hospital IT departments pilot FDA-aligned clinical documentation architectures. |
| Explainable AI Talent Acquisition | Regulatory documentation expertise scarcity extends hiring timelines for compliance roles. |
| Outcome-Based Pricing Transition | Japanese manufacturing buyers now expect usage-based contracts tied to productivity gains. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down infrastructure spending tracking forms the analytical core. Primary interviews with hospital IT directors, financial services compliance officers, manufacturing technology leads, and hyperscaler platform engineers combine with secondary validation from FDA 510(k) filings, EU notified body conformity assessment registries, and METI smart factory procurement databases. Top-down triangulation against cloud hyperscaler AI revenue disclosures and GPU supply chain customs data anchors volume estimates.
Input-output matrices map technology adoption rates against regulatory compliance thresholds across the projection horizon. Segmentation dimensions span deployment model, end-use vertical, organization size tier, and regional regulatory cluster. CAGRs derive from capability diffusion curves adjusted for jurisdiction-specific validation timelines. Forecast inputs incorporate EU AI Act implementation pace and FDA Software as a Medical Device guidance evolution.
Regulatory enforcement variance, GPU supply disruption events, and foundation model capability breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions on compliance cost pass-through rates and enterprise procurement cycle durations. A model refresh is warranted upon material change in EU AI Act delegated act specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Mlops Market