
 Europe Agricultural Tires Market | 2026-2036
Europe Agricultural Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Tires Market Foresight
The premium-commodity split in Europe agricultural tires is rebalancing as radial construction with reinforced sidewalls commands higher replacement premiums against bias-ply alternatives. Michelin leverages its European manufacturing footprint to sustain technical leadership in high-horsepower tractor fitments. Trelleborg AB anchors Nordic and Baltic distribution through specialized forestry-agriculture crossover tires. Continental AG differentiates via embedded sensor technology for tire pressure monitoring in precision farming applications.
Europe agricultural tires are pneumatic structures engineered with nylon, polyester, or steel cord reinforcement layers, molded with lug or rib tread patterns designed to operate at inflation pressures between 1.0 and 2.5 bar across varied soil conditions. Their primary function transmits engine torque to loose or cultivated surfaces while minimizing soil compaction and crop yield loss. Radial tires capture the dominant share of replacement value as their flexible sidewalls reduce slip and fuel draw in heavy draft work. Bias tires retain volume in southern European vineyards and orchards where compact machinery and lower speeds predominate. Floatation tires represent the fastest-expanding category as Central European contractors adopt wider footprints to meet seasonal field access windows without triggering soil damage penalties.
EU Green Deal machinery emissions benchmarks and ECHA REACH chemical compliance obligations shape tire compound formulations and recyclability mandates across member states. CE marking requirements under the EU Machinery Directive govern tire safety ratings and load index declarations for original equipment and aftermarket channels. Stakeholders must monitor how the EU AI Act intersects with smart tire sensor data governance as connected agriculture platforms proliferate.
Market Dynamics
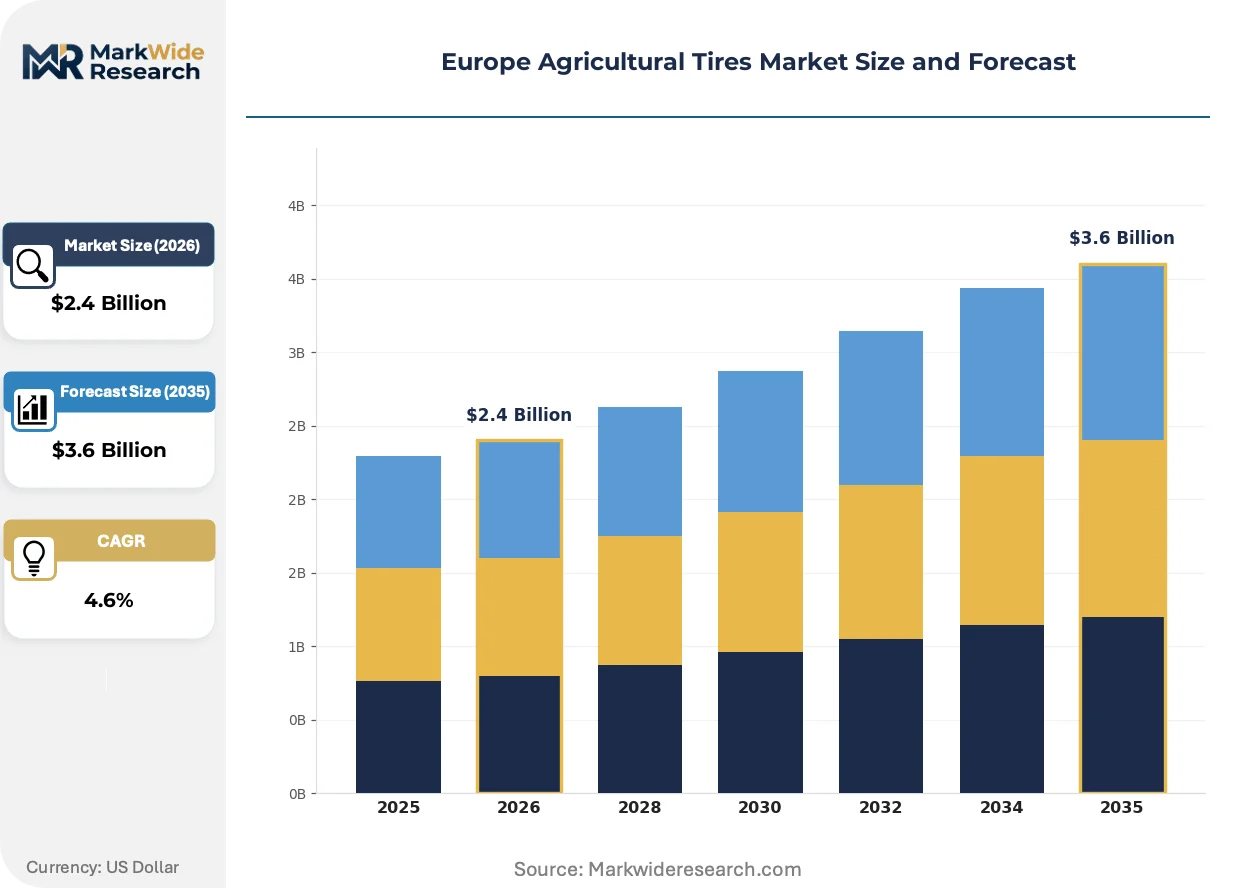
The EU Green Deal machinery emissions benchmarks are compressing replacement cycles across German and French arable farming cooperatives, forcing capital allocation toward low-rolling-resistance radial fitments that reduce fuel draw in heavy draft operations.
Growth Catalysts
- EU Green Deal compliance pressure:German and French cooperatives are accelerating fleet renewal to meet 2030 machinery emissions benchmarks, pulling forward replacement demand for fuel-efficient radial tires.
- Precision agriculture penetration:Large-scale cereal operations in France and Germany are embedding tire pressure monitoring systems into connected farming platforms, requiring sensor-compatible tire architectures.
- Soil protection regulation:Central European contractors face seasonal field access restrictions and soil damage penalties, driving adoption of wider flotation footprints that distribute load across cultivated surfaces.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and climate-induced harvest variability are compressing compound cost predictability for European tire manufacturers.
- Steel cord supply concentration:Dependence on a limited number of European metallurgical suppliers creates vulnerability in high-horsepower radial reinforcement layer sourcing.
- ECHA REACH chemical compliance:Restrictions on aromatic oils and plasticizers in tire compounds are forcing reformulation investments that extend product development timelines.
Strategic Opportunities
- Forestry-agriculture crossover expansion:Nordic and Baltic markets present underpenetrated demand for specialized tires serving dual-purpose machinery in timber and field operations.
- EU AI Act data governance alignment:Smart tire sensor platforms that comply with emerging AI Act requirements for agricultural data processing can capture premium positioning in connected farming ecosystems.
- Vineyard and orchard electrification:Southern European compact machinery electrification creates demand for low-load bias-ply variants optimized for battery-powered traction systems.
Industry Challenges
- Compound formulation expertise scarcity:REACH-compliant rubber chemistry and recyclability engineering require specialized polymer scientists that European manufacturers struggle to recruit.
- CE marking certification timelines:Extended safety rating and load index declaration processes under the EU Machinery Directive delay product launches for aftermarket channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Tires Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Floatation Tires, All-Terrain Tires End User: Farms, Cooperatives, Agricultural Machinery Dealers, Contractors Size: Standard Size, Large Size, Compact Size, Specialty Size Feature: Deep Tread, Weather Resistance, Fuel Efficiency, Load Capacity |
| Companies Covered | Trelleborg AB, Balkrishna Industries Limited, Michelin, Nokian Tyres plc, Yokohama Rubber Co. Ltd., Bridgestone Corporation, Titan International, Mitas, Continental AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Tires Market Shifts & Advancements
Active reshaping of the Europe agricultural tires landscape centers on three converging forces: embedded sensor architectures enabling precision farming integration, regulatory chemistry mandates driving compound reformulation, and contractor procurement models favoring total-cost-of-ownership over upfront acquisition price.
Sensor-embedded tire architectures are absorbing capital allocation from major European manufacturers as real-time pressure and temperature monitoring becomes standard in high-horsepower tractor fitments. German and French precision farming cooperatives are adopting these systems at accelerating rates to optimize field-by-field inflation protocols. The technology is absorbing service revenue from traditional dealer networks as predictive maintenance alerts shift value toward data platform providers.
REACH chemical compliance obligations are forcing systematic elimination of aromatic oils and high-priority substance additives from tire compound recipes across European production facilities. Industrial consequence includes accelerated R&D timelines and partnerships with bio-based polymer suppliers to maintain performance characteristics. Southern European vineyard and orchard tire segments face the most acute reformulation pressure given their reliance on softer compounds for compact machinery traction.
Contractor procurement patterns are pivoting toward lifecycle cost agreements that bundle tire supply with pressure monitoring subscriptions and field service coverage. Traditional distributor networks in Central Europe face disintermediation threat as manufacturer-direct platform sales capture large fleet accounts. This behavioral shift is most visible in Germany, where arable farming cooperatives consolidate purchasing power through centralized procurement consortia.
Europe Agricultural Tires Market Segmentation
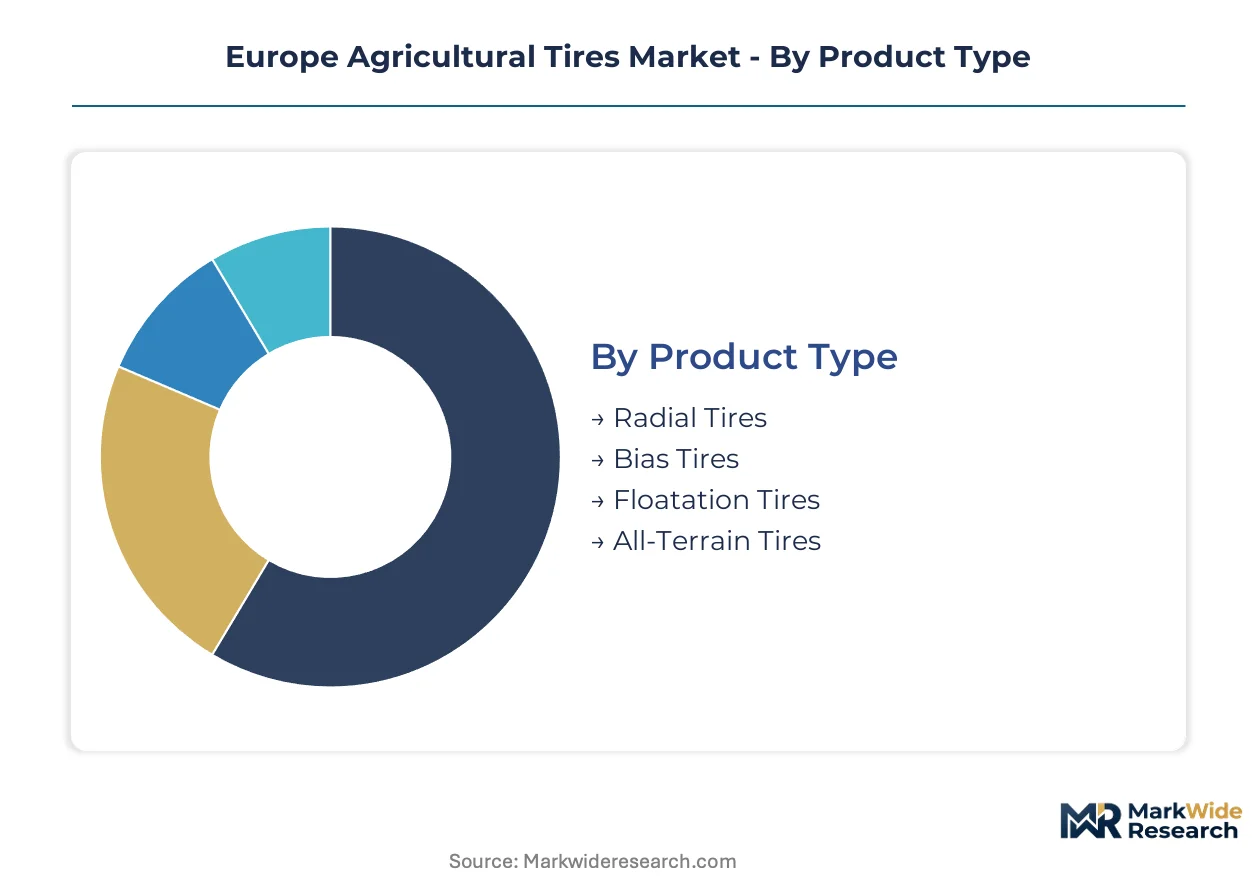
Segmentation in Europe agricultural tires reflects divergent technical requirements across machinery types, farm scales, and regulatory environments. Tire construction, end-user procurement patterns, and specification tiers determine replacement cycles and pricing architecture differently across German arable cooperatives, French cereal operations, and Southern European specialty farms.
Product Type:
Construction methodology defines load distribution, fuel efficiency, and soil compaction performance across European farming applications.
- Radial Tires:Steel or nylon cord plies arranged at 90 degrees to the direction of travel enable flexible sidewalls that reduce slip and fuel consumption in heavy draft work. German and French large-scale cereal operations concentrate replacement demand here as precision agriculture platforms require compatible sensor architectures.
- Floatation Tires:Ultra-wide footprints distribute machinery weight across larger surface areas to minimize soil penetration depth. Central European contractors facing seasonal field access restrictions and soil damage penalties under national implementing regulations are expanding adoption fastest.
- Bias Tires:Diagonal ply construction delivers puncture resistance and lower unit cost for compact machinery operating at reduced speeds. Southern European vineyard and orchard owners retain volume preference where maneuverability constraints dominate over efficiency metrics.
- All-Terrain Tires:Hybrid tread patterns bridge field and road performance for machinery with high transport-to-work ratios. Mixed-use contractors in the Nordic-Baltic zone generate specialized demand for forestry-agriculture crossover applications.
Radial tires lead on scale; floatation tires lead on momentum.
End User:
Procurement concentration and fleet renewal cycles vary sharply by organizational scale and capital access.
- Cooperatives:Consolidated purchasing power across German and French arable farming groups accelerates replacement cycles in response to EU Green Deal machinery emissions benchmarks. Centralized procurement consortia negotiate lifecycle cost agreements bundling tire supply with monitoring subscriptions.
- Farms:Individual owner-operators in Southern Europe prioritize upfront acquisition cost over total-cost-of-ownership calculations. Smaller fleet scale limits bargaining leverage with manufacturer-direct platforms.
- Contractors:Seasonal field access windows and soil protection compliance obligations drive specification requirements for flotation-capable fitments. Service revenue models are absorbing value from traditional dealer networks.
- Agricultural Machinery Dealers:Aftermarket channel intermediaries face disintermediation pressure as OEMs and tire manufacturers build direct platform relationships with large fleet accounts.
Cooperatives concentrate replacement value; contractors generate specification innovation pull.
Size:
Dimensional categories map to horsepower classes, soil types, and crop system constraints across European agricultural zones.
- Large Size:High-horsepower tractor fitments for extensive arable operations in France and Germany. CE marking load index declarations govern safety ratings under EU Machinery Directive requirements.
- Compact Size:Narrow profiles for vineyard and orchard machinery in Italy, Spain, and Portugal where row spacing limits equipment width. Electrification trends are reshaping load requirements.
- Standard Size:Mid-range utility tractors serving mixed livestock-crop operations across Central European family farms. Volume concentration supports distributor inventory strategies.
- Specialty Size:Custom specifications for forestry equipment, slope tractors, and controlled traffic farming systems. Baltic and Nordic markets generate disproportionate demand relative to arable acreage.
Large size commands premium replacement value; compact size faces acute reformulation pressure from electrification.
Feature:
Performance attributes align tire selection with operational priorities and regulatory compliance obligations.
- Fuel Efficiency:Low-rolling-resistance compounds and tread designs reduce diesel draw in heavy draft operations. EU Green Deal benchmarks are accelerating specification priority in German cooperative procurement.
- Deep Tread:Extended lug patterns enhance traction in loose or cultivated surfaces and extend service intervals. High-horsepower applications in cereal zones concentrate demand.
- Load Capacity:Reinforced sidewall structures and bead designs for heavy implements and ballasted tractors. Safety rating declarations under CE marking requirements govern aftermarket channel compliance.
- Weather Resistance:Compound formulations resisting UV degradation, temperature cycling, and moisture ingress. Extended storage periods between seasonal use cycles in Northern Europe drive specification priority.
Fuel efficiency leads on regulatory pull; deep tread leads on replacement cycle extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer scientists and tire compound engineers cluster around Clermont-Ferrand in France and Hanover in Germany, anchoring European agricultural tire R&D capabilities. These talent concentrations feed directly into radial tire development for high-horsepower machinery. Regional demand patterns diverge sharply between arable farming zones and specialty crop regions.
Germany
Arable farming cooperatives in Lower Saxony and Brandenburg are compressing fleet renewal cycles to meet EU Green Deal machinery emissions benchmarks. CE marking requirements under the EU Machinery Directive govern load index declarations for aftermarket channels. Claas and Fendt manufacturing clusters around Münsterland and Lake Constance drive specification pull for sensor-compatible radial fitments.
France
Large-scale cereal operations in Île-de-France and Grand Est are embedding tire pressure monitoring into precision agriculture platforms. ECHA REACH chemical compliance obligations are forcing reformulation of aromatic oil-dependent compounds. The Michelin technical center at Clermont-Ferrand anchors compound innovation for low-rolling-resistance tread designs.
Italy
Vineyard and orchard owners in Piedmont and Tuscany retain bias-ply preference for compact machinery navigating narrow row spacing. Electrification trends in specialty farming are reshaping load requirements for battery-powered traction systems. Bologna's agricultural machinery district generates demand for maneuverability-optimized tire profiles.
Poland
Central European contractors are adopting flotation tires fastest to meet seasonal field access windows without triggering soil damage penalties. National implementing regulations of EU soil protection directives create compliance-driven specification requirements. Masovian Voivodeship farming cooperatives are consolidating purchasing power through procurement consortia.
Sweden
Forestry-agriculture crossover machinery in Västerbotten and Norrland generates specialized demand for all-terrain tread patterns. Trelleborg AB anchors Nordic distribution networks serving dual-purpose timber and field operations. Arctic temperature cycling demands weather-resistant compound formulations for extended storage periods between seasonal use.
Europe Agricultural Tires Market Competitive Landscape
Top-tier vendors anchor premium radial development, while mid-scale specialists occupy bias-ply and flotation niches. The vendor base stratifies across three tiers: integrated tire manufacturers with in-house polymer research, regional fabricators serving distributor networks, and private-label suppliers for aftermarket channels. Two strategic archetypes dominate: sensor-embedded architecture specialists and REACH-compliant compound innovators. Competitive moves center on backward integration into rubber cultivation partnerships and predictive maintenance platform licensing.
Within the integrated manufacturer tier, Michelin and Continental AG exemplify sensor-embedded architecture development for precision farming compatibility. Trelleborg AB occupies a specialized position serving forestry-agriculture crossover demand in Nordic markets. These three entities represent distinct competitive vectors: French-led radial innovation, German sensor-platform integration, and Swedish-Baltic distribution anchoring.
| Leading Market Players |
|---|
| Trelleborg AB |
| Balkrishna Industries Limited |
| Michelin |
| Nokian Tyres plc |
| Yokohama Rubber Co. Ltd. |
| Bridgestone Corporation |
| Titan International |
| Mitas |
| Continental AG |
| Others |
Supply & Pricing Matrix
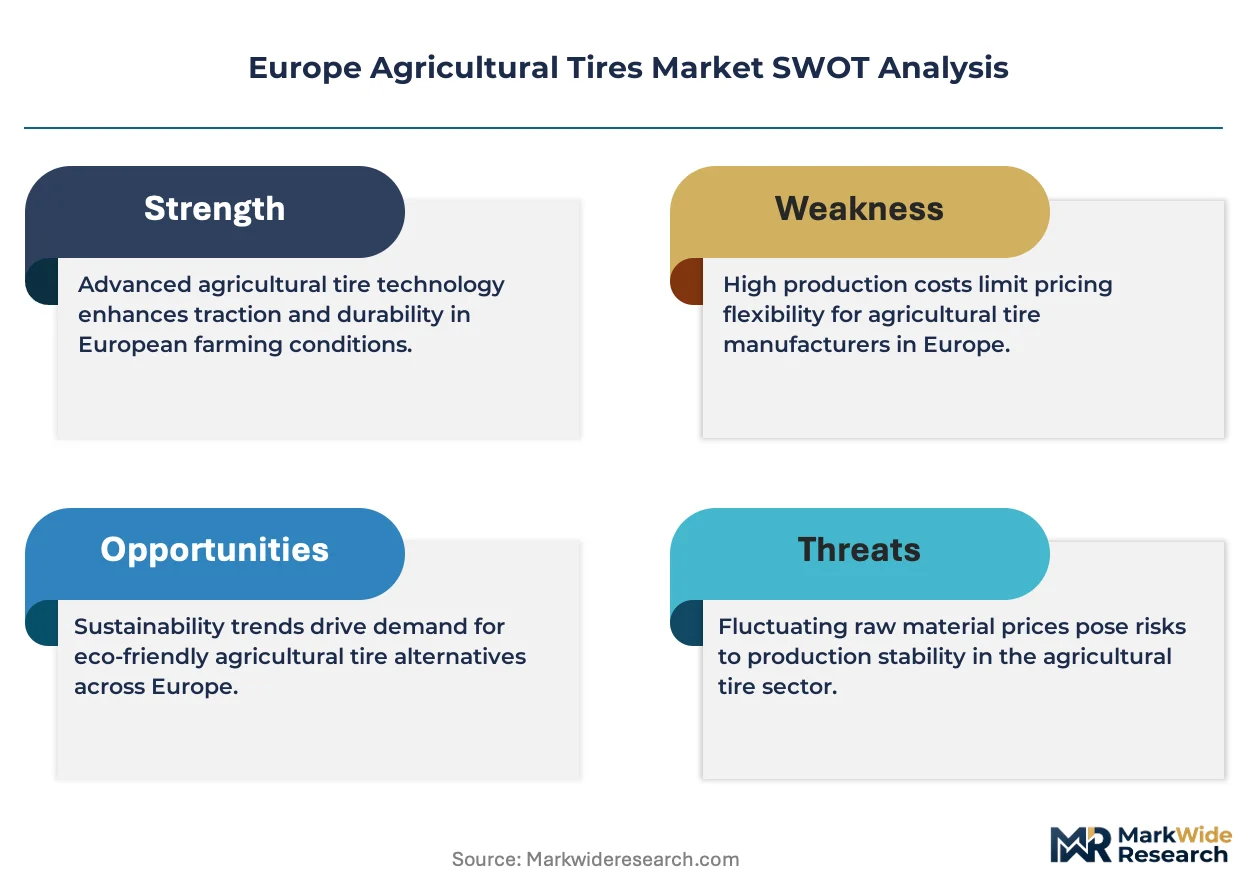
Sensor-embedded tire architectures are simultaneously elevating R&D cost structures and concentrating procurement leverage among German and French cooperative buyers capable of negotiating lifecycle cost agreements. This technical transition compresses margin pools for distributors while rewarding manufacturers with captive polymer research capabilities.
Pricing Analysis
Bundled service contracts separating tire supply from pressure monitoring subscriptions now command premium positioning against unbundled transactional sales. Three-tier pricing structure across premium sensor-embedded, standard radial, and economy bias-ply levels reflects CE marking certification tiers and volume scale. Pricing pressure stems from REACH-compliant compound reformulation investments that extend product development timelines. Individual owner-operators in Southern Europe exhibit highest price sensitivity, while consolidated cooperative procurement consortia in Germany prioritize total-cost-of-ownership metrics over upfront acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for tire retreading and steel cord recovery remain underdeveloped across European facilities, limiting circular material recapture. Natural rubber sourcing draws from Thailand, Indonesia, and Vietnam, while steel cord reinforcement rests on German and Belgian metallurgical suppliers. Single-source vulnerability in high-horsepower radial reinforcement layer sourcing creates structural risk exposure. Distribution runs through manufacturer-direct platform sales capturing large fleet accounts alongside traditional agricultural machinery dealer networks serving fragmented vineyard and orchard segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal machinery emissions benchmarks function as a regulatory compounder, accelerating replacement cycles as German and French cooperatives compress fleet renewal timelines to meet 2030 compliance milestones.
For Market Incumbents: Hedge against distributor disintermediation by deepening direct platform relationships with centralized procurement consortia. Prioritize backward integration into bio-based polymer supply partnerships to secure REACH-compliant compound feedstock. Sensor-platform licensing revenue streams offer defensive positioning against pure manufacturing margin erosion.
For New Entrants and Emerging Players: Agricultural machinery OEM technical partnership channels offer lowest customer acquisition friction for sensor-compatible tire architectures. Southern European vineyard electrification presents underpenetrated white-space for low-load bias-ply variants optimized for battery-powered traction systems. Baltic and Nordic forestry-agriculture crossover segments reward specialized tread pattern development with limited incumbent focus.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with distributor network assets but limited polymer research capabilities. Long-term viability centers on compound formulation expertise scarcity and predictive maintenance platform integration. Watch for CE marking certification timeline compression as inflection signal for aftermarket channel consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polymer Supply | REACH-compliant compound feedstock security reduces reformulation cost volatility for European manufacturers. |
| Predictive Maintenance Platform Licensing | Sensor data monetization captures recurring revenue from German precision farming cooperative adoption. |
| Forestry-Agriculture Crossover Product Line Expansion | Nordic and Baltic dual-purpose machinery demand offers margin premium over commodity radial segments. |
| CE Marking Certification Acceleration Program | Faster EU Machinery Directive compliance reduces time-to-revenue for aftermarket channel product launches. |
| Cooperative Procurement Consortium Direct Sales | Manufacturer-direct relationships bypass distributor margin extraction in German arable farming consolidation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tire compound engineers, agricultural machinery OEM procurement teams, cooperative fleet managers, and aftermarket distributor principals against secondary validation. Customs data, ECHA regulatory filings, EU agricultural machinery registration databases, and tire manufacturer technical disclosures anchored supply-side assessment. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Historical replacement cycle patterns and machinery emissions benchmark implementation timelines anchored the forecast window against comparable regulatory transition periods. Modeled dimensions span tire construction methodology, end-user procurement archetype, dimensional category, and feature specification tier across the projection horizon. CAGRs derive from segment-level replacement elasticity coefficients and precision agriculture technology diffusion curves calibrated to EU Green Deal compliance trajectory.
Revisions become necessary when ECHA REACH chemical restrictions expand beyond aromatic oils, natural rubber supply disruptions exceed historical volatility bands, or EU AI Act data governance requirements reshape sensor platform economics. Forecasts reflect documented assumptions regarding cooperative consolidation rates and electrification penetration in specialty farming segments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Global Advanced Tires Market