
 Asia Pacific Two Wheeler Tire Market | 2026-2036
Asia Pacific Two Wheeler Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Two Wheeler Tire Market Insights
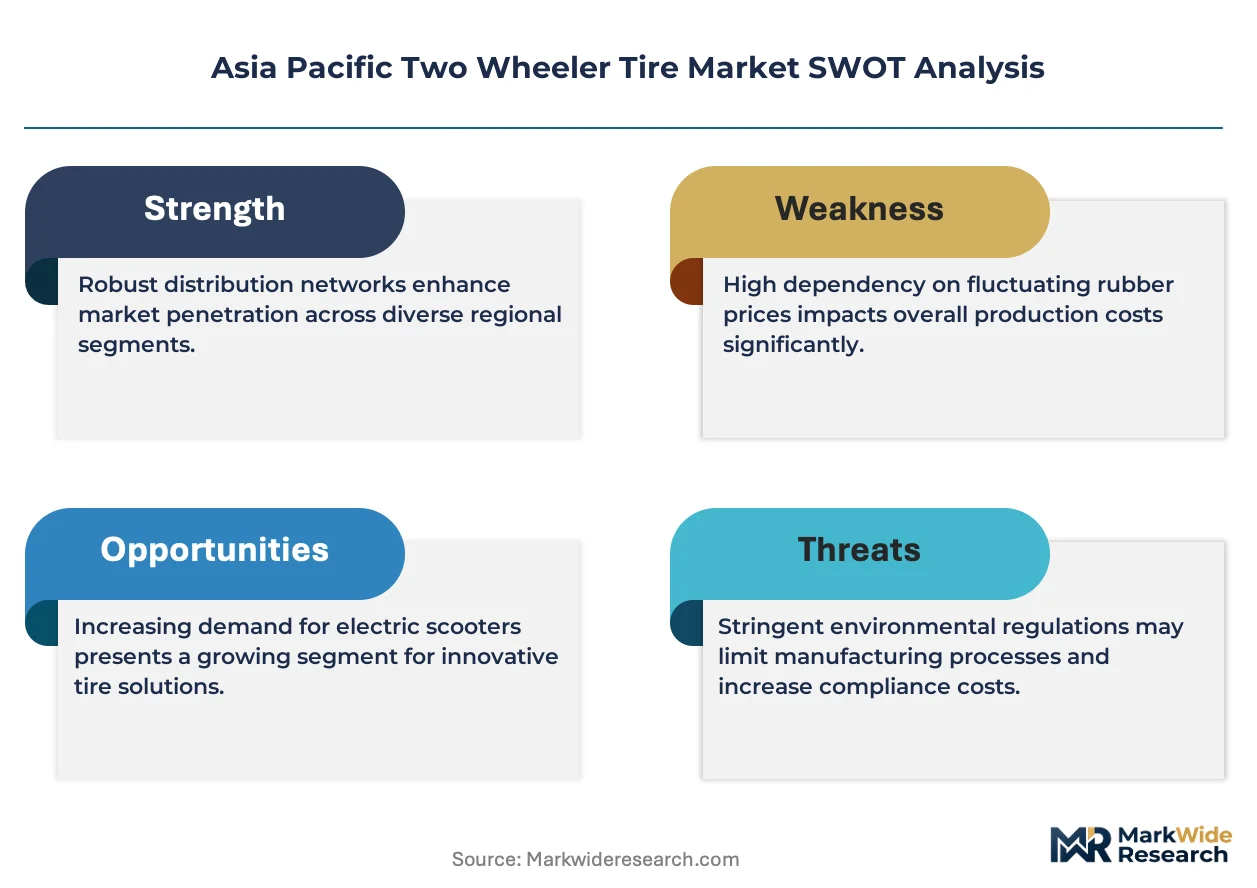
Aftermarket service revenue is rewriting profit allocation across the Asia Pacific two wheeler tire value chain. Hangzhou Zhongce Rubber leverages its captive rubber sourcing to dominate replacement cycles in Southeast Asian cities. Bridgestone Corporation sustains premium positioning through advanced tread compound R&D aimed at wet-grip performance. MRF Limited anchors its competitiveness with dense authorized dealer networks spanning tier-2 and tier-3 Indian towns.
Asia Pacific two wheeler tires are pneumatic structures engineered from natural rubber, synthetic rubber, carbon black, and steel bead wire, manufactured through calendering and vulcanization to deliver traction, load-bearing capacity, and durability on motorcycles and scooters. Tubeless tires now command margin preference due to their puncture resistance and compatibility with alloy wheel adoption across commuter segments. Radial tires represent the fastest-growing construction category as performance motorcycle ownership rises in Thailand and Malaysia, while bias tires retain volume dominance in price-sensitive scooter applications across South Asia.
India's BIS mandates, Thailand's TISI standards, and Vietnam's QCVN technical regulations collectively tighten rolling resistance and safety labeling requirements, forcing compound reformulation across manufacturing bases. METI's energy efficiency guidelines in Japan further constrain import eligibility for non-compliant suppliers. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national certification regimes when allocating regional production capacity.
Market Dynamics
Tubeless tire architecture is displacing tubed construction across Asia Pacific commuter fleets as alloy wheel penetration accelerates in Indonesian and Vietnamese urban delivery markets. This structural shift compresses replacement intervals while elevating compound performance requirements for puncture resistance and heat dissipation.
Growth Catalysts
- Urban delivery fleet expansion:Last-mile logistics operators across Ho Chi Minh City, Jakarta, and Bangalore are standardizing on motorcycles with shorter tire replacement cycles, creating sustained aftermarket pull.
- BIS certification mandates:India's Bureau of Indian Standards labeling requirements for rolling resistance and wet grip are forcing compound upgrades that lift average selling prices in the replacement channel.
- Radial construction adoption:Performance motorcycle segments in Thailand and Malaysia are migrating toward radial tires for enhanced stability at highway speeds, opening premium tier expansion.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian rubber futures fluctuations directly compress manufacturer margins, particularly for producers without backward integration into plantation assets.
- Supply concentration in Thai manufacturing:Overreliance on Eastern Seaboard production clusters exposes the regional value chain to monsoon-related logistics disruptions and port congestion.
- Bias tire technical ceiling:Scooter-dominant South Asian markets remain locked in cross-ply construction due to rim compatibility constraints, limiting radial penetration in volume segments.
Strategic Opportunities
- Vietnam QCVN regulatory tailwind:Technical safety mandates for two wheeler tires create first-mover advantage for suppliers with pre-certified compound portfolios ahead of full enforcement.
- Tier-3 Indian town channel penetration:Authorized service networks remain underdeveloped in Madhya Pradesh, Bihar, and Odisha, offering whitespace for branded replacement capture.
- Sensor-integrated smart tire convergence:Pressure monitoring systems paired with tread wear algorithms enable predictive maintenance offerings for fleet operators in Singapore and Kuala Lumpur.
Industry Challenges
- Compound formulation talent scarcity:Experienced rubber chemists capable of balancing rolling resistance against wet grip under tropical humidity conditions command premium compensation across Southeast Asian manufacturing hubs.
- BIS certification timeline compression:Laboratory testing queues for new tire SKUs extend lead times for product launches, penalizing suppliers without established testing relationships.
- Legacy tubed tire inventory obsolescence:Distributors in Bangladesh and Sri Lanka face write-downs as OEM fitment shifts decisively toward tubeless architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Two Wheeler Tire Market |
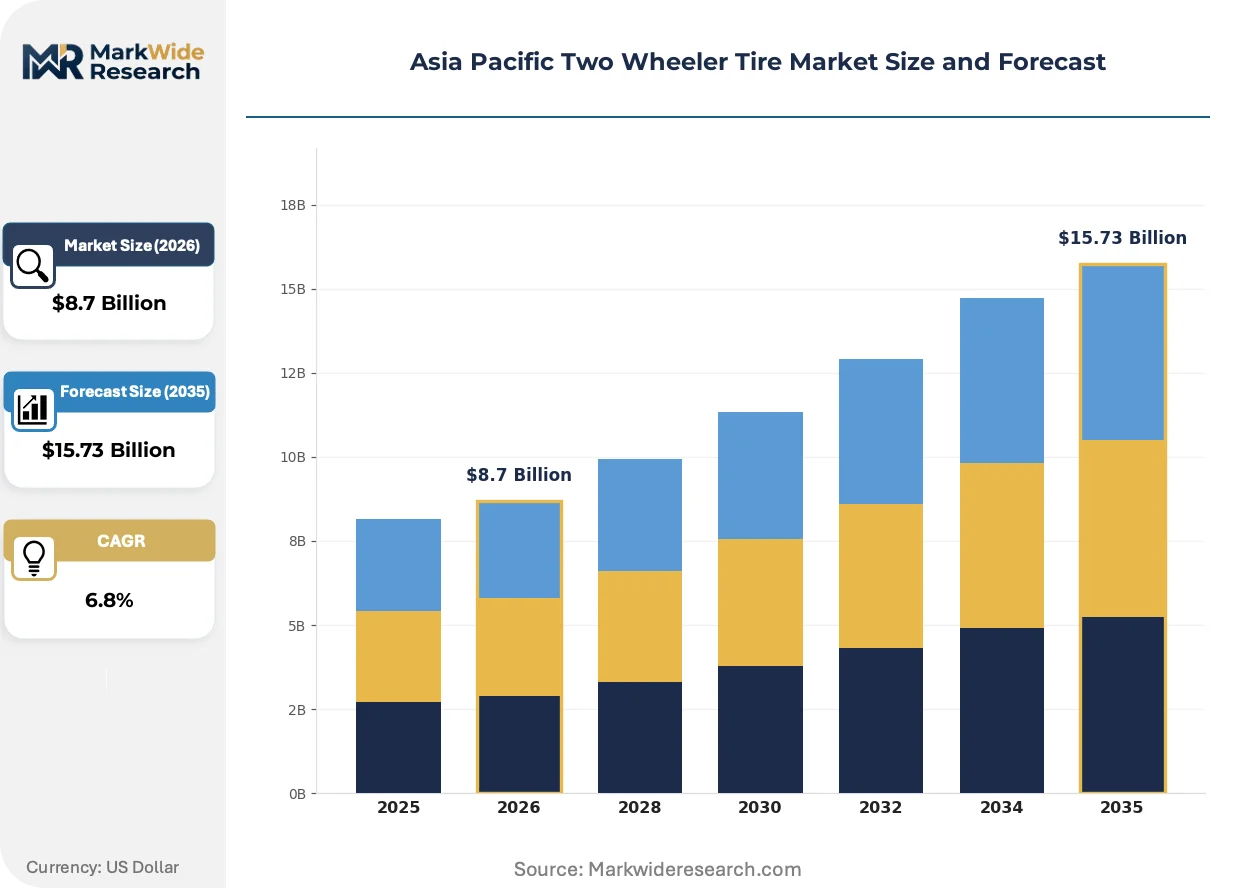
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube Tires, Tubeless Tires, Bias Tires, Radial Tires Material: Natural Rubber, Synthetic Rubber, Steel, Fabric End User: Motorcycle Riders, Scooter Owners, Delivery Services, Rental Services Distribution Channel: Online Retail, Authorized Dealers, Service Stations, Supermarkets |
| Companies Covered | Hangzhou Zhongce Rubber, Bridgestone Corporation, Michelin, MRF Limited, CEAT Limited, TVS Srichakra Limited, JK Tyre & Industries Ltd, Apollo Tyres Ltd, Cheng Shin Rubber, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Two Wheeler Tire Market Trends and Innovations
Material science advances and regulatory labeling convergence are redefining performance benchmarks across Asia Pacific two wheeler tire procurement. Manufacturers now compete on compound transparency and lifecycle traceability rather than durability claims alone.
Silica-reinforced tread compounds are migrating from premium motorcycle segments into mid-range scooter applications. Bangkok-based fleet operators now specify silica loading percentages in procurement tenders. This technology shift is compressing the performance gap between economy and standard tiers while forcing compound suppliers to disclose filler ratios.
Thailand's TISI safety labeling requirements for rolling resistance and wet grip are mandating reformulation across all domestic production. Manufacturers must submit tires for standardized testing before market release. Vietnamese and Indonesian regulators are studying TISI implementation timelines for potential harmonization, creating anticipatory compliance investment.
Delivery fleet procurement is consolidating around total-cost-of-ownership metrics rather than unit price. Grab and Gojek partner fleets in Jakarta now negotiate tire supply with wear-rate guarantees and replacement scheduling bundled. This behavioral shift is most visible in Indonesian and Vietnamese urban corridors where motorcycle utilization rates exceed 200 kilometers daily.
Asia Pacific Two Wheeler Tire Market Segmentation
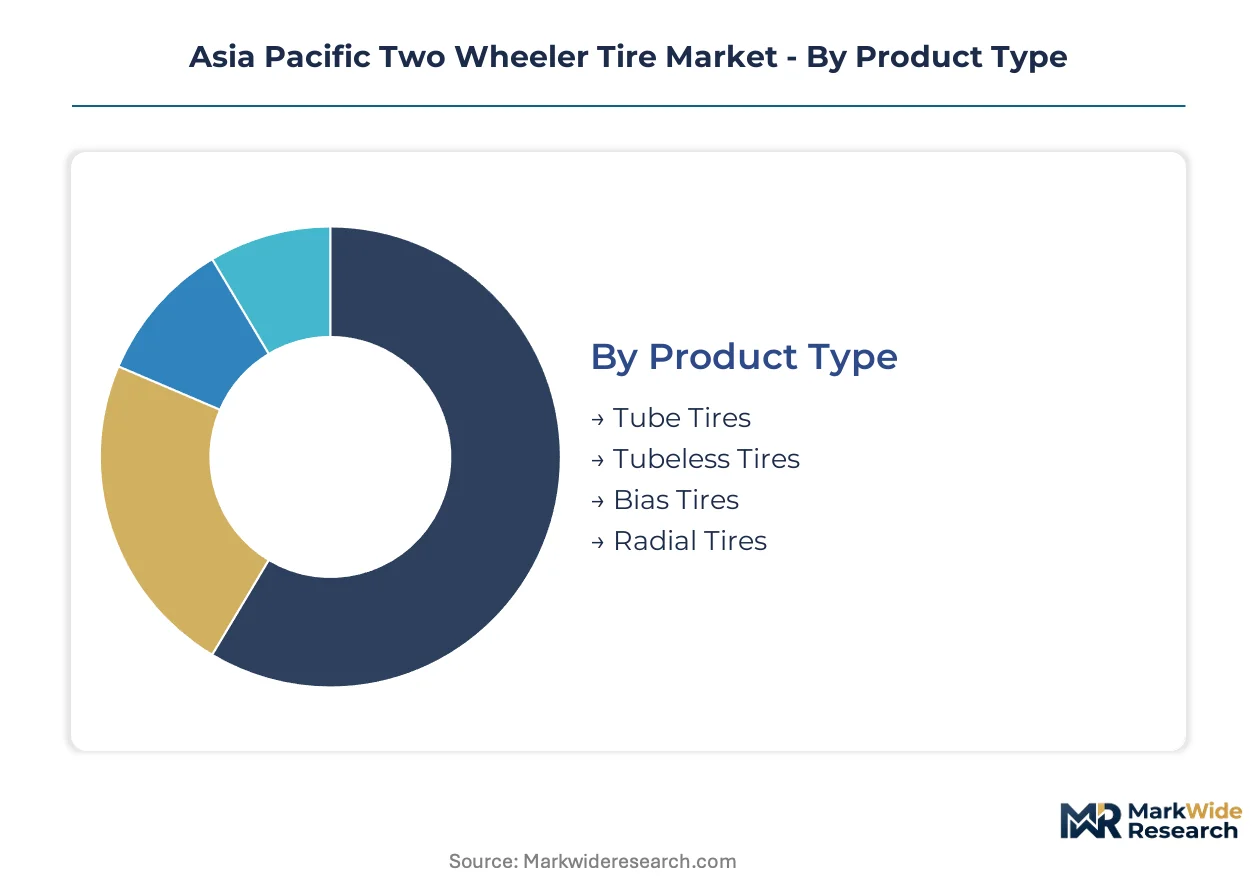
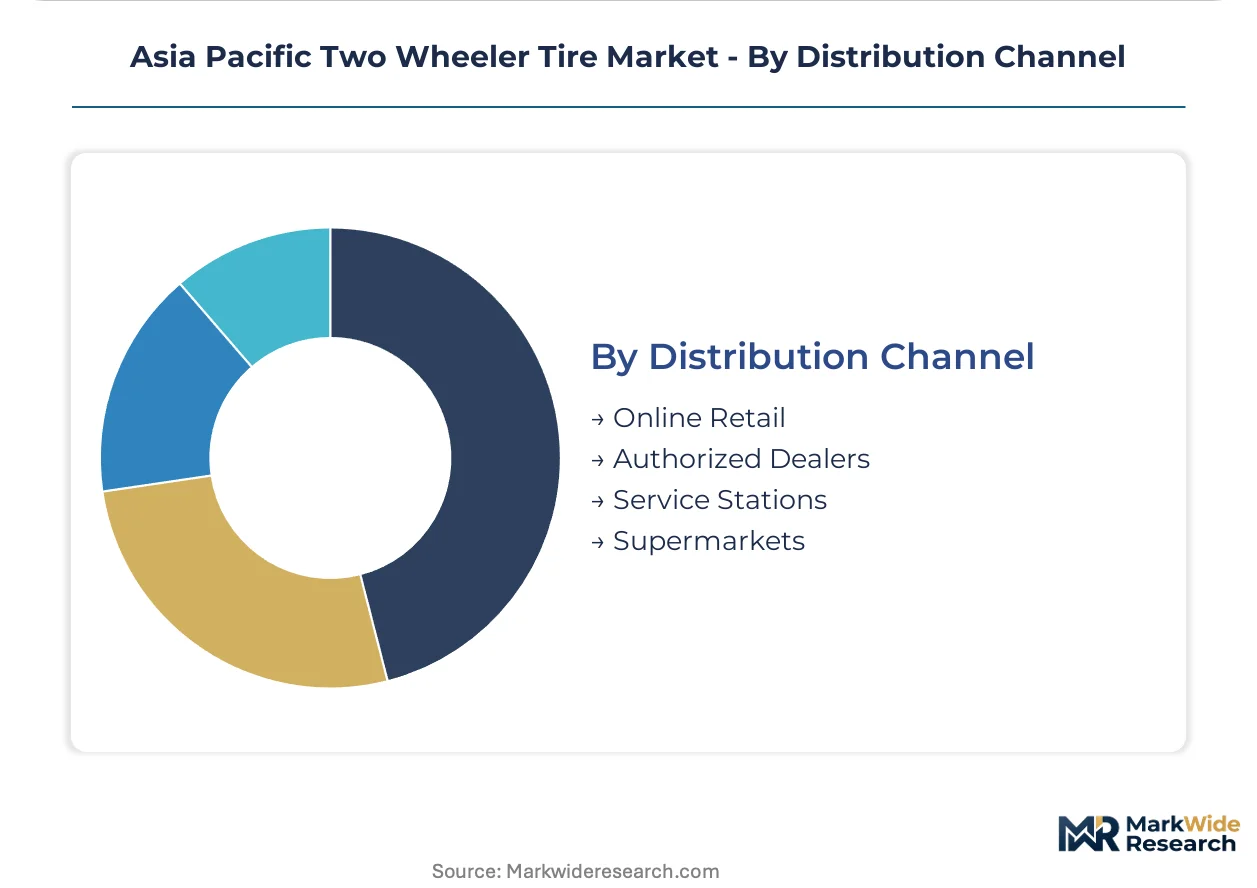
Segmentation in the Asia Pacific two wheeler tire market reveals divergent replacement cycles and margin profiles. Product architecture and distribution channel choices determine whether suppliers capture fleet volume or premium retail pricing.
Product Type:
Tubeless tires turn over fastest in urban delivery corridors, while bias construction persists longest in rural scooter applications.
- Tubeless Tires:Pneumatic structures eliminate inner tubes through airtight bead-to-rim sealing. Grab and Gojek partner fleets across Jakarta and Ho Chi Minh City mandate tubeless fitment for puncture resistance under 200-kilometer daily utilization. Replacement intervals compress to 8,000-12,000 kilometers versus 15,000+ for tubed alternatives.
- Radial Tires:Steel belt layers stabilize tread contact patches at highway speeds. Performance motorcycle ownership in Thailand and Malaysia drives adoption where riders prioritize cornering stability over cost minimization. BIS wet-grip certification requirements favor radial construction for premium positioning.
- Tube Tires:Inner tube construction dominates legacy scooter parc in Bangladesh and Sri Lanka where rim compatibility constraints block tubeless migration.
- Bias Tires:Cross-ply nylon cord layers deliver load capacity at lower manufacturing cost, retaining volume dominance in price-sensitive commuter segments across northern India.
Bias tires dominate installed base. Radial tires are where expansion concentrates.
Material:
Compound composition separates premium from economy tier positioning across procurement tenders.
- Natural Rubber:Polyisoprene harvested from Thai and Indonesian plantations provides elasticity and heat resistance. Bangkok-based fleet operators now specify natural rubber percentages in sustainability-linked procurement contracts.
- Synthetic Rubber:Styrene-butadiene copolymers enhance wear resistance under tropical humidity. Silica-reinforced SBR compounds are migrating from premium motorcycle into mid-range scooter applications as TISI labeling mandates tighten.
- Steel:Bead wire and belt plies provide structural integrity. Radial construction adoption in Malaysia and Thailand elevates steel tonnage per tire.
- Fabric:Nylon and polyester cord bodies in bias construction retain cost advantage for South Asian scooter OEM fitment.
Natural rubber anchors installed base. Synthetic rubber blends are climbing the fastest.
End User:
Utilization intensity varies tenfold between occasional private riders and commercial fleet operators.
- Delivery Services:Last-mile logistics operators across Bangalore, Jakarta, and Ho Chi Minh City standardize on motorcycles with compressed replacement cycles. Total-cost-of-ownership procurement now bundles wear-rate guarantees with scheduled replacement.
- Scooter Owners:Private commuter applications in tier-2 and tier-3 Indian towns drive replacement through wear rather than performance upgrading. Authorized dealer networks in Madhya Pradesh and Bihar remain underdeveloped.
- Motorcycle Riders:Enthusiast segments in Thailand and Malaysia prioritize wet-grip performance and radial construction for highway stability.
- Rental Services:Fleet operators in Singapore and Kuala Lumpur pilot sensor-integrated tires with pressure monitoring and tread wear algorithms for predictive maintenance.
Scooter owners dominate installed base. Delivery services are where expansion concentrates.
Distribution Channel:
Channel selection determines margin capture versus volume throughput for suppliers.
- Authorized Dealers:Branded replacement capture in tier-2 and tier-3 Indian towns depends on dense service networks. MRF Limited anchors competitiveness through authorized outlets spanning Gurugram to Chennai.
- Online Retail:E-commerce penetration accelerates in Indonesian and Vietnamese urban markets where fleet procurement managers compare compound specifications digitally.
- Service Stations:Quick replacement infrastructure dominates commuter corridors where riders prioritize convenience over brand loyalty.
- Supermarkets:Mass retail captures economy-tier private replacement in mature markets with established consumer tire literacy.
Service stations dominate installed base. Authorized dealers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Indonesian rubber belt concentration shapes regional supply resilience, while manufacturing clusters across Vietnam, India, and Malaysia absorb compound formulation investments. BIS, TISI, and QCVN regulatory divergence fragments certification pathways.
India
Urban delivery fleet densification across Gurugram, Bangalore, and Chennai compresses replacement intervals below 12,000 kilometers. BIS certification mandates for rolling resistance and wet-grip labeling force compound upgrades that elevate replacement channel pricing. The northern industrial corridor from Haryana through Tamil Nadu hosts captive mixing facilities serving both OEM fitment and aftermarket demand.
Thailand
Performance motorcycle ownership in Bangkok and Chiang Mai accelerates radial tire migration for highway stability applications. TISI safety labeling requirements for energy efficiency and wet grip mandate standardized testing submissions before market release. Eastern Seaboard manufacturing clusters face monsoon-related logistics exposure that regional procurement managers hedge through dual-sourcing arrangements.
Vietnam
Ho Chi Minh City delivery operators running 200-kilometer daily utilization rates standardize tubeless fitment for puncture resistance. QCVN technical regulations for two wheeler tire safety create compliance windows for pre-certified compound portfolios. Northern industrial zones around Hai Phong attract mixing capacity investments targeting ASEAN export qualification.
Indonesia
Jakarta-based Grab and Gojek partner fleets negotiate total-cost-of-ownership contracts bundling wear-rate guarantees with scheduled replacement. Natural rubber price volatility from Sumatran plantation supply directly compresses manufacturer margins for non-integrated producers. Jababeka and MM2100 industrial estates host vulcanization capacity serving domestic replacement and regional re-export.
Malaysia
Kuala Lumpur fleet operators pilot sensor-integrated tires with pressure monitoring algorithms for predictive maintenance scheduling. METI-aligned energy efficiency guidelines from Japanese OEM partners constrain import eligibility for non-compliant suppliers. Shah Alam manufacturing corridors anchor radial production for premium motorcycle segments serving Thailand re-export demand.
Asia Pacific Two Wheeler Tire Market Competitive Landscape
Pan-Asian rubber conglomerates and Japanese precision manufacturers split the market into supply-security and performance-innovation camps. The vendor base organizes around three strategic archetypes: plantation-integrated compounders controlling upstream latex supply, R&D-heavy multinationals patenting tread formulations, and dense-network domestic specialists capturing tier-3 replacement access. Competitive moves concentrate on backward integration into Indonesian and Thai rubber assets, alongside authorized dealer network expansion across Indian secondary cities.
Within the plantation-integrated tier, Hangzhou Zhongce Rubber and Cheng Shin Rubber exemplify supply-security positioning through captive sourcing advantages. Bridgestone Corporation occupies the precision-manufacturing archetype with advanced compound R&D capabilities. MRF Limited anchors the dense-network specialist model through tier-2 and tier-3 Indian town penetration. These three patterns represent the dominant competitive configurations shaping regional procurement negotiations.
| Leading Market Players |
|---|
| Hangzhou Zhongce Rubber |
| Bridgestone Corporation |
| Michelin |
| MRF Limited |
| CEAT Limited |
| TVS Srichakra Limited |
| JK Tyre & Industries Ltd |
| Apollo Tyres Ltd |
| Cheng Shin Rubber |
| Others |
Pricing and Supply Chain Analysis
Eastern Seaboard manufacturing clusters around Rayong and Chonburi concentrate vulcanization capacity for radial and bias construction alike, granting integrated producers pricing leverage over non-captive competitors during natural rubber futures volatility. This geographic concentration compresses margins for distributors in Bangladesh and Sri Lanka who lack backward integration into Thai or Indonesian plantation supply.
Pricing Analysis
BIS certification mandates dictate the pricing tier structure across India's replacement channel, separating certified wet-grip compounds from uncertified economy alternatives. Three-tier pricing structure across premium radial, standard tubeless, and economy bias levels reflects compound transparency and testing queue access. Cost compression in the economy tier is intensifying because legacy tubed inventory faces obsolescence write-downs. Delivery fleet procurement managers show least price sensitivity due to total-cost-of-ownership contracting, while private scooter owners in tier-3 towns remain most responsive to unit price.
Supply Chain Analysis
Export-control regimes on steel bead wire and advanced silica fillers limit technology transfer to non-ASEAN manufacturing bases, constraining radial production expansion. Thailand, Indonesia, and Vietnam anchor natural rubber supply, while India and Malaysia absorb compound formulation investments. The chain draws from polyisoprene latex, styrene-butadiene copolymers, and steel cord inputs. Single-source vulnerability concentrates in Eastern Seaboard logistics corridors exposed to monsoon disruption. Distribution runs through authorized dealer networks in Indian tier-2 towns and fleet procurement offices in Jakarta and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific two wheeler tires sit in early-cycle expansion as radial construction penetrates performance motorcycle segments and sensor-integrated smart tires pilot in Singapore and Kuala Lumpur fleet applications.
For Market Incumbents: Insulate margin position through captive sourcing of Indonesian and Thai natural rubber assets to offset futures volatility. Defend against Hangzhou Zhongce Rubber's plantation-integrated cost structure by accelerating BIS certification for premium wet-grip compounds, creating regulatory moats in India's replacement channel.
For New Entrants and Emerging Players: Build out authorized service networks in Madhya Pradesh, Bihar, and Odisha where branded replacement capture remains underdeveloped. Target delivery fleet procurement in Vietnamese urban corridors ahead of full QCVN enforcement, leveraging pre-certified compound portfolios as first-mover qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators bundling wear-rate guarantees with scheduled replacement in Indonesian and Vietnamese markets. Five-to-ten year viability favors plantation-integrated compounders with mixing capacity in northern Indian industrial zones. Monitor silica-reinforced compound adoption rates in Bangkok fleet tenders as inflection signal for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive natural rubber supply insulates margins against Thai and Indonesian futures volatility. |
| BIS Certification Investment | Pre-certified wet-grip compounds unlock premium positioning in India's replacement channel. |
| Sensor-Integrated Smart Tire Development | Pressure monitoring algorithms enable predictive maintenance contracts with Singapore fleet operators. |
| Tier-3 Indian Town Network Expansion | Authorized dealer density in Madhya Pradesh and Bihar captures branded replacement whitespace. |
| QCVN Pre-Compliance Positioning | Pre-certified portfolios secure first-mover advantage ahead of Vietnamese technical regulation enforcement. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with tire manufacturing executives, rubber procurement leads at plantation-integrated producers, fleet procurement managers at Grab and Gojek partners, and authorized dealer network heads in Indian tier-2 towns; alongside secondary validation through BIS certification databases, TISI testing submissions, Thai rubber futures exchange records, and customs trade data for natural rubber and finished tire flows. Bottom-up volume estimates from replacement cycle modeling triangulated against top-down market sizing from production capacity analysis.
Forecast inputs span product architecture migration from bias to radial construction, regulatory enforcement timelines for BIS and QCVN compliance, and fleet utilization intensity across Indonesian and Vietnamese urban corridors. Segmentation dimensions modeled include tire construction type, compound composition tier, end-user utilization profile, and distribution channel density. CAGRs derive from replacement cycle compression rates and premium tier penetration curves.
Practitioners should monitor natural rubber futures volatility, monsoon-related Eastern Seaboard logistics disruption, and silica filler supply constraints for early signals of forecast revision. Material shifts in ASEAN regulatory harmonization timelines or Indian BIS testing queue capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Wheel Market
Tires and Wheels
Airless Tires Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Off-The-Road (OTR) Tire Market