
 Global Advanced Tires Market | 2026-2036
Global Advanced Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Tires Market Analysis
Silica-silane coupling is shifting the reinforcement economics of advanced tire compounds away from conventional carbon black loadings. Michelin leverages proprietary solution-polymerized styrene-butadiene rubber formulations to sustain wet-grip performance in performance segments. Bridgestone anchors its position through backward integration into synthetic rubber production across Southeast Asian feedstock zones. Continental AG differentiates via integrated sensor architectures that embed pressure and temperature monitoring within run-flat carcass structures.
Advanced tires integrate multi-layer carcass constructions, tread compounds with glass-transition temperatures tuned to operating climates, and bead-to-bead reinforcement systems to deliver load-bearing capacity, fuel efficiency, and safety margins under dynamic stress conditions. OEM procurement of smart tire variants with embedded RFID and pressure-monitoring transponders is accelerating as connected-vehicle architectures mandate real-time wheel-end data streams. Eco-friendly tread formulations utilizing bio-sourced oils and reclaimed carbon black occupy expanding shelf space in European retail channels where lifecycle carbon scoring influences consumer selection. Off-road segments for mining and agricultural machinery retain premium pricing power due to specialized carcass durability requirements and limited supplier certification pools.
The EPA regulates tire rolling resistance through corporate average fuel economy standards, while the EU F-Gas Regulation constrains blowing agents in tire manufacturing processes. China's MIIT enforces GB standards for tire labeling and energy efficiency grades that condition market access for imported products. Stakeholders must monitor evolving chemical restriction schedules across REACH, state-level California tire recycling mandates, and Japan's METI carbon-footprint disclosure requirements for automotive components.
Market Dynamics
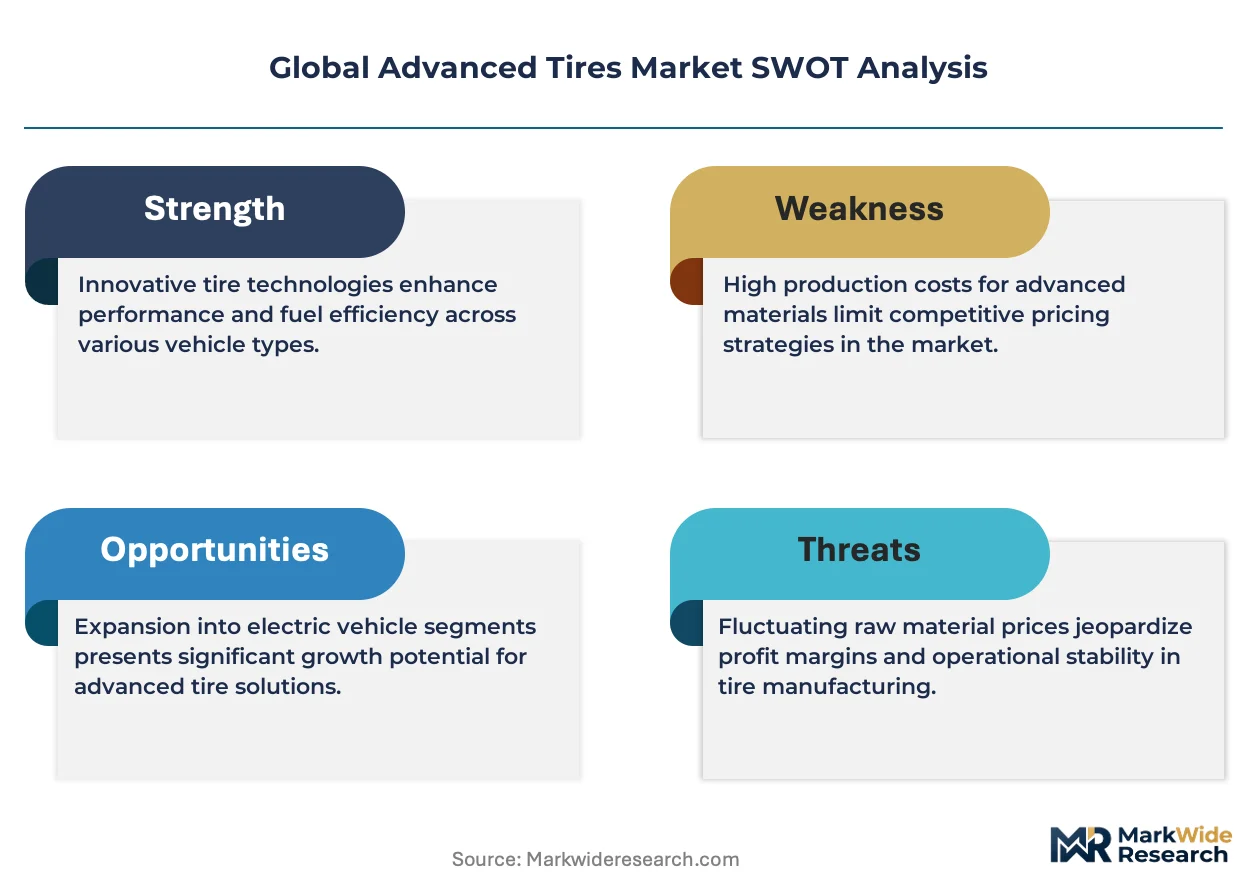
EU REACH chemical restrictions and China's dual carbon goals are forcing compound reformulation across the tire value chain, compressing lead times for sustainable material qualification while OEMs accelerate low-rolling-resistance specifications for electric vehicle platforms.
Growth Catalysts
- Electric vehicle platform expansion:OEM procurement teams are mandating low-rolling-resistance compounds for battery-electric drivetrains, pulling advanced silica-silane formulations into high-volume production schedules.
- REACH Annex XVII amendments:Restrictions on polycyclic aromatic hydrocarbons in extender oils are redirecting R&D spending toward bio-sourced alternatives and reclaimed carbon black processing.
- Smart tire mandates:Connected-vehicle architectures are embedding RFID and pressure-monitoring transponders as standard equipment, creating captive demand for sensor-integrated carcass designs.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to weather-driven harvest disruptions and speculative trading swings.
- Synthetic rubber feedstock lock-in:Southeast Asian butadiene and styrene production clusters limit geographic diversification for solution-polymerized styrene-butadiene rubber sourcing.
- Run-flat durability thresholds:Extended mobility requirements impose bead-to-bead reinforcement specifications that increase unit weight and material intensity.
Strategic Opportunities
- India commercial vehicle fleet modernization:BIS tire labeling standards and energy efficiency grades are creating first-mover advantages for premium compound suppliers entering the replacement channel.
- Agricultural tire digitalization:Pressure-monitoring systems for high-horsepower tractors enable yield-optimization services tied to soil compaction data.
- EU F-Gas Regulation phase-down:Blowing agent restrictions are accelerating investment in water-based foaming and physical expansion technologies for tire cavity insulation.
Industry Challenges
- Silica dispersion expertise scarcity:Wet-grip compound development requires specialized rheology and mixing process knowledge that outpaces current technical training pipelines.
- Multi-material recycling complexity:Steel bead wires, textile plies, and heterogeneous rubber blends complicate end-of-life processing and circular material recovery economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Tires Market |
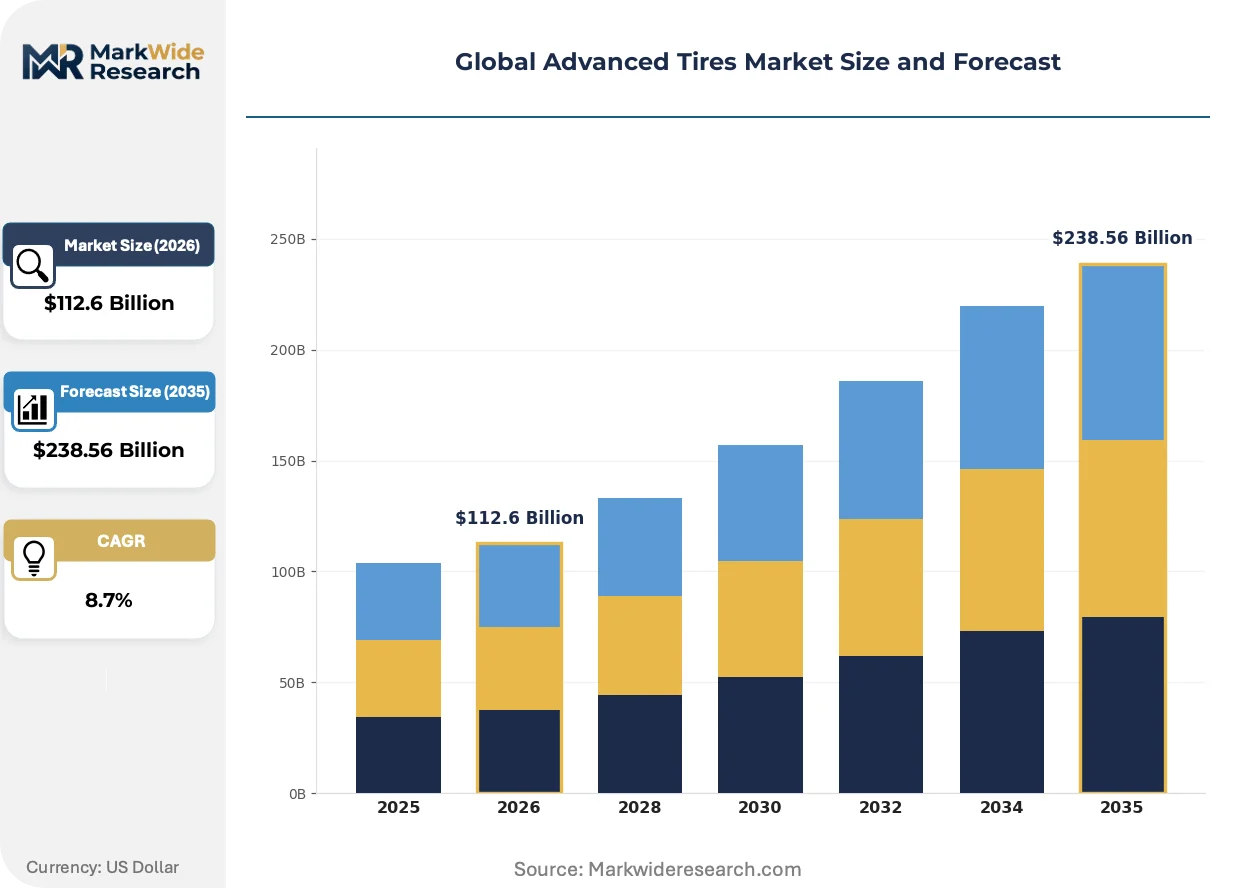
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season, Winter, Performance, Off-Road End User: OEMs, Commercial Fleets, Retail Consumers, Aftermarket Providers Material: Rubber Compounds, Synthetic Fibers, Metal Reinforcements, Nanomaterials Technology: Run-Flat, Smart Tires, Eco-Friendly, Self-Sealing |
| Companies Covered | Bridgestone Corporation, Michelin, Continental AG, The Goodyear Tire & Rubber Company, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Ltd., THE YOKOHAMA RUBBER CO., LTD., Hankook Tire & Technology Co., Ltd., Toyo Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Tires Market Emerging Trajectories
Material science breakthroughs and embedded sensor architectures are converging to redefine performance benchmarks across passenger, commercial, and off-road segments, compressing traditional development cycles.
Silica-silane coupling chemistry is integrating with solution-polymerized styrene-butadiene rubber matrices to deliver simultaneous gains in wet-grip and rolling-resistance metrics. Tier-one suppliers are qualifying these compounds for original equipment fitments on premium electric vehicle platforms. The technology is integrating tread formulation and carcass design into unified performance optimization workflows rather than sequential specification stages.
China's MIIT GB standards for tire labeling and energy efficiency grades are conditioning market access for imported products, forcing foreign manufacturers to establish local testing and certification capabilities. Domestic producers are leveraging this regulatory friction to defend shelf space in domestic replacement channels. The policy is reshaping competitive intensity most acutely in the standard passenger segment where grade differentiation influences fleet procurement decisions.
Fleet operators are consolidating tire procurement through direct manufacturer contracts with embedded lifecycle cost guarantees, bypassing traditional wholesale distribution layers. This channel compression is displacing independent dealer networks in long-haul trucking and urban delivery verticals. The pattern is concentrating most visibly in Germany and the United States where telematics-enabled wear tracking supports outcome-based contract structures.
Global Advanced Tires Market Segmentation
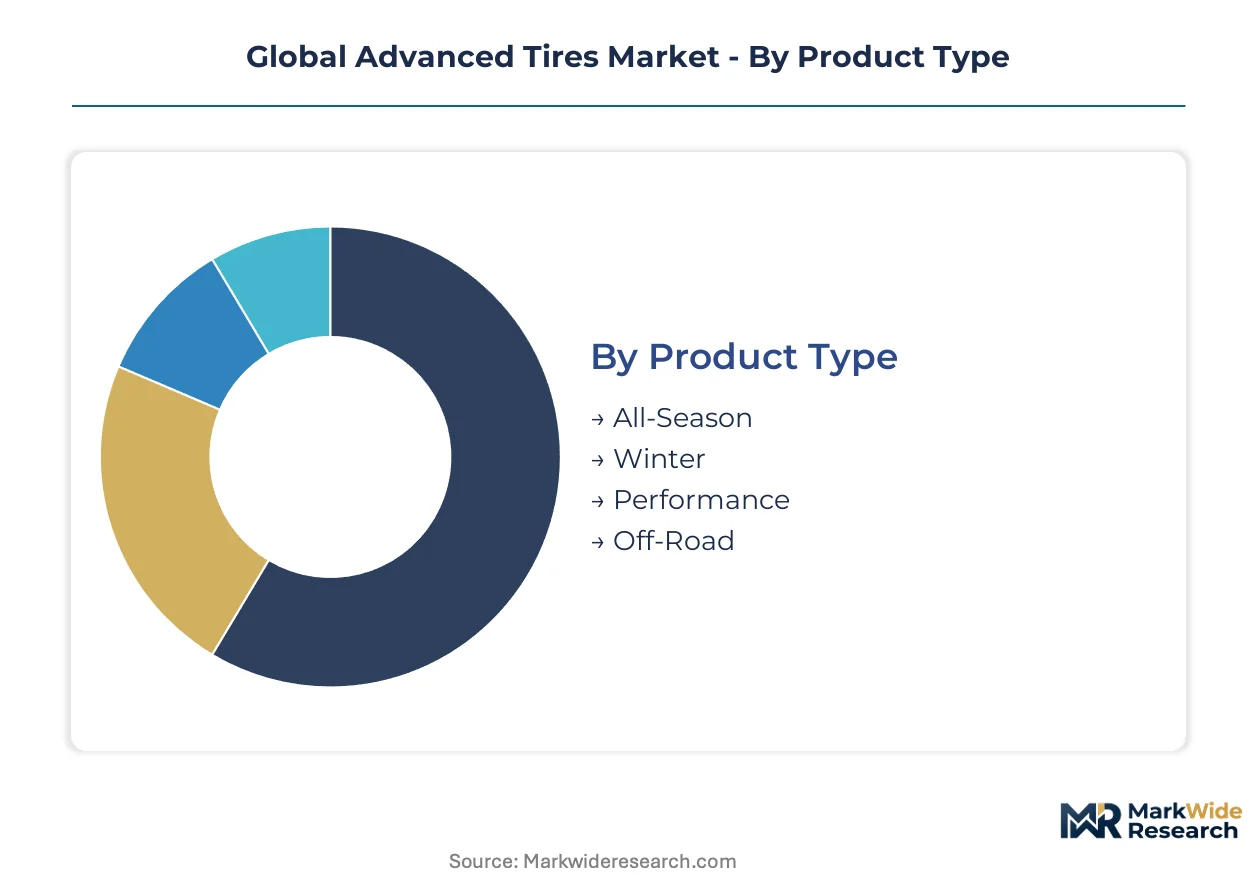
Advanced tire segmentation reflects competing performance mandates across electric vehicle platforms, connected-vehicle architectures, and regulatory compliance tiers. Compound chemistry, sensor integration, and carcass construction each create distinct value propositions that reshape procurement patterns across OEM and replacement channels.
Product Type:
Seasonal performance specifications and terrain specialization define the product architecture, with compound glass-transition temperatures and tread patterns optimized to distinct operating envelopes.
- All-Season:Tread formulations balance wet-grip silica loadings with low-rolling-resistance polymers for temperate climate operation. OEM procurement from Germany, Japan, and the United States concentrates volume in passenger electric vehicle fitments where efficiency grades influence fleet purchasing.
- Winter:Soft-compound constructions with high natural rubber content maintain elasticity below glass-transition thresholds. Nordic markets and alpine regions in Germany and Japan sustain premium pricing through mandatory cold-weather performance certification.
- Performance:Asymmetric tread designs and aramid-reinforced belts deliver lateral stiffness for high-speed stability.
- Off-Road:Deep-lug patterns and cut-resistant sidewall compounds address mining and agricultural machinery durability requirements.
Mature deployment sits with All-Season variants. Newer deployment is concentrated in Performance segments serving electric vehicle torque characteristics.
End User:
Procurement authority is fragmenting across direct manufacturer contracts, fleet lifecycle agreements, and retail self-selection channels with divergent specification priorities.
- OEMs:Platform-integrated tire programs mandate embedded sensors and rolling-resistance certification as standard equipment. German and Japanese vehicle manufacturers specify silica-silane compounds and run-flat carcasses for premium electric vehicle architectures.
- Commercial Fleets:Telematics-enabled wear tracking supports outcome-based contracts with lifecycle cost guarantees. Long-haul operators in the United States and Germany bypass wholesale distribution through direct manufacturer relationships.
- Retail Consumers:Lifecycle carbon scoring and energy efficiency labels influence replacement channel selection in European markets.
- Aftermarket Providers:Independent dealer networks retain position in standard passenger segments where grade differentiation matters less.
Volume concentrates with OEMs and Commercial Fleets. Margin expansion is climbing the fastest in direct fleet contracts with embedded service guarantees.
Material:
Feedstock chemistry and reinforcement architectures determine performance ceilings, with sustainable material qualification compressing traditional compound development timelines.
- Rubber Compounds:Solution-polymerized styrene-butadiene rubber matrices integrate with silica-silane coupling for simultaneous wet-grip and efficiency gains. Thai and Indonesian natural rubber supply concentration exposes compounders to harvest volatility.
- Synthetic Fibers:Aramid and polyester ply materials reduce carcass weight while maintaining dimensional stability under dynamic stress. Textile integration with bead-to-bead reinforcement systems addresses run-flat durability thresholds.
- Metal Reinforcements:Steel bead wires and belt plies deliver load-bearing capacity for commercial vehicle applications.
- Nanomaterials:Graphene and carbon nanotube additives enhance thermal conductivity and abrasion resistance in high-performance tread formulations.
Established supply chains dominate Rubber Compounds. Emerging qualification efforts concentrate on Nanomaterials for next-generation efficiency targets.
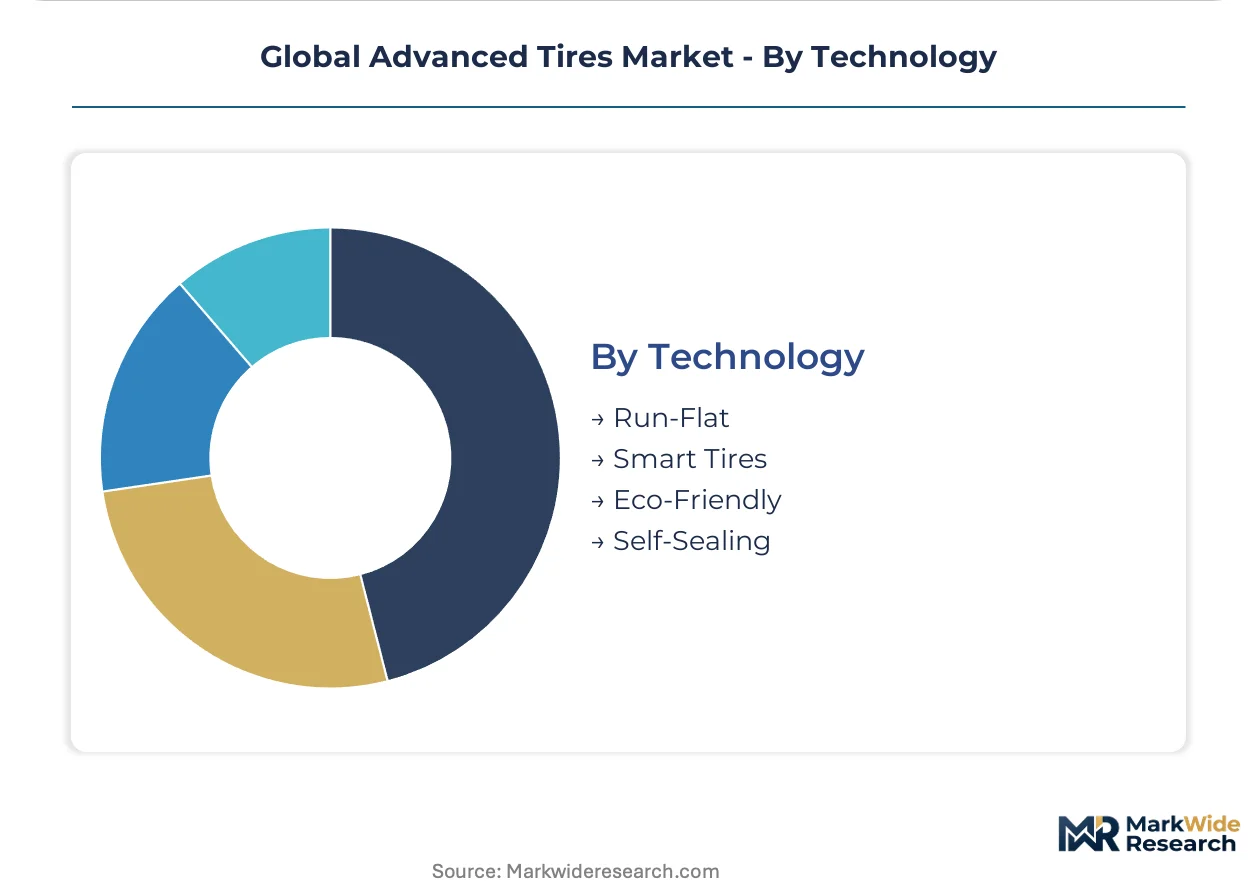
Technology:
Embedded functionality and sustainable manufacturing processes are converging to redefine baseline specifications across regulatory jurisdictions.
- Run-Flat:Bead-to-bead reinforcement systems and heat-resistant sidewall inserts sustain vehicle mobility following pressure loss. Extended mobility requirements increase unit weight and material intensity, constraining adoption in efficiency-focused electric vehicle platforms.
- Smart Tires:RFID transponders and pressure-monitoring sensors generate real-time wheel-end data streams for connected-vehicle architectures. OEM mandates from Germany, Japan, and the United States are accelerating sensor-integrated carcass designs.
- Eco-Friendly:Bio-sourced oils and reclaimed carbon black formulations address EU REACH chemical restrictions and China's dual carbon goals.
- Self-Sealing:Internal sealant layers polymerize upon puncture to maintain pressure without driver intervention.
Regulatory pressure is expanding fastest in Eco-Friendly formulations. Technology integration is deepest in Smart Tires serving connected-vehicle data requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free-trade zones in Thailand and Indonesia concentrate natural rubber processing for global compounders, while Germany's automotive corridors anchor premium tire R&D infrastructure. China's coastal manufacturing belts integrate MIIT certification laboratories with export-oriented production. These spatial configurations condition how regulatory regimes and supply chain nodes interact across national boundaries.
United States
Long-haul fleet operators in Texas and the Midwest are consolidating procurement through direct manufacturer contracts with embedded telematics tracking. EPA corporate average fuel economy standards mandate rolling-resistance thresholds that condition OEM fitment decisions. The Southeast manufacturing corridor spanning South Carolina and Georgia hosts carcass production facilities serving German and Japanese vehicle assembly plants.
Germany
KBA type-approval requirements for winter tire performance sustain premium pricing in alpine and Nordic export markets. EU REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons redirect extender oil sourcing toward bio-based alternatives. The Baden-Württemberg and Bavaria automotive clusters integrate tire testing facilities with OEM development centers for electric vehicle platform calibration.
China
MIIT GB standards for tire labeling and energy efficiency grades condition market access for imported products, forcing foreign manufacturers to establish local certification capabilities. The dual carbon goals accelerate reclaimed carbon black processing investments in Shandong and Jiangsu provinces. Yangtze River Delta production hubs concentrate silica-silane compound manufacturing for domestic electric vehicle supply chains.
Japan
METI carbon-footprint disclosure requirements for automotive components shape procurement specifications from domestic vehicle manufacturers. Solution-polymerized styrene-butadiene rubber expertise concentrates in Kansai and Chubu industrial zones. The Kanto region anchors smart tire sensor development integrated with connected-vehicle architectures from Tokyo-based OEMs.
India
BIS tire labeling standards and energy efficiency grades create first-mover advantages for premium compound suppliers entering the commercial vehicle replacement channel. Maharashtra and Gujarat manufacturing corridors scale production to serve domestic fleet modernization programs. Tamil Nadu automotive clusters integrate tire testing with OEM platform development for export-oriented vehicle assembly.
Global Advanced Tires Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium OEM fitments consolidating around integrated compound-and-carcass developers while replacement channels retain fragmentation. The vendor base organizes into three tiers: multinational integrated suppliers with backward rubber production control, regional compound specialists serving fleet procurement, and private-label assemblers for price-sensitive retail. Dominant competitive moves include captive supply integration into Southeast Asian feedstock zones and technology licensing agreements for silica-silane formulation expertise.
Within the integrated multinational tier, Bridgestone Corporation and Michelin exemplify archetypes of feedstock control and proprietary compound development respectively. Continental AG occupies a position representing sensor-integrated carcass specialization. These three entities anchor competitive dynamics through their distinct strategic postures: one through upstream rubber plantation and synthetic production assets, another through solution-polymerized styrene-butadiene rubber formulation IP, and the third through embedded electronics integration for connected-vehicle data architectures.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries, Ltd. |
| THE YOKOHAMA RUBBER CO., LTD. |
| Hankook Tire & Technology Co., Ltd. |
| Toyo Tire Corporation |
| Others |
Supply Flow & Price Mechanics
Natural rubber feedstock costs flow from Thai and Indonesian plantation belts through compounders in Southeast Asia, accumulating margin layers at each processing stage before reaching three-tier pricing structures across premium, standard, and economy levels in replacement channels.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with OEMs paying premiums for qualified compound delivery inside compressed electric vehicle platform schedules while spot inventory in replacement channels trades at discounts. Price differentiation rests on silica-silane formulation certification and run-flat carcass integration tiers. Pricing pressure stems from REACH Annex XVII reformulation mandates forcing R&D cost absorption. Fleet buyers exhibit lowest price sensitivity due to lifecycle cost guarantees, while independent retail consumers show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese OEMs mandate multi-supplier qualification for solution-polymerized styrene-butadiene rubber matrices, preventing single-feedstock dependency. Geographic supply concentration centers on Thailand, Indonesia, and Malaysia for natural rubber, with China and South Korea anchoring synthetic production. Raw material dependencies include butadiene monomer, silica particulates, and aramid textile plies. Single-source vulnerability concentrates in Southeast Asian harvest zones exposed to climate disruption. Distribution runs through direct manufacturer contracts for fleet operators and wholesale dealer networks for retail replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compound-and-carcass integration capabilities, with EU REACH chemical restrictions and China's dual carbon goals forcing sub-scale compounders toward exit or acquisition.
For Market Incumbents: Deploy captive supply integration into Southeast Asian feedstock zones to secure natural rubber volumes against harvest volatility. Accelerate silica-silane formulation IP licensing to capture revenue from competitors facing REACH compliance deadlines. Capacity addition in Shandong and Jiangsu provinces positions suppliers for MIIT GB standard certification proximity. For New Entrants and Emerging Players: Sensor-integrated carcass architectures offer technology-first wedge opportunities as OEMs mandate embedded RFID and pressure-monitoring transponders. Agricultural tire digitalization for high-horsepower tractors presents the most penetrable segment, with yield-optimization services enabling software-recurring revenue models alongside hardware sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional compound specialists with BIS certification in Maharashtra and Gujarat corridors as India's commercial fleet modernization accelerates. Long-term viability hinges on sustainable material qualification pipelines and backward rubber production control. Watch silica dispersion expertise scarcity as the inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Production | Bridgestone's Southeast Asian feedstock control insulates margin from butadiene price volatility. |
| Silica-Silane Formulation Licensing | Michelin's proprietary S-SBR IP generates recurring revenue from REACH-driven compound reformulation. |
| Smart Tire Sensor Platform Development | Continental's integrated architectures capture OEM mandates for connected-vehicle data streams. |
| Reclaimed Carbon Black Processing Investment | Shandong province facilities align with China's dual carbon goals for domestic EV supply chains. |
| Direct Fleet Contract Consolidation | Telematics-enabled wear tracking displaces wholesale layers in Texas and Midwest long-haul corridors. |
Methodological Framework
Trade databases, customs filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews spanning tire compound R&D directors, OEM platform procurement managers, aftermarket distributor operations heads, and fleet maintenance supervisors. Bottom-up and top-down triangulation validated volume estimates against production capacity disclosures and vehicle registration data.
Bottom-up modeling aggregated segment-level unit economics across product type, end user, material, and technology dimensions, while top-down approaches benchmarked against automotive production clusters and replacement cycle assumptions. CAGRs were derived from regression analysis of historical pricing trajectories and forward-looking regulatory compliance cost curves, with silica-silane adoption rates and electric vehicle platform ramp schedules as key forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including speculative natural rubber futures positions, force majeure events in Southeast Asian processing zones, and unannounced REACH Annex XVII amendment schedules. Deviation in EU F-Gas Regulation phase-down timing or China's MIIT certification reciprocity agreements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
EV Tire Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
Bicycle Rim Brake Market