
 Global High Performance Tires Market | 2026-2036
Global High Performance Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Tires Market Intelligence
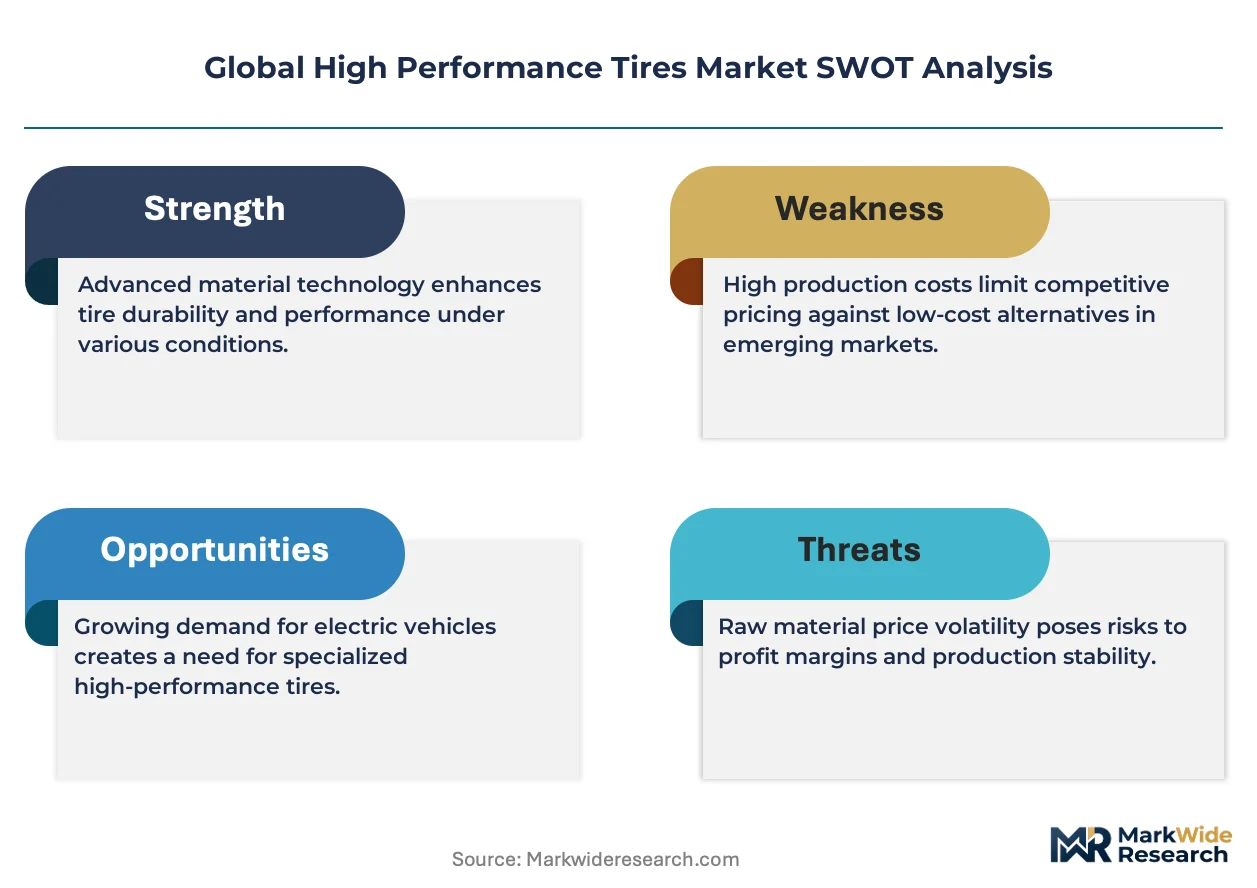
Motorsports procurement is hardening as factory-backed racing series expand technical partnerships with tire suppliers. Michelin leverages vertical integration in motorsport supply chains to sustain premium positioning across endurance and open-wheel categories. Continental AG competes through R&D intensity in connected tire architectures, while Pirelli & C. S.p.A. dominates single-supply racing contracts that anchor brand credibility in consumer markets.
High performance tires incorporate specialized tread compounds, asymmetric patterns, and reinforced sidewalls engineered for sustained operation above standard speed ratings. Their primary purpose centers on delivering enhanced grip, thermal stability, and steering response under aggressive driving conditions across passenger vehicles and motorsports applications. Summer tires occupy the dominant margin pool in warm-climate markets, while all-season variants are capturing share in temperate regions where consumers prioritize year-round convenience over peak performance. Track tires represent a concentrated niche where low-volume production sustains premium pricing through motorsport homologation requirements.
EU REACH and F-Gas Regulation constrain fluorinated compound use, compelling reformulation of high-grip tread polymers. NHTSA speed-rating enforcement and EPA rolling-resistance benchmarks in the United States shape product development priorities for cross-border manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance-driven material cost shifts and speed-to-market timelines.
Market Dynamics
Factory-backed motorsport contracts are hardening procurement relationships between tire suppliers and racing series, locking in multi-year technical partnerships that cascade specifications into consumer-grade product lines. This supply-side concentration is reshaping competitive positioning across endurance, open-wheel, and touring car categories.
Growth Catalysts
- Motorsport homologation pipelines:Racing series technical partnerships validate tread compounds and construction methods for road-legal derivatives. Factory-backed contracts in endurance racing accelerate consumer product development cycles.
- REACH-compliant silica formulations:EU regulatory pressure on fluorinated compounds is redirecting R&D investment toward sustainable high-grip polymers. Reformulated tread compounds maintain wet grip ratings while satisfying ECHA substance restrictions.
- OEM performance variant expansion:Passenger vehicle manufacturers are expanding factory fitment of speed-rated tires on sport trims and performance packages. Germany, Japan, and the United States show concentrated OEM specification activity.
Market Restraints
- Petrochemical input volatility:Synthetic rubber and carbon black prices fluctuate with crude oil derivatives, compressing margin predictability for compound-dependent manufacturers.
- Single-supplier contract concentration:Exclusive racing series tire contracts limit market access for secondary suppliers, concentrating technical validation pathways with incumbent holders.
- Speed rating certification costs:NHTSA enforcement of uniform tire quality grading requires expensive laboratory testing infrastructure, raising barriers for regional manufacturers.
Strategic Opportunities
- Connected tire architectures:Integration of pressure monitoring, temperature sensing, and wear prediction into tire construction creates data service revenue streams. Continental AG and competitors are patenting embedded sensor layouts.
- All-season performance white space:Temperate-climate consumers in the northeastern United States and northern Europe are accepting modest dry-grip trade-offs for year-round convenience.
- IRA domestic content incentives:United States manufacturing tax credits for clean energy supply chains could subsidize domestic compound production and mixing facilities.
Industry Challenges
- Compound formulation talent scarcity:Specialized polymer chemistry expertise for high-grip, low-rolling-resistance combinations commands premium compensation and limited graduate pipeline output.
- Homologation timeline compression:Racing series technical regulation changes require rapid retooling of production molds and compound batches, straining quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Tires Market |
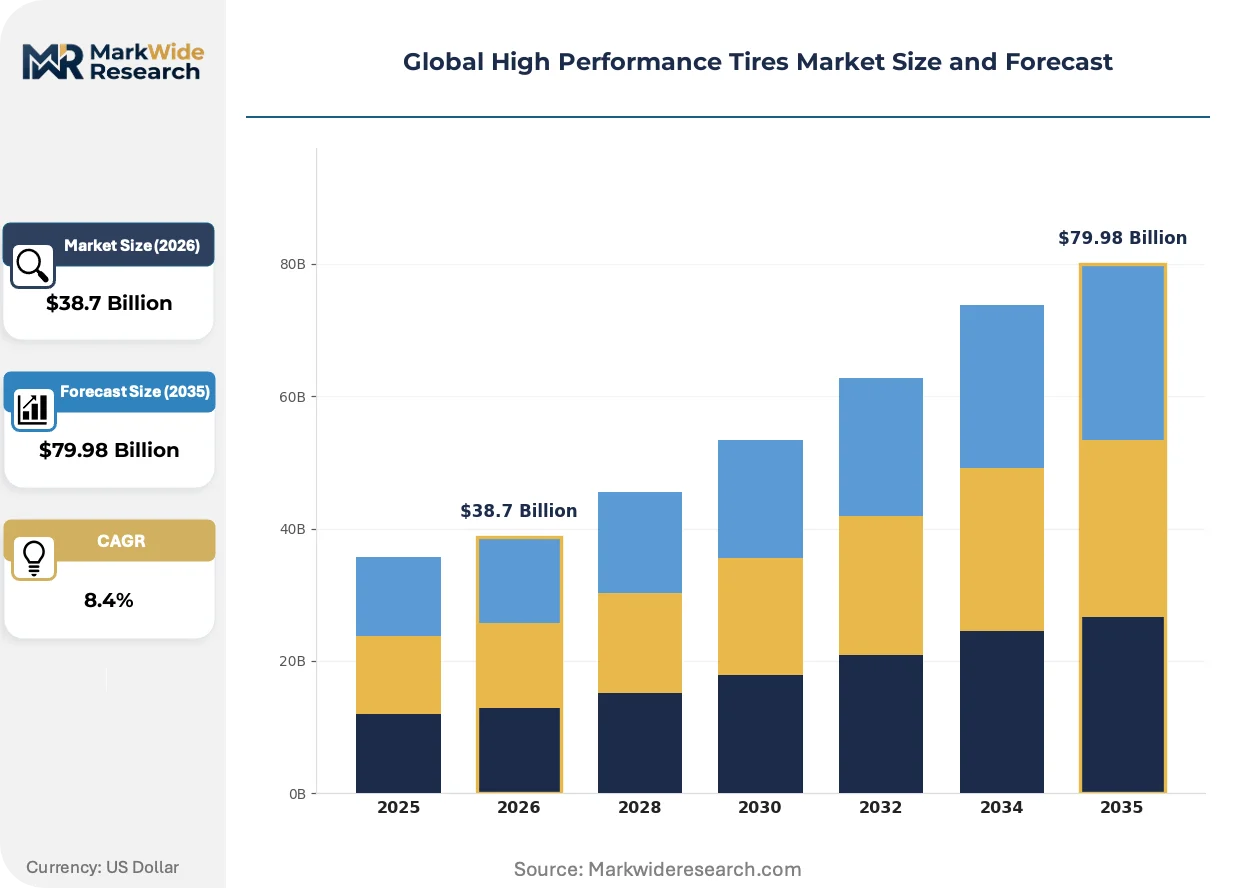
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Summer Tires, Winter Tires, All-Season Tires, Track Tires End User: Passenger Vehicles, Light Trucks, SUVs, Motorsports Technology: Run Flat Technology, Noise Reduction, Eco-Friendly Materials, Low Rolling Resistance Distribution Channel: Online Retail, Specialty Stores, Automotive Dealerships, Tire Shops |
| Companies Covered | Michelin, Bridgestone Corporation, Continental AG, The Goodyear Tire & Rubber Company, Pirelli & C. S.p.A., Yokohama Rubber Co., Ltd., Sumitomo Rubber Industries, Ltd., Hankook Tire & Technology Co., Ltd., Toyo Tire & Rubber Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Tires Market Strategic Shifts & Innovations
Sustainable material substitution and digital integration are rewriting product architecture standards. Suppliers are racing to decouple performance metrics from petrochemical dependence while embedding intelligence into tire construction.
Silica-silane coupling systems are rewriting wet-grip performance benchmarks without fluorinated polymer dependence. Premium OEM fitment programs in Germany and Japan are adopting these compounds at accelerated validation schedules. The technology is compressing the performance gap between summer and all-season categories.
EU F-Gas Regulation and REACH Annex XVII restrictions are eliminating perfluorinated substances from high-grip tread formulations. Compound laboratories are requalifying entire polymer portfolios to maintain EU market access. Track-day tire segments face the steepest reformulation costs due to extreme friction coefficient requirements.
Direct-to-consumer fitment scheduling is displacing traditional wholesale-distributor relationships for enthusiast segments. Specialty retailers in the United States are building digital appointment platforms that bypass regional warehouse networks. Southern California and Texas metropolitan clusters show the highest platform adoption rates among track-day participants.
Global High Performance Tires Market Segmentation
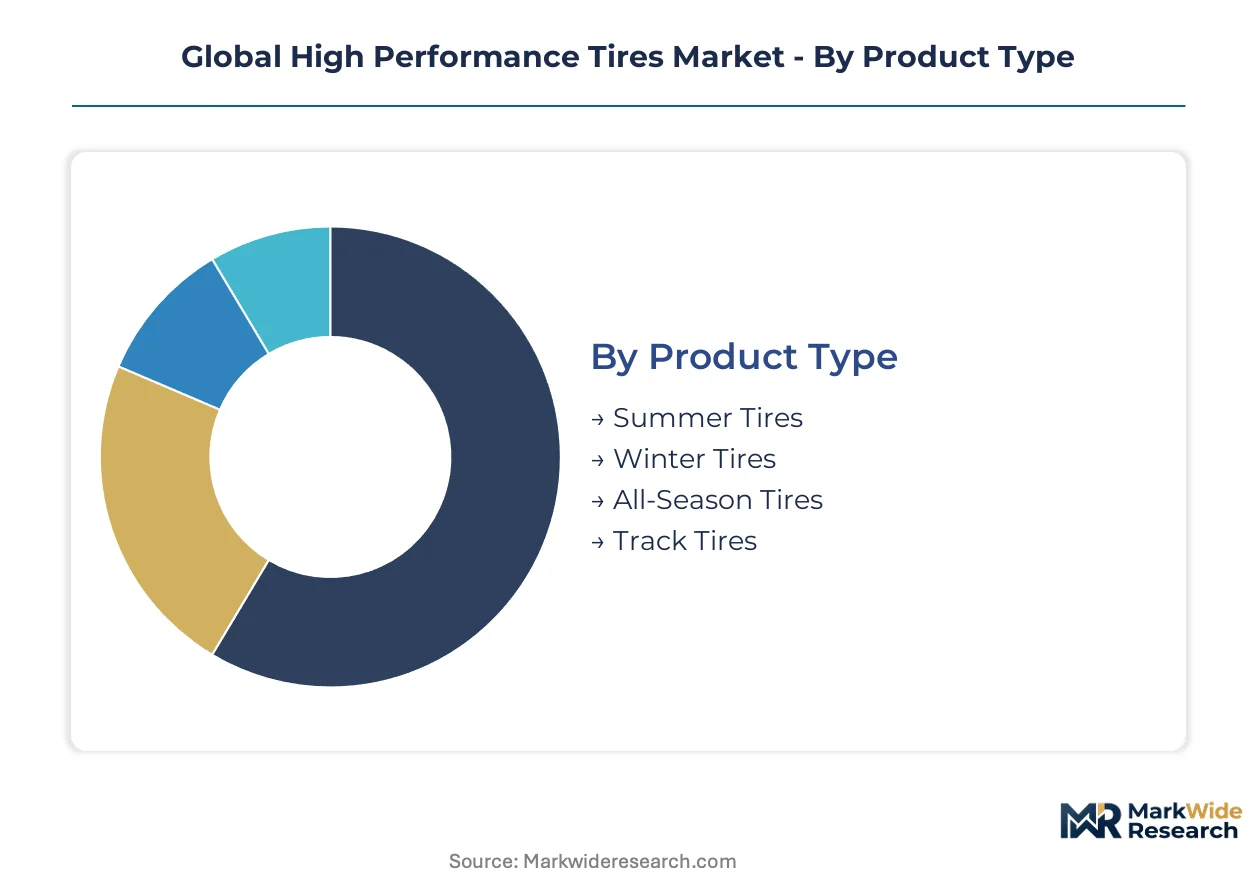
High performance tire segmentation reflects divergent engineering priorities across climate zones, vehicle architectures, and consumer risk tolerances. Manufacturers optimize compound portfolios across these axes to capture margin pools while managing homologation complexity.
Product Type:
Speed ratings and thermal operating windows define the technical differentiation axis across product categories.
- Summer Tires:Specialized tread compounds with asymmetric patterns deliver peak dry and wet grip in temperatures above 7°C. Demand concentrates in Germany, Japan, and the southern United States where warm-climate driving sustains year-round fitment.
- All-Season Tires:Intermediate tread compounds balance cold-weather pliability with warm-weather stiffness through silica-heavy formulations. Temperate regions in the northeastern United States and northern Europe are accepting modest dry-grip trade-offs for year-round convenience.
- Winter Tires:Siped tread blocks and soft compounds maintain elasticity below freezing. Regulatory mandates in Germany and Scandinavian countries sustain replacement cycles.
- Track Tires:Motorsport-homologated constructions with extreme friction coefficients and minimal tread depth. Low-volume production sustains premium pricing through racing series validation requirements.
Mature deployment sits with summer tires. Newer deployment is concentrated in all-season variants.
End User:
Vehicle mass, center of gravity, and duty cycle dictate load rating and construction requirements.
- Passenger Vehicles:Sport sedans and coupes specify W, Y, or Z speed ratings with reinforced sidewalls. OEM fitment rates on performance variants continue climbing in Germany and Japan.
- SUVs:Higher load indices and stiffer carcass plies manage elevated center-of-gravity forces during cornering. Premium electric SUV platforms are specifying staggered fitments with asymmetric compounds.
- Light Trucks:LT-metric sizing with enhanced puncture resistance serves towing and payload applications. Aftermarket upgrade demand runs through specialty retailers in Texas and California.
- Motorsports:Slick and grooved racing compounds undergo continuous homologation against series technical regulations. Factory-backed contracts lock in multi-year supply relationships.
Volume concentration rests with passenger vehicles. Margin expansion is fastest in motorsports.
Technology:
Embedded capabilities and material substitutions are rewriting value propositions beyond raw grip metrics.
- Run Flat Technology:Reinforced sidewall inserts sustain vehicle mobility after pressure loss. Premium OEM fitment in Germany and Japan is accelerating as manufacturers delete spare tires.
- Eco-Friendly Materials:REACH-compliant silica-silane coupling systems replace fluorinated polymers. EU F-Gas Regulation is compelling reformulation of entire high-grip compound portfolios.
- Low Rolling Resistance:Tread compound optimization reduces energy dissipation without sacrificing wet grip ratings. EPA benchmarks in the United States shape cross-border product development priorities.
- Noise Reduction:Variable pitch sequencing and foam absorber layers meet pass-by sound regulations. Urban low-emission zones in European cities are tightening acoustic compliance thresholds.
Regulatory pressure is concentrating investment in eco-friendly materials. Connected architectures represent the emerging technology frontier.
Distribution Channel:
Channel selection determines margin capture, fitment service integration, and consumer education depth.
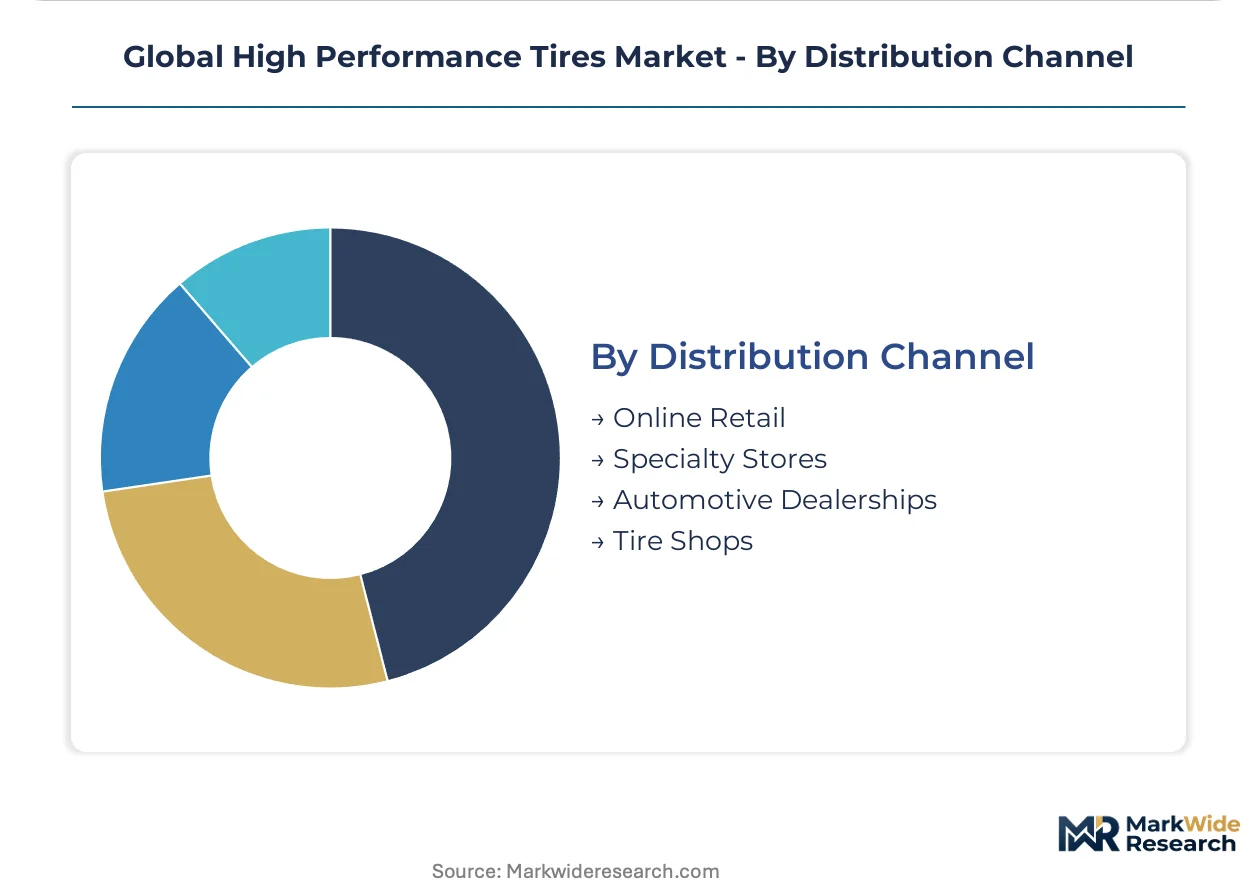
- Specialty Stores:Enthusiast-focused retailers provide mounting, balancing, and alignment services with technical consultation. Southern California and Texas metropolitan clusters show concentrated platform adoption.
- Automotive Dealerships:OEM-authorized channels capture replacement cycles during scheduled maintenance. Factory performance packages specify speed-rated fitments at point of sale.
- Tire Shops:Volume-oriented chains compete on installation speed and promotional pricing. Regional warehouse networks dominate replacement demand in the United States.
- Online Retail:Direct-to-consumer platforms with appointment scheduling are displacing traditional wholesale relationships. Digital fitment tools reduce specification errors for enthusiast segments.
Service integration favors specialty stores and dealerships. Price transparency is compressing margins in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing tax incentives and special economic zones for tire production are concentrating high-performance tire demand in Germany, Japan, and the United States. Factory-backed motorsport contracts and OEM performance variant programs anchor regional market development.
United States
EPA rolling-resistance benchmarks and NHTSA speed-rating enforcement shape product development priorities for cross-border manufacturers. IRA domestic content incentives subsidize compound production facilities in the Southeast. Southern California and Texas metropolitan clusters show concentrated specialty retailer platform adoption among track-day participants.
Germany
KBA type-approval requirements and EU F-Gas Regulation compliance drive reformulation of high-grip tread polymers toward sustainable silica compounds. REACH Annex XVII restrictions eliminate perfluorinated substances from premium OEM fitment portfolios. Bavaria and Baden-Württemberg host concentrated R&D activity for connected tire architectures.
Japan
METI industrial standards and factory performance package expansion sustain OEM fitment rate growth for W, Y, and Z speed-rated tires. JIS certification protocols maintain quality thresholds for export-oriented production. Kanto and Kansai industrial corridors concentrate motorsport technical partnership negotiations with global racing series.
China
MIIT new-energy vehicle regulations and dual carbon goals redirect domestic tire demand toward low-rolling-resistance compounds. GB standards enforcement accelerates quality convergence with international speed-rating protocols. Yangtze River Delta manufacturing zones supply premium electric SUV platforms with staggered asymmetric fitments.
South Korea
MFDS chemical substance management and automotive export requirements align domestic compound laboratories with EU REACH compliance timelines. Seoul Capital Area headquarters coordinate multi-series motorsport supply contract bidding. Busan-Ulsan industrial complexes manufacture track-day tire segments for Asia-Pacific distribution.
Global High Performance Tires Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium positioning commanding sustained margin premiums in motorsport-homologated categories. The vendor base concentrates around five integrated tire groups controlling factory-backed racing contracts and OEM supply relationships. Three strategic archetypes dominate: vertically integrated compound-to-retail operators, technology-licensing regional specialists, and motorsport-exclusive performance brands. Competitive moves center on R&D intensity in connected architectures and backward integration into sustainable silica supply chains.
Among European integrated tire groups, Continental AG and Pirelli & C. S.p.A. exemplify divergent positioning strategies within the premium tier. Continental AG occupies a position emphasizing embedded sensor development and digital service revenue streams. Pirelli & C. S.p.A. anchors the motorsport-exclusive archetype through single-supply racing contracts that cascade technical validation into consumer markets. Yokohama Rubber Co., Ltd. represents the Asia-Pacific technology-licensing model, with Japanese headquarters coordinating regional compound development.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Pirelli & C. S.p.A. |
| Yokohama Rubber Co., Ltd. |
| Sumitomo Rubber Industries, Ltd. |
| Hankook Tire & Technology Co., Ltd. |
| Toyo Tire & Rubber Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation and REACH Annex XVII compliance gates qualified supply access and premium-tier pricing power, forcing compound-dependent manufacturers to absorb reformulation costs or exit high-grip segments entirely. OEM fitment contracts in Germany and Japan reward certified suppliers with multi-year pricing stability while spot-market buyers absorb volatility in synthetic rubber and carbon black inputs.
Pricing Analysis
Lead-time compression commands premium positioning in motorsport-homologated categories where racing series deadlines override standard procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates track-day compounds with homologation validation from mass-market summer variants. Pricing pressure stems from petrochemical input volatility compressing margin predictability for compound-dependent manufacturers. Aftermarket specialty retailers in Texas and California show highest price sensitivity, while OEM platform engineers in Germany and Japan prioritize performance validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian natural rubber plantations facing climate disruption and labor availability constraints. Synthetic rubber feedstocks draw from South Korean and Japanese petrochemical complexes, while silica processing concentrates in China and Germany. Tariff exposure on cross-border carbon black shipments strains regional mixing facility economics. Distribution runs through OEM-authorized dealer networks for factory fitment, bypassing wholesale channels for performance package specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII substance restrictions erect a cost-of-compliance moat that advantages incumbent compound laboratories with existing ECHA registration portfolios and disadvantages capital-constrained entrants lacking reformulation infrastructure.
For Market Incumbents: Acquire specialized polymer chemistry talent pools and captive silica processing capacity to defend against emerging entrants with sustainable material credentials. Backward integration into REACH-compliant raw material sourcing locks in margin stability as ECHA expands restricted substance lists. Compound formulation expertise scarcity in high-grip, low-rolling-resistance combinations commands premium compensation that only scaled players can absorb. For New Entrants and Emerging Players: Capture direct-to-consumer fitment scheduling platforms in Southern California and Texas metropolitan clusters where specialty retailer relationships remain underdeveloped. All-season performance variants for temperate-climate consumers in the northeastern United States present the most penetrable white space, accepting modest dry-grip trade-offs for year-round convenience. Partner with track-day event organizers for technical validation that bypasses traditional motorsport homologation pipelines. For Investors and Strategic Acquirers: Factory-backed racing series contract renewals are the leading indicator that technical validation pathways remain concentrated with incumbent holders rather than fragmenting across new suppliers. Five-to-ten-year viability favors vertically integrated compound-to-retail operators with embedded sensor patent portfolios and sustainable silica supply chain control. Watch for IRA domestic content incentive utilization rates in Southeast U.S. manufacturing zones as inflection signal for regional production cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Reformulation | ECHA substance restrictions force portfolio-wide requalification to maintain EU market access. |
| Connected Tire Architecture Patenting | Embedded sensor layouts in Bavaria and Baden-Württemberg R&D clusters create data service revenue streams. |
| Motorsport Homologation Pipeline Investment | Endurance racing technical partnerships validate tread compounds for road-legal derivative acceleration. |
| Direct-to-Consumer Platform Buildout | Digital appointment scheduling in Southern California and Texas bypasses traditional wholesale-distributor relationships. |
| Sustainable Silica Supply Integration | Backward integration into silica-silane coupling systems decouples wet-grip performance from fluorinated polymer dependence. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving tire compound R&D directors, OEM platform engineers, aftermarket distributor procurement leads, and motorsport series technical directors. ECHA substance restriction databases, NHTSA uniform tire quality grading enforcement records, and EPA rolling-resistance benchmark disclosures provided regulatory validation layers. Bottom-up production capacity assessments triangulated against top-down OEM fitment rate projections across Germany, Japan, and the United States.
Granularity-level modeling deployed product type, end user vehicle architecture, technology embedding, and distribution channel dimensions at country-level resolution across the analysis window. CAGRs derived from segment-specific volume trajectories weighted by regional OEM specification intensity and replacement cycle frequency. Motorsport contract renewal timelines and IRA domestic content incentive utilization rates informed cross-border manufacturing footprint assumptions.
The model holds under stable petrochemical input pricing and sustained EU regulatory enforcement; deviation in ECHA substance restriction expansion timelines or NHTSA speed-rating certification protocol changes would shift compound laboratory investment priorities. Forecasts reflect assumptions regarding OEM performance package expansion rates and racing series technical regulation stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Performance Tires Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market