
 Automotive Wheel Alignment System Market | 2026-2036
Automotive Wheel Alignment System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Alignment System Market Analysis
Software-defined calibration and remote diagnostics is consolidating the traditional equipment sale into recurring revenue relationships. Robert Bosch GmbH leverages its embedded sensor ecosystem to anchor service contracts alongside hardware placements. Hunter Engineering Co. dominates the North American independent shop channel through proprietary cloud-connected alignment platforms. Snap-on Inc. differentiates by integrating wheel alignment data into broader fleet management dashboards for commercial vehicle operators.
An automotive wheel alignment system measures and adjusts the angular relationship between wheels and the vehicle's suspension geometry, typically correcting camber, caster, and toe angles within tolerance ranges of 0.1 degrees to ensure even tire wear and stable handling. Camera-based 3D alignment systems lead the product type category due to superior measurement speed and integration with automated vehicle inspection lanes. Aftermarket providers represent the fastest-growing end user segment as aging vehicle fleets extend service intervals and independent shops upgrade from 2D to computerized systems. Magnetic sensor technology occupies a niche but defensible position in heavy-duty commercial applications where environmental contamination degrades optical components.
NHTSA safety standards and EPA fuel efficiency regulations in the United States shape demand by mandating precise suspension geometry to maintain tire rolling resistance and emissions compliance. The EU Green Deal and REACH frameworks in Europe restrict hazardous materials in sensor housings and calibration targets, forcing redesigns of consumable alignment accessories. Stakeholders must monitor how camera-based systems evolve against lidar and radar calibration requirements as advanced driver assistance packages proliferate across vehicle segments.
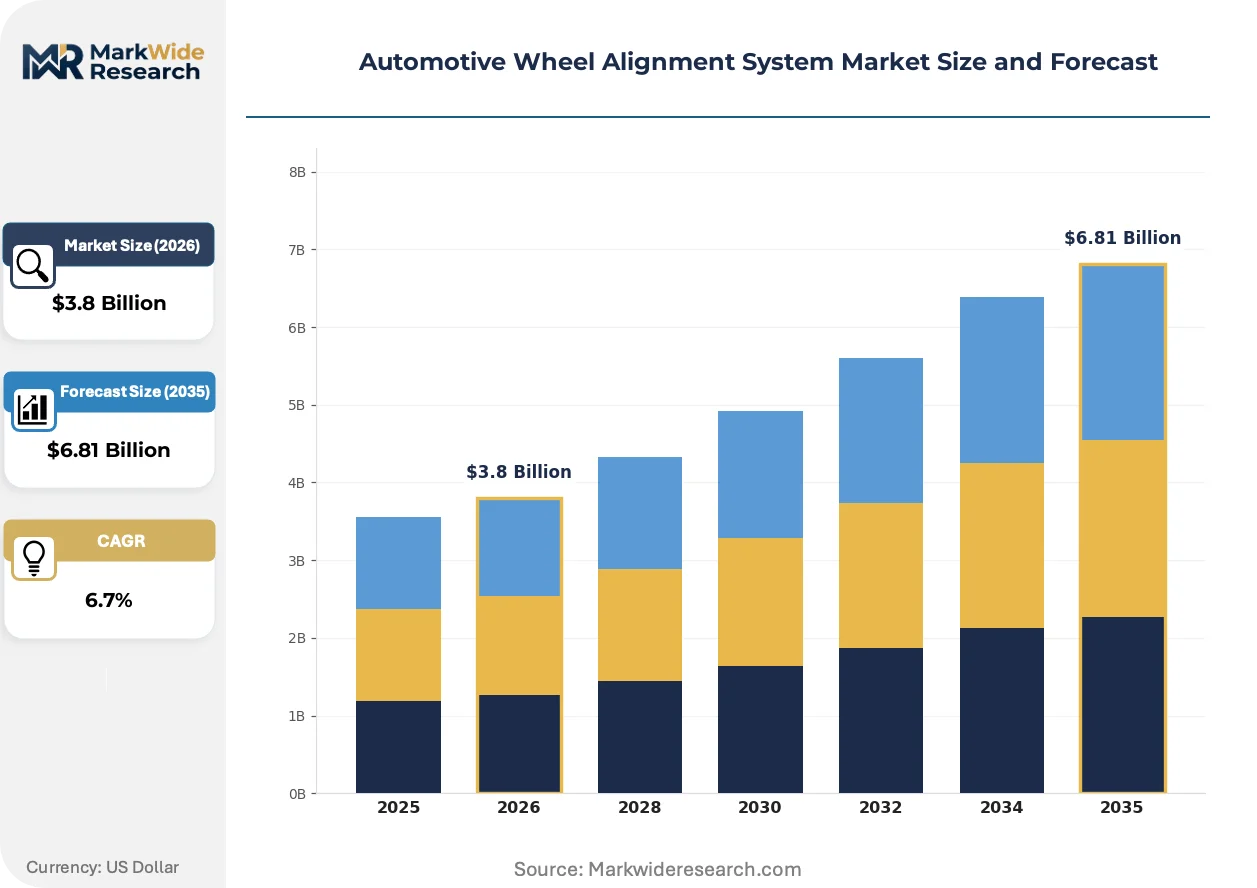
Market Dynamics
Software-defined calibration is compressing hardware replacement cycles into recurring service relationships, forcing equipment vendors to restructure revenue models around embedded diagnostics and predictive maintenance subscriptions.
Growth Catalysts
- NHTSA inspection mandates:Stricter vehicle safety protocols in the United States compel independent repair shops to upgrade from manual gauges to computerized alignment systems, accelerating replacement demand.
- ADAS proliferation:Advanced driver assistance packages require sub-degree angular precision during sensor recalibration, expanding alignment system functionality beyond traditional suspension geometry.
- German precision engineering standards:Dense OEM service networks in Germany sustain premium equipment procurement, creating a reference market for high-specification 3D camera systems.
Market Restraints
- Optical component vulnerability:Camera-based systems degrade in heavy-duty commercial environments where particulate contamination and temperature cycling exceed sealed housing tolerances.
- Consumable redesign costs:EU REACH restrictions on hazardous materials in calibration targets and sensor housings force manufacturers to reformulate accessories at elevated R&D expense.
- Technician certification barriers:Complex 3D systems require specialized training that smaller independent shops cannot readily access, slowing adoption outside franchise networks.
Strategic Opportunities
- India aftermarket expansion:Aging vehicle fleets and tightening state-level inspection norms create whitespace for computerized alignment penetration in tier-2 and tier-3 cities.
- Cloud-connected fleet dashboards:Commercial vehicle operators seek integrated maintenance data streams, opening subscription revenue channels beyond equipment sales.
- Magnetic sensor niche defense:Heavy-duty mining and construction applications favor electromagnetic measurement where optical systems fail, supporting specialized product lines.
Industry Challenges
- ADAS calibration complexity:Integration of wheel alignment with lidar and radar recalibration demands software competencies that traditional hardware vendors lack.
- Legacy 2D system stranded assets:Independent shops face write-downs on recent 2D equipment purchases as 3D camera systems become the de facto standard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Alignment System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Alignment Systems, 3D Alignment Systems, CCD Alignment Systems, Computerized Alignment Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Technology: Laser Technology, Infrared Technology, Camera-Based Systems, Magnetic Sensors Installation: Mobile Installation, Fixed Installation, Portable Systems, Integrated Systems |
| Companies Covered | Hunter Engineering Co., Dover Corp., CEMB Spa, Fori Automation Inc., HAWEKA AG, Robert Bosch GmbH, Snap-on Inc., ATS ELGI, Manatec Electronics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Alignment System Market Emerging Trajectories
Digital service architectures are displacing transactional equipment sales across the automotive aftermarket, embedding alignment systems within broader vehicle health monitoring ecosystems.
Camera-based 3D alignment technology is rewriting competitive requirements in the independent repair channel. These systems capture complete vehicle geometry in under two minutes, compressing bay turnover times that directly determine shop profitability. Mid-size independent operators in the United States are adopting 3D platforms at the fastest clip, abandoning laser and CCD alternatives that require sequential wheel positioning.
EPA fuel efficiency regulations are tightening tolerance requirements for suspension geometry to maintain certified tire rolling resistance. Manufacturers must now document alignment precision within 0.1 degrees to preserve vehicle emissions compliance ratings. OEM service networks face the steepest compliance burden, retrofitting alignment bays with calibration-grade equipment that independent shops subsequently emulate.
Service contract unbundling is fragmenting traditional capital expenditure decisions into operational line items. Fleet operators now procure alignment capacity through per-vehicle service agreements rather than equipment ownership, transferring utilization risk to vendors. This shift concentrates most visibly among commercial vehicle lessors in Germany, where total-cost-of-ownership accounting dominates procurement evaluation.
Automotive Wheel Alignment System Market Segmentation
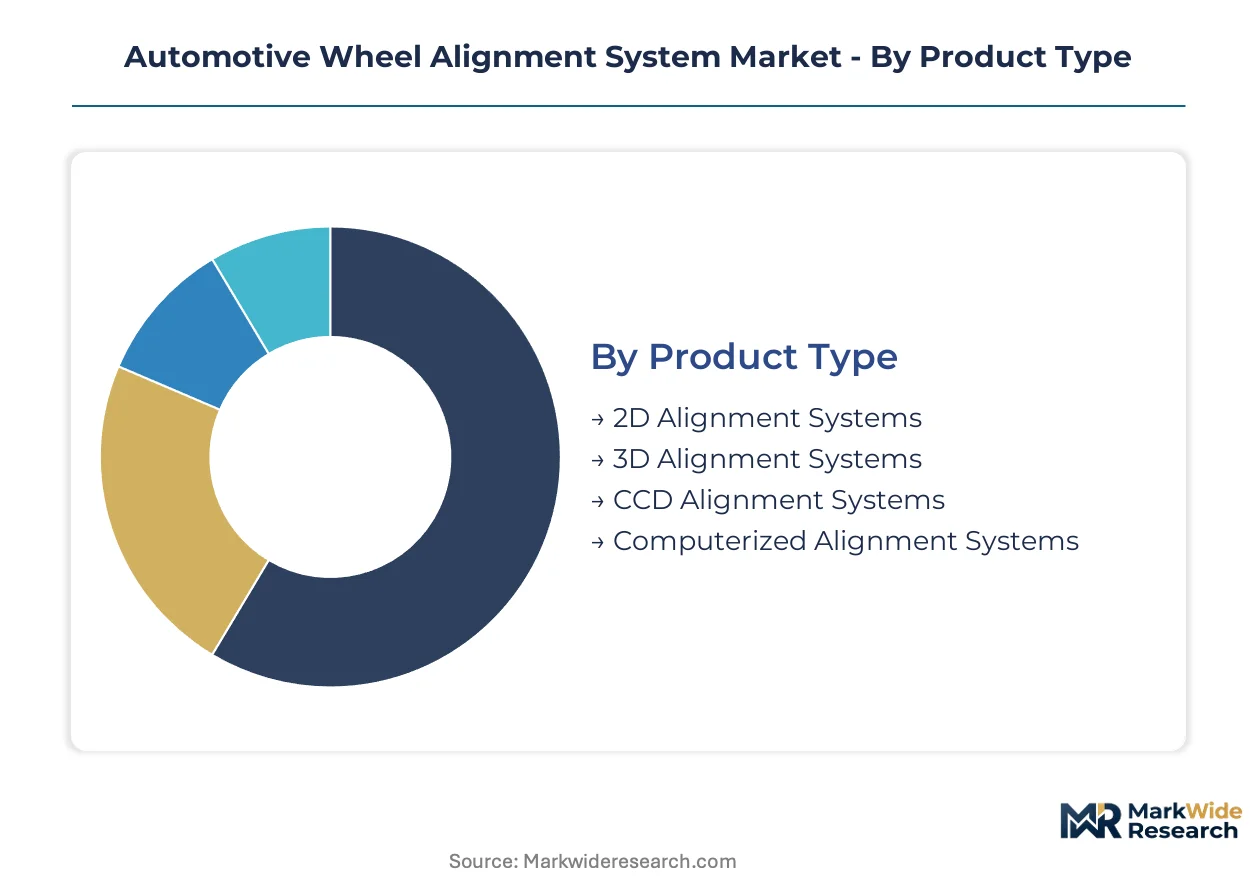
Segmentation in wheel alignment systems reveals how equipment specifications diverge across customer sophistication levels and operational environments. Product architecture, technology modality, and installation format each create distinct purchasing criteria that reshape vendor go-to-market strategies.
Product Type:
The customization-to-standardization spectrum runs from manually operated 2D platforms to fully automated 3D camera arrays with embedded calibration software.
- 3D Alignment Systems:Camera-based triangulation captures complete vehicle geometry in under two minutes, compressing bay turnover times. Demand concentrates in mid-size independent repair shops across the United States where Hunter Engineering and Robert Bosch GmbH anchor service contracts alongside hardware placements. NHTSA inspection mandates accelerate replacement of legacy equipment.
- 2D Alignment Systems:Laser or mechanical gauge-based measurement requires sequential wheel positioning and manual recording. Smaller franchise networks in tier-2 Indian cities retain these systems where capital constraints limit 3D adoption, though state-level inspection tightening forces gradual upgrades.
- CCD Alignment Systems:Charge-coupled device sensors deliver sub-degree precision at moderate price points, occupying a middle tier for budget-conscious operators.
- Computerized Alignment Systems:Software-defined calibration platforms integrate diagnostic databases and predictive maintenance modules, embedding hardware within recurring revenue relationships.
Most installed capacity flows through 3D Alignment Systems. Expansion is steepest in Computerized Alignment Systems.
End User:
Purchasing authority distributes across captive OEM networks, fragmented independent channels, and fleet operators with divergent total-cost-of-ownership calculations.
- Aftermarket Providers:Independent repair shops and regional service chains drive volume, upgrading from 2D to camera-based platforms as vehicle fleets age and inspection norms tighten. Germany's dense OEM service networks create reference demand that independent operators subsequently emulate.
- OEMs:Vehicle manufacturers specify calibration-grade equipment for warranty compliance and emissions certification documentation, requiring 0.1-degree tolerance verification.
- Repair Shops:Franchise and independent facilities balance equipment cost against bay throughput, with cloud-connected platforms reducing technician training burdens.
- Vehicle Assemblers:Production-line integration demands high-speed measurement with direct MES connectivity for quality traceability.
Aftermarket Providers command the largest equipment footprint. Vehicle Assemblers are gaining share fastest as EV platform launches multiply alignment stations per factory.
Technology:
Measurement modality selection hinges on environmental resilience, speed requirements, and integration complexity with ADAS recalibration workflows.
- Camera-Based Systems:Multi-lens arrays capture wheel position through target recognition, dominating light-duty applications where measurement speed determines shop profitability. EPA fuel efficiency regulations tighten tolerance requirements to preserve certified tire rolling resistance.
- Magnetic Sensors:Electromagnetic measurement operates reliably in heavy-duty mining and construction environments where particulate contamination degrades optical components. These systems defend a defensible niche in commercial vehicle applications.
- Laser Technology:Point-to-point laser projection offers proven accuracy for standard alignment procedures, retaining share in cost-sensitive segments.
- Infrared Technology:Non-visible spectrum sensing reduces ambient light interference in outdoor or variable lighting conditions.
Camera-Based Systems absorb the majority of new investment. Magnetic Sensors hold the most durable niche position against optical alternatives.
Installation:
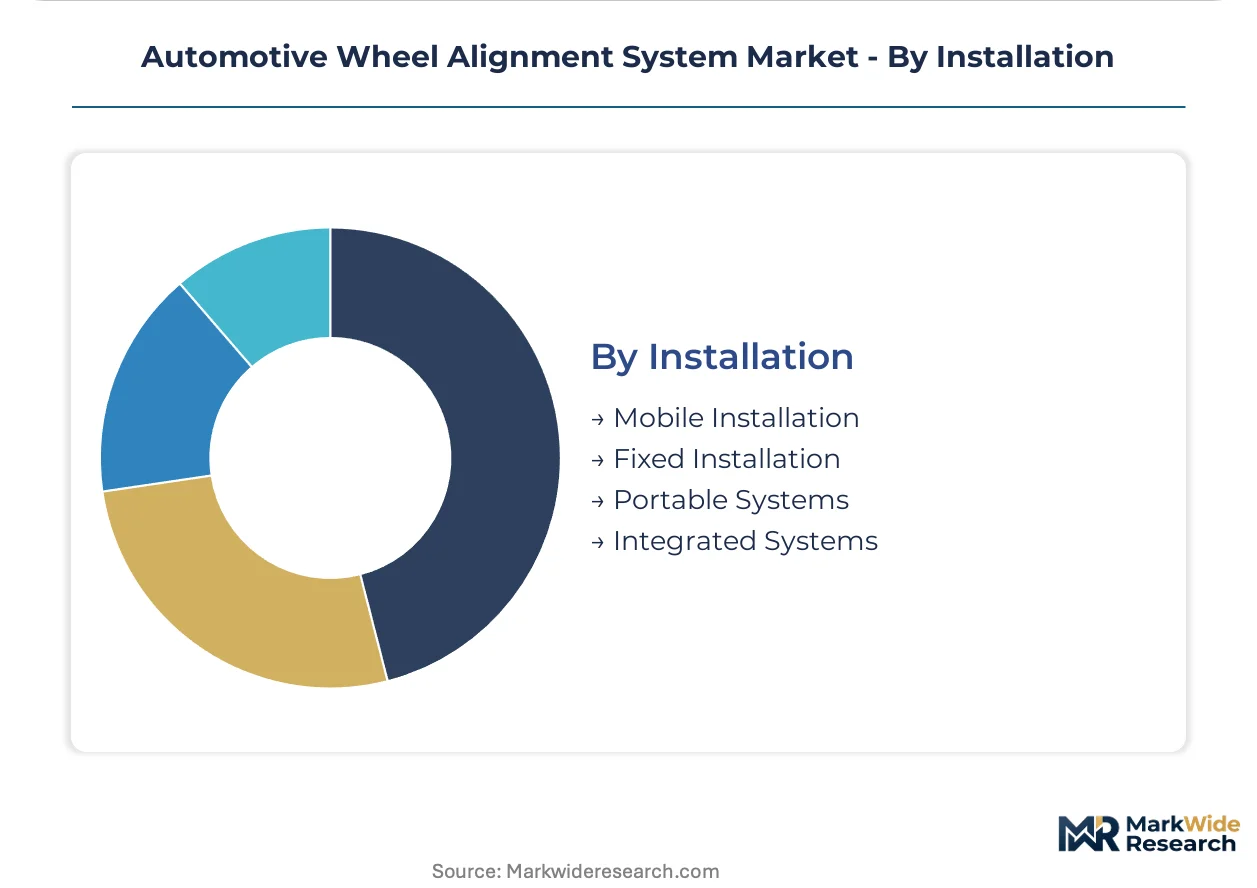
Physical configuration options span permanent bay integration through field-service mobility, with procurement patterns reflecting facility tenure and vehicle throughput variability.
- Fixed Installation:Permanent bay-mounted systems with embedded lifts and target storage dominate high-volume facilities. German precision engineering standards sustain premium equipment procurement in OEM-certified service networks.
- Mobile Installation:Vehicle-mounted or trailer-based units serve fleet operators and remote construction sites where vehicle immobilization costs exceed equipment transport expenses.
- Portable Systems:Compact units with rapid deployment suit multi-bay facilities sharing alignment capacity across service lanes.
- Integrated Systems:Alignment modules embedded within automated vehicle inspection lanes combine measurement with regulatory compliance documentation.
Fixed Installation retains the deepest equipment base. Mobile Installation is climbing fastest as commercial fleet operators prioritize uptime over facility constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains premium equipment procurement through precision engineering standards, while the United States drives volume through NHTSA-mandated safety inspections at independent repair chains.
United States
NHTSA inspection mandates compel independent repair shops to abandon manual gauges for computerized alignment systems. The EPA enforces fuel efficiency regulations requiring 0.1-degree tolerance documentation to preserve certified tire rolling resistance. Mid-size independent operators in the Midwest and Southeast upgrade fastest, abandoning legacy 2D platforms for camera-based 3D systems.
Germany
Dense OEM service networks anchor premium equipment demand, with calibration-grade systems required for warranty compliance documentation. The KBA enforces stringent vehicle safety protocols that independent operators subsequently emulate. Stuttgart and Munich industrial clusters concentrate high-specification 3D camera system procurement for both captive and aftermarket channels.
China
MIIT standards for vehicle safety inspections tighten alignment tolerance requirements across domestic and imported vehicle fleets. GB standards for automotive service equipment accelerate replacement of mechanical gauges in provincial repair networks. Yangtze River Delta manufacturing hubs absorb the steepest equipment volumes as EV platform launches multiply alignment stations per assembly plant.
India
Aging vehicle fleets and tightening state-level inspection norms create whitespace for computerized alignment penetration beyond tier-1 metros. BIS certification requirements for automotive service equipment filter substandard imports from regional supply chains. Tier-2 cities in Maharashtra and Gujarat lead aftermarket upgrades as franchise networks expand from Mumbai and Ahmedabad.
Japan
METI guidelines for automotive maintenance standards preserve precision requirements that sustain premium equipment replacement cycles. JIS standards for measurement equipment calibration force periodic recertification of installed alignment systems. Kanto and Kansai industrial corridors concentrate both OEM service networks and independent shop equipment procurement.
Automotive Wheel Alignment System Market Vendor Landscape
Top-tier vendors anchor the premium calibration-grade segment, while mid-tier specialists compete on throughput speed and cloud connectivity features. The vendor base stratifies across three tiers: multinational industrial conglomerates with embedded sensor ecosystems, dedicated automotive equipment manufacturers with proprietary software platforms, and regional fabricators serving cost-sensitive emerging markets. Dominant competitive moves include strategic partnerships with fleet operators for subscription-based service contracts and geographic expansion through distributor networks in underpenetrated Asian markets.
Within the multinational industrial tier, Robert Bosch GmbH and Snap-on Inc. exemplify divergent strategic positioning. Hunter Engineering Co. anchors the North American independent shop channel. These three entities represent distinct archetypes: the diversified industrial conglomerate leveraging sensor ecosystem integration, the tool-focused manufacturer pursuing fleet management dashboard integration, and the dedicated automotive equipment specialist dominating a single geography through proprietary cloud platforms.
| Leading Market Players |
|---|
| Hunter Engineering Co. |
| Dover Corp. |
| CEMB Spa |
| Fori Automation Inc. |
| HAWEKA AG |
| Robert Bosch GmbH |
| Snap-on Inc. |
| ATS ELGI |
| Manatec Electronics Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Germany and Italy anchor the premium calibration-grade segment, concentrating supply-side discipline that sustains price floors for 3D camera systems while limiting discounting pressure in North American independent shop channels.
Pricing Analysis
Capacity additions in China are reshaping price floors for entry-level 2D alignment platforms, compressing margins for regional fabricators serving cost-sensitive Indian and Southeast Asian markets. Three-tier pricing structure across premium, standard, and economy levels separates Hunter Engineering's cloud-connected platforms from Bosch's sensor-integrated systems and unbranded CCD alternatives. Pricing pressure stems from EU REACH compliance costs forcing consumable redesigns at elevated R&D expense. Franchise networks exhibit lowest price sensitivity due to warranty compliance requirements, while tier-2 Indian independent shops face acute capital constraints.
Supply Chain Analysis
High-precision optical lens supply rests on Japanese specialty glass producers and German engineered component manufacturers, with camera sensor arrays drawing heavily from South Korean semiconductor foundries. Aluminum extrusion for lift mechanisms sources from Chinese mills, while calibration target substrates depend on coated polyester film from Taiwan. Single-source vulnerability concentrates in EU-certified sensor housings facing REACH material restrictions. Distribution runs through captive OEM service networks in Germany, independent distributor channels in the United States, and fragmented multi-brand dealers across India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory compounder, with NHTSA inspection mandates and EPA fuel efficiency documentation requirements creating durable replacement demand that transcends cyclical vehicle sales volatility.
For Market Incumbents: Lock in service contract unbundling to convert capital equipment sales into recurring revenue streams, embedding predictive maintenance modules that raise switching costs for independent repair shops. Backward integration into sensor calibration software protects margin position against ADAS recalibration specialists encroaching from adjacent diagnostic markets.
For New Entrants and Emerging Players: The mid-tier price-point gap between Hunter Engineering's premium platforms and unbranded 2D alternatives creates whitespace for cloud-native alignment systems with reduced technician training burdens. Target tier-2 Indian cities where state-level inspection tightening outpaces franchise network expansion, leveraging mobile installation formats that eliminate fixed bay requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among magnetic sensor specialists serving heavy-duty mining and construction applications, where optical system failures sustain durable niche pricing power. Long-term viability hinges on software-defined calibration competencies that bridge wheel alignment with lidar and radar recalibration workflows. The signal to watch is ADAS penetration rates in commercial vehicle segments, which would accelerate sensor recalibration bundling requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Calibration Platform | Embedded diagnostics from Bosch transform hardware placements into recurring service contracts with independent shops. |
| Cloud-Connected Fleet Dashboard | Snap-on's integration of alignment data into commercial vehicle management systems opens subscription revenue channels. |
| ADAS Recalibration Capability | Camera-based 3D systems that incorporate lidar and radar alignment capture sensor fusion maintenance demand. |
| Mobile Installation Format | Trailer-based units from emerging vendors serve remote construction sites where vehicle immobilization costs dominate. |
| EU REACH Compliance Redesign | Reformulated calibration targets and sensor housings preserve market access amid hazardous material restrictions. |
Methodological Framework
Bottom-up aftermarket provider modeling reconciled against top-down OEM service network tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at independent repair chains, aftermarket distributors, OEM platform engineers, and fleet maintenance directors combined with secondary validation against NHTSA inspection mandate documentation, EPA fuel efficiency certification databases, EU REACH regulatory filings, and vehicle production registration data. Triangulation across these sources reconciles equipment shipment volumes with installed base replacement cycles.
Historical trendline analysis of 3D camera system adoption rates, 2D platform retirement patterns, and ADAS penetration trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product architecture tier, technology modality, installation format, end-user category, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression, inspection mandate expansion timelines, and software subscription attach rate assumptions. Industry-specific forecast inputs encompass NHTSA safety protocol evolution and EU Green Deal material restriction timelines.
Caveats apply where ADAS calibration complexity outpaces technician certification availability or where EU material restrictions accelerate beyond supplier reformulation capacity. Forecasts reflect assumptions around inspection mandate enforcement intensity and fleet operator subscription willingness. A small set of named triggers warrants ongoing watch: commercial vehicle ADAS penetration inflection, REACH restriction scope expansion, and Indian state-level inspection norm implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Automotive Wheel Market