
 Automotive All-Season Tire Market | 2026-2036
Automotive All-Season Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive All-Season Tire Market Outlook
Light commercial vehicle fleets is expanding as a share of all-season tire demand, driven by delivery networks and contractor services seeking reduced seasonal changeover costs. Michelin leverages its silica compound expertise to sustain premium positioning across touring categories. Bridgestone anchors North American supply through its Tennessee manufacturing complex. Continental differentiates via integrated tire sensor systems that pair with all-season tread designs.
Automotive all-season tires are pneumatic tires engineered with intermediate tread compounds and siping patterns designed to perform across temperature ranges from approximately 7°C to above 40°C, typically incorporating silica-enhanced synthetic rubber blends and polyester carcass plies to balance wet grip, wear resistance, and fuel efficiency. Their primary purpose is to eliminate the need for seasonal tire swaps while maintaining safe traction in varied weather conditions for passenger and light truck applications. Passenger tires occupy the largest volume pool but face margin compression in economy fitments, while SUV tires capture expanding share as vehicle architectures shift toward higher center-of-gravity platforms. Grand Touring segments lead value generation through extended treadwear warranties and comfort-oriented construction, whereas All-Terrain variants within the performance category attract premium pricing from crossover owners seeking mild off-road capability.
The EPA enforces rolling resistance benchmarks through corporate average fuel economy standards, directly shaping compound development priorities for tires sold in the United States. The EU's tire labeling regulation and REACH chemical restrictions constrain formulation choices while creating market access barriers for non-compliant manufacturers. China's GB standards and MIIT energy consumption rules add parallel compliance layers for suppliers serving domestic OEM fitment programs. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional product variants or unified global platforms offer superior returns.
Market Dynamics
Fleet electrification is compressing replacement cycles while simultaneously demanding higher load-rated all-season compounds to accommodate battery weight penalties and instant torque delivery.
Growth Catalysts
- EPA Corporate Average Fuel Economy Standards:Rolling resistance benchmarks force compound reformulation toward silica-dominant treads, pulling R&D investment into low-hysteresis elastomer systems.
- Ride-hailing fleet standardization:Uber and Lyft operator networks in the United States consolidate procurement around single-fitment year-round tires to eliminate seasonal downtime.
- Crossover platform proliferation:Higher center-of-gravity vehicle architectures from Detroit Three and domestic Chinese OEMs require reinforced sidewall constructions that all-season tire suppliers now specify as factory fitment.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to commodity swings that compress margin on economy-tier products.
- EU REACH chemical restrictions:Polycyclic aromatic hydrocarbon limits in extender oils constrain traditional carbon-black loadings, forcing costly formulation pivots for European market access.
- Performance ceiling in extreme cold:Glass transition temperature boundaries prevent all-season compounds from matching dedicated winter tire grip below minus seven degrees Celsius, creating substitution risk in Nordic climates.
Strategic Opportunities
- India BIS certification expansion:Mandatory tire labeling and safety standards create first-mover advantage for suppliers establishing local testing partnerships ahead of enforcement deadlines.
- Integrated tire-pressure-monitoring convergence:Sensor-embedded tread blocks paired with fleet telematics platforms enable predictive replacement scheduling for logistics operators.
- Brazil ANVISA import harmonization:Streamlined homologation pathways under Mercosur technical regulations reduce time-to-market for South American distribution expansion.
Industry Challenges
- Compounder talent scarcity:Silica dispersion expertise and dynamic mechanical analysis proficiency lag demand as formulation complexity escalates.
- Multi-jurisdiction homologation timelines:Parallel EPA, ECE R30, and GB certification tracks extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive All-Season Tire Market |
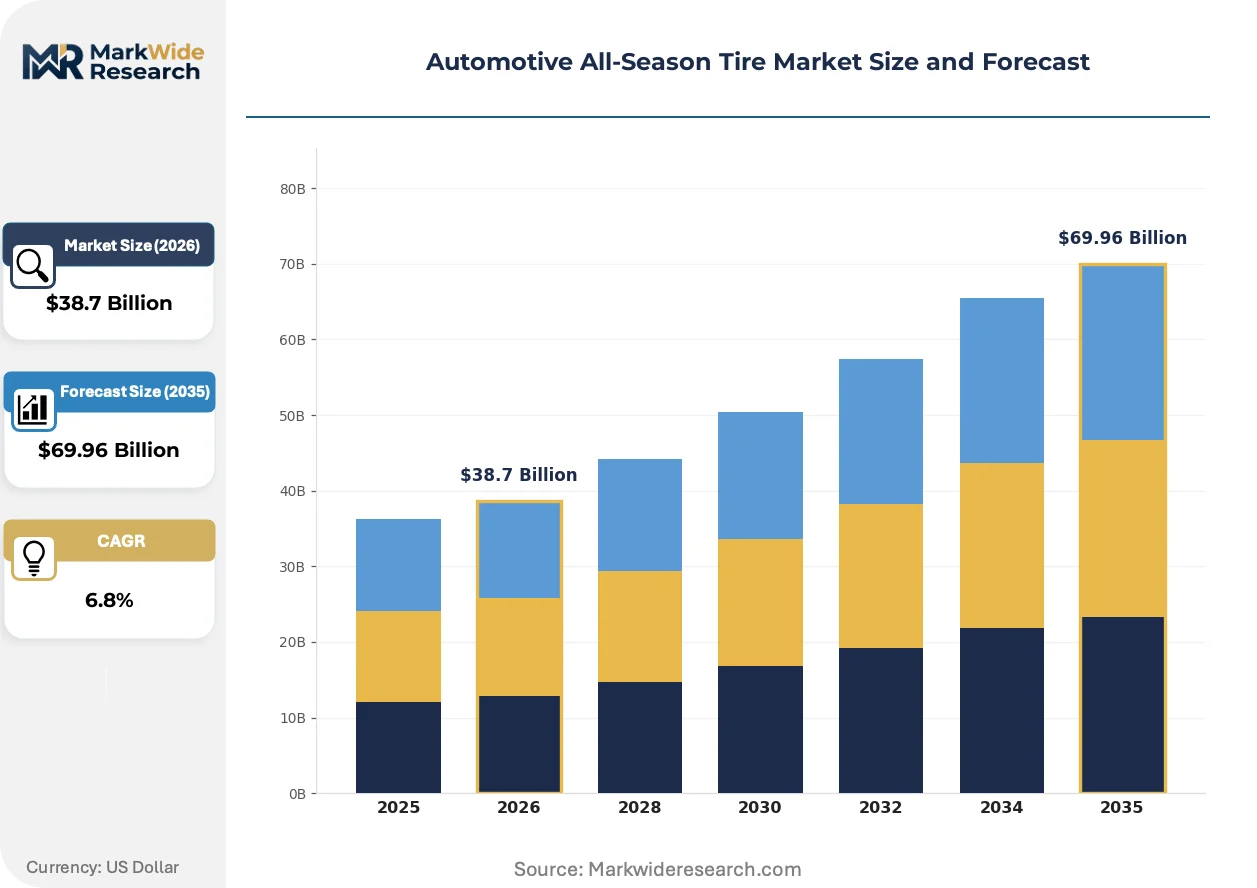
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Tires, Light Truck Tires, SUV Tires, Crossover Tires Material: Natural Rubber, Synthetic Rubber, Polyester, Steel Performance Category: Grand Touring, Touring, High Performance, All-Terrain Distribution Channel: Online Retail, Wholesale, Tire Dealers, Service Centers |
| Companies Covered | Michelin, Bridgestone, Continental, Goodyear, Pirelli, Hankook, Yokohama, Sumitomo Rubber, Nokian Tyres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive All-Season Tire Market Strategic Shifts
Active tread compound engineering is displacing passive material selection as the primary competitive lever, with suppliers now optimizing viscoelastic response across temperature bands rather than targeting single-point performance.
Functionalized silica-silane coupling systems are expanding into OE fitments for electric vehicle platforms, with Tesla and BYD procurement teams specifying compounds that reduce rolling resistance by fifteen percent versus conventional blends. Tier-one suppliers retrofit mixing lines to handle high-surface-area silica loads that demand precise temperature control during non-productive time transitions. This technology is expanding into aftermarket premium tiers as warranty-backed mileage claims become the decisive purchase criterion.
EU tire labeling regulation updates now mandate declared ice-grip performance classes alongside existing wet-braking grades, forcing manufacturers to validate Nordic test track data for any all-season product marketed across the twenty-seven member states. Compounders face reformulation costs to maintain B-grade wet grip while achieving C-grade or better ice performance. The Grand Touring segment bears the heaviest compliance burden as its comfort-oriented constructions historically prioritized dry handling over cold-weather elasticity.
Direct-to-fleet procurement models are consolidating buyer power among last-mile delivery operators, with Amazon DSP networks and regional courier cooperatives negotiating annual volume contracts that bypass traditional wholesale distribution. Tire-as-a-service billing structures, where suppliers retain ownership and charge per kilometer, displace upfront purchase transactions in German and Dutch logistics markets. This shift concentrates demand planning risk with manufacturers while transferring inventory carrying costs downstream.
Automotive All-Season Tire Market Segmentation
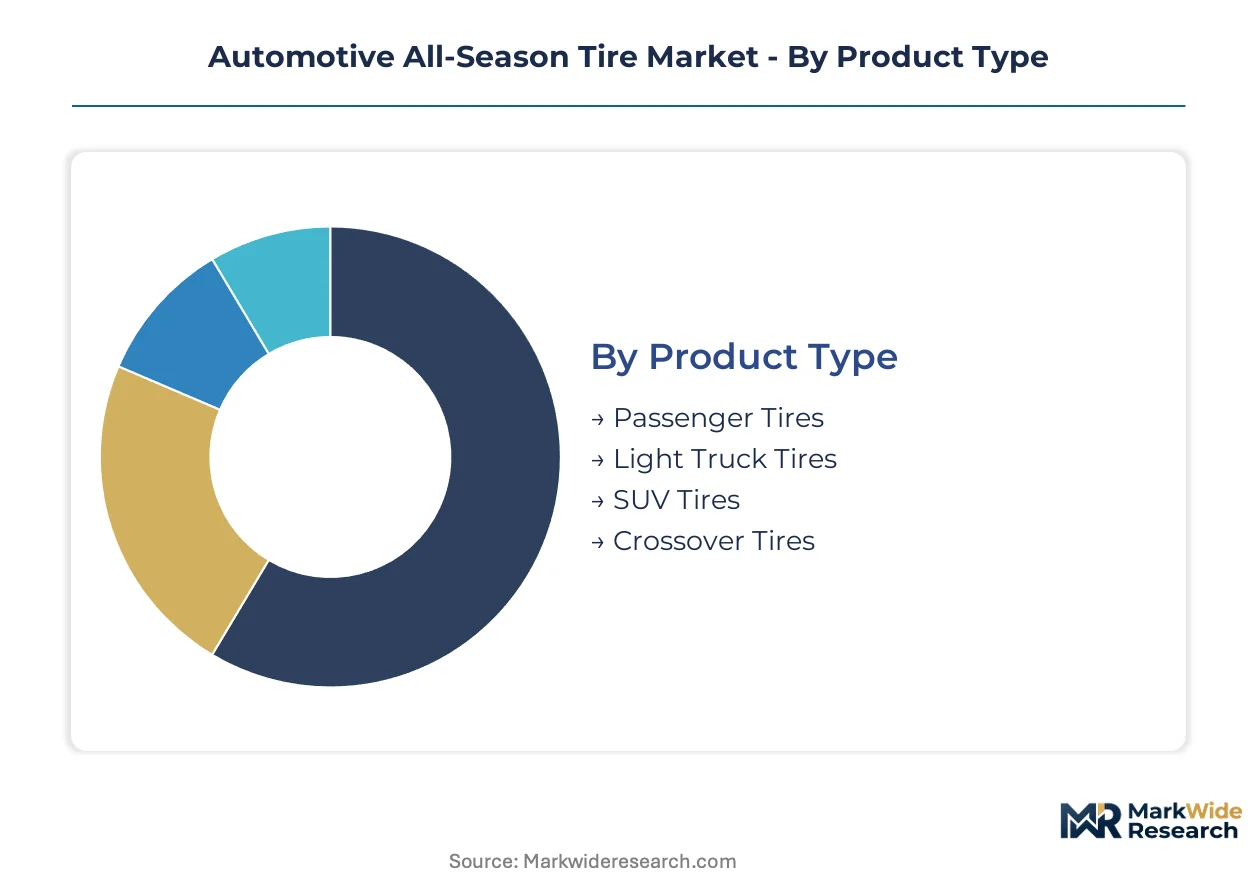
Segmentation in all-season tires reveals divergent upgrade cycles across vehicle platforms, with replacement timing driven by mileage accumulation patterns rather than seasonal mandates. Fleet procurement and consumer retail channels operate on fundamentally different specification logics, forcing suppliers to maintain parallel product architectures.
Product Type:
Upgrade cycles vary dramatically by vehicle duty cycle, with commercial applications demanding reinforced constructions that accelerate wear rates and compress replacement intervals.
- Passenger Tires:Bias-ply and radial constructions using silica-enhanced tread compounds dominate this volume pool. Replacement demand concentrates among ride-hailing fleets in the United States and domestic vehicle parc expansion in China, where annual mileage accumulation reaches 40,000 kilometers for commercial operators versus 15,000 for private owners.
- SUV Tires:Reinforced sidewall plies and higher load index ratings accommodate elevated vehicle mass and center-of-gravity shifts. Demand is climbing fastest in China as BYD and Geely scale production of electrified SUV platforms requiring factory-fit all-season specifications.
- Light Truck Tires:Heavier carcass constructions with deeper tread depths serve contractor and last-mile delivery segments.
- Crossover Tires:Hybrid designs blending passenger comfort with light-truck durability target the fastest-expanding vehicle architecture category.
Volume placements concentrate in Passenger Tires; the faster expansion belongs to SUV Tires.
Material:
Cost tier positioning determines compound formulation priorities, with premium segments absorbing advanced elastomer costs that economy tiers cannot sustain.
- Synthetic Rubber:Styrene-butadiene and butadiene rubber blends enable precise tuning of glass transition temperatures for broad thermal operating windows. Procurement from Chinese SBR producers is accelerating as domestic petrochemical capacity expands, reducing reliance on Korean and Japanese supply.
- Natural Rubber:Polyisoprene from Thai and Indonesian plantations provides tear resistance and low-heat buildup critical for heavy-load applications. Price volatility in Southeast Asian spot markets is forcing compounders toward longer-term offtake agreements to stabilize input costs.
- Polyester:High-tenacity fiber carcass materials reduce rolling mass versus rayon alternatives.
- Steel:Bead wire and belt plies provide structural integrity for high-speed and load-rated fitments.
Input cost pressures fall heaviest on Natural Rubber; Synthetic Rubber formulations are gaining formulation share fastest.
Performance Category:
Application severity dictates performance tier selection, with highway-biased segments prioritizing wear life and mixed-terrain use cases demanding compromised durability.
- Grand Touring:Asymmetric tread patterns with variable-pitch sequencing and advanced noise-cancellation foam layers target luxury vehicle fitments. OEM specification in German premium marques and extended treadwear warranties in the aftermarket sustain margin premiums above standard touring tiers.
- All-Terrain:Open-shoulder designs with interlocking tread blocks and cut-resistant compound packages address crossover owners seeking gravel and light-mud capability. Adoption is climbing among Subaru and Toyota platform owners in the United States who reject dedicated winter swaps.
- Touring:Balanced wet-grip and wear-performance specifications serve mainstream replacement demand.
- High Performance:Stiff sidewall constructions and summer-biased compounds trade cold-weather elasticity for dry-road response.
Factory fitments concentrate in Grand Touring; aftermarket mix is shifting fastest toward All-Terrain.
Distribution Channel:
Customer type fragmentation—fleet versus retail, informed versus price-sensitive—channels volume through divergent fulfillment architectures with incompatible service expectations.
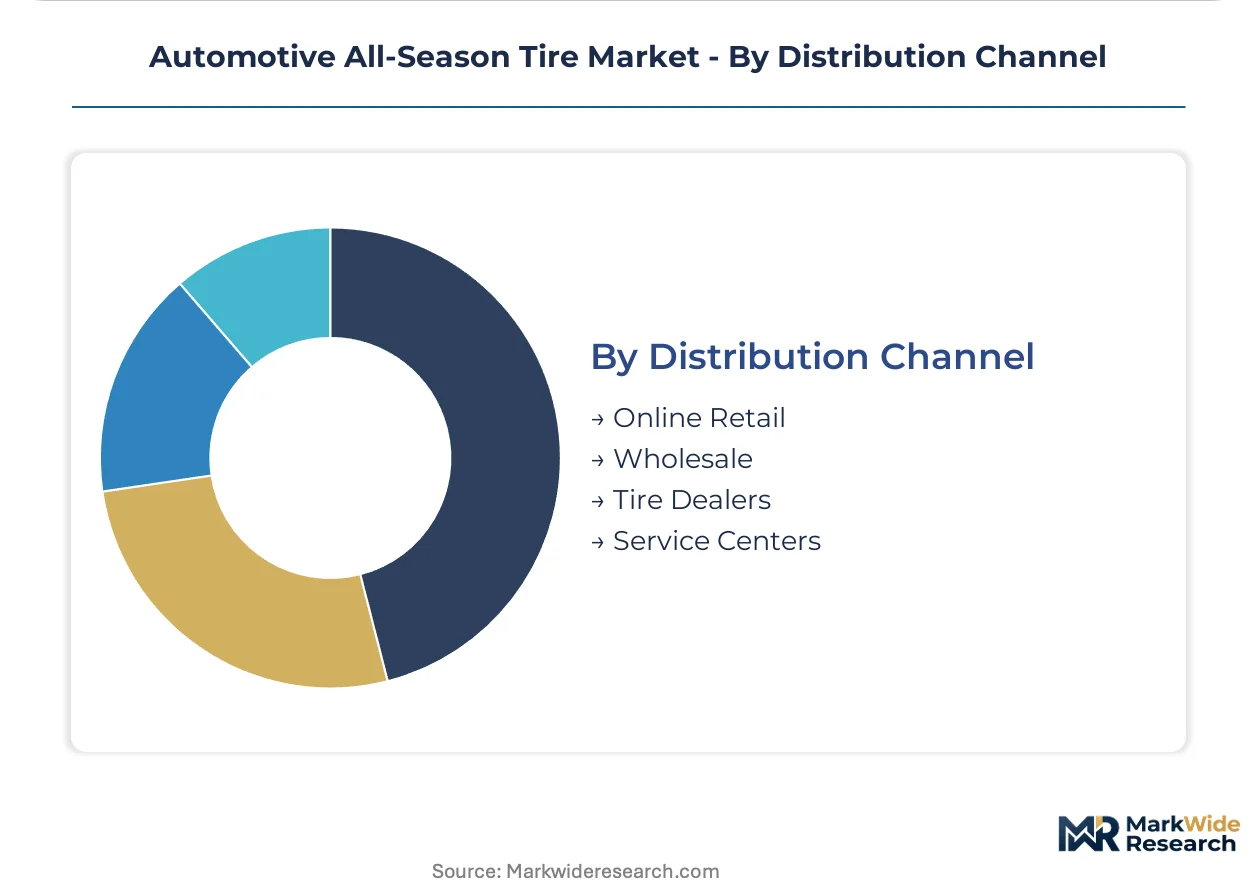
- Tire Dealers:Specialist installers with mounting and balancing equipment capture replacement demand from consumers seeking professional guidance. Regional chains in the United States and independent fitters in Europe consolidate procurement through wholesale distributors, extracting volume discounts that compress supplier margins.
- Online Retail:Direct-to-consumer platforms with drop-ship fulfillment and mobile installation partnerships are eroding traditional dealer share. Growth concentrates among millennial vehicle owners in China and the United States who prioritize price transparency and scheduling convenience over in-person consultation.
- Wholesale:Distributor networks supplying independent garages and small retailers.
- Service Centers:OEM-affiliated and national quick-lube chains bundling tire replacement with maintenance services.
Transaction volume concentrates in Tire Dealers; channel expansion is occurring fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang New Area and adjacent Yangtze River Delta special economic zones concentrate all-season tire demand through integrated EV manufacturing clusters serving both domestic OEM fitment and export channels.
United States
Ride-hailing fleet operators in Texas and Florida drive replacement volume through year-round operational mandates. EPA Corporate Average Fuel Economy standards enforce rolling resistance benchmarks that compounders must meet for market access. Tennessee's manufacturing corridor anchors Continental and Bridgestone production capacity serving Detroit Three OEM programs.
Germany
Grand Touring aftermarket demand concentrates among luxury vehicle owners in Bavaria and Baden-Württemberg seeking extended treadwear warranties. EU tire labeling regulation mandates declared ice-grip performance classes alongside wet-braking grades. Continental's Hanover R&D complex develops integrated tire sensor systems pairing with all-season tread architectures.
China
BYD and Geely scale electrified SUV platforms requiring factory-fit all-season specifications with higher load ratings for battery weight penalties. MIIT energy consumption rules and GB standards add parallel compliance layers for domestic OEM fitment programs. Shandong Province's petrochemical corridor expands SBR production capacity reducing reliance on Korean supply.
India
Last-mile delivery networks in Maharashtra and Karnataka consolidate procurement around single-fitment tires to eliminate seasonal downtime. BIS certification expansion for mandatory tire labeling creates first-mover advantage for suppliers establishing local testing partnerships ahead of enforcement deadlines. Chennai's automotive belt hosts regional distribution hubs serving southern fleet operators.
Brazil
Crossover platform proliferation from São Paulo-based automaker assembly drives reinforced sidewall demand for higher center-of-gravity vehicles. ANVISA import harmonization under Mercosur technical regulations streamlines homologation pathways for South American distribution expansion. ABC Paulista industrial corridor concentrates tire mounting and balancing service infrastructure for aftermarket replacement.
Automotive All-Season Tire Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium-tier suppliers commanding margin premiums through compound expertise while economy-tier fabricators compete on throughput scale. The structure concentrates among five multinational conglomerates controlling OE fitment certification pipelines, with regional specialists occupying aftermarket niches through price-aggressive positioning. Three archetypes dominate: integrated rubber-to-retail conglomerates, technology-licensing compound specialists, and private-label contract manufacturers serving price-sensitive channels. Competitive moves center on silica dispersion R&D investment and backward integration into synthetic rubber feedstocks.
Within the integrated conglomerate tier, Michelin and Bridgestone exemplify archetypes differentiated by geographic manufacturing footprint and OE certification depth. Continental occupies a position emphasizing sensor-embedded tread systems. These three anchors demonstrate how compound expertise and manufacturing scale combine to defend premium positioning against regional price competitors.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone |
| Continental |
| Goodyear |
| Pirelli |
| Hankook |
| Yokohama |
| Sumitomo Rubber |
| Nokian Tyres |
| Others |
Value Chain & Pricing Dynamics
Silica dispersion specialists in Germany's Ruhr industrial belt command wage premiums that widen spreads between Grand Touring and economy-tier pricing. Labor-cost differentials between Western European compounder expertise and Southeast Asian manufacturing capacity feed directly into three-tier pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Short lead-time premiums apply to sensor-embedded all-season tires serving German logistics fleets operating tire-as-a-service contracts. Price differentiation hinges on ECE R30 certification grade and silica compound sophistication, with OEM-specified fitments carrying brand premiums over aftermarket equivalents. Cost compression in economy tiers is intensifying because Chinese SBR capacity expansion floods spot markets with undifferentiated radial constructions. Fleet procurement managers exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while independent retail buyers in India and Brazil drive hardest bargain hunting.
Supply Chain Analysis
Regional distribution centers in Tennessee, Hanover, and Shanghai anchor hub-and-spoke fulfillment architectures serving OEM fitment and aftermarket replacement channels. Manufacturing concentrates in Germany, China, and the United States, with Thailand and Indonesia anchoring natural rubber feedstock supply. Raw material dependencies center on styrene-butadiene rubber from Shandong petrochemical corridors, Thai polyisoprene plantations, and high-surface-area silica from Chinese specialty chemical producers. Single-source vulnerability in Southeast Asian natural rubber exposes compounders to commodity price swings. Distribution runs through wholesale distributor networks supplying tire dealers, with direct-to-fleet procurement bypassing traditional channels in German and Dutch markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EU REACH chemical restrictions and EPA rolling resistance benchmarks erect formidable barriers against non-compliant entrants. Regulatory fragmentation across jurisdictions creates durable moats for manufacturers maintaining parallel certification pipelines.
For Market Incumbents: Deploy sensor-embedded tread systems as the primary defensive lever against direct-to-fleet disintermediation threatening wholesale distributor relationships. Deepen backward integration into synthetic rubber feedstocks to insulate margin from Thai and Indonesian natural rubber volatility. Capacity expansion in Tennessee and Shandong Province secures proximity to Detroit Three and BYD OEM programs respectively. For New Entrants and Emerging Players: Enter via India BIS certification partnerships ahead of mandatory tire labeling enforcement deadlines, capturing first-mover positioning in Maharashtra and Karnataka last-mile delivery networks. White-space concentration sits with regional courier cooperatives bypassing Amazon DSP procurement consolidation. Mobile installation partnerships with online retail platforms offer lowest-friction go-to-market pathway versus dealer network buildout. For Investors and Strategic Acquirers: Re-rating potential sits with silica-silane coupling specialists given fleet electrification catalysts compressing replacement cycles and demanding higher load-rated compounds. Long-term viability favors compounders demonstrating dynamic mechanical analysis proficiency and integrated tire-pressure-monitoring convergence capabilities. Signal to watch: Tesla and BYD procurement team specifications for fifteen percent rolling resistance reduction becoming aftermarket premium tier standard.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Silane Coupling R&D Investment | Functionalized compound systems meet Tesla and BYD procurement specifications for electric vehicle platforms. |
| Backward Integration into SBR Feedstocks | Shandong Province petrochemical capacity expansion reduces Korean supply dependency and stabilizes input costs. |
| Integrated Tire Sensor System Development | Continental's Hanover R&D complex pairs predictive replacement scheduling with fleet telematics platforms. |
| Direct-to-Fleet Procurement Model Adoption | Amazon DSP networks and German logistics markets displace upfront purchase transactions with per-kilometer billing. |
| Multi-Jurisdiction Homologation Streamlining | Parallel EPA, ECE R30, and GB certification tracks compress eight-to-fourteen month product launch windows. |
Study Parameters
Document review covered customs and trade data, SEC 10-K filings, vehicle production databases, and IHS Markit registration data, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers. Primary fieldwork engaged compounder R&D directors and tire dealer network owners across the United States, Germany, and China. Secondary validation drew from EPA fuel economy filings, EU tire labeling registries, and MIIT energy consumption disclosures. Bottom-up unit economics triangulated against top-down market sizing across vehicle class, propulsion architecture, and regional production cluster dimensions.
Segmented volume and value trajectories emerged from elasticity modeling across passenger, SUV, light truck, and crossover fitment categories throughout the projection horizon. The analytical framework incorporated glass transition temperature boundaries, load index rating shifts for battery weight penalties, and replacement cycle compression from fleet electrification. CAGRs derived from regression against historical OEM fitment ratios and aftermarket mix shifts. Modeled inputs included ride-hailing fleet mileage accumulation patterns, silica compound adoption curves, and regulatory enforcement timelines for India BIS and Brazil ANVISA pathways.
Revisions become necessary when natural rubber price volatility exceeds historical bands, EU REACH chemical restrictions tighten polycyclic aromatic hydrocarbon limits, or Nordic winter tire substitution accelerates below minus seven degrees Celsius. Forecasts reflect documented assumptions around fleet electrification penetration and OEM platform standardization trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
GCC Tire Market