
 North America Alloy Wheels Market | 2026-2036
North America Alloy Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alloy Wheels Market Insights
Buyer concentration among North American automakers is shifting as electric vehicle specialists and legacy OEMs split procurement volumes across multiple wheel suppliers. Superior Industries International anchors its position through manufacturing scale across Mexican and U.S. plants. Alcoa Wheels differentiates via in-house aluminum smelting and forged wheel expertise for commercial vehicle segments. Enkei Corporation competes on flow-forming technology leadership that reduces unsprung mass for performance-oriented OEM programs.
Alloy wheels are non-ferrous metal wheel assemblies, typically aluminum or magnesium alloy, manufactured through casting, forging, or flow-forming processes with typical specifications including 15-22 inch diameters and load ratings exceeding 2,000 pounds per wheel, designed primarily to reduce unsprung weight and improve vehicle handling, braking, and fuel efficiency. The forged segment commands premium positioning due to superior strength-to-weight ratios and durability under high-stress commercial applications, while the lightweight cast category extends volume through cost-sensitive OEM fitments on mass-market sedans and crossovers. Aftermarket demand concentrates in custom finishes where glossy and matte treatments capture enthusiast spending, though OEM channels dominate absolute unit flows through multi-year platform supply agreements.
NHTSA safety standards and EPA fuel economy mandates jointly shape alloy wheel specifications, forcing material and design trade-offs between crashworthiness and mass reduction across the U.S. and Canadian vehicle fleets. The EPA's greenhouse gas regulations for light-duty vehicles indirectly accelerate magnesium and carbon-fiber hybrid wheel research as manufacturers seek incremental weight savings. California Air Resources Board zero-emission vehicle requirements extend influence into wheel supplier technical roadmaps through weight-sensitive range optimization. Stakeholders must monitor how domestic content requirements in pending U.S. trade legislation reshape sourcing decisions for aluminum billet and finished wheel imports from Canadian and Mexican production bases.
Market Dynamics
The EPA's tightened corporate average fuel economy standards are forcing automakers to reweight every pound of unsprung mass, accelerating magnesium alloy adoption and flow-forming process investments across OEM supply chains.
Growth Catalysts
- EPA Fuel Economy Mandates:Light truck and SUV manufacturers are expanding factory-fit forged alloy specifications to meet Corporate Average Fuel Economy targets, driving specification upgrades across Detroit Three lineups.
- Electric Vehicle Weight Optimization:Range-sensitive EV platforms are specifying 19-22 inch flow-formed wheels to offset battery mass, with Michigan and Ontario assembly plants leading implementation.
- Great Lakes Manufacturing Density:Concentrated stamping and casting capacity across Ohio, Michigan, and Ontario creates localized supplier ecosystems with 48-hour JIT delivery windows to assembly plants.
Market Restraints
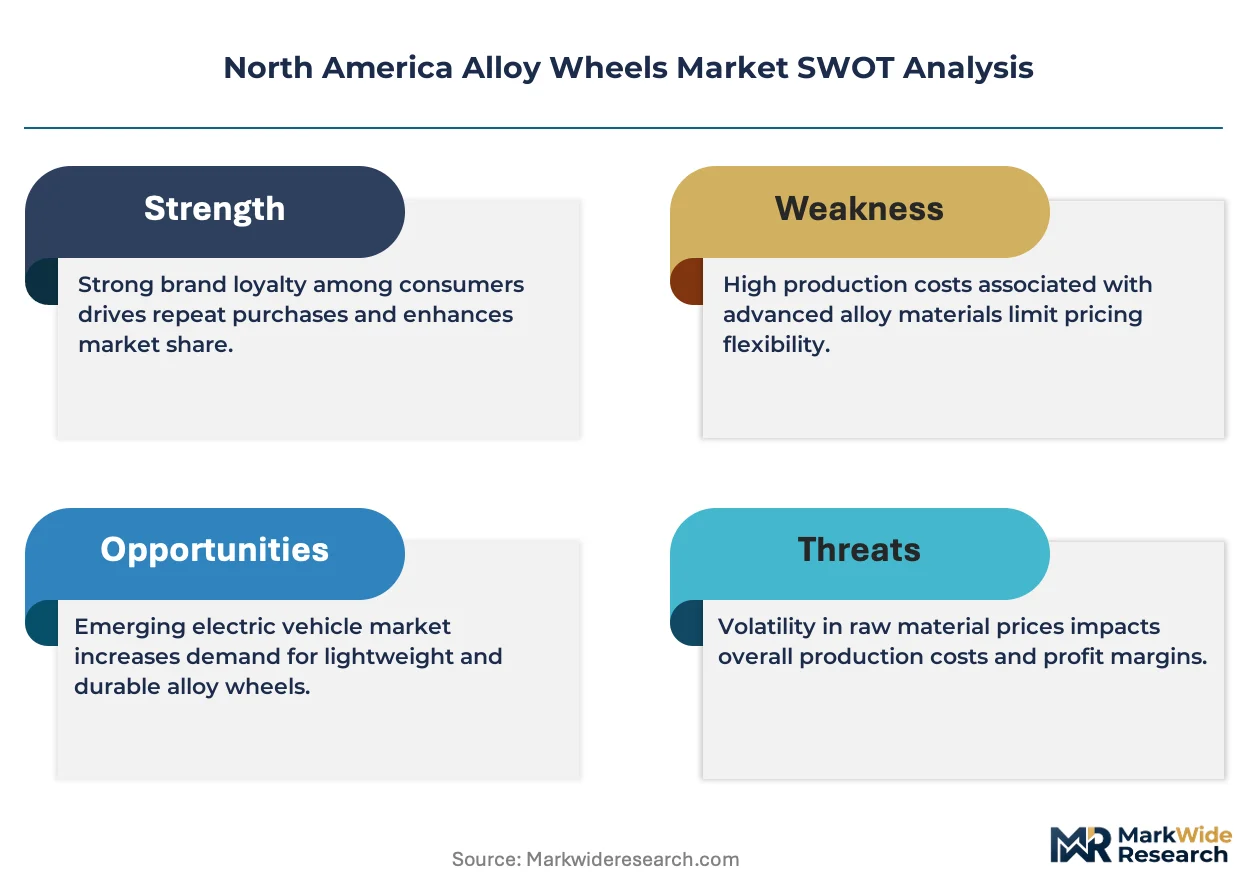
- Magnesium Price Volatility:Primary magnesium ingot sourced from Chinese smelters faces tariff exposure and energy cost pass-through, compressing margins on lightweight wheel programs.
- Monopsony Buyer Power:Consolidated Detroit Three and Tesla procurement desks extract multi-year price-down schedules, limiting supplier pricing leverage on platform contracts.
- Cast Aluminum Substitution Ceiling:Conventional A356.2 cast wheels hit strength-to-weight limits above 20-inch diameters, blocking entry into heavy-duty commercial fitments without forging cost premiums.
Strategic Opportunities
- Mexico Nearshoring Expansion:Nuevo Leon and Queretaro wheel plants can capture incremental GM and Ford EV platform volumes under USMCA rules of origin compliance.
- Carbon-Fiber Hybrid Rims:Emerging aluminum-carbon fiber hybrid construction techniques promise 30% mass reduction for premium EV sports variants, opening technology licensing revenue streams.
- California ZEV Weight Credits:CARB zero-emission vehicle regulations implicitly reward range-extending lightweight components, creating specification pull for magnesium-intensive wheel designs.
Industry Challenges
- Flow-Forming Technician Scarcity:Specialized CNC roll-forming operators command 40% wage premiums in Detroit and Windsor labor markets, constraining capacity expansion timelines.
- Multi-Material Welding Certification:NHTSA crashworthiness validation for magnesium-aluminum hybrid wheel assemblies requires 18-24 month homologation cycles, delaying platform launches.
- Legacy ERP Integration:Tier-two foundries struggle to synchronize production scheduling with OEM cloud-based supplier portals, causing forecast mismatch penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alloy Wheels Market |
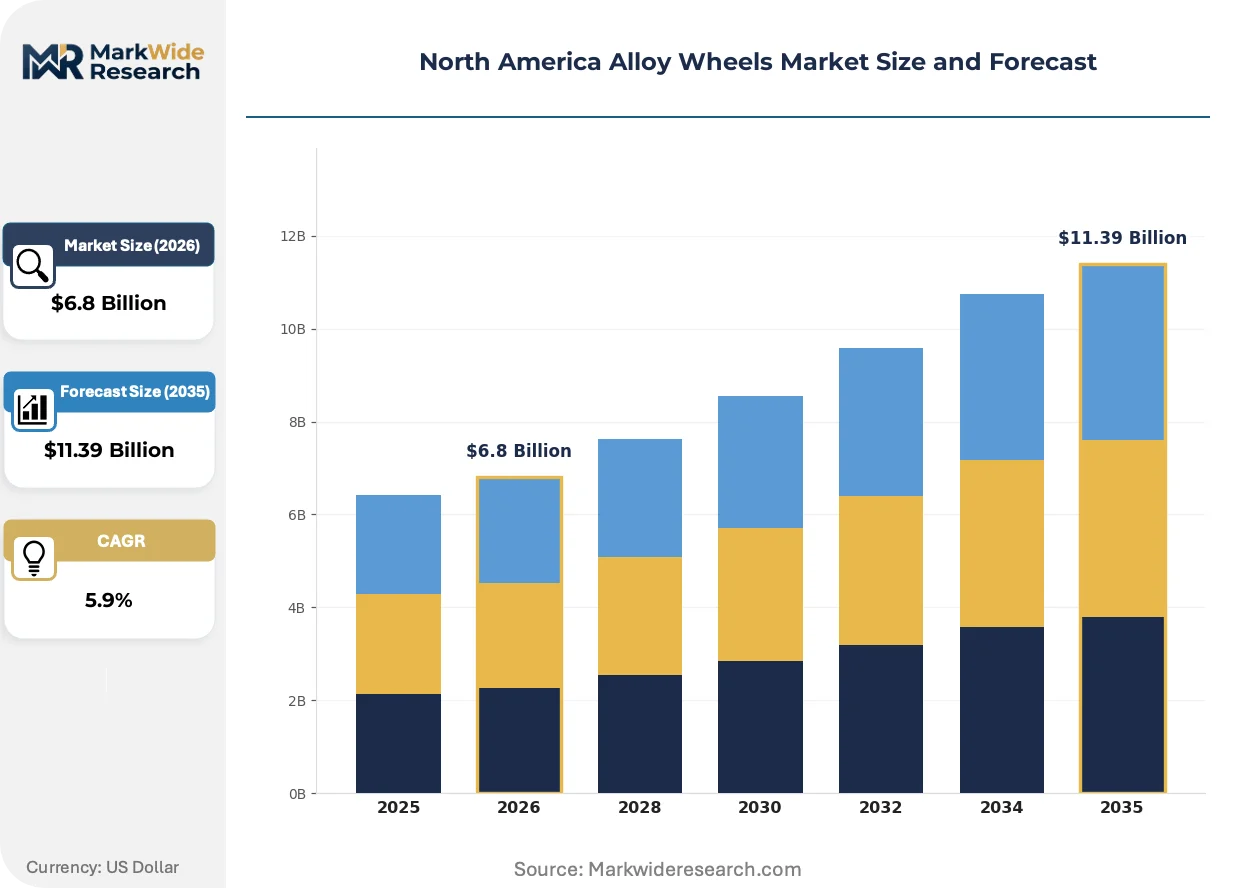
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight, Cast, Forged, Custom End User: OEMs, Aftermarket, Automotive Enthusiasts, Rental Services Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch Finish: Glossy, Matte, Polished, Anodized |
| Companies Covered | Superior Industries International, Alcoa Wheels, Enkei Corporation, American Racing, OZ Racing, Borbet GmbH, TSW Alloy Wheels, Maxion Wheels, Accuride Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alloy Wheels Market Trends and Innovations
Active material substitution and regulatory-driven mass reduction targets are compressing traditional casting dominance while elevating advanced forming processes and hybrid material architectures.
Flow-forming technology is integrating into mainstream OEM wheel supply through computer-controlled roller die compression that thins barrel walls while preserving rim strength. Light truck manufacturers in Michigan and Texas are specifying these wheels for 2026 model year refreshes. This process integration is compressing the cost gap between cast and forged constructions across 18-20 inch diameter segments.
NHTSA safety standards are tightening dynamic radial fatigue test requirements for wheels above 3,500 pound vehicle gross weights, forcing commercial vehicle suppliers to redesign bead seat geometries. The EPA's indirect greenhouse gas regulations for light-duty vehicles are simultaneously pushing material substitution toward magnesium alloys. Heavy-duty pickup platforms face the tightest compliance squeeze, accelerating hybrid aluminum-magnesium wheel research.
Fleet procurement desks are consolidating wheel specifications across multiple nameplates to extract volume pricing, collapsing previous brand-specific design variations. Tier-one suppliers are responding with modular wheel families sharing core castings but differentiated through finish and cap treatments. This specification consolidation is most visible in Detroit Three full-size SUV and light truck programs where common wheel architectures now span Chevrolet, GMC, and Cadillac lineups.
North America Alloy Wheels Market Segmentation
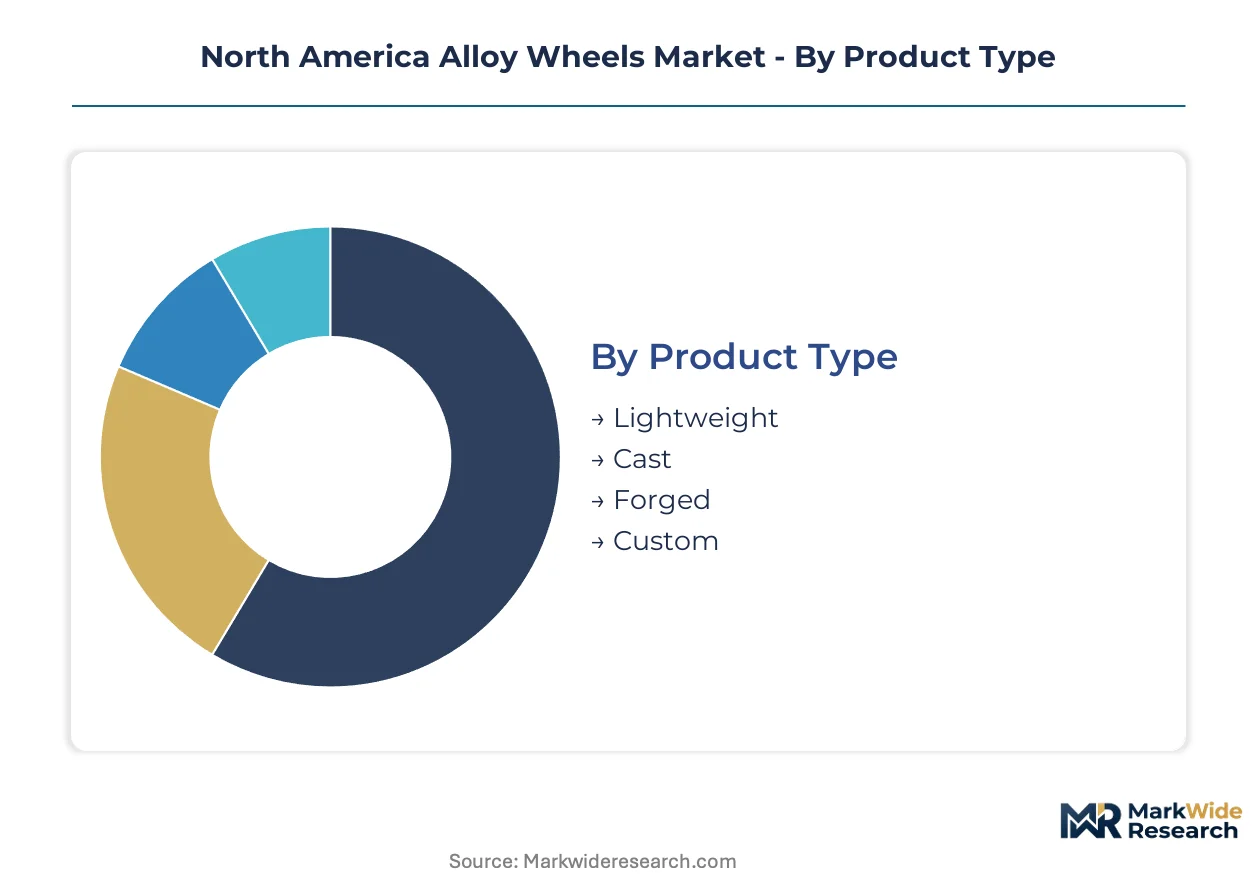
Alloy wheel specifications fragment across manufacturing process, procurement channel, dimensional requirements, and surface treatment. Each segmentation axis carries distinct margin profiles and regulatory exposure across the North American automotive supply base.
Product Type:
Manufacturing technology determines strength-to-weight ratios and cost positioning across OEM and aftermarket channels.
- Forged:Aluminum or magnesium billets undergo high-pressure compression forming, yielding grain-aligned microstructures with superior fatigue resistance. Heavy-duty commercial platforms in Michigan and Texas specify these wheels to meet NHTSA dynamic load requirements under tightened EPA fuel economy mandates.
- Lightweight:Advanced flow-forming and hollow-spoke designs shave 15-30% mass versus conventional castings. Electric vehicle assembly plants in Ontario and Ohio prioritize this specification to offset battery pack weight and extend driving range.
- Cast:Gravity and low-pressure die casting of A356.2 aluminum dominates mass-market sedan and crossover fitments through cost-efficient volume production.
- Custom:Bespoke forging and finishing operations serve enthusiast segments with unique offset, width, and spoke configurations outside standard OEM specifications.
Mature deployment sits with Cast wheels across Detroit Three high-volume platforms. Newer deployment is concentrated in Lightweight specifications for EV architectures.
End User:
Procurement channel fragmentation creates divergent pricing power and technical specification authority.
- OEMs:Multi-year platform supply agreements with GM, Ford, and Stellantis govern 70%+ of North American alloy wheel volume. These contracts embed annual price-down schedules and JIT delivery requirements with 48-hour windows to Great Lakes assembly plants.
- Aftermarket:Distributor and retailer channels stock replacement wheels for collision repair and wear-cycle refresh, with demand clustering in metropolitan markets with higher vehicle age profiles.
- Automotive Enthusiasts:Track-day participants and show-car builders commission forged monoblock and multi-piece configurations with aggressive fitments and custom finishes.
- Rental Services:Fleet operators standardize wheel specifications across nameplates to simplify maintenance and damage replacement protocols at high-turnover locations.
Volume concentration favors OEMs through consolidated procurement desks. Margin expansion is climbing the fastest in Automotive Enthusiast channels with premium forging premiums.
Size:
Wheel diameter specifications track vehicle class segmentation and brake package requirements.
- 18 Inch:Dominant specification for mid-size crossovers and light trucks, accommodating larger brake rotors while maintaining sidewall compliance for ride quality. Assembly lines in Ohio and Kentucky run this diameter at highest volume.
- 17 Inch:Compact sedan and entry crossover standard, balancing cost efficiency with adequate brake clearance for mainstream powertrains.
- 16 Inch:Economy segment and fleet vehicle specification, preserving tire cost advantages and replacement availability.
- 15 Inch:Niche application for subcompact vehicles and specific commercial van platforms with load-rated requirements.
Specification gravity centers on 18 Inch diameters for light truck and SUV proliferation. Upsizing momentum is displacing 16 Inch fitments in mainstream segments.
Finish:
Surface treatment differentiation drives aftermarket margin capture and OEM brand expression.
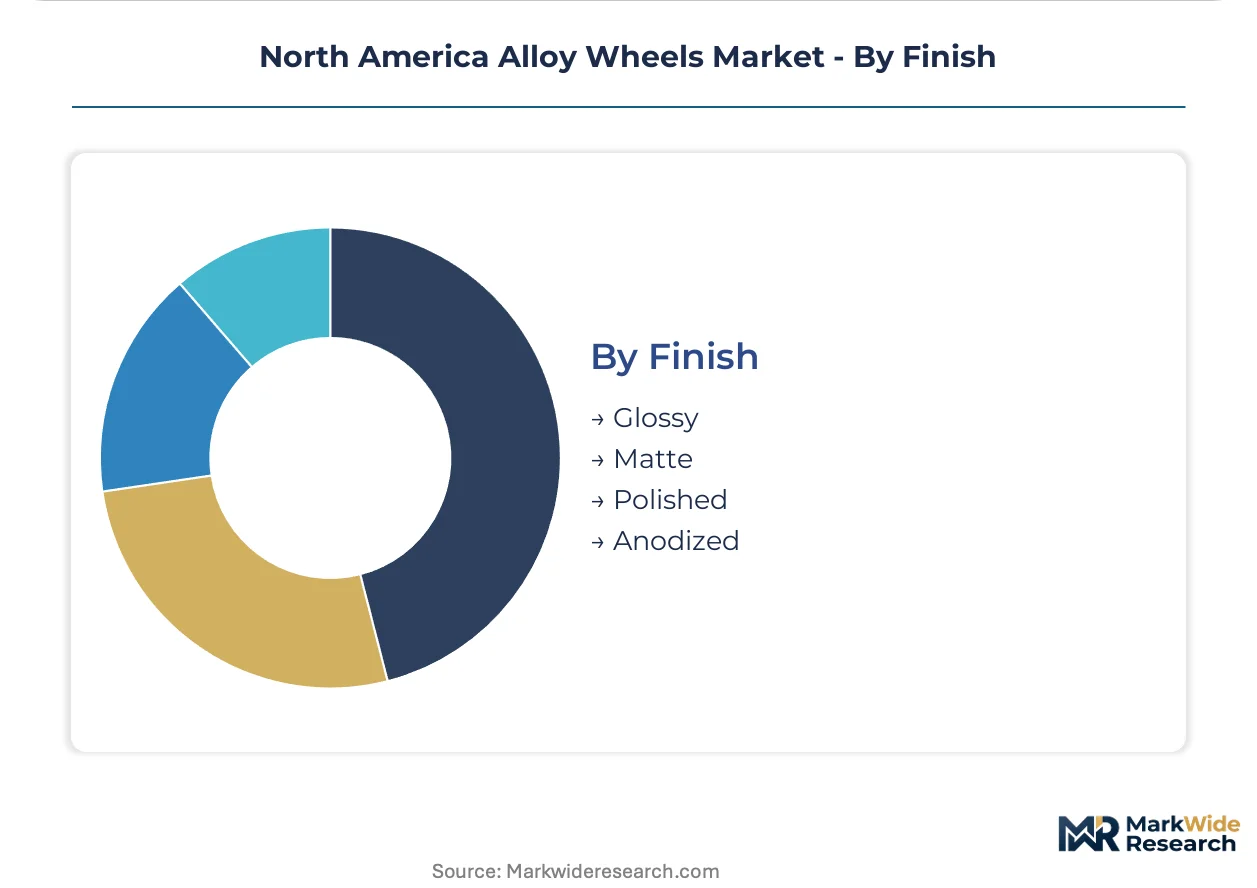
- Glossy:Clearcoat-over-basecoat systems deliver mirror-like reflectivity and color depth. Luxury nameplates specify this finish for showroom impact and premium positioning.
- Matte:Satin and flat clearcoat formulations resist brake dust visibility and fingerprints. Performance-oriented OEM programs and aftermarket customizers favor this treatment for motorsport aesthetic association.
- Polished:Mechanical buffing of aluminum surfaces creates uncoated metallic luster requiring periodic maintenance. Classic truck restorations and show vehicles sustain limited demand.
- Anodized:Electrochemical surface conversion builds wear-resistant oxide layers in tinted hues without applied coatings. Industrial and commercial applications value durability over cosmetic refinement.
Finish mix is shifting toward Matte treatments in EV lineups seeking differentiated visual identity. Glossy retains specification dominance in traditional luxury segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelting capacity in Quebec and the Ohio River Valley anchors North American alloy wheel feedstock security. Regional demand concentrates where automotive assembly density intersects with JIT logistics feasibility.
United States
Michigan and Ohio assembly plants specify 19-22 inch flow-formed wheels for electric truck platforms to offset battery mass. EPA Corporate Average Fuel Economy standards tighten through 2032, forcing material substitution toward magnesium alloys in heavy-duty applications. Detroit-Windsor corridor stamping facilities operate 48-hour delivery windows to Ford and GM plants.
Canada
Ontario EV manufacturing expansion in Windsor and Oakville drives specification upgrades for lightweight wheel programs. Environment and Climate Change Canada carbon border adjustments affect aluminum billet sourcing decisions from offshore smelters. Quebec's aluminum smelter corridor supplies primary metal to regional foundries at tariff-advantaged rates under USMCA rules.
Mexico
Nuevo León and Querétaro wheel plants capture incremental GM and Ford EV platform volumes under USMCA regional value content requirements. Mexican automotive manufacturing integration deepens as Detroit Three consolidate North American supply chains. Monterrey-area facilities leverage proximity to Texas assembly plants for cross-border JIT delivery.
North America Alloy Wheels Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-fiber hybrid architectures and magnesium-intensive designs. The supplier base concentrates around three strategic archetypes: scale-driven stamped wheel manufacturers, vertically integrated aluminum producers, and flow-forming technology specialists. Competitive positioning hardens through multi-year OEM platform contracts with embedded annual price-down schedules. Capacity expansion in Mexican border states and technology licensing for hybrid material processes represent dominant competitive moves.
Among North American-headquartered suppliers, Superior Industries International anchors the scale-driven tier through multi-plant manufacturing footprints. Alcoa Wheels exemplifies vertical integration with captive aluminum smelting capacity. Enkei Corporation occupies the precision-forming specialist position with flow-forming process leadership.
| Leading Market Players |
|---|
| Superior Industries International |
| Alcoa Wheels |
| Enkei Corporation |
| American Racing |
| OZ Racing |
| Borbet GmbH |
| TSW Alloy Wheels |
| Maxion Wheels |
| Accuride Corporation |
| Others |
Pricing and Supply Chain Analysis
Specialized CNC roll-forming technicians in Detroit and Windsor labor markets command 40% wage premiums, compressing margins on flow-formed wheel programs and widening spreads between premium forged and economy cast pricing tiers. This workforce scarcity in the Great Lakes corridor directly feeds into how suppliers structure multi-year OEM contracts versus spot aftermarket transactions.
Pricing Analysis
Volume concentrates in cast aluminum fitments for Detroit Three mass-market platforms, while margin pools accumulate in forged and flow-formed specifications for EV and heavy-duty applications. Price differentiation hinges on certification grade for NHTSA dynamic load compliance and volume scale across multi-year platform agreements. Pricing pressure stems from consolidated Detroit Three and Tesla procurement desks extracting annual price-down schedules. Fleet operators and rental services exhibit highest price sensitivity, while automotive enthusiasts accept substantial premiums for bespoke forged configurations.
Supply Chain Analysis
Workforce availability constraints in Michigan, Ohio, and Ontario limit capacity expansion timelines for precision-forming operations despite concentrated demand from regional assembly plants. Primary aluminum smelting in Quebec and the Ohio River Valley feeds regional foundries, while magnesium ingot draws from Chinese sources exposed to tariff volatility. Single-source vulnerability sits with primary magnesium supply from offshore smelters. Distribution runs through JIT 48-hour delivery windows to Great Lakes assembly plants and aftermarket distributor networks serving collision repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America alloy wheels market sits in a technology-transition phase where flow-forming and magnesium-intensive designs displace conventional cast aluminum dominance across OEM specifications.
For Market Incumbents: Extend manufacturing scale advantages through backward integration into aluminum billet production and captive flow-forming capacity additions in Nuevo León. Threats from carbon-fiber hybrid entrants and EPA fuel economy mandates demand defensive certification investments for magnesium-aluminum hybrid assemblies. Channel control through exclusive multi-year platform contracts remains the critical lever against price erosion. For New Entrants and Emerging Players: Aftermarket custom finish specialists represent an underserved buyer archetype with fragmented supply and willingness to pay premium margins. White-space targets include carbon-fiber hybrid rim licensing for premium EV sports variants and magnesium-intensive designs for California ZEV credit optimization. Go-to-market positioning through technology licensing rather than capital-intensive manufacturing buildout offers fastest penetration. For Investors and Strategic Acquirers: Re-rating potential sits with flow-forming technology specialists given EPA fuel economy mandate acceleration and EV platform proliferation. Long-term viability favors suppliers with demonstrated NHTSA homologation track records and USMCA-compliant Mexican manufacturing footprints. The signal to watch is Detroit Three EV platform award announcements as inflection indicators for specification pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Flow-Forming Capacity Expansion | Captures EPA-driven specification upgrades across GM and Ford light truck platforms. |
| Magnesium Supply Agreement | Mitigates tariff exposure on primary ingot from Chinese smelters for lightweight wheel programs. |
| NHTSA Homologation Investment | Accelerates 18-24 month validation cycles for hybrid aluminum-magnesium wheel assemblies. |
| USMCA Manufacturing Footprint | Secures regional value content compliance for Nuevo León and Querétaro wheel plants. |
| Carbon-Fiber Hybrid Licensing | Opens technology revenue streams for 30% mass reduction in premium EV applications. |
Research Methodology
Trade databases, SEC automotive supplier filings, and vehicle production registries formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and flow-forming equipment specialists. Bottom-up triangulation across wheel unit volumes by vehicle platform and top-down validation against aluminum and magnesium consumption data anchored market sizing.
Historical trendline analysis of OEM fitment rates by wheel diameter and manufacturing process informed projection modeling across the forecast period. Segmentation dimensions included manufacturing technology, procurement channel, vehicle class, and regional production cluster. CAGRs derived from regression analysis of content-per-vehicle trajectories and EV platform ramp schedules, with sensitivity testing against EPA regulatory stringency scenarios.
Revisions become necessary when NHTSA safety standard amendments, USMCA rule changes, or magnesium supply disruptions materialize outside baseline assumptions. Forecasts reflect documented judgments on technology adoption curves and regulatory enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Automotive Wheel Market