
 Carbon Aerogel Market | 2026-2036
Carbon Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Aerogel Market Analytics
REACH compliance is shifting the cost-of-entry calculus for carbon aerogel suppliers targeting European industrial buyers. Cabot Corporation leverages its carbon black infrastructure to sustain precursor cost advantages across North American manufacturing. Aerogel Technologies LLC specializes in custom monolith geometries for defense and aerospace contractors. Shanghai Aerogelzone Technology Co., Ltd. dominates domestic supply chains for battery-grade aerogel powders in East Asian electronics markets.
Carbon aerogel consists of a continuous three-dimensional network of nanoscale carbon particles with porosity exceeding 80%, bulk densities below 0.5 g/cm³, and specific surface areas surpassing 500 m²/g, produced through sol-gel polymerization of resorcinol-formaldehyde followed by supercritical drying and pyrolysis. The material serves primarily as a high-performance electrode substrate, thermal insulator, and adsorbent for heavy-metal capture in wastewater streams. Flexible aerogel formats occupy the largest revenue pool in building envelope retrofits where conformability to irregular substrates commands premium positioning. Energy storage applications represent the fastest-expanding segment as supercapacitor manufacturers specify ultralight aerogel architectures to maximize gravimetric capacitance. Rigid aerogel panels remain mature in oil and gas pipeline insulation, with margin compression from standardized production protocols and commodity pricing dynamics.
The EPA enforces particulate emissions thresholds during pyrolysis stages, while China's MEE imposes dual carbon goals that constrain coal-derived precursor pathways. ISO 9001 and IEC technical standards govern quality assurance for electronics-grade aerogel supply into semiconductor fabrication facilities. Stakeholders must monitor evolving carbon-accounting methodologies that could reclassify synthetic versus bio-based precursor routes under emerging scope-three disclosure regimes.
Market Dynamics
Supercapacitor electrode procurement is concentrating around Ludwigshafen and Leverkusen, where chemical conglomerates anchor pilot production programs and reshape supplier qualification criteria for monolithic carbon aerogel architectures.
Growth Catalysts
- EU Green Deal carbon border adjustments:Tightening embodied-emissions standards for imported insulation materials are redirecting procurement toward domestic aerogel producers with verified carbon-accounting methodologies.
- Energy storage manufacturers:Scaling procurement of monolithic carbon aerogels for supercapacitor electrodes is pulling capacity expansion across pyrolysis and supercritical drying infrastructure.
- Sol-gel polymerization advances:Process intensification in resorcinol-formaldehyde precursor synthesis is compressing batch cycle times and improving pore-size distribution control.
Market Restraints
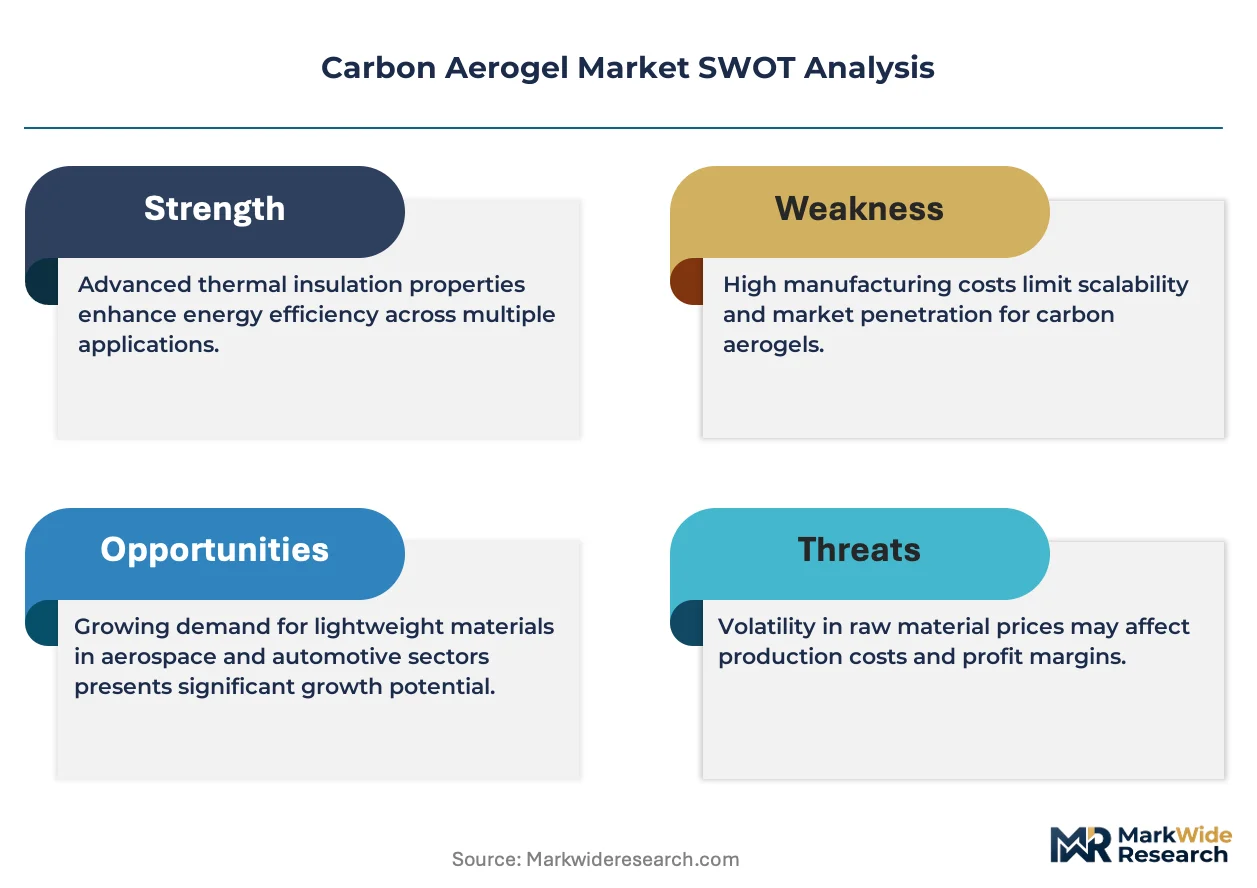
- Resorcinol cost volatility:Petrochemical feedstock price swings compress margin predictability for synthetic precursor routes.
- Supercritical drying equipment concentration:Limited installed base of high-pressure CO2 systems in North America and Europe creates bottleneck risk.
- Rigid panel commoditization:Standardized oil and gas pipeline insulation specifications eliminate performance-based pricing premiums.
Strategic Opportunities
- India PLI scheme for advanced chemistry cell manufacturing:Domestic battery-grade aerogel powder production can capture incentives targeting electrode material localization.
- Bio-based precursor routes:Lignin-derived carbon aerogels from pulp and paper waste streams qualify for emerging scope-three carbon disclosure preferences.
- Defense and aerospace custom monoliths:Non-standard geometries for thermal protection systems command pricing multiples unavailable in commodity formats.
Industry Challenges
- Pyrolysis emissions compliance:EPA particulate thresholds and MEE dual carbon goals require continuous emissions monitoring system investments.
- Electronics-grade certification timelines:ISO 9001 and IEC technical standard audits for semiconductor fabrication supply extend qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Aerogel Market |
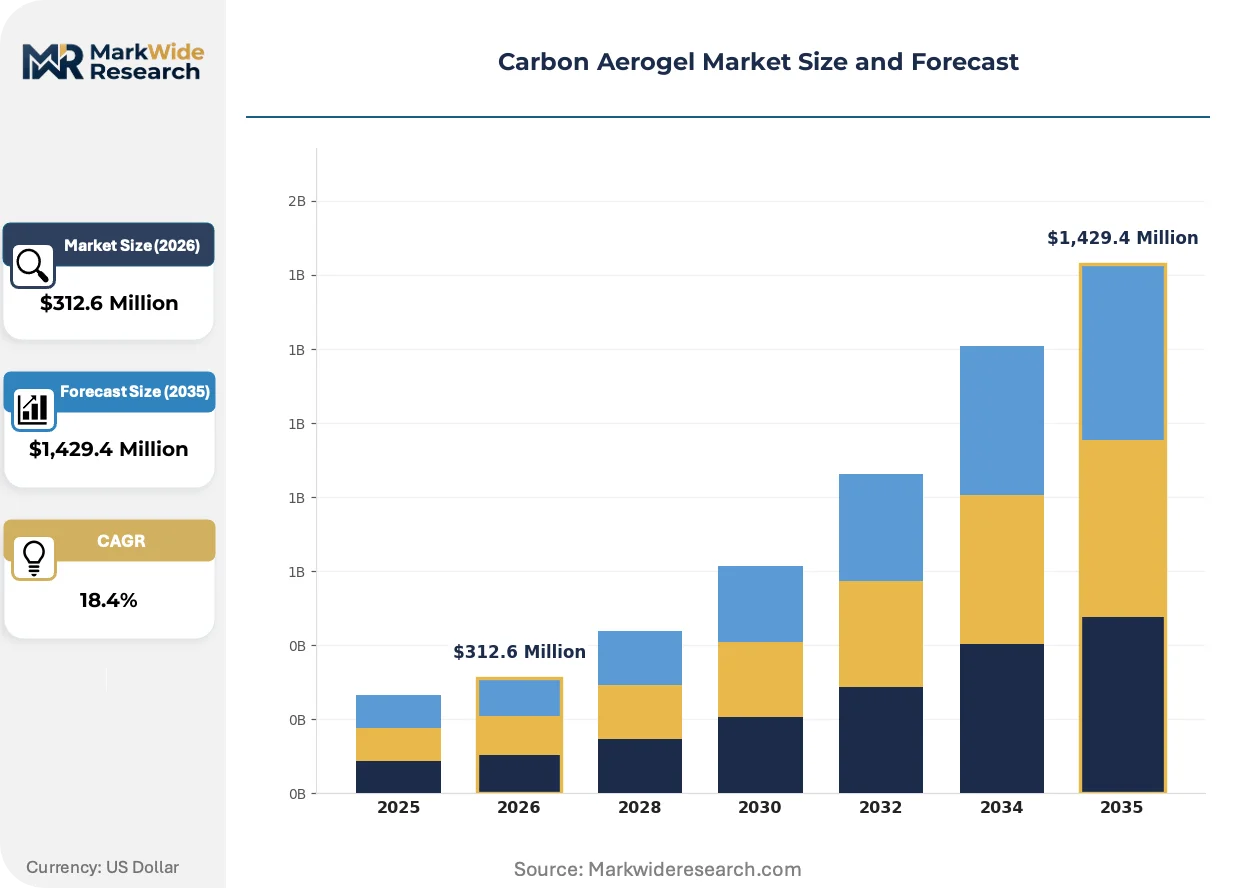
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,429.4 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Aerogel, Rigid Aerogel, Composite Aerogel, Ultralight Aerogel Application: Aerospace, Insulation, Energy Storage, Environmental Remediation End User: Construction, Electronics, Automotive, Oil & Gas Form: Granules, Films, Monoliths, Powders |
| Companies Covered | Cabot Corporation, Nanolit, Aerogel Technologies LLC, Shanghai Aerogelzone Technology Co., Ltd., High Tech Material Solutions, American Elements, Aspen Aerogels, KEEY Aerogel, Green Earth Aerogel Technologies (GEAT), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Aerogel Market Evolving Landscape
Carbon aerogel manufacturing is bifurcating between commodity rigid panels and engineered monoliths, with process control capabilities becoming the primary competitive differentiator across end-use verticals.
Continuous-flow sol-gel processing is overtaking batch reactor configurations for resorcinol-formaldehyde polymerization. Supercapacitor electrode manufacturers in Germany and South Korea are specifying flow-synthesized aerogels for improved pore-size uniformity. This technology is overtaking conventional batch methods in premium electrode applications where gravimetric capacitance tolerances tighten below 5%.
REACH authorization requirements for formaldehyde-based precursors are extending compliance documentation burdens. ECHA substance evaluation workflows now require full life-cycle carbon footprint disclosure for imported aerogel materials. European industrial buyers are consolidating supplier panels to entities with in-house environmental product declaration capabilities.
Battery-grade powder specifications are hardening procurement qualification protocols. East Asian electronics manufacturers now mandate particle size distributions below 50 microns and surface area minima above 600 m²/g. Chinese MEE enforcement of dual carbon goals is accelerating domestic substitution of coal-derived precursor pathways with biomass alternatives.
Carbon Aerogel Market Segmentation
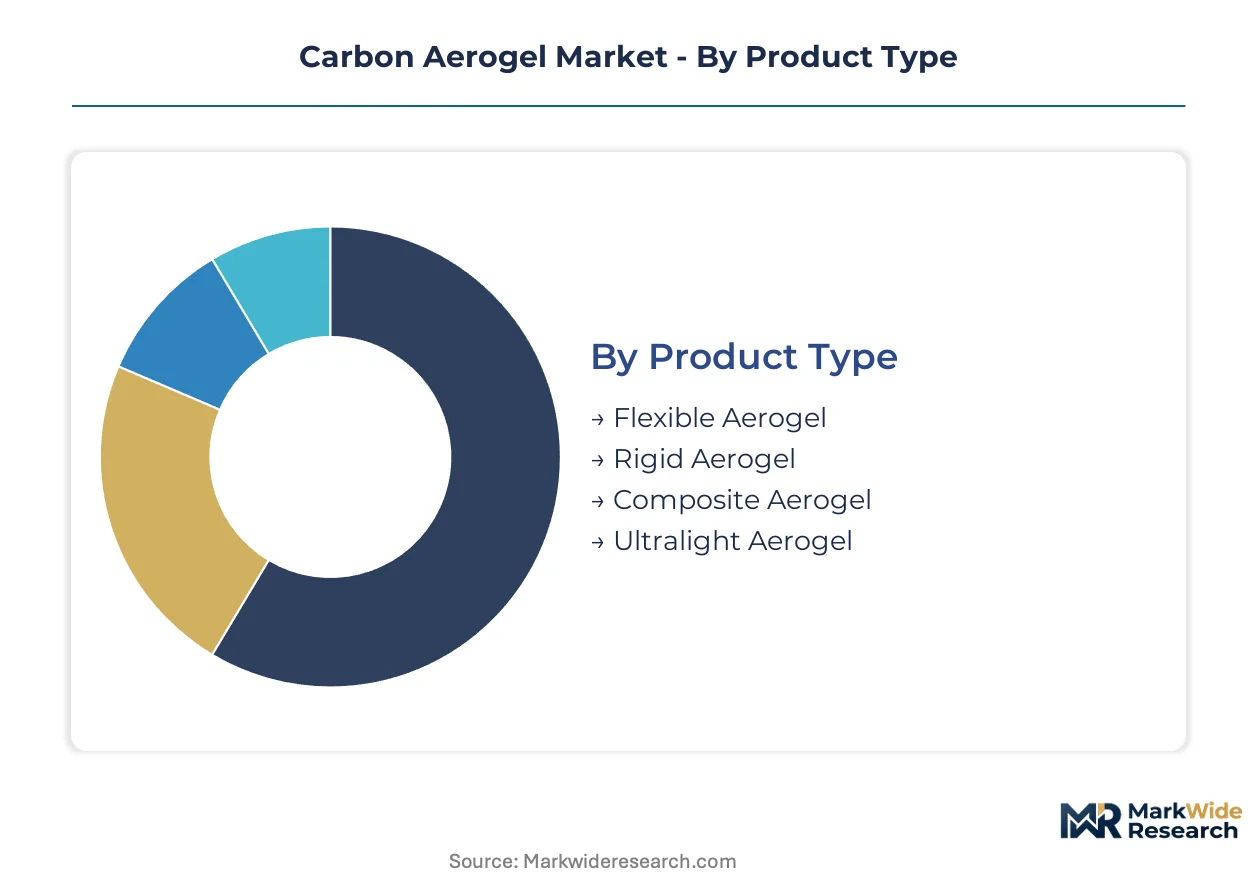
Carbon aerogel specifications diverge sharply across thermal, electrical, and mechanical performance requirements. Procurement patterns track end-use certification tiers rather than commodity pricing. Manufacturers configure sol-gel protocols and pyrolysis parameters to match segment-specific porosity and conductivity targets.
Product Type:
Structural density and compressibility define the manufacturing pathway and capital intensity for each format.
- Flexible Aerogel:Polymer-reinforced carbon matrices with bend radii below 5mm retain thermal conductivity below 0.020 W/m·K. Building envelope retrofits in Germany's industrial corridor around Ludwigshafen and Leverkusen concentrate procurement where conformability to irregular substrates commands premium positioning.
- Ultralight Aerogel:Bulk densities below 0.1 g/cm³ enable gravimetric capacitance maximization in supercapacitor electrodes. Energy storage manufacturers in South Korea specify these architectures for electric vehicle powertrains where every gram reduction extends range.
- Rigid Aerogel:Standardized panels serve mature oil and gas pipeline insulation with compressed margins from commodity pricing dynamics.
- Composite Aerogel:Hybrid structures with glass or ceramic reinforcement target aerospace thermal protection systems requiring ablation resistance.
Mature deployment sits with Rigid Aerogel. Newer deployment is concentrated in Ultralight Aerogel.
Application:
Performance validation protocols and certification timelines segment the addressable market by technical barrier height.
- Energy Storage:Supercapacitor electrode applications demand surface areas above 600 m²/g and pore-size distributions below 50nm for ion transport optimization. Pilot production programs at chemical conglomerates in Germany are reshaping supplier qualification criteria for monolithic architectures.
- Insulation:Thermal conductivity specifications below 0.015 W/m·K drive specification in EU Green Deal compliance scenarios where embodied-emissions documentation is mandatory for carbon border adjustment eligibility.
- Aerospace:Re-entry vehicle heat shields and satellite thermal management require non-standard geometries with pricing multiples unavailable in commodity formats.
- Environmental Remediation:Heavy-metal capture in wastewater streams leverages high surface area for adsorption capacity, though volume scales remain constrained by regeneration cost economics.
Insulation commands the largest revenue pool. Energy Storage is climbing the fastest as electrode material localization incentives accelerate capacity buildout.
End User:
Customer technical capabilities and integration complexity determine the viable supplier base for each vertical.
- Electronics:Semiconductor fabrication facilities enforce ISO 9001 and IEC technical standards that extend qualification cycles but lock in multi-year supply agreements for qualified powder suppliers.
- Oil & Gas:Pipeline operators specify rigid panel formats with standardized installation protocols, eliminating performance-based pricing premiums through procurement centralization.
- Construction:Building envelope contractors prioritize flexible formats for retrofit accessibility, with REACH compliance documentation increasingly mandatory for EU project eligibility.
- Automotive:Battery pack thermal management and lightweight structural components drive specification, though qualification timelines lag electronics by 18-24 months.
Electronics maintains the stickiest supplier relationships. Automotive is expanding most quickly as electric vehicle platforms proliferate.
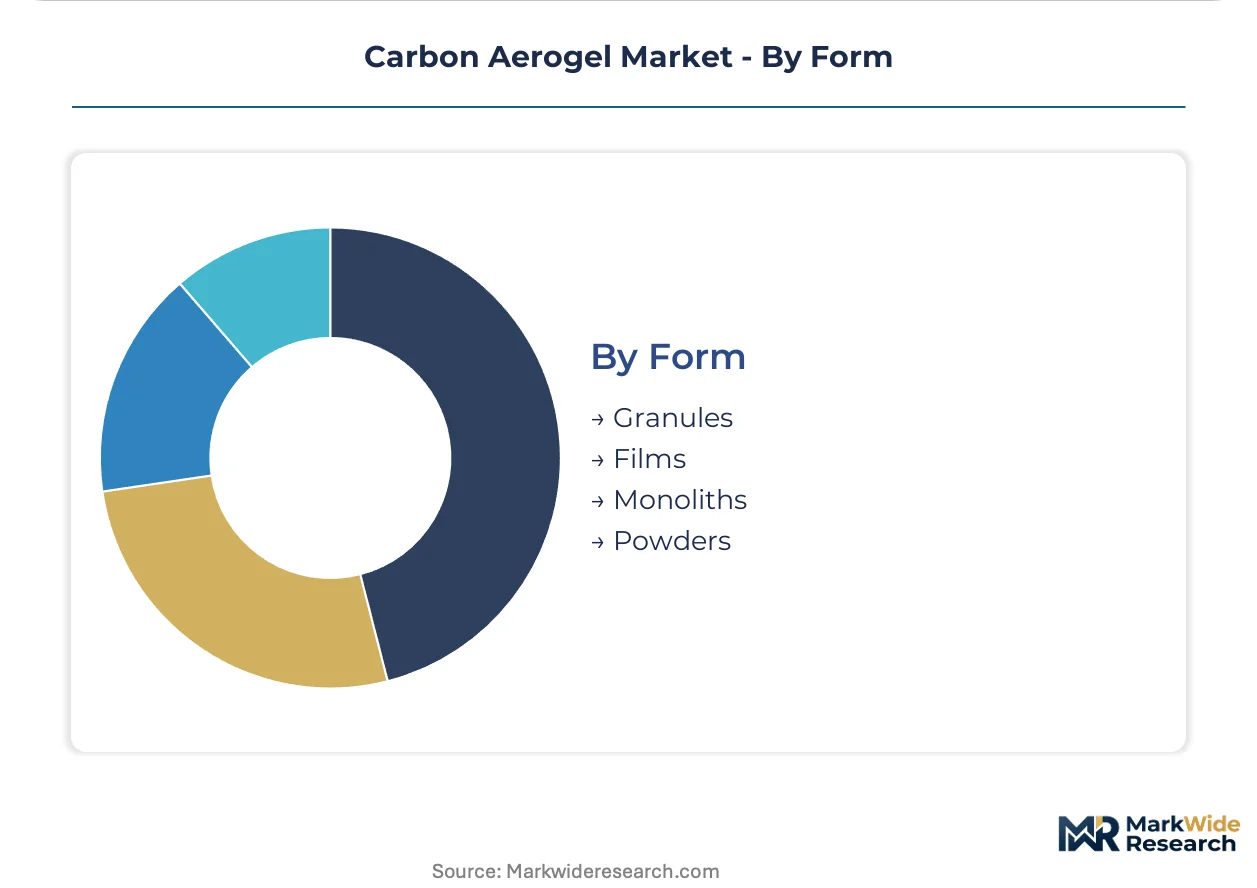
Form:
Processing state determines downstream handling equipment requirements and integration labor intensity.
- Monoliths:Continuous three-dimensional networks with tunable pore architectures serve supercapacitor electrodes where electrical contact uniformity is critical.
- Powders:Battery-grade specifications with particle size distributions below 50 microns dominate East Asian electronics supply chains.
- Granules:Flowable formats suit packed-bed adsorption columns in environmental remediation with lower capital equipment barriers.
- Films:Sub-millimeter thicknesses target thin-film battery electrodes and flexible electronics substrates with emerging process development requirements.
Powders represent the highest volume format. Monoliths are gaining share fastest as energy storage manufacturers scale electrode production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy storage procurement concentrates in Germany's industrial corridor, while insulation demand clusters under EU carbon border enforcement. East Asian electronics manufacturers drive battery-grade powder volumes through semiconductor fabrication supply chains.
Germany
Chemical conglomerates in Ludwigshafen and Leverkusen anchor pilot production programs for supercapacitor electrode materials. REACH authorization requirements for formaldehyde-based precursors extend compliance documentation burdens for imported materials. The Rhine-Neckar metropolitan region concentrates supplier qualification activity as energy storage manufacturers reshape procurement criteria.
China
Domestic battery-grade aerogel powder production scales to serve East Asian electronics supply chains. MEE enforcement of dual carbon goals accelerates substitution of coal-derived precursor pathways with biomass alternatives. Shanghai-based producers dominate semiconductor fabrication facility supply agreements under tightening particle size specifications.
United States
Carbon black infrastructure sustains precursor cost advantages across North American manufacturing networks. EPA particulate emissions thresholds during pyrolysis stages require continuous emissions monitoring system investments. Texas and Louisiana chemical corridors host capacity expansion for oil and gas pipeline insulation formats.
South Korea
Electric vehicle powertrain manufacturers specify ultralight aerogel architectures to maximize gravimetric capacitance. MFDS alignment with IEC technical standards governs quality assurance for electronics-grade supply into semiconductor fabrication. The Seoul Capital Area concentrates supercapacitor electrode procurement from flow-synthesized aerogel suppliers.
India
Domestic battery-grade aerogel powder production targets PLI scheme incentives for advanced chemistry cell manufacturing. BIS certification timelines extend qualification cycles for electrode material localization. Gujarat and Maharashtra industrial corridors attract pilot production investments from chemical conglomerates seeking regional supply base establishment.
Carbon Aerogel Market Competitive Landscape
North American producers anchor one tier; East Asian specialists hold battery-grade powder dominance. The vendor base splits between commodity rigid panel fabricators and engineered monolith specialists. Three archetypes emerge: carbon black infrastructure leverage, custom geometry specialists, and domestic supply chain dominators. Capacity expansion and strategic partnerships constitute the dominant competitive moves across pyrolysis and supercritical drying infrastructure.
Among United States-based material conglomerates, Cabot Corporation exemplifies carbon black infrastructure leverage. Shanghai Aerogelzone Technology Co., Ltd. occupies a position within the domestic supply chain dominance archetype for East Asian electronics markets. Aerogel Technologies LLC represents the custom geometry specialist tier serving non-standard architectural requirements.
| Leading Market Players |
|---|
| Cabot Corporation |
| Nanolit |
| Aerogel Technologies LLC |
| Shanghai Aerogelzone Technology Co., Ltd. |
| High Tech Material Solutions |
| American Elements |
| Aspen Aerogels |
| KEEY Aerogel |
| Green Earth Aerogel Technologies (GEAT) |
| Others |
Value Network & Pricing Analysis
Specialized pyrolysis technicians in Germany's Rhine-Neckar region command wage premiums that compress margin spreads between premium monoliths and economy-grade rigid panels. Labor-cost differentials between European chemical clusters and East Asian manufacturing hubs directly shape three-tier pricing stratification across battery-grade powders and commodity insulation formats.
Pricing Analysis
Volume concentrates in rigid panels while margins pool in custom monoliths. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified electronics-grade supply from oil and gas pipeline specifications. Cost compression in rigid formats is intensifying because standardized procurement centralization eliminates performance premiums. Oil and gas buyers exhibit highest price sensitivity; semiconductor fabricators show least.
Supply Chain Analysis
Regional distribution centers in Shanghai, Ludwigshafen, and Seoul Capital Area anchor hub-and-spoke patterns for time-sensitive electrode material delivery. Manufacturing concentrates in China, Germany, and South Korea. Production draws from resorcinol-formaldehyde precursors, supercritical CO2 systems, and pyrolysis furnace capacity. Single-source vulnerability sits with limited North American supercritical drying equipment. Distribution runs through chemical conglomerate direct sales for monoliths and distributor networks for commodity panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon aerogel sector is becoming a vertical-integration race as energy storage manufacturers pursue captive pyrolysis capacity to secure electrode material supply.
For Market Incumbents: Acquire supercritical drying equipment fleets to lock in capacity availability before infrastructure bottlenecks harden. Defend against bio-based precursor substitutes by securing long-term resorcinol offtake agreements. Add pyrolysis capacity in Germany's industrial corridor to meet EU carbon border documentation requirements. For New Entrants and Emerging Players: The premium-to-economy price gap in flexible aerogel retrofits offers entry space for regional insulation specialists. Target India's PLI scheme incentives for battery-grade powder localization. Pursue defense and aerospace custom monolith contracts where non-standard geometries escape commodity pricing. For Investors and Strategic Acquirers: Re-rating potential sits with custom geometry specialists given supercapacitor electrode procurement concentration in South Korea and Germany. Five-to-ten year viability favors producers with in-house environmental product declaration capabilities. Watch EPA particulate emissions enforcement as inflection indicator for North American capacity economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Cabot Corporation's carbon black infrastructure demonstrates cost advantages in resorcinol-formaldehyde supply security. |
| Capacity Expansion in Supercritical Drying | High-pressure CO2 system additions in Germany address electrode material bottlenecks for Ludwigshafen chemical conglomerates. |
| Green Manufacturing Transition | Lignin-derived carbon aerogels from pulp waste qualify for EU Green Deal scope-three disclosure preferences. |
| Long-term Supply Agreement | Semiconductor fabrication facilities lock in multi-year powder contracts under tightening IEC technical standards. |
| Joint Venture for Regional Supply Base | Gujarat and Maharashtra corridors attract pilot production investments targeting India's advanced chemistry cell localization. |
Research Methodology
Trade databases, customs records, and chemical industry association filings formed the secondary backbone for production capacity and trade flow quantification. Primary interviews with supercapacitor electrode procurement managers, pyrolysis plant engineers, and REACH compliance officers combined with secondary validation. Bottom-up and top-down triangulation cross-checked facility-level capacity against end-use demand aggregation.
Bottom-up modeling tracked individual production facilities across format types while top-down analysis anchored demand to energy storage and insulation sector growth. Segmentation dimensions included product density tier, application certification level, and regional regulatory cluster. CAGRs derived from facility expansion announcements and procurement contract visibility. Forecast inputs incorporated EPA emissions compliance costs and EU carbon border adjustment implementation timelines.
Inputs from ECHA substance evaluation workflows and MEE dual carbon goal enforcement data were available through the study window; gaps in real-time pyrolysis emissions monitoring system deployment rates introduce uncertainty bands around North American capacity forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Carbon Composites Market
Composite Materials
Biocomposites Market
Composite Materials
Core Material for Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Thermoset Composites Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Global Carbon Fiber Resin Market