
 Aerospace Foam Market | 2026-2036
Aerospace Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Foam Market Analysis
A shift from single-source to multi-source foam supply is rebalancing procurement leverage across tier-1 aerostructures. Evonik Industries AG leverages its high-performance polymer chemistry portfolio to sustain differentiation in cabin interior foams. BASF SE anchors large-volume polyurethane supply through integrated petrochemical feedstock control. Zotefoams plc competes via specialized nitrogen-expanded cell structures that command premium positioning in insulation and seating applications.
Aerospace foam encompasses engineered cellular polymer materials—typically polyurethane, polyethylene, or phenolic systems—manufactured through controlled foaming processes to achieve densities ranging from under 2 lb/ft³ to over 20 lb/ft³, serving primarily as lightweight structural fillers, thermal barriers, and acoustic dampeners in aircraft assemblies. Polyurethane formulations dominate current volume due to established processing infrastructure and versatile property tuning, while phenolic foams are gaining structural share in insulation applications where fire resistance requirements have intensified. Commercial aviation end users command the largest value pool, though UAVs represent the fastest-expanding demand segment as uncrewed platform production scales.
FAA flammability regulations under 14 CFR Part 25.853 govern cabin material certification in the United States, while EASA enforces comparable CS-25 standards across Europe, and REACH restrictions from ECHA limit certain halogenated flame retardants in foams sold into EU aerospace supply chains. These overlapping compliance frameworks elevate R&D spending on inherently fire-resistant chemistries and restrict market access for non-compliant formulations. Stakeholders must monitor evolving MEE environmental standards in China and potential convergence of transatlantic flammability test protocols to anticipate reformulation costs and qualification timelines.
Market Dynamics
Multi-sourcing mandates from tier-1 aerostructure suppliers are redistributing procurement leverage away from incumbent foam producers, forcing qualification of secondary chemistries and regional supply bases.
Growth Catalysts
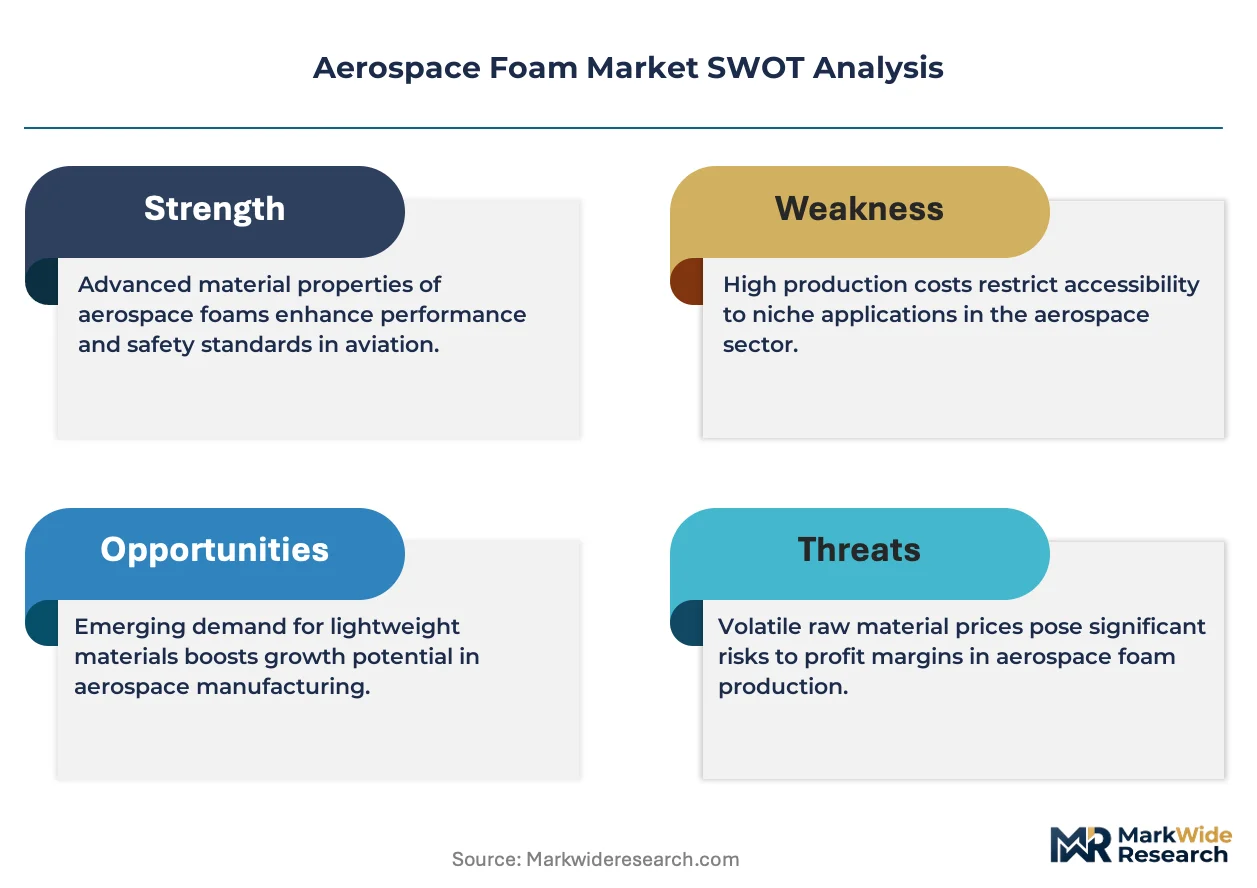
- FAA 14 CFR Part 25.853:Stricter flammability testing protocols for cabin interiors are accelerating replacement cycles for legacy foam insulation across US-registered fleets.
- UAV production scaling:Uncrewed platform manufacturers are consuming specialized low-density polyethylene foams for payload protection and structural core applications.
- REACH chemical restrictions:ECHA limitations on halogenated flame retardants are pulling demand toward inherently fire-resistant phenolic formulations in European aerospace supply chains.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with crude oil and natural gas pricing, compressing margin predictability for foam converters.
- Supplier concentration in Germany and China:Tier-1 aerostructure procurement depends heavily on nitrogen-expanded cell foam production clustered around Hamburg and Shanghai.
- Technical limitation in cryogenic performance:Standard polyurethane formulations degrade below -40°C, restricting application in next-generation hydrogen fuel cell insulation.
Strategic Opportunities
- India defense aerospace:Indigenous fighter and helicopter programs under the Ministry of Defence are creating qualified supplier slots for thermal-acoustic foam systems.
- Sustainable aviation fuel infrastructure:Airport hydrogen storage and distribution systems require cryogenic-compatible insulation foams with vacuum-panel hybrid designs.
- Urban air mobility certification:EASA SC-VTOL special conditions for electric vertical takeoff aircraft are mandating new fire-blocking foam barriers in battery compartments.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise for nitrogen-expanded and phenolic systems concentrates among retiring technical workforces in Germany and the United States.
- Qualification timeline compression:OEMs are demanding 12-18 month material certification cycles that conflict with 24-36 month standard FAA fire-testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Foam Market |
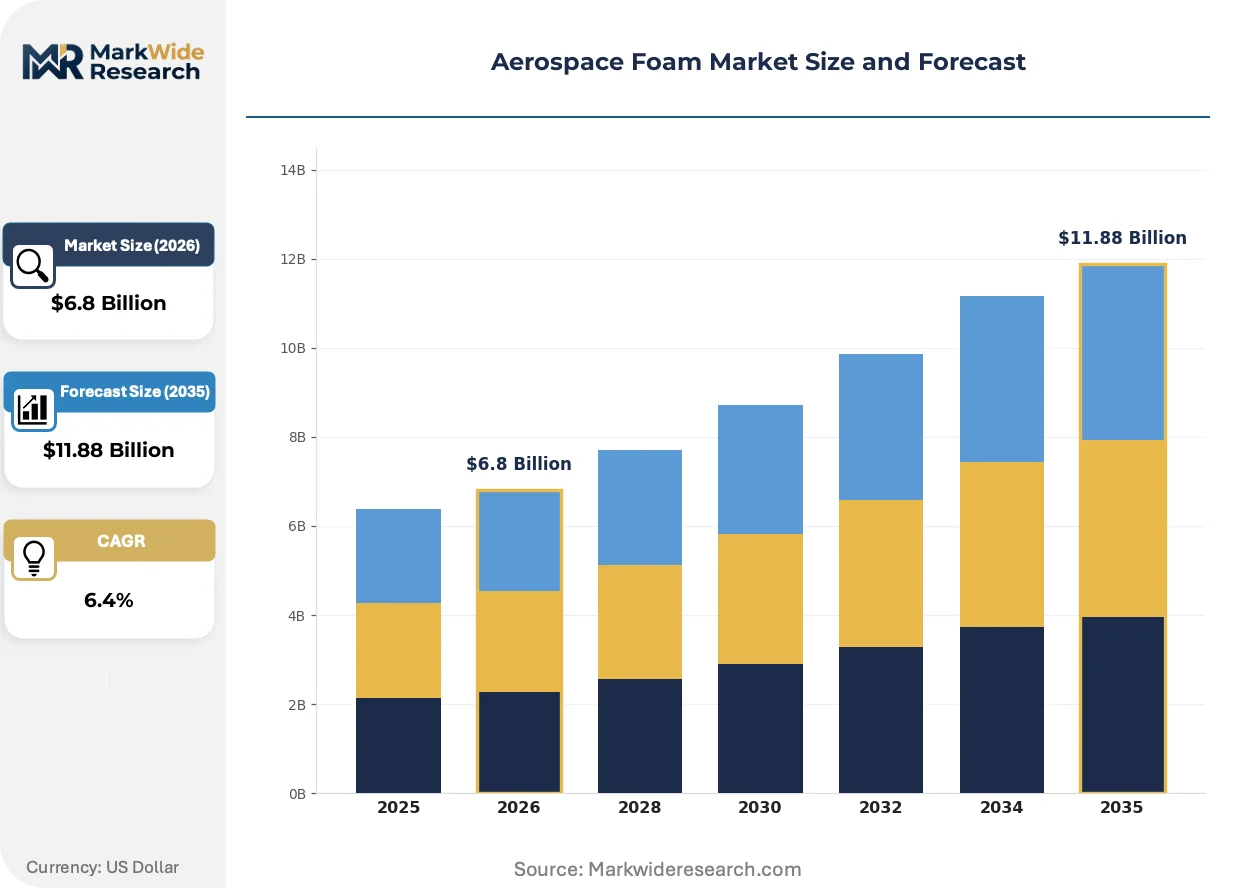
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyethylene, PVC, Phenolic Application: Insulation, Seating, Soundproofing, Packaging End User: Commercial Aviation, Military Aviation, Space Exploration, UAVs Density: Low Density, Medium Density, High Density, Ultra-High Density |
| Companies Covered | Boyd Corporation, Evonik Industries AG, BASF SE, SABIC, Solvay, Zotefoams plc, General Plastics Manufacturing Company, ERG Aerospace Corporation, UFP Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Foam Market Emerging Trajectories
Bio-based feedstocks and closed-loop manufacturing processes are disrupting established petroleum-derived foam chemistries, while digital qualification tools compress testing timelines.
Microcellular nitrogen-expanded polyethylene foam is absorbing structural core applications previously served by honeycomb aluminum in UAV wings and satellite bus structures. Small satellite manufacturers are specifying these foams for vibration damping during launch. This absorption is compressing the addressable market for traditional metallic core suppliers while opening premium positioning for controlled-density polymer specialists.
REACH restrictions on persistent organic pollutants are forcing reformulation of legacy brominated flame retardants across EU aerospace supply chains. Foam producers must qualify phosphorus-nitrogen synergist systems or mineral hydrate alternatives. Cabin interior segments serving European-registered aircraft face the steepest compliance costs, with some suppliers accelerating dual-certification under FAA and EASA protocols to maintain cross-Atlantic market access.
Airframe OEMs are unbundling foam procurement from seat and insulation system integrators, establishing direct material specifications and approved supplier lists. This disintermediation strips margin from tier-2 converters and transfers qualification burden to raw foam producers. The shift is most pronounced in United States-based final assembly lines, where Boeing and Airbus US operations now specify foam grades independently of seat manufacturer preferences.
Aerospace Foam Market Segmentation
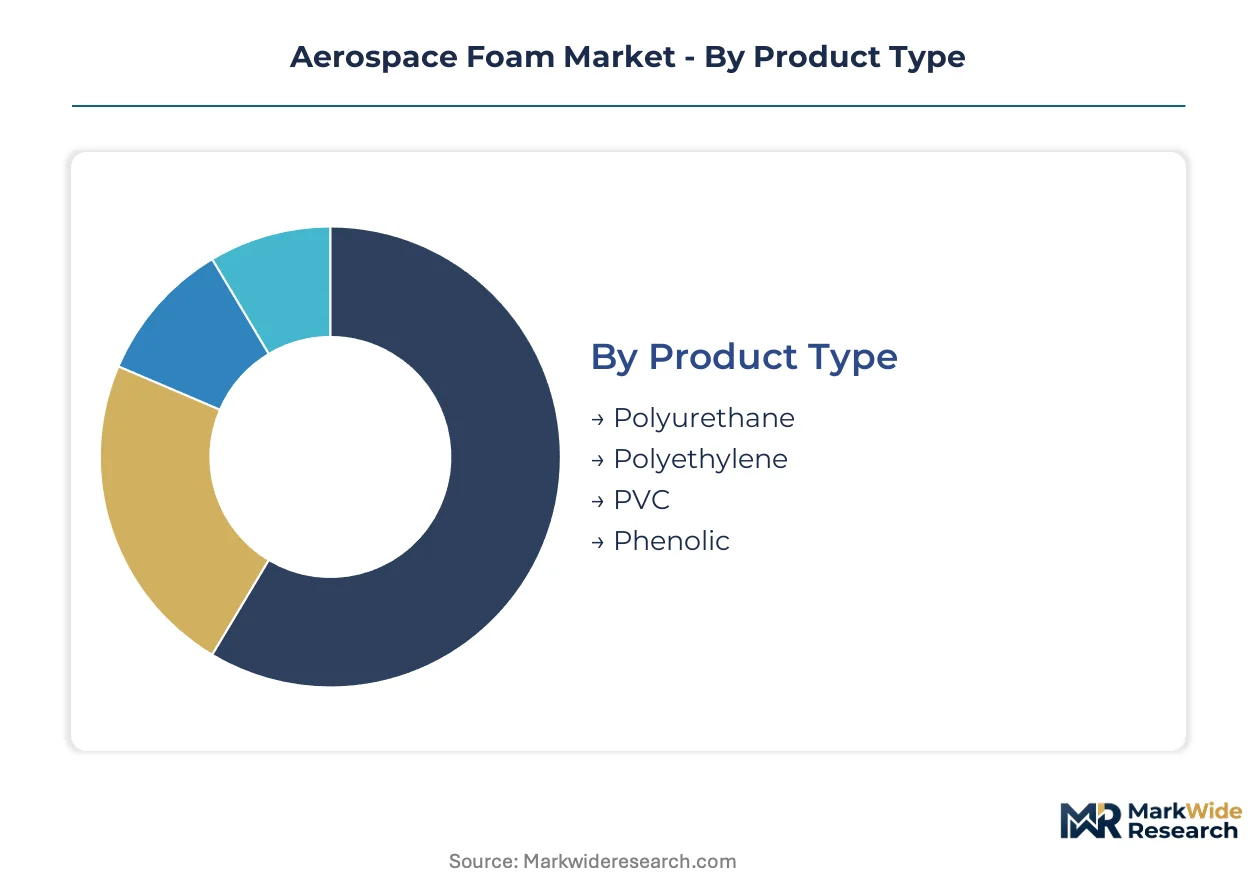
Aerospace foam procurement splits across material chemistry, integration depth, and performance tier. Each segmentation axis carries distinct qualification burdens and margin structures that reshape supplier positioning.
Product Type:
Polyurethane formulations dominate as standalone thermal and acoustic layers, while phenolic systems embed deeper into fire-rated structural assemblies.
- Polyurethane:Open and closed-cell formulations span densities from 2 to 20 lb/ft³ through controlled isocyanate-polyol reactions. Boeing 737 and Airbus A320 family insulation retrofits in the United States and Germany consume the largest volumes as FAA 14 CFR Part 25.853 compliance deadlines accelerate replacement cycles.
- Polyethylene:Nitrogen-expanded microcellular structures achieve sub-2 lb/ft³ densities for payload protection. UAV manufacturers in China specify these foams for structural cores in uncrewed platform wings, displacing aluminum honeycomb in satellite bus applications.
- PVC:Closed-cell formulations serve gasket and seal applications with moderate chemical resistance.
- Phenolic:Inherently fire-resistant closed-cell systems meet REACH-restricted flammability standards without halogenated additives.
Polyurethane leads volumes today; polyethylene is gaining share fastest.
Application:
Cost tier separation runs deepest here — insulation commands qualification premiums while packaging sits at commodity margins.
- Insulation:Thermal barrier foams in fuselage crown and sidewall assemblies must survive 2000°F burner tests under FAA protocols. Hamburg and Shanghai final assembly lines specify nitrogen-expanded grades for next-generation narrowbody programs.
- Seating:Fire-blocking layers in seat cushions and backrests face 12-18 month OEM certification timelines that conflict with standard 24-36 month FAA fire-testing protocols.
- Soundproofing:Acoustic absorption foams reduce cabin noise in engine-adjacent zones.
- Packaging:Protective foam inserts for avionics and component transport carry minimal regulatory burden.
Insulation absorbs the largest value pool; soundproofing faces margin compression from specification unbundling.
End User:
Customer type determines technical specification intensity — commercial aviation imposes the steepest certification barriers.
- Commercial Aviation:Cabin interior retrofits and new production programs at Boeing Charleston and Airbus Mobile drive demand for dual-certified FAA-EASA foam grades. Seat and insulation system integrators are losing procurement control as OEMs establish direct approved supplier lists.
- UAVs:Uncrewed platform manufacturers prioritize low-density polyethylene cores for weight reduction in extended-range missions. Chinese and Israeli UAV producers scale fastest, though export control restrictions limit supplier access.
- Military Aviation:Fighter and helicopter programs under India's Ministry of Defence create qualified supplier slots for thermal-acoustic systems with sovereign content requirements.
- Space Exploration:Small satellite manufacturers specify vibration-damping foams for launch payload protection.
Commercial aviation anchors revenue today; UAVs show the steepest expansion trajectory.
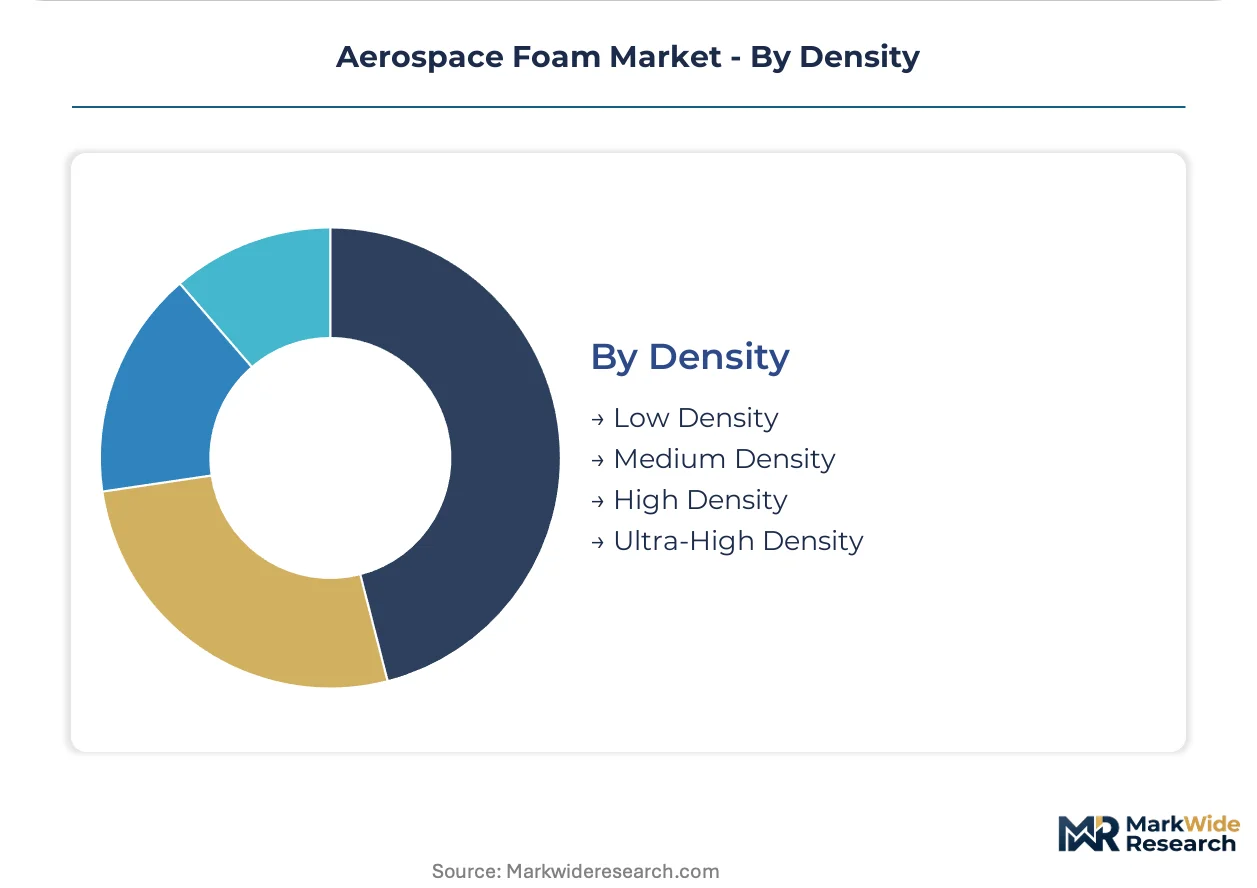
Density:
Performance tier stratification aligns with structural load-bearing requirements and thermal performance tradeoffs.
- Low Density:Sub-4 lb/ft³ polyethylene grades serve UAV structural cores and satellite vibration damping where mass reduction outweighs compressive strength needs.
- Medium Density:4-10 lb/ft³ polyurethane dominates cabin insulation and seating applications with balanced thermal-acoustic performance.
- High Density:10-20 lb/ft³ formulations provide structural filler in landing gear doors and access panels.
- Ultra-High Density:Above 20 lb/ft³ specialized grades address cryogenic hydrogen storage insulation for sustainable aviation fuel infrastructure, though standard polyurethanes degrade below -40°C.
Medium density commands the largest installed base; ultra-high density is climbing the fastest on hydrogen economy pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg's nitrogen-expanded foam production cluster anchors aerospace foam supply for narrowbody programs across Europe and Asia. Final assembly lines in this northern German city specify controlled-density grades for next-generation aircraft insulation. Procurement leverage is shifting as tier-1 suppliers diversify beyond this concentration.
United States
Boeing's Charleston and Mobile operations drive demand for dual-certified FAA-EASA foam grades in cabin retrofits. FAA 14 CFR Part 25.853 compliance deadlines accelerate replacement cycles for legacy insulation across US-registered fleets. The Pacific Northwest hosts specialized converters serving satellite and UAV manufacturers with low-density polyethylene cores.
Germany
Airbus Hamburg final assembly lines specify nitrogen-expanded grades for A320 family thermal barriers. ECHA REACH restrictions on halogenated flame retardants pull demand toward inherently fire-resistant phenolic formulations. Bavaria's chemical corridor supplies polyurethane precursors through integrated petrochemical infrastructure.
China
UAV manufacturers in Shanghai and surrounding Yangtze River Delta clusters consume specialized low-density polyethylene foams for structural cores. MEE environmental standards are tightening material compliance requirements for domestic aerospace supply chains. Tianjin's aerostructure assembly hub is qualifying regional foam suppliers to reduce import dependence.
India
Indigenous fighter and helicopter programs under the Ministry of Defence create qualified supplier slots for thermal-acoustic foam systems. BIS certification requirements are converging with military aerospace specifications for sovereign content compliance. Bangalore's defense aerospace cluster is integrating foam converters into tier-2 supply networks.
Japan
METI-supported small satellite programs specify vibration-damping polyethylene foams for launch payload protection. JIS standards govern material qualification for domestic aerospace applications. Nagoya's industrial corridor hosts specialty chemical producers developing cryogenic-compatible formulations for hydrogen fuel cell insulation.
Aerospace Foam Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue UAV-specific and cryogenic insulation niches. The vendor base stratifies across three tiers: integrated petrochemical conglomerates controlling precursor supply, specialized nitrogen-expansion technologists commanding premium positioning, and regional converters serving qualification-light packaging segments. Dominant competitive moves include backward integration into petrochemical feedstocks and technology licensing partnerships for nitrogen-expansion processes.
Within the premium-tier vector, Evonik Industries AG and Zotefoams plc exemplify specialized positioning through high-performance polymer chemistry and controlled cell-structure expertise respectively. BASF SE anchors the scale-driven segment through integrated polyurethane supply chains. These three entities represent divergent strategic archetypes: chemistry-led differentiation, process-technology specialization, and feedstock-integrated volume leadership.
| Leading Market Players |
|---|
| Boyd Corporation |
| Evonik Industries AG |
| BASF SE |
| SABIC |
| Solvay |
| Zotefoams plc |
| General Plastics Manufacturing Company |
| ERG Aerospace Corporation |
| UFP Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into petrochemical feedstock control anchors BASF SE's supply position and pricing power, locking in margin stability that independent converters cannot match when isocyanate-polyol costs spike with crude volatility. This captive supply structure lets integrated producers absorb input shocks while specialty nitrogen-expansion technologists like Zotefoams plc command premium positioning through process scarcity rather than feedstock scale.
Pricing Analysis
Petrochemical feedstock pass-through dominates polyurethane foam pricing, with crude-linked isocyanate and polyol costs transmitting directly to tier-1 aerostructure buyers through quarterly contract adjustments. Price differentiation rests on certification grade—dual FAA-EASA qualified foams command substantial premiums over single-certified alternatives—and volume scale, where narrowbody program commitments unlock tiered rebates. Pricing pressure stems from multi-sourcing mandates redistributing procurement leverage away from incumbents, compressing margins for non-specialized converters. UAV manufacturers show highest price sensitivity due to payload-driven density requirements, while commercial aviation OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
India's Ministry of Defence sovereign content requirements are reshaping sourcing patterns, compelling tier-1 suppliers to qualify domestic foam converters for indigenous fighter and helicopter programs. Geographic supply concentration centers on Germany's Hamburg nitrogen-expansion cluster, China's Shanghai Yangtze River Delta UAV production hub, and the United States' Pacific Northwest satellite manufacturing corridor. Raw material dependencies draw from Middle Eastern crude for polyurethane precursors, nitrogen gas supply for microcellular expansion, and phosphorus-nitrogen flame retardant chemistries replacing REACH-restricted halogenated additives. Single-source vulnerability runs through Hamburg's specialized nitrogen-expansion capacity, where retiring polymer chemist expertise concentrates. Distribution runs through direct OEM specification channels, bypassing traditional seat and insulation system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-regulated European supply chains and India's sovereign-content-driven qualification opportunities, where compliance cost differentials exceed formulation complexity barriers.
For Market Incumbents: To counter multi-sourcing mandates redistributing procurement leverage, BASF SE and Evonik Industries AG should deepen captive control over polyurethane precursor supply and accelerate dual-certification investment under FAA-EASA protocols to maintain cross-Atlantic market access. Securing nitrogen-expansion technology licensing partnerships defends premium positioning against regional challengers. For New Entrants and Emerging Players: Digital qualification platforms offering compressed 12-18 month certification timelines present the most penetrable route into UAV-specific low-density polyethylene core supply, where Chinese and Israeli uncrewed platform manufacturers scale fastest. Target satellite bus vibration-damping applications with sub-2 lb/ft³ nitrogen-expanded grades, leveraging export control gaps limiting incumbent access. For Investors and Strategic Acquirers: Roll-up economics work for regional foam converters with sovereign-content qualifications because India's Ministry of Defence programs and China's MEE compliance requirements create defensible local supplier slots. Over the medium-term horizon, acquisition targets should demonstrate cryogenic formulation capability for hydrogen fuel cell insulation. The signal to watch is EASA SC-VTOL battery compartment fire-blocking mandates accelerating qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | BASF SE's captive isocyanate-polyol supply locks in margin stability against crude volatility. |
| Dual-Certification Investment under FAA-EASA Protocols | Cross-Atlantic qualification maintains access as OEMs unbundle procurement from integrators. |
| Nitrogen-Expansion Technology Licensing | Process-technology partnerships extend Zotefoams plc's controlled cell-structure expertise. |
| Cryogenic Formulation Development | Phenolic and modified polyethylene systems address hydrogen storage below -40°C degradation limits. |
| Sovereign-Content Supplier Qualification | India's Ministry of Defence programs create defensible regional slots for thermal-acoustic systems. |
Methodological Framework
Direct dialogue with foam formulation chemists, tier-1 aerostructure procurement directors, EASA certification engineers, and UAV platform supply chain managers grounded qualitative findings in operational reality. Secondary validation drew from FAA 14 CFR Part 25.853 regulatory filings, ECHA REACH restriction updates, customs trade data for polyurethane precursor flows, and OEM approved supplier list disclosures. Bottom-up segment sizing triangulated against top-down aerospace production forecasts across the analysis window.
Segment-level projections incorporated material chemistry splits, density tier stratification, and end-user qualification intensity as core dimensions. CAGRs derived from production ramp schedules at Boeing Charleston, Airbus Hamburg, and Shanghai UAV clusters, cross-referenced with replacement cycle timing for FAA flammability compliance retrofits. Nitrogen-expansion capacity expansion announcements and phenolic formulation R&D pipelines fed industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cryogenic-compatible hydrogen storage insulation would alter the outlook if standard polyurethane degradation limits are breached through novel polymer architecture. Forecasts reflect assumptions around REACH chemical restriction enforcement timelines and FAA-EASA protocol convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Threaded Fasteners Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Materials Market