
 Aerographite Market | 2026-2036
Aerographite Market Size, Share, and Industry Trends Forecast 2026-2036
Aerographite Market Analysis
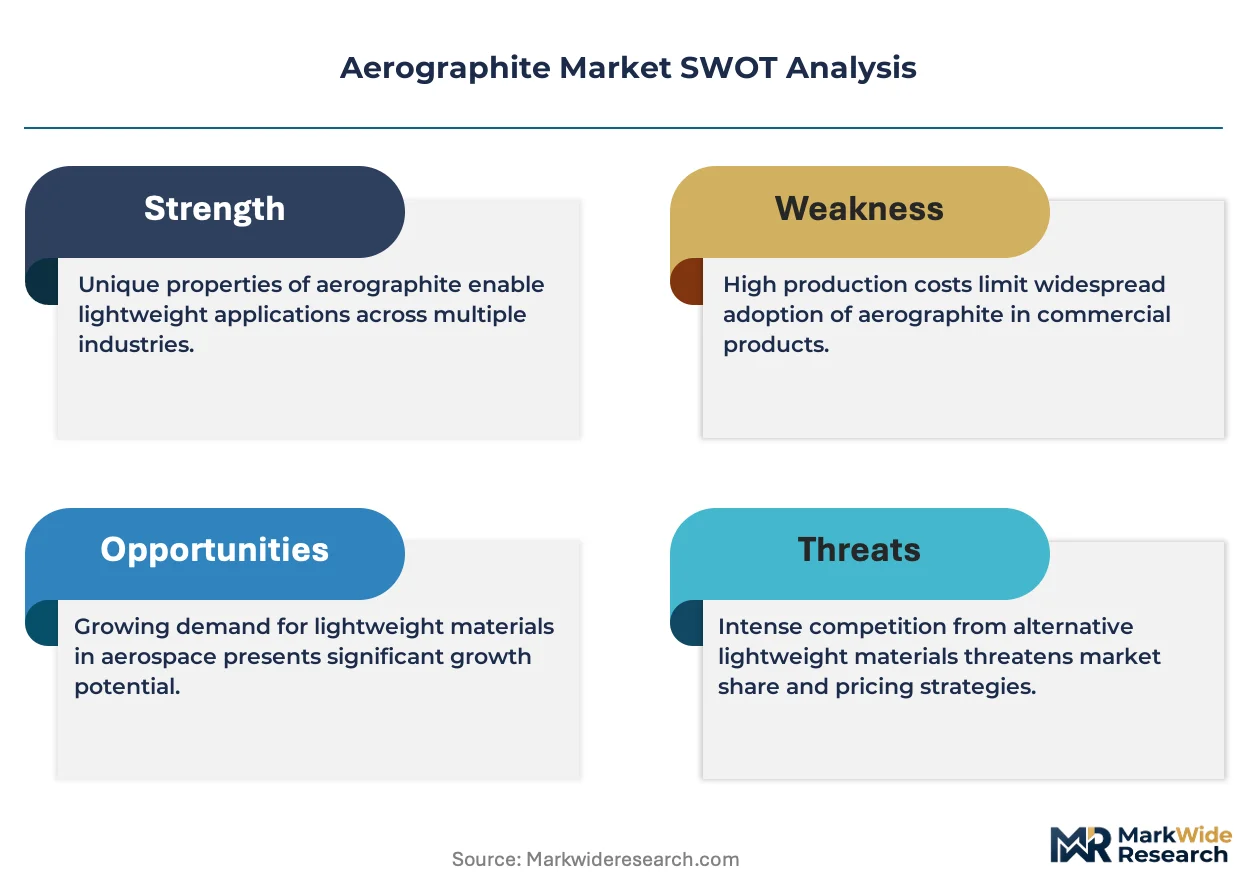
Project finance tied to clean-tech manufacturing facilities is reshaping which carbon-material specialists can scale aerographite production. SGL Carbon leverages captive precursor supply and graphitization capacity to sustain cost leadership in European aerospace qualification programs. Graphenea anchors its position through R&D intensity, operating dedicated CVD reactors for customized aerographite architectures. Miami Advanced Material Technology Co Ltd competes on manufacturing scale, controlling multi-ton powder output for domestic battery-anode trials.
Aerographite consists of a three-dimensional interconnected network of porous carbon nanotubes grown via chemical vapor deposition, achieving densities below 0.18 mg/cm³ while retaining electrical conductivity above 100 S/m. This ultralight carbon foam primarily serves applications demanding extreme weight reduction without sacrificing electromagnetic shielding or compressive resilience. Aerographite foam leads current revenue contribution, absorbing the bulk of aerospace prototyping budgets, while aerographite composite exhibits the fastest trajectory as automotive OEMs validate structural battery enclosures. Additive manufacturing commands the technology spotlight, though coating technology still occupies the widest installed base across electronics manufacturers seeking conformal EMI layers.
FDA device-clearance pathways and EPA manufacturing-emission thresholds jointly determine which aerographite variants reach biomedical and commercial markets in the United States. REACH substance-registration requirements in Europe add compliance cost layers for powder imports, filtering smaller trading intermediaries from the supply base. China's GB standards for nanomaterial workplace exposure further shape production-location decisions for multinational suppliers. Stakeholders must monitor how evolving battery-safety certifications in major economies redirect R&D investment between energy-storage and structural applications.
Market Dynamics
Aerospace OEMs and battery manufacturers are compressing qualification cycles for ultra-light carbon foams, forcing precursor suppliers to synchronize graphitization capacity with prototype timelines rather than traditional volume forecasts.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's binding emissions intensity targets for automotive and aviation sectors are redirecting R&D budgets toward materials below 0.2 mg/cm³ density.
- Structural Battery Enclosures:Automotive OEMs in Germany are validating aerographite composites for load-bearing battery housings that integrate electromagnetic shielding with crash absorption.
- Chemical Vapor Deposition Scaling:Dedicated reactor clusters for three-dimensional carbon nanotube growth are reducing unit economics below legacy carbon foam benchmarks.
Market Restraints
- Acetylene Precursor Volatility:Hydrocarbon feedstock cost swings directly compress margins for chemical vapor deposition operators without captive supply.
- Graphitization Bottleneck Concentration:High-temperature furnace capacity clusters in Germany and China, creating geographic single-point-of-failure exposure for qualified aerospace supply chains.
- Silicon-Carbide Foam Substitution:Ceramic alternatives above 400°C operating thresholds are capturing thermal management applications where electrical conductivity is secondary.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for advanced chemistry cell manufacturing are opening qualification pathways for aerographite anode architectures in domestic battery trials.
- Additive Manufacturing Convergence:Laser powder bed fusion systems are integrating aerographite feedstock for topology-optimized satellite components with embedded RF shielding.
- EU Green Deal Procurement Rules:Embodied carbon scoring in public aerospace tenders is favoring low-density materials with verified lifecycle data over conventional aluminum-lithium alloys.
Industry Challenges
- CVD Reactor Technician Scarcity:Chemical vapor deposition process engineering expertise concentrates in semiconductor supply chains, forcing cross-industry recruitment premiums.
- FAA Material Qualification Timelines:Fire-smoke-toxicity certification for cabin interior applications extends development cycles beyond typical venture capital horizons.
- REACH Powder Registration Burden:European nanomaterial substance dossier requirements filter smaller trading intermediaries from import channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerographite Market |
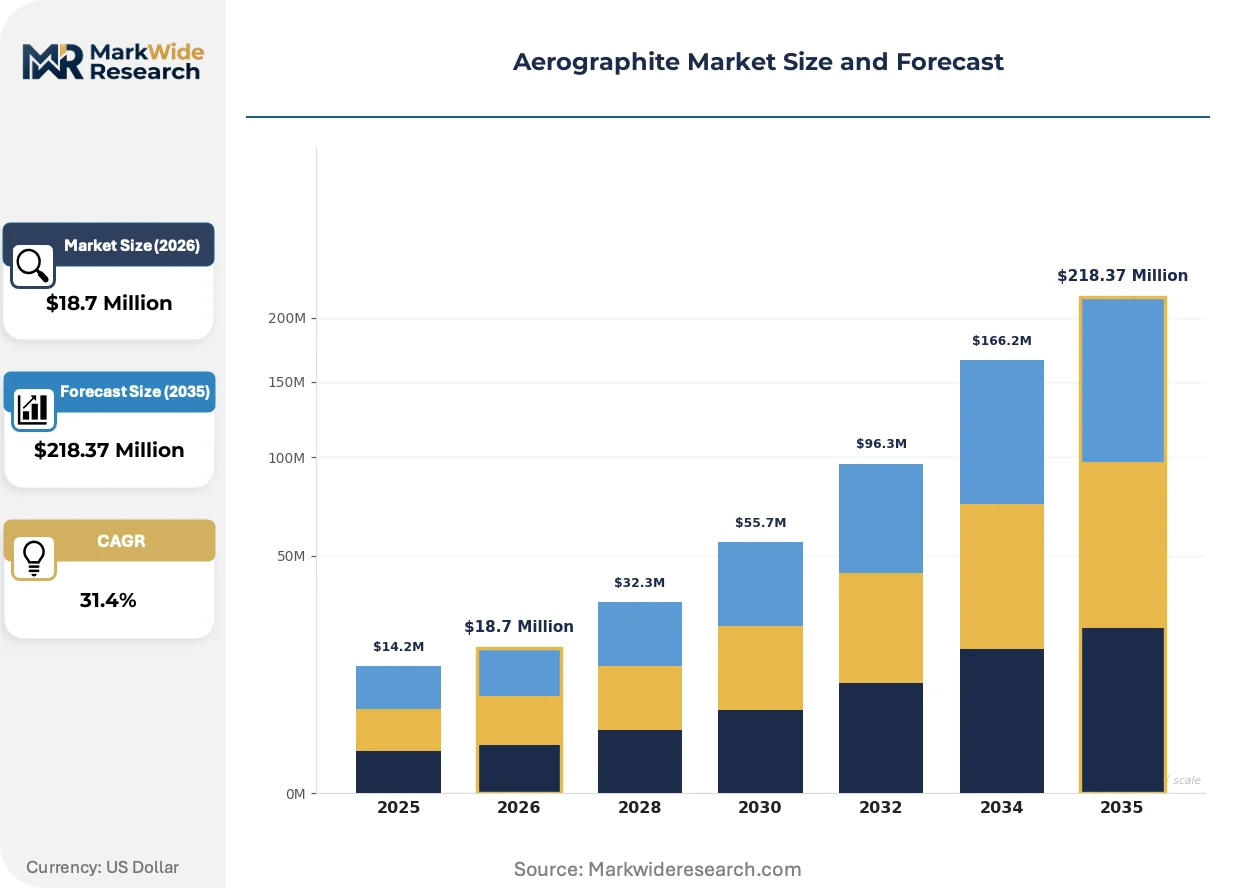
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerographite Foam, Aerographite Powder, Aerographite Coating, Aerographite Composite Application: Energy Storage, Aerospace Components, Automotive Parts, Biomedical Devices End User: Electronics Manufacturers, Aerospace Industries, Automotive OEMs, Research Institutions Technology: Additive Manufacturing, Coating Technology, Composite Fabrication, Surface Treatment |
| Companies Covered | Xinghe County Muzi Carbon Co Ltd, SGL Carbon, Aero Industries, BASF SE, Cabot Corporation, Miami Advanced Material Technology Co Ltd, Zhejiang Huarong Technology Co Ltd, Graphenea, Pingdingshan Kaiyuan Special Graphite Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerographite Market Emerging Trajectories
Process virtualization and regulatory carbon accounting are compressing the boundary between materials R&D and production-scale qualification, collapsing traditional stage-gate timelines for advanced carbon architectures.
Digital twin platforms for chemical vapor deposition reactors are virtualizing process parameter optimization before physical prototype runs. Aerospace suppliers in Germany and the United States are deploying these models to predict three-dimensional nanotube network density distributions without iterative furnace campaigns. This virtualization is compressing qualification timelines from 18-month cycles toward 6-month validation windows for structural battery enclosure programs.
REACH substance registration requirements in Europe are mandating full lifecycle toxicity dossiers for nanoscale carbon powders imported above 1-ton thresholds. ECHA compliance costs are restructuring supply chains toward in-house European graphitization capacity rather than Asian powder imports. Battery anode manufacturers are responding by relocating precursor synthesis to Rotterdam and Antwerp port zones to maintain EU market access.
Certificate-driven procurement is displacing specification-only purchasing in defense and satellite programs. Prime contractors now require material pedigree documentation traceable to specific reactor batches and graphitization furnace logs. This behavioral shift is most visible in German aerospace clusters, where Airbus tier-one suppliers are rejecting uncertified aerographite lots regardless of measured performance metrics.
Aerographite Market Segmentation
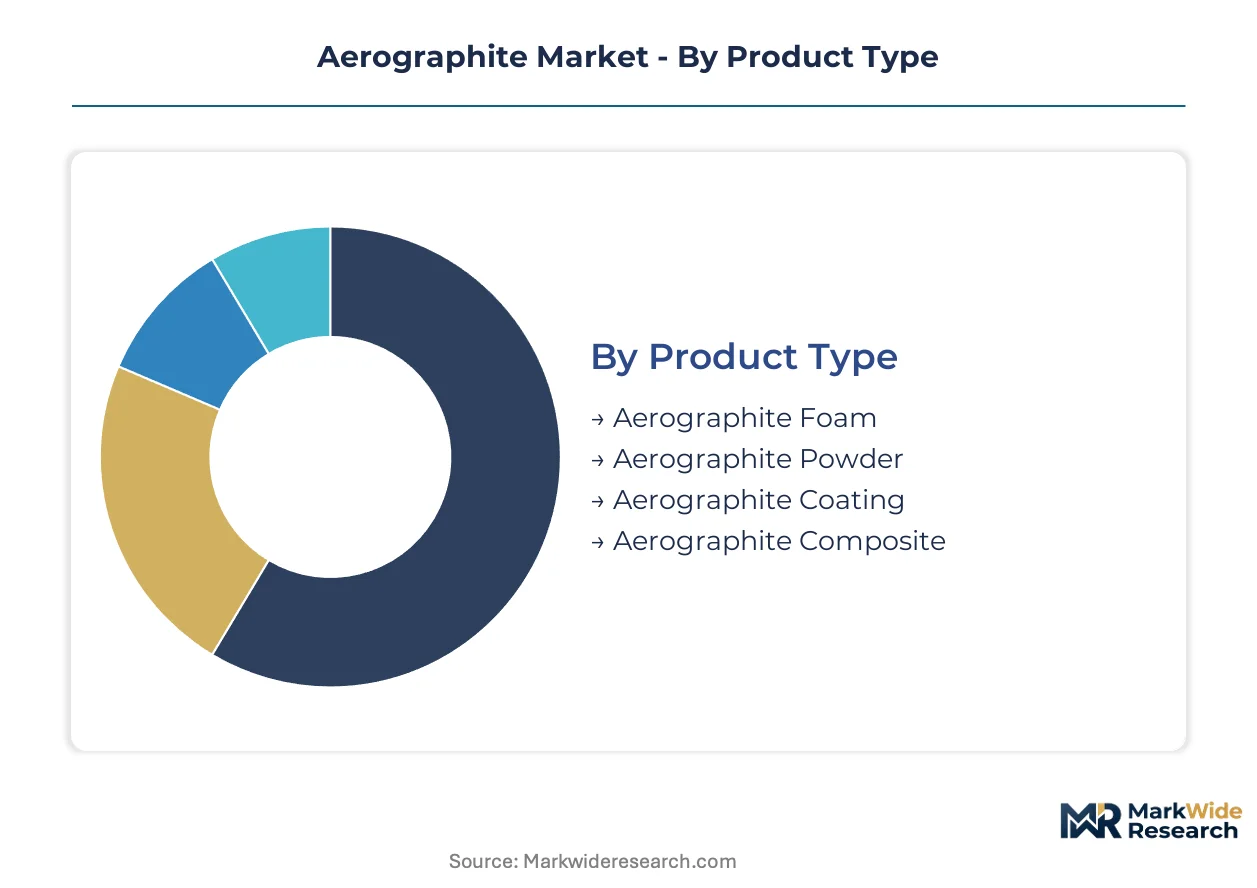
Aerographite's extreme density-to-performance ratio creates divergent value propositions across product forms and processing routes. Segmentation reveals how CVD reactor output, qualification timelines, and end-use certification requirements reshape competitive boundaries between foam, powder, and composite architectures.
Product Type:
Cost tier separates prototype-grade foams from qualified composite laminates entering vehicle and airframe programs.
- Aerographite Foam:Three-dimensional interconnected carbon nanotube networks grown via chemical vapor deposition achieve densities below 0.18 mg/cm³. Aerospace prototyping budgets in Germany and the United States absorb the bulk of foam output as Airbus and Boeing suppliers iterate structural concepts.
- Aerographite Composite:Resin-impregnated architectures combining ultralight carbon scaffolds with structural matrices. Automotive OEMs in Germany validate these for load-bearing battery enclosures integrating electromagnetic shielding with crash absorption, compressing traditional metal-housing timelines.
- Aerographite Powder:Milled particulate for battery anode blending and conductive additive applications. China's domestic advanced chemistry cell trials drive powder qualification.
- Aerographite Coating:Conformal EMI layers deposited via spray or dip processes. Electronics manufacturers in Japan and South Korea deploy coating technology for smartphone and tablet shielding.
Aerographite foam commands the established base. The steepest expansion runs through aerographite composite as automotive structural validation accelerates.
Application:
Application focus tracks where weight reduction carries premium pricing versus where electrical properties dominate specification sheets.
- Energy Storage:Silicon-anode architectures and solid-state battery prototypes leverage aerographite's conductive scaffolding to accommodate volume expansion during lithiation. China's MIIT dual carbon mandates redirect domestic cell manufacturer R&D toward ultra-light current collectors.
- Aerospace Components:Satellite bus structures and unmanned aerial vehicle airframes exploit compressive resilience at extreme weight reduction. German aerospace clusters anchor demand as Airbus tier-one suppliers reject uncertified lots regardless of measured performance.
- Automotive Parts:Structural battery enclosures and interior trim panels where electromagnetic compatibility meets crashworthiness. BMW supplier integration programs in Munich and Leipzig drive specification development.
- Biomedical Devices:Neural interfaces and implantable sensors exploiting biocompatible carbon surfaces. FDA device-clearance pathways determine which variants reach commercial markets in the United States.
Aerospace components absorb the highest unit values. Energy storage climbs fastest as battery safety certifications in major economies redirect R&D investment.
End User:
Customer type dictates qualification burden and contract structure, from spot powder purchases to multi-year aerospace development agreements.
- Electronics Manufacturers:Volume purchasers of coating and powder grades for EMI shielding and thermal interface materials. Procurement concentrates in East Asian contract manufacturers serving consumer device brands.
- Aerospace Industries:Certificate-driven buyers requiring material pedigree documentation traceable to specific reactor batches and graphitization furnace logs. German and French prime contractors enforce the strictest traceability protocols.
- Automotive OEMs:Structural validation programs for battery enclosures and lightweight body-in-white components. German OEMs lead integration timelines, with supplier qualification cycles compressing toward 18-month validation windows.
- Research Institutions:Small-volume purchasers for fundamental materials science and prototype demonstration. University and national laboratory procurement operates outside commercial qualification frameworks.
Aerospace industries maintain the most demanding specification regime. Automotive OEMs expand their addressable spend fastest as structural battery programs scale.
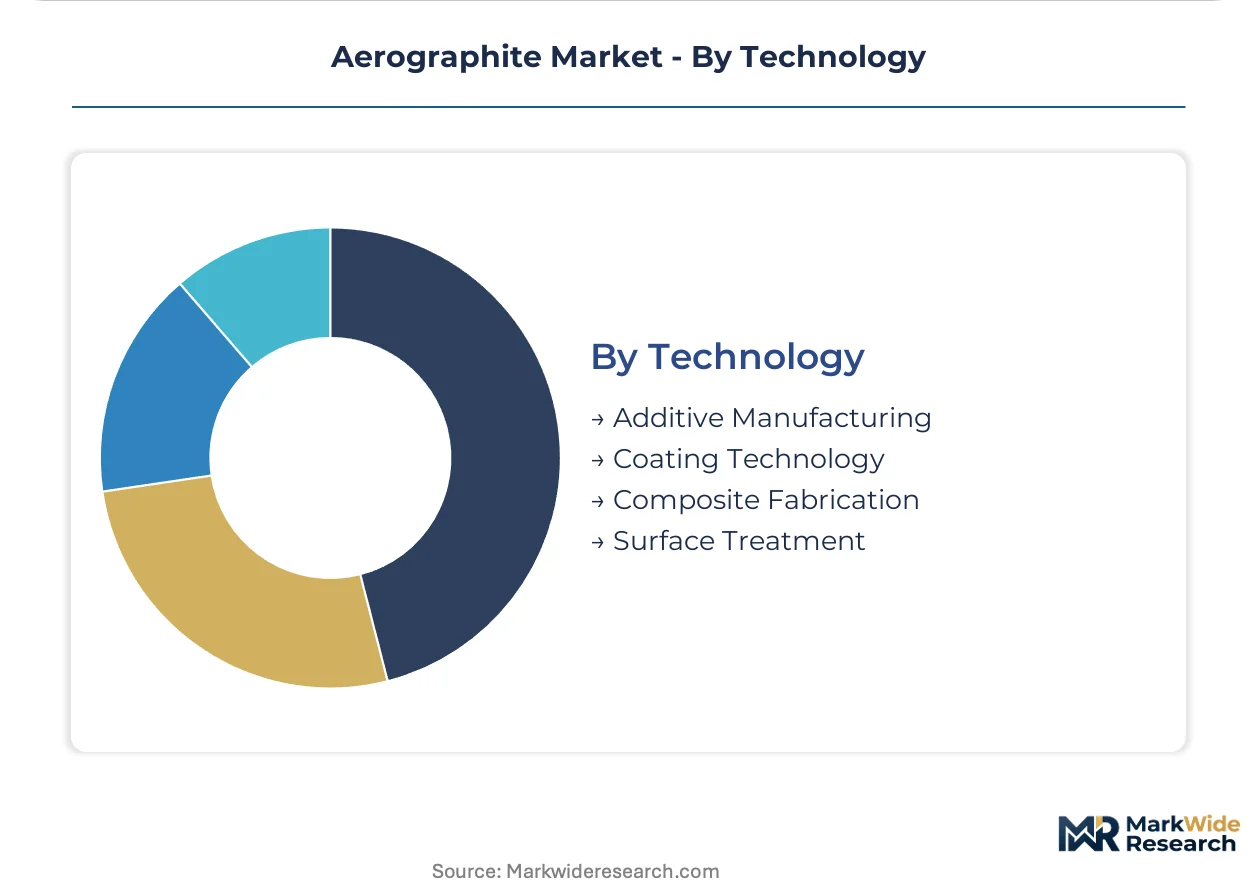
Technology:
Processing maturity separates installed coating capacity from emerging additive manufacturing integration.
- Coating Technology:Established spray and dip processes occupying the widest installed base across electronics manufacturers. Conformal EMI layer deposition dominates current commercial output.
- Additive Manufacturing:Laser powder bed fusion systems integrating aerographite feedstock for topology-optimized satellite components. German aerospace suppliers deploy digital twin platforms to virtualize process parameters before physical prototype runs.
- Composite Fabrication:Resin transfer molding and autoclave curing of aerographite-reinforced laminates. Automotive structural battery enclosure programs in Germany validate these processes for crash-rated production.
- Surface Treatment:Plasma and chemical functionalization modifying aerographite interfaces for matrix adhesion. Research-stage applications predominate, with limited commercial scale.
Coating technology holds the broadest commercial footprint. Additive manufacturing gains share fastest as satellite component qualification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German aerospace clusters where Airbus tier-one suppliers enforce certificate-driven premiums, while Chinese domestic battery trials compress margins through volume procurement of unqualified powder grades.
Germany
Airbus supplier networks in Hamburg and Munich drive structural battery enclosure validation for BMW and automotive OEMs. KBA vehicle-type approval requirements extend qualification timelines, filtering speculative suppliers from certified supply chains. The Munich-Leipzig corridor concentrates graphitization furnace capacity, creating geographic chokepoints for aerospace-qualified aerographite output.
China
MIIT dual carbon mandates redirect advanced chemistry cell manufacturer R&D toward ultra-light current collectors below 0.2 mg/cm³ density. GB standards for nanomaterial workplace exposure shape production-location decisions for multinational suppliers. Domestic trials in Yangtze River Delta battery clusters absorb multi-ton powder output from captive precursor operations.
United States
FDA device-clearance pathways and EPA manufacturing-emission thresholds jointly determine which aerographite variants reach biomedical and commercial markets. FAA fire-smoke-toxicity certification for cabin interior applications extends development cycles beyond venture capital horizons. Greater Boston and Pacific Northwest research institutions anchor prototype demand outside commercial qualification frameworks.
India
PLI scheme production-linked incentives for advanced chemistry cell manufacturing open qualification pathways for aerographite anode architectures in domestic battery trials. BIS standards for nanomaterial imports add compliance layers for powder trading intermediaries. Gujarat and Maharashtra industrial corridors attract precursor synthesis relocation to maintain market access.
Japan
METI technology roadmaps prioritize electromagnetic shielding materials for consumer electronics miniaturization. JIS standards for carbon nanotube purity filter non-specialized suppliers from coating technology procurement. Osaka-Tokyo electronics manufacturers deploy conformal EMI layers across smartphone and tablet production lines.
Aerographite Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where CVD reactor capacity and graphitization furnace access determine qualification velocity. The vendor base stratifies across three tiers: captive precursor operators sustaining cost leadership, R&D-intensive specialists customizing architectures, and scale-driven fabricators feeding domestic battery trials. Strategic moves concentrate on backward integration into acetylene supply and geographic relocation of precursor synthesis to Rotterdam-Antwerp port zones for EU market access.
Among European specialists, SGL Carbon and Graphenea exemplify divergent archetypes: the former leverages captive graphitization capacity for aerospace qualification programs, while the latter anchors position through dedicated CVD reactor operations for customized architectures. Miami Advanced Material Technology Co Ltd occupies the scale-driven tier, controlling multi-ton powder output for battery-anode trials. Xinghe County Muzi Carbon Co Ltd and Zhejiang Huarong Technology Co Ltd represent Chinese domestic fabricators competing on manufacturing volume rather than certificate-driven premiums.
| Leading Market Players |
|---|
| Xinghe County Muzi Carbon Co Ltd |
| SGL Carbon |
| Aero Industries |
| BASF SE |
| Cabot Corporation |
| Miami Advanced Material Technology Co Ltd |
| Zhejiang Huarong Technology Co Ltd |
| Graphenea |
| Pingdingshan Kaiyuan Special Graphite Co Ltd |
| Others |
Supply Flow & Price Mechanics
Acetylene precursor concentration in German and Chinese chemical clusters funnels margin capture toward CVD reactor operators with captive hydrocarbon supply, while downstream buyers face widening spreads between qualified aerospace grades and unqualified battery powder tiers.
Pricing Analysis
Configured-to-order pricing for aerospace-qualified aerographite laminates commands spreads exceeding three times standard powder grades, with certification tier and reactor batch traceability as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects qualification burden rather than raw material cost, as KBA vehicle-type approval and FAA fire-smoke-toxicity certification extend development timelines. Cost compression in unqualified powder segments is intensifying because Chinese domestic battery trials prioritize volume procurement over pedigree documentation. Electronics manufacturers in East Asia exhibit the highest price sensitivity, while Airbus tier-one suppliers in Germany accept premium positioning for certified lots with full furnace log traceability.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment as REACH substance registration requirements restructure import channels toward Rotterdam-Antwerp port zones. Geographic supply concentration clusters in Germany, China, and the United States, with Munich-Leipzig and Yangtze River Delta corridors anchoring graphitization furnace capacity. Raw material dependencies center on acetylene feedstock, high-purity metal catalysts, and specialized refractory linings for high-temperature processing. Single-source vulnerability persists for qualified aerospace supply chains given furnace qualification timelines extending beyond typical equipment replacement cycles. Distribution runs through direct long-term offtake agreements with automotive OEMs and aerospace tier-one suppliers, bypassing spot market intermediaries filtered by nanomaterial compliance burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerographite qualification services and reactor batch certification represent the fastest-expanding recurring-revenue layer, outpacing hardware margins as certificate-driven procurement displaces specification-only purchasing across defense and satellite programs.
For Market Incumbents: Entrench position through backward integration into acetylene precursor supply and captive graphitization capacity additions in the Munich-Leipzig corridor, defending against silicon-carbide foam substitution in thermal management applications above 400°C operating thresholds. Prioritize ECHA compliance investment to filter smaller trading intermediaries from European import channels and sustain certificate-driven premiums. For New Entrants and Emerging Players: India's PLI scheme production-linked incentives for advanced chemistry cell manufacturing offer the most penetrable geographic entry point, with Gujarat and Maharashtra industrial corridors attracting precursor synthesis relocation. Target domestic battery anode trials with unqualified powder grades as the fastest qualification pathway, leveraging BIS nanomaterial import compliance as a competitive moat against established European suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed carbon-material specialists holding stranded graphitization capacity outside qualified aerospace supply chains. Five-to-ten year viability hinges on successful navigation of FAA material qualification timelines and REACH substance registration cost absorption. Watch for MIIT dual carbon mandate enforcement intensity as the signal indicating redirection of Chinese cell manufacturer R&D budgets toward ultra-light current collector architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CVD Reactor Cluster Expansion | Dedicated reactor capacity in Germany reduces unit economics below legacy carbon foam benchmarks for Airbus suppliers. |
| Backward Integration into Acetylene Supply | Captive hydrocarbon feedstock insulates margin compression from volatile precursor cost swings in chemical vapor deposition operations. |
| REACH Substance Registration Compliance | ECHA dossier completion filters non-specialized intermediaries from European nanomaterial import channels above 1-ton thresholds. |
| Digital Twin Platform Deployment | Virtualized process parameter optimization compresses qualification timelines from 18-month cycles toward 6-month validation windows. |
| Rotterdam-Antwerp Precursor Relocation | Port zone synthesis maintains EU market access as Asian powder imports face escalating compliance cost layers. |
Methodological Framework
Cross-validation between primary interviews with CVD reactor operators, aerospace procurement leads, and battery cell R&D directors and secondary sources including ECHA registration databases, FAA certification filings, and MIIT policy directives anchors the qualitative findings. Technical discussions with graphitization furnace manufacturers and carbon precursor chemical suppliers supplemented demand-side perspectives. Customs trade data for carbon nanomaterial imports and SEC filings from listed advanced materials companies provided volume triangulation. Bottom-up segment sizing across foam, composite, powder, and coating product types was reconciled with top-down market value estimates derived from aerospace prototyping budget disclosures and automotive structural battery program announcements.
Calibration against historical qualification timeline data and observed CVD reactor deployment patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, end-use application, processing technology, and customer qualification tier. CAGRs were derived from elasticity-adjusted adoption curves reflecting regulatory enforcement intensity and OEM validation cycle compression. Industry-specific inputs incorporated reactor technician scarcity premiums, acetylene feedstock volatility bands, and certificate-driven procurement behavioral shifts visible in German aerospace clusters.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic fabricators or accelerated FAA certification pathway reforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market