
 China Airbag Systems Market | 2026-2036
China Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
China Airbag Systems Market Outlook
GB/T 24550 qualification cycles for occupant restraint systems is unwinding competitive access, forcing suppliers to recertify against updated crash-test protocols. Autoliv Inc. leverages its inflator foundry network to anchor supply security for domestic OEM programs. Joyson Safety Systems sustains engineering centers in Ningbo and Shanghai to compete on localization depth. ZF Friedrichshafen AG differentiates through integrated crash-sensor and airbag-module architectures.
China airbag systems encompass pyrotechnic inflators, woven nylon or polyester cushion fabrics, and electronic control units programmed to deploy at collision forces exceeding 15-20 g, all engineered to reduce occupant trauma during frontal, side, and rollover events. Curtain airbags command widening fitment in C-segment sedans and crossovers as OEMs chase NCAP-equivalent ratings without importing full Euro NCAP architectures. Smart airbag technology, integrating multi-stage deployment logic and occupant-classification sensors, captures the fastest expansion trajectory among technology tiers. The aftermarket provider channel remains structurally thin given China's collision-repair ecosystem preference for OEM-authorized parts.
MIIT vehicle-type approval rules and GB standards administered by SAMR shape mandatory airbag configuration minimums, while NMPA oversight of propellant chemicals constrains inflator supply-chain flexibility. Dual-stage and adaptive systems face stepped-up homologation testing under revised GB/T frameworks, compressing timelines for unqualified entrants. Stakeholders must monitor MIIT's phased integration of motorcycle airbag requirements into type-approval scopes.
Market Dynamics
MIIT's phased tightening of GB/T occupant protection standards is compressing supplier certification timelines while domestic OEMs accelerate airbag fitment across mid-tier vehicle platforms to capture NCAP-equivalent safety ratings.
Growth Catalysts
- GB/T 24550 Recertification:Updated crash-test protocols under SAMR administration force incumbent suppliers to reinvest in validation infrastructure, raising barriers for unqualified entrants and consolidating qualified supply.
- Curtain Airbag Penetration:C-segment sedans and crossovers in the Yangtze River Delta cluster now specify side-curtain modules as standard equipment to meet export-market safety benchmarks without full Euro NCAP architecture imports.
- Smart Airbag Logic:Multi-stage deployment systems integrating occupant-classification sensors capture the fastest expansion trajectory among technology tiers as domestic OEMs differentiate on adaptive restraint performance.
Market Restraints
- Propellant Chemical Constraints:NMPA oversight of sodium azide and guanidine nitrate formulations limits inflator supply-chain flexibility, forcing module assemblers to qualify alternative gas-generant chemistries under extended stability protocols.
- Woven Fabric Cost Volatility:Nylon 6,6 and high-tenacity polyester yarn prices fluctuate with petrochemical feedstock exposure, compressing cushion fabric margins for tier-two weavers lacking backward integration into polymer production.
- Aftermarket Channel Thinness:China's collision-repair ecosystem maintains strong preference for OEM-authorized parts, structurally constraining independent distributor penetration in replacement airbag modules.
Strategic Opportunities
- Motorcycle Airbag Mandates:MIIT's planned integration of powered-two-wheeler occupant protection into type-approval scopes creates first-mover advantage for inflator suppliers with compact module architectures.
- Sensor-Airbag Convergence:Integration of millimeter-wave occupant detection with pyrotechnic deployment logic enables tier-one suppliers to offer crash-sensor-module bundles that simplify OEM electrical architectures.
- Central China Expansion:Automotive production migration toward Wuhan and Chongqing clusters opens procurement relationships for suppliers with engineering presence beyond the Yangtze River Delta concentration.
Industry Challenges
- Homologation Timeline Compression:Revised GB/T frameworks demand simultaneous validation across frontal-offset, side-pole, and rollover test modes, straining proving-ground capacity and compressing program-to-production intervals.
- Occupant-Classification Calibration:Seat-integrated weight-sensor algorithms require extensive real-world data collection across China's diverse body-morphometry distribution, delaying smart-deployment system launches for mass-market platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Airbag Systems Market |
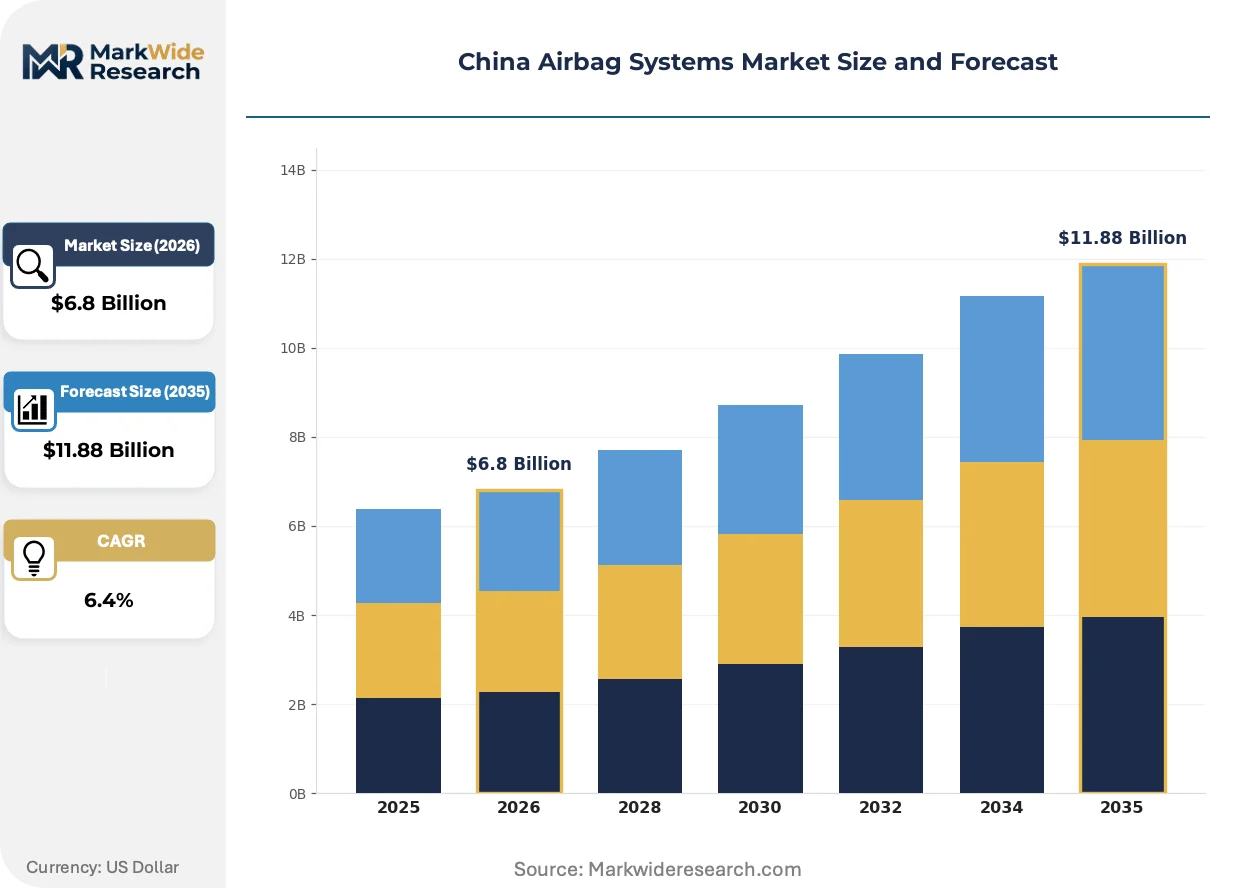
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Airbags, Side Airbags, Curtain Airbags, Knee Airbags Deployment: Passenger Vehicles, Commercial Vehicles, Motorcycles, Buses Technology: Traditional, Smart, Adaptive, Dual-Stage End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Repair Services |
| Companies Covered | Autoliv Inc., ZF Friedrichshafen AG, Joyson Safety Systems, TOYODA GOSEI Co., Ltd., Denso Corporation, Robert Bosch GmbH, Continental AG, Hyundai Mobis Co., Ltd., Daicel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Airbag Systems Market Strategic Shifts
Deployment intelligence is migrating from centralized airbag control units toward distributed sensor-fusion architectures, while regulatory pressure on propellant chemistry accelerates alternative inflator technologies.
Pyrotechnic inflator design is bifurcating between compact single-chamber units for cost-sensitive A-segment vehicles and adaptive dual-chamber systems with variable venting for premium platforms. Domestic OEMs in the Yangtze River Delta cluster adopt the latter at accelerated pace to satisfy export-market safety benchmarks. This technology stratification is compressing mid-tier supplier margins while rewarding foundry-scale producers with architecture flexibility.
MIIT vehicle-type approval rules now mandate side-impact protection for all new passenger vehicle certifications, eliminating the previous frontal-airbag-only compliance pathway. SAMR-administered GB standards enforce this through stepped-up audit testing at designated crash facilities. Tier-one suppliers with established Shanghai-area engineering centers capture disproportionate homologation support contracts from domestic OEMs racing to meet these deadlines.
Buyer concentration among state-owned automotive groups is consolidating procurement decisions into centralized safety-system sourcing committees. These committees now specify module-and-sensor bundles rather than discrete component purchases, displacing standalone inflator vendors from direct OEM relationships. The shift is most visible at SAIC, FAW, and Dongfeng programs where single-source responsibility clauses dominate recent tender documentation.
China Airbag Systems Market Segmentation
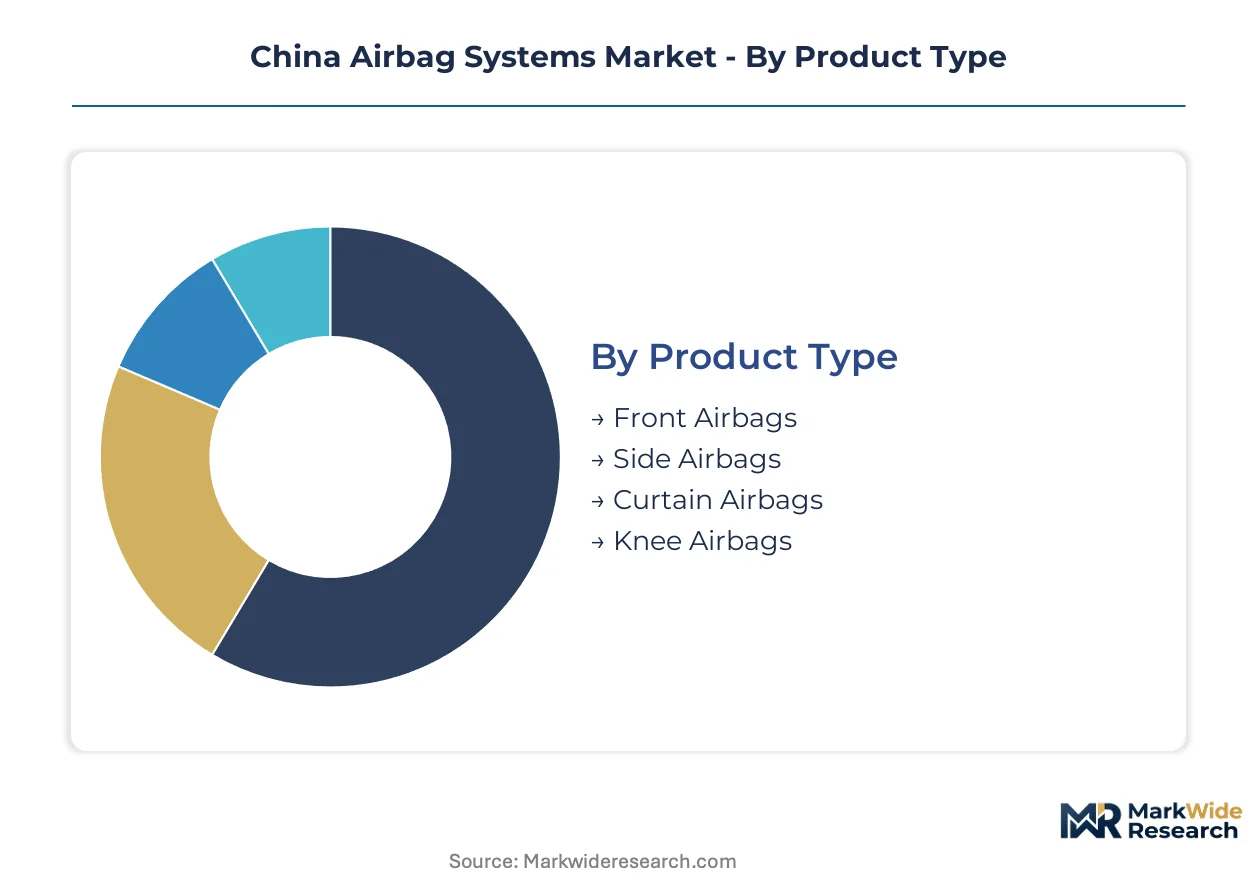
Airbag system procurement in China flows through distinct technical and commercial channels, with MIIT type-approval rules and GB standards dictating which configurations qualify for specific vehicle classes. Segment boundaries determine supplier qualification requirements, foundry capacity allocation, and homologation timeline risk.
Product Type:
Module specifications determine whether supply routes through domestic OEM direct contracts or tier-1 bundling arrangements, with curtain and smart-configuration variants commanding dedicated engineering support.
- Curtain Airbags:Woven nylon cushion fabrics deploy from roof-rail housings to cover side-window apertures during rollover and side-impact events. Yangtze River Delta OEMs now specify these as standard equipment on C-segment sedans and crossovers to satisfy export-market safety benchmarks without importing full Euro NCAP architectures. By volume, front airbags lead. By growth pace, curtain airbags are expanding most quickly.
- Front Airbags:Pyrotechnic driver and passenger modules remain the baseline fitment for GB/T 24550 compliance, with single-stage inflator units dominating A-segment cost-optimized platforms. Procurement concentrates through SAIC, FAW, and Dongfeng centralized safety-system committees that specify module-and-sensor bundles.
- Side Airbags:Seat-mounted thorax protection modules integrate with seat-frame structures for side-impact energy absorption.
- Knee Airbags:Lower-dash deployment units address femur and pelvis trauma in frontal collisions, gaining fitment in premium platforms.
Curtain configurations capture the steepest expansion trajectory as domestic OEMs chase NCAP-equivalent ratings.
Deployment:
Vehicle-class segmentation determines inflator chemistry constraints and control-unit programming complexity, with motorcycle applications facing emerging MIIT mandate timelines.
- Passenger Vehicles:Sedans, crossovers, and SUVs absorb the majority of pyrotechnic inflator foundry output, with dual-stage and adaptive systems penetrating mid-range models as domestic OEMs differentiate on adaptive restraint performance. NMPA oversight of sodium azide and guanidine nitrate formulations constrains supply-chain flexibility for this segment.
- Motorcycles:Powered-two-wheeler occupant protection is entering MIIT type-approval scopes, creating first-mover positioning for suppliers with compact module architectures. Ningbo and Shanghai engineering centers are validating reduced-form-factor inflators for this emerging fitment class.
- Commercial Vehicles:Light trucks and vans require modified deployment thresholds calibrated for unbelted occupant scenarios.
- Buses:Multi-point occupant protection systems face extended homologation testing for high-occupancy configurations.
Passenger vehicles dominate absolute volume. Motorcycle applications are gaining share fastest.
Technology:
Intelligence tier determines proving-ground validation burden and software calibration scope, with multi-stage systems requiring extensive real-world data collection.
- Smart:Multi-stage deployment logic integrates occupant-classification sensors to adjust inflation force based on seat-track position, weight distribution, and crash severity. This tier demands the most extensive calibration across China's diverse body-morphometry distribution, delaying launches for mass-market platforms.
- Dual-Stage:Variable-output inflators switch between low and high deployment energy based on crash-sensor inputs, bridging cost and performance tiers.
- Adaptive:Continuous venting adjustment during deployment optimizes restraint force throughout the collision event.
- Traditional:Single-threshold pyrotechnic units serve cost-sensitive A-segment vehicles with fixed deployment profiles.
Traditional systems anchor volume. Smart technology is climbing the fastest.
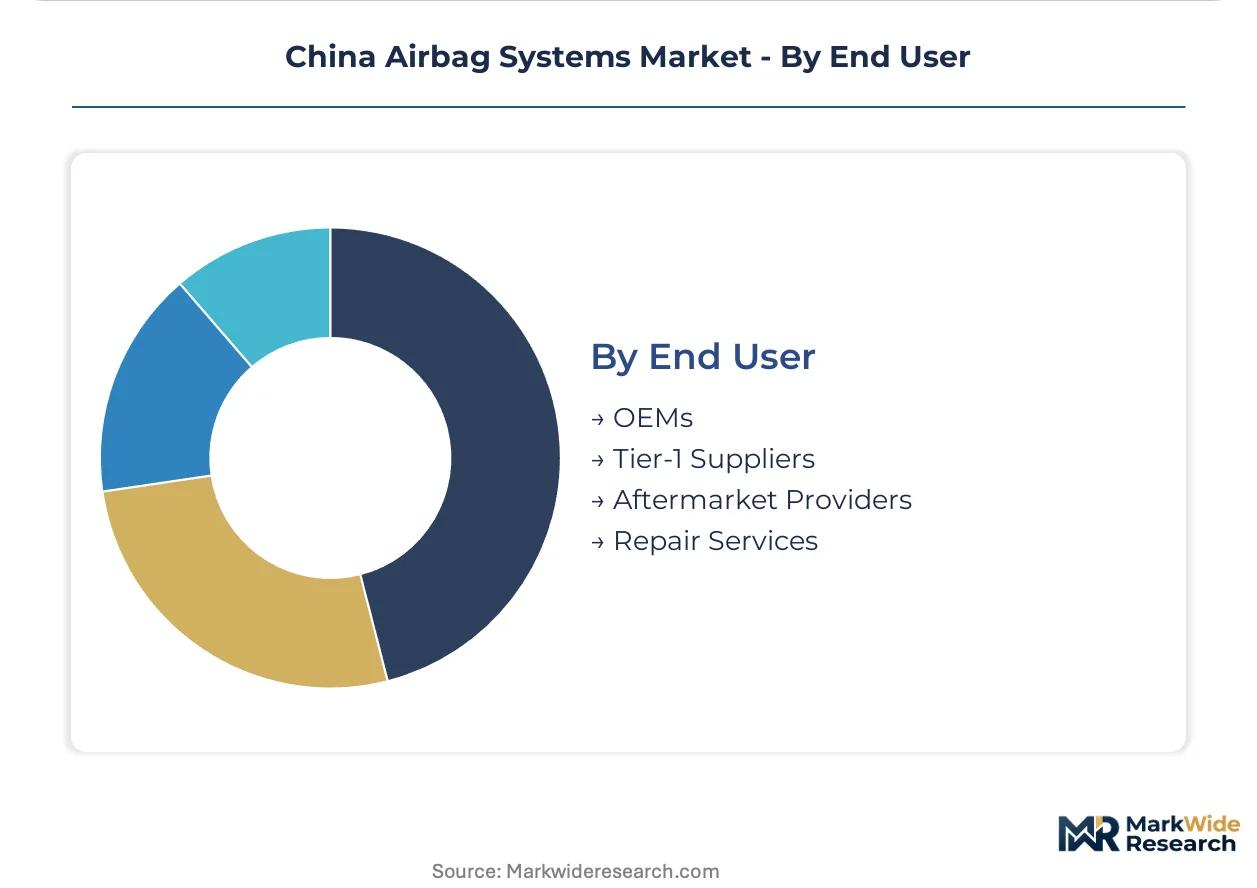
End User:
Channel structure concentrates procurement influence among state-owned automotive groups while constraining independent aftermarket penetration.
- OEMs:SAIC, FAW, and Dongfeng operate centralized safety-system sourcing committees that specify module-and-sensor bundles rather than discrete components, displacing standalone inflator vendors from direct relationships. Single-source responsibility clauses dominate recent tender documentation.
- Tier-1 Suppliers:Autoliv, Joyson Safety Systems, and ZF Friedrichshafen capture homologation support contracts through Shanghai-area engineering centers, anchoring supply security for domestic OEM programs.
- Aftermarket Providers:China's collision-repair ecosystem maintains strong preference for OEM-authorized parts, structurally constraining independent distributor penetration.
- Repair Services:Authorized service networks handle post-collision replacement under insurer-directed claims workflows.
OEMs command the largest procurement volume. Tier-1 supplier relationships are deepening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic OEM procurement committees at SAIC, FAW, and Dongfeng concentrate demand authority in state-owned automotive groups. These buyers specify module-and-sensor bundles through centralized safety-system sourcing committees. Geographic supply concentration follows automotive production migration patterns across China's industrial clusters.
Yangtze River Delta
Shanghai anchors the densest automotive engineering ecosystem, with MIIT type-approval testing facilities and SAMR crash-test protocols administered locally. GB/T 24550 recertification cycles compress supplier timelines here most severely. Tier-one suppliers maintain Ningbo and Shanghai engineering centers to capture homologation support contracts from domestic OEMs.
Pearl River Delta
Guangzhou and Shenzhen host expanding electric vehicle platforms demanding smart airbag configurations with occupant-classification sensors. Local OEMs source curtain airbag modules to satisfy export-market safety benchmarks. The cluster attracts inflator foundry investment serving both passenger vehicle and emerging motorcycle airbag programs.
Beijing-Tianjin-Hebei
State-owned automotive headquarters concentrate procurement decision-making in this northern corridor. FAW operates centralized safety-system committees that specify single-source responsibility clauses. NMPA oversight of propellant chemicals creates supply-chain constraints for module assemblers serving this market.
Sichuan-Chongqing
Western automotive production migration opens procurement relationships for suppliers establishing engineering presence beyond coastal concentrations. Chongqing-based OEMs specify dual-stage airbag systems for mid-range platforms. Local programs face extended timelines for smart-deployment calibration across diverse body-morphometry distributions.
Shandong Peninsula
Heavy commercial vehicle production centers here drive demand for modified deployment thresholds calibrated for unbelted occupant scenarios. Bus manufacturers face extended homologation testing for high-occupancy multi-point protection systems. The cluster remains secondary for passenger vehicle airbag sourcing.
China Airbag Systems Market Competitive Environment
Player mix skews toward multinational tier-one suppliers with foundry-scale inflator production and integrated sensor-module architectures. Three to five global safety-system specialists anchor qualified supply against GB/T certification requirements. Domestic specialists compete on localization depth and MIIT relationship access. Consolidation pressure intensifies as OEM procurement committees displace standalone component vendors through bundled sourcing mandates.
Among the multinational tier-one anchors, Autoliv Inc., ZF Friedrichshafen AG, and Joyson Safety Systems exemplify divergent competitive positioning within the China market. Autoliv represents the foundry-scale archetype with integrated inflator manufacturing networks. ZF occupies the sensor-airbag convergence position through crash-sensor and module architecture bundling. Joyson exemplifies the localization-depth strategy with sustained engineering center investment in Ningbo and Shanghai to compete on MIIT homologation support proximity.
| Leading Market Players |
|---|
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| TOYODA GOSEI Co., Ltd. |
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Hyundai Mobis Co., Ltd. |
| Daicel Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with petrochemical indexation lock in woven nylon cushion fabric supply for tier-one module assemblers while capping margin volatility against NMPA propellant chemical oversight. These arrangements bind Yangtze River Delta OEM procurement committees to qualified inflator foundries, embedding price visibility within GB/T 24550 recertification timelines.
Pricing Analysis
Cost-plus contracts indexed to nylon 6,6 and high-tenacity polyester yarn benchmarks dominate cushion fabric procurement, with SAMR-administered GB standards acting as certification-tier price differentiators. Smart airbag modules with occupant-classification sensors command premium positioning over single-stage pyrotechnic units, while A-segment cost-optimized platforms exhibit acute price sensitivity. Cost compression in traditional airbag tiers is intensifying because tier-two weavers lack backward integration into polymer production, forcing margin concessions to secure foundry allocation.
Supply Chain Analysis
NMPA oversight of sodium azide and guanidine nitrate formulations creates a regulatory chokepoint that constrains inflator chemistry flexibility for module assemblers serving MIIT type-approval programs. Supply concentrates in China's Yangtze River Delta foundry cluster, with secondary engineering presence in Japan and South Korea for sensor-fusion architectures. Raw material dependencies span woven nylon fabrics, pyrotechnic gas generants, and millimeter-wave occupant detection components. Single-source vulnerability runs through centralized OEM safety-system sourcing committees at SAIC, FAW, and Dongfeng. Distribution runs through tier-one supplier direct contracts rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China airbag systems are exiting a regulatory recertification trough as MIIT's phased GB/T tightening forces OEM fleet-wide upgrades, creating replacement demand cyclicality tied to homologation deadline clustering.
For Market Incumbents: Shield qualified supplier status by accelerating GB/T 24550 revalidation investments before SAMR audit capacity saturates, while securing captive woven fabric supply through backward integration into polymer production to offset NMPA propellant constraints. For New Entrants and Emerging Players: Lead with compact module architectures for MIIT's emerging motorcycle airbag mandates, where reduced-form-factor inflator validation at Ningbo and Shanghai engineering centers offers lower barrier-to-entry than passenger vehicle dual-stage system competition. For Investors and Strategic Acquirers: Sensor-airbag convergence specialists with integrated crash-sensor-module bundles represent the highest-conviction acquisition archetype, as OEM procurement committees displace standalone inflator vendors. Long-term viability hinges on proving-ground capacity access across the five-to-ten year window. The signal to watch is MIIT's publication of powered-two-wheeler occupant protection implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 24550 Recertification Investment | SAMR qualification cycles consolidate supply among validated foundry-scale producers. |
| Sensor-Airbag Module Bundling | Integrated architectures simplify OEM electrical systems and capture homologation support contracts. |
| Compact Inflator Development | Reduced-form-factor designs address MIIT's emerging motorcycle airbag mandate requirements. |
| Woven Fabric Backward Integration | Captive nylon 6,6 supply insulates margins from petrochemical feedstock volatility. |
| Central China Engineering Expansion | Wuhan and Chongqing presence captures procurement relationships from automotive production migration. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, inflator foundry operations managers, and aftermarket service network coordinators anchored the qualitative base. These primary inputs combined with MIIT vehicle-type approval filings, SAMR GB standards documentation, NMPA propellant chemical registrations, and IHS Markit vehicle production databases. Bottom-up module demand estimates triangulated against top-down OEM safety-system procurement budgets.
Sensitivity analysis around GB/T implementation phasing, propellant chemistry substitution rates, and smart airbag penetration curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include airbag product type, deployment vehicle class, technology intelligence tier, and end-user channel structure. CAGRs derived from fitted adoption curves against MIIT regulatory milestone constraints, with nylon 6,6 price elasticity and proving-ground capacity utilization as key forecast inputs.
Forecasts assume regulatory continuity in MIIT vehicle-type approval rules and SAMR GB/T enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as motorcycle airbag mandate timing and NMPA propellant oversight stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market