
 Automotive Friction Brake System Market | 2026-2036
Automotive Friction Brake System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Friction Brake System Market Outlook
Fleet operators and commercial vehicle buyers is collapsing as a share of total friction brake procurement while electric vehicle manufacturers gain ground. Continental AG leverages its integrated brake control portfolio to serve hybrid and battery-electric platforms. ZF Friedrichshafen AG anchors its position through electrically actuated brake systems that interface with regenerative architectures. Robert Bosch competes across the full stack from hydraulic foundation brakes to brake-by-wire modules.
Automotive friction brake systems are mechanical assemblies that use caliper-actuated pads pressed against rotating discs or drums to convert kinetic energy into thermal energy through friction, typically operating within temperature thresholds of 300°C to 800°C depending on material grade and duty cycle. These systems serve as the primary safety-critical stopping mechanism in road vehicles, requiring predictable fade resistance and consistent torque output across variable load conditions. Disc brake configurations dominate passenger vehicle applications where thermal capacity and wet-weather performance outweigh cost considerations, while drum brake architectures persist in rear axle and commercial vehicle segments where parking brake integration and cost efficiency matter more. Electric vehicle demand is accelerating fastest for carbon composite and low-copper organic friction materials that reduce particulate emissions while managing the blended braking profiles of regenerative-plus-friction systems.
NHTSA's Federal Motor Vehicle Safety Standards and the EU's ECE R90 homologation framework govern friction material performance, noise, and environmental criteria across their respective jurisdictions. China's GB standards and NMPA vehicle certification protocols add a third compliance layer that shapes material composition and testing protocols for suppliers serving domestic OEMs. Stakeholders must monitor how brake particulate matter regulations in Europe and California's Air Resources Board jurisdictions redefine permissible material chemistries and accelerate substitution timelines for copper and antimony compounds.
Market Dynamics
The transition to electrified powertrains is compressing friction brake duty cycles while elevating thermal performance requirements for residual mechanical braking events. This structural shift forces suppliers to engineer carbon composite formulations that withstand sporadic high-load stops without the thermal conditioning of frequent conventional braking.
Growth Catalysts
- ECE R90 Certification Mandates:Europe's homologation framework for replacement brake linings is accelerating material upgrades across aftermarket channels, forcing suppliers to validate fade resistance and noise performance under standardized test protocols.
- Commercial Fleet Expansion:Logistics operators in Germany, China, and the United States are expanding heavy-duty vehicle procurement as e-commerce fulfillment networks densify, driving demand for drum brake architectures with integrated parking mechanisms.
- Copper Substitution Chemistry:Advances in low-metallic and non-asbestos organic formulations are enabling compliance with California Air Resources Board particulate standards while maintaining friction stability across temperature ranges.
Market Restraints
- Raw Material Concentration:Synthetic aramid fiber supply concentrates in a narrow supplier base, exposing brake pad manufacturers to input cost volatility and qualification delays for alternative fiber architectures.
- Regulatory Friction:China's NMPA type-approval timelines for new friction material grades extend certification cycles, delaying platform launches for domestic OEMs serving both local and export markets.
- Regenerative Braking Displacement:Battery-electric vehicles from Tesla, BYD, and Volkswagen Group brands reduce mechanical brake engagement frequency, compressing replacement part demand and challenging aftermarket revenue models.
Strategic Opportunities
- India's Commercial Vehicle Surge:Domestic OEMs and joint ventures are localizing brake system production under the PLI scheme, creating openings for suppliers with GB-standard-compatible testing capabilities.
- Brake-by-Wire Convergence:Integration of electromechanical actuation with autonomous emergency braking algorithms is creating demand for modular brake control units that interface with vehicle dynamics computers.
- Aftermarket Digital Channels:Fleet management platforms and parts marketplaces are disintermediating traditional distributor networks, enabling direct specification of certified friction materials by vehicle identification number.
Industry Challenges
- Tribology Expertise Scarcity:Formulation chemists with deep knowledge of brake fade dynamics and transfer film behavior command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Dual-Chemistry Validation Burden:Suppliers serving both European ECE R90 and Chinese GB/T 17469 markets must maintain parallel testing facilities, duplicating capital expenditure for dynamometer capacity.
- Legacy Platform Integration:Electromechanical brake systems must maintain hydraulic fallback architectures during transition periods, doubling system complexity and warranty exposure for Tier 1 integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Friction Brake System Market |
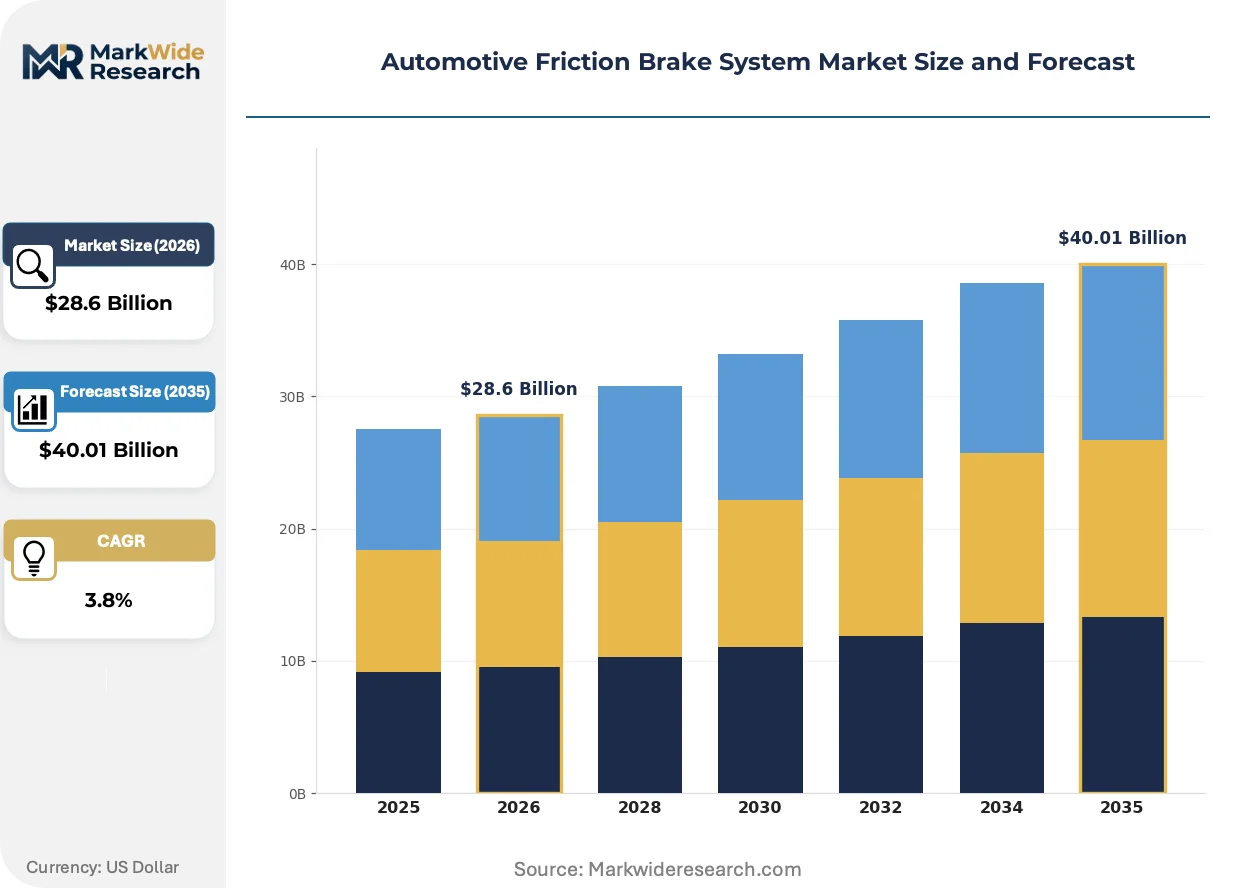
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $40.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Anti-lock Brake System, Power Brake Material: Cast Iron, Carbon Composite, Aluminum, Organic Friction Materials Vehicle Type: Passenger Vehicle, Commercial Vehicle, Heavy-Duty Truck, Electric Vehicle Technology: Hydraulic, Pneumatic, Electrically Actuated, Regenerative Braking |
| Companies Covered | Nisshinbo Holdings Inc., Continental AG, ZF Friedrichshafen AG, Tenneco Inc., Robert Bosch, Brembo, Akebono Brake Industry Co., Ltd., Knorr-Bremse AG, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Friction Brake System Market Strategic Shifts
Material science breakthroughs and regulatory particulate limits are converging to redefine friction brake architecture across vehicle electrification platforms. Suppliers are racing to engineer thermal management solutions for intermittent high-load braking events.
Electromechanical brake actuation is miniaturizing caliper motors and gearboxes to package within wheel hub envelopes previously occupied by hydraulic lines. European premium OEMs are adopting these systems for electric sports sedans where brake-by-wire enables tunable pedal feel. The technology is miniaturizing component footprints while eliminating hydraulic fluid maintenance, compressing supplier margins on traditional master cylinder and hose assemblies.
California's Air Resources Board copper reduction mandates are forcing reformulation of friction materials ahead of 2025 enforcement deadlines. The regulation limits copper content to trace levels, compelling suppliers to validate alternative fiber matrices and ceramic fillers. Aftermarket distributors in the United States are stockpiling compliant inventory while domestic OEMs accelerate qualification of low-copper platforms for 2026 model year launches.
Procurement centralization among commercial fleet operators is consolidating brake system specification authority at headquarters rather than regional maintenance depots. Large logistics buyers in Germany and the United States are mandating ECE R90-certified pads across entire vehicle pools, displacing price-driven local sourcing. This concentration is most visible in long-haul trucking segments where total cost of ownership models prioritize pad life and rotor compatibility over unit purchase price.
Automotive Friction Brake System Market Segmentation
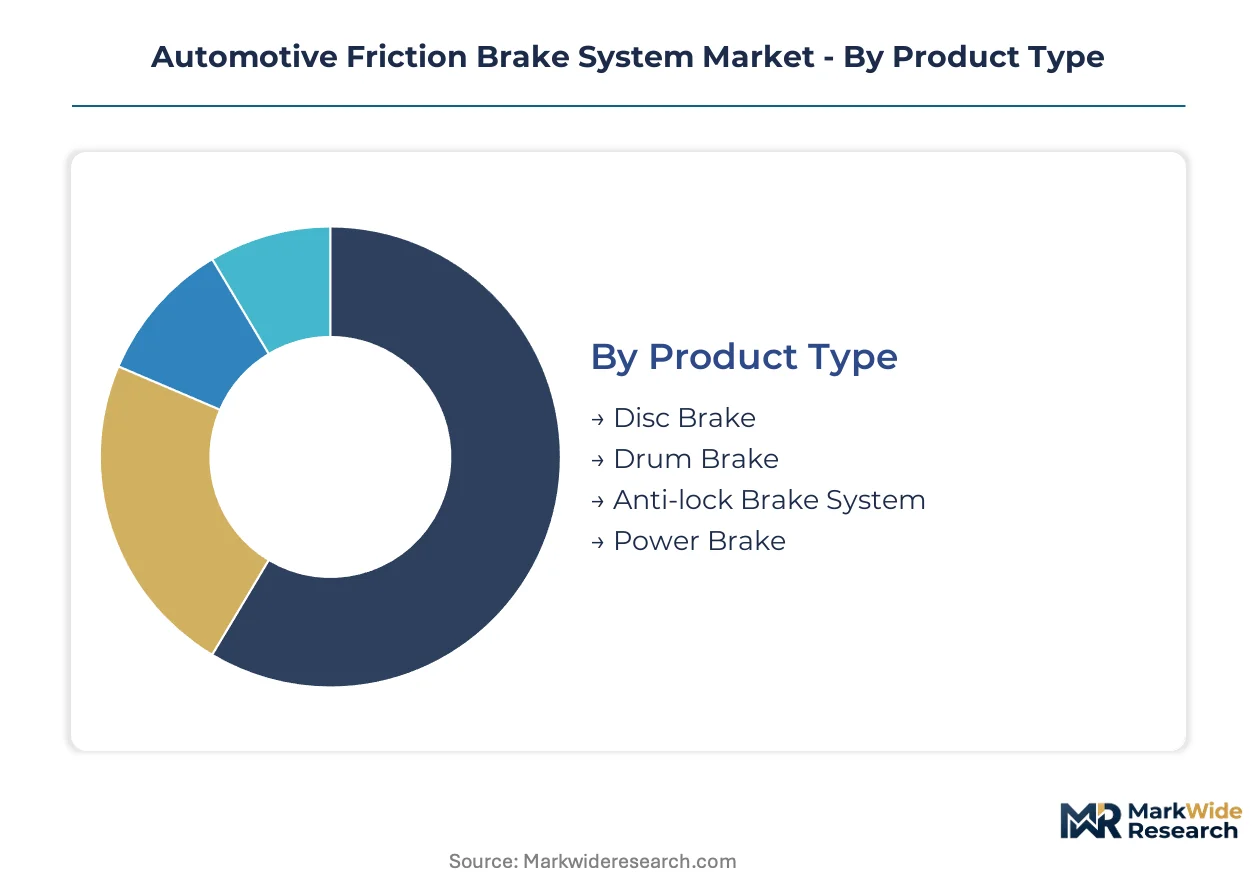
Friction brake procurement patterns diverge sharply across vehicle architectures and duty cycles. Suppliers must align formulation chemistry and actuation technology with distinct thermal load profiles and regulatory compliance tiers.
Product Type:
Margin pools concentrate in integrated brake control modules where electromechanical actuation commands premium positioning over conventional hydraulic assemblies.
- Disc Brake:Caliper-actuated pads clamp rotating rotors to deliver fade-resistant stopping power across repeated high-load events. Demand clusters in Germany's premium passenger vehicle manufacturing corridor where OEMs specify ventilated rotor geometries for thermal management.
- Drum Brake:Expanding shoes press against cylindrical drums to generate friction torque with integrated parking brake functionality. Procurement is expanding among Chinese commercial fleet operators serving e-commerce logistics networks where cost efficiency and mechanical simplicity outweigh thermal performance tradeoffs.
- Anti-lock Brake System:Wheel-speed sensors modulate hydraulic pressure to prevent lockup during emergency stops.
- Power Brake:Vacuum or electric boosters amplify driver pedal effort for reduced stopping distances.
Disc brake architectures hold installed capacity across passenger vehicle platforms. Drum brake configurations are rotating up the share rankings in commercial vehicle procurement.
Material:
Raw material qualification timelines stretch longest for fiber-reinforced composites where thermal cycling validation dominates supplier R&D allocation.
- Carbon Composite:Carbon-ceramic matrices withstand temperatures exceeding 800°C while reducing unsprung mass for performance applications. European ECE R90 certification mandates are accelerating adoption among German sports car manufacturers seeking fade resistance without weight penalties.
- Cast Iron:Pearlitic gray iron formulations deliver cost-effective thermal mass for standard duty cycles. China's NMPA type-approval protocols continue to favor this material for domestic OEM cost structures despite weight disadvantages.
- Aluminum:Lightweight alloy rotors and caliper housings reduce fuel consumption in efficiency-focused platforms.
- Organic Friction Materials:Non-asbestos organic binders with aramid fiber reinforcement comply with California Air Resources Board copper limits.
Cast iron maintains volume leadership across replacement channels. Carbon composite formulations are climbing the fastest in electric vehicle platform specifications.
Vehicle Type:
Procurement authority is fragmenting across vehicle electrification strategies where regenerative braking integration reshapes friction system duty cycles.
- Electric Vehicle:Blended braking architectures combine regenerative energy recovery with residual mechanical friction for emergency stops. BYD and Volkswagen Group platforms specify low-copper organic pads that manage sporadic thermal loading without conventional brake conditioning cycles.
- Commercial Vehicle:Air-actuated drum and disc configurations serve freight operators with high annual mileage and predictable maintenance intervals. Fleet buyers in the United States are consolidating specification authority at headquarters level under total cost of ownership models.
- Passenger Vehicle:Hydraulic disc brakes dominate light-duty stopping requirements across mass-market platforms.
- Heavy-Duty Truck:S-cam drum brakes and air disc brakes manage gross combination weights with integrated spring brake parking mechanisms.
Commercial vehicle segments retain replacement part density. Electric vehicle demand is expanding most quickly for carbon composite and low-metallic formulations.
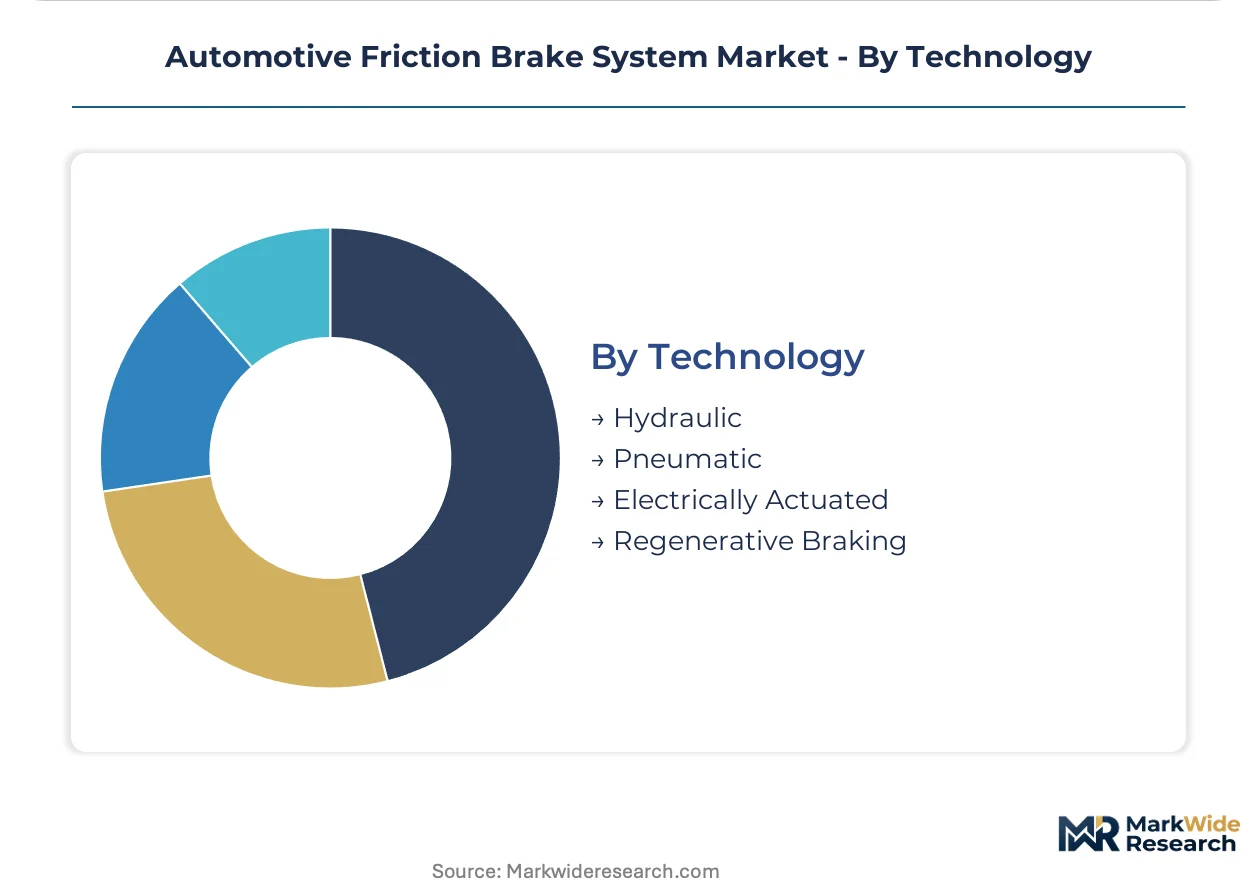
Technology:
Actuation method determines system integration complexity and software interface requirements for autonomous emergency braking algorithms.
- Electrically Actuated:Electromechanical caliper motors eliminate hydraulic fluid while enabling brake-by-wire pedal feel tuning. ZF Friedrichshafen AG supplies these systems to European premium OEMs packaging within constrained wheel hub envelopes.
- Regenerative Braking:Motor-generators convert kinetic energy to electrical storage, displacing mechanical brake engagement frequency. Tesla and BYD platforms compress friction pad wear rates while elevating thermal performance requirements for residual braking events.
- Hydraulic:Master cylinder and brake line architectures persist across legacy platforms and cost-sensitive segments.
- Pneumatic:Compressed air systems serve heavy-duty commercial vehicles with reliable actuation force across variable load conditions.
Hydraulic technology retains installed base across internal combustion platforms. Electrically actuated systems are gaining share fastest in battery-electric and hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier consolidation clusters in Germany's automotive corridor, where Tier 1 integrators anchor OEM relationships. China's manufacturing bases serve domestic volume and export qualification simultaneously. India's commercial vehicle expansion creates new procurement density.
Germany
Premium OEMs specify ventilated disc geometries and carbon-ceramic matrices for thermal management. ECE R90 homologation mandates accelerate aftermarket material upgrades. Baden-Württemberg hosts integrated brake control development for hybrid platforms.
China
Domestic OEMs expand heavy-duty fleet procurement under e-commerce logistics densification. NMPA type-approval protocols shape friction material composition for local cost structures. Yangtze River Delta manufacturing bases supply both domestic volume and export qualification pipelines.
United States
Commercial fleet operators consolidate brake specification authority under total cost of ownership models. NHTSA Federal Motor Vehicle Safety Standards govern stopping distance and fade resistance criteria. Midwest automotive corridors maintain drum brake production for long-haul trucking segments.
India
Domestic OEMs and joint ventures localize brake system production under PLI scheme incentives. BIS standards and CDSCO protocols add compliance layers for material qualification. Maharashtra and Tamil Nadu manufacturing clusters serve commercial vehicle platform expansion.
Japan
Automotive manufacturers specify low-copper organic formulations for hybrid and battery-electric platforms. METI industrial standards guide friction material testing protocols. Kanto region R&D centers engineer carbon composite architectures for sporadic high-load thermal events.
Automotive Friction Brake System Market Competitive Environment
Concentration sits with diversified Tier 1 automotive suppliers possessing integrated brake control portfolios. Three archetypes dominate: full-stack system integrators spanning hydraulic foundation to brake-by-wire modules; specialized friction material formulators with deep tribology expertise; and electromechanical actuation specialists packaging within constrained wheel hub envelopes. Competitive moves center on strategic partnerships for regenerative braking integration and backward integration into carbon-ceramic matrix production.
Among diversified German automotive suppliers, Continental AG and ZF Friedrichshafen AG exemplify full-stack integration archetypes. Robert Bosch occupies a position bridging hydraulic legacy systems with electromechanical transition architectures. Japanese specialists including Akebono Brake Industry Co., Ltd. and Nisshinbo Holdings Inc. represent friction material formulation depth. Brembo anchors premium-tier positioning for performance applications. Knorr-Bremse AG exemplifies commercial vehicle air brake specialization.
| Leading Market Players |
|---|
| Nisshinbo Holdings Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Tenneco Inc. |
| Robert Bosch |
| Brembo |
| Akebono Brake Industry Co., Ltd. |
| Knorr-Bremse AG |
| Aisin Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Tier 1 brake system integrators and German OEMs lock in both synthetic aramid fiber supply access and multi-year price visibility, insulating procurement teams from spot market volatility in critical friction material inputs while compressing margin flexibility for mid-tier formulators serving aftermarket channels.
Pricing Analysis
Volume-discount tiering structures separate ECE R90-certified premium formulations from standard cast iron replacement grades and economy organic pads. Pricing stratifies across premium, standard, and economy tiers based on certification grade and thermal performance specifications. Cost compression in economy-grade organic materials is intensifying because Chinese NMPA type-approval delays extend supplier qualification cycles. Commercial fleet buyers exhibit lowest price sensitivity due to total cost of ownership models, while independent aftermarket distributors remain most price-responsive.
Supply Chain Analysis
Inventory lead times for carbon-ceramic matrices stretch longest where Japanese and German specialty chemical suppliers control precursor fiber production. Manufacturing concentrates in Germany, China, and Japan for disc brake assemblies, with drum brake production clustering in China's Yangtze River Delta and the United States Midwest. The supply chain draws from synthetic aramid fibers, pearlitic gray iron, and ceramic fillers as critical inputs. Single-source vulnerability in aramid fiber qualification exposes formulators to disruption. Distribution runs through Tier 1 integrators to OEM assembly plants, with aftermarket channels served by authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with electromechanical actuation specialists and low-copper formulation chemists as electric vehicle platform proliferation creates specification niches outside incumbent hydraulic system portfolios.
For Market Incumbents: Shield aftermarket revenue streams by accelerating backward integration into carbon-ceramic matrix production and securing ECE R90 certification lock-in across European fleet accounts. Regenerative braking displacement threatens replacement part density, demanding channel control through direct fleet management platform partnerships. For New Entrants and Emerging Players: Differentiate on brake-by-wire software integration capabilities for autonomous emergency braking algorithms. India's commercial vehicle surge under PLI scheme incentives offers the most penetrable geography, with go-to-market traction through joint ventures with domestic OEMs seeking GB-standard-compatible testing capabilities. For Investors and Strategic Acquirers: Formulation chemists with deep tribology expertise in transfer film behavior represent priority acquisition targets given scarcity premiums constraining R&D throughput. Long-term viability frames around suppliers capable of serving dual ECE R90 and Chinese GB/T 17469 validation requirements. Watch brake particulate matter enforcement timelines in California and European jurisdictions as inflection indicators for copper substitution chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Ceramic Backward Integration | Captive supply of precursor fibers reduces aramid dependency for Continental AG and ZF Friedrichshafen AG. |
| Brake-by-Wire Platform Standardization | Modular electromechanical caliper designs enable software-defined pedal feel tuning for European premium OEMs. |
| Dual-Certification Testing Investment | Parallel ECE R90 and GB/T 17469 facilities accelerate platform launches for suppliers serving export markets. |
| Low-Copper Formulation Scale-Up | California Air Resources Board compliance ahead of enforcement deadlines secures aftermarket inventory positioning. |
| Fleet Management Platform Partnership | Direct VIN-based specification authority displaces traditional distributor networks for commercial vehicle segments. |
Study Parameters
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership service operations anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, NHTSA safety filings, and ECE R90 homologation records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the automotive manufacturing corridor.
Sensitivity analysis tested forecast outputs against variable assumptions for electric vehicle penetration rates and regenerative braking displacement effects across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, brake system technology, material grade tier, and regional production cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement timelines and fleet procurement cycle patterns. Industry-specific inputs incorporated OEM platform launch schedules and friction material qualification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained commercial vehicle fleet expansion or accelerated copper substitution mandates would require recalibration. Forecasts reflect documented assumptions regarding NMPA type-approval efficiency and ECE R90 certification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market