
 Automotive Side Guard Door Beam Market | 2026-2036
Automotive Side Guard Door Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Side Guard Door Beam Market Outlook
Japanese steel capacity for automotive structural components is decoupling from traditional integrated mill economics as specialty alloy production shifts to dedicated electric-arc operations. KIRCHHOFF Automotive GmbH leverages its European stamping footprint to supply hot-formed door beams across multiple OEM platforms. Gestamp sustains competitive intensity through in-house roll-forming and laser-welding capabilities for ultra-high-strength steel sections. Benteler International AG dominates tubular beam architectures with seamless processing lines that reduce weight-to-strength ratios.
An automotive side guard door beam is a structural reinforcement member installed within vehicle doors, typically fabricated from press-hardened steel grades exceeding 1500 MPa tensile strength or extruded aluminum alloys, designed to absorb and distribute lateral impact energy away from occupants during side collisions. Steel product types retain volume leadership in mass-market passenger cars where cost-per-kilogram and repair-network familiarity anchor procurement decisions, though aluminum segments are gaining fastest in electric vehicle applications where every kilogram of mass reduction extends battery range. Composite material categories occupy niche positions in premium SUVs where multi-material door architectures justify higher per-vehicle beam costs.
NHTSA Federal Motor Vehicle Safety Standard 214 governs side-impact protection requirements in the United States, mandating specific intrusion resistance levels that directly determine beam cross-section geometry and material grade selection. ECE R95 regulations in Europe enforce comparable side-pole and movable-barrier test protocols, while China's GB standards administered by MIIT incorporate localized crash-speed parameters that influence supplier qualification timelines. Stakeholders must monitor how evolving NCAP rating schemes in multiple geographies are elevating pedestrian-protection criteria that affect door-beam placement and outer-panel deformation characteristics.
Market Dynamics
Hot-forming press technology is compressing the cost gap between 1500 MPa press-hardened steel and 6000-series aluminum extrusions, forcing material selection decisions upstream into platform engineering rather than component sourcing.
Growth Catalysts
- NHTSA FMVSS 214:Side-impact intrusion mandates in the United States are mandating higher-strength beam cross-sections across all passenger vehicle classes, eliminating lower-grade steel options from qualified supplier lists.
- Electric vehicle platforms:Battery-electric architectures prioritize mass reduction at the component level, accelerating aluminum door beam specifications in premium and mid-range segments where range anxiety drives engineering trade-offs.
- German OEM engineering centers:Concentrated R&D investment in Wolfsburg, Munich, and Stuttgart is setting global benchmarks for multi-material door structures that cascade into supplier qualification requirements worldwide.
Market Restraints
- Scrap aluminum price volatility:LME-linked input costs for 6061 and 6082 alloys create margin compression for extruded beam manufacturers unable to pass through raw material fluctuations.
- Hot-forming die concentration:Specialized press-hardening tooling capacity clusters in Upper Austria and southern Germany, creating single-source risk for OEMs qualifying new beam programs.
- Repair network incompatibility:Ultra-high-strength steel grades above 1300 MPa require dedicated inert-gas welding equipment absent from most North American collision repair facilities.
Strategic Opportunities
- India passenger vehicle safety mandate:Upcoming side-impact requirements from the Ministry of Road Transport and Highways will force beam adoption in A- and B-segment vehicles currently lacking structural reinforcement.
- Hybrid steel-aluminum architectures:Converging roll-forming and friction-stir welding processes enable tailored blank solutions that optimize strength-to-weight ratios across door height.
- Direct OEM contracting:Platform engineering consolidation is opening direct supply relationships that bypass traditional Tier-1 door module integrators.
Industry Challenges
- Hot-forming process engineering talent:Qualified technicians for press-hardening line operation and die maintenance remain scarce in emerging manufacturing regions.
- Multi-material corrosion management:Galvanic isolation between steel and aluminum beam sections requires validated coating systems that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Side Guard Door Beam Market |
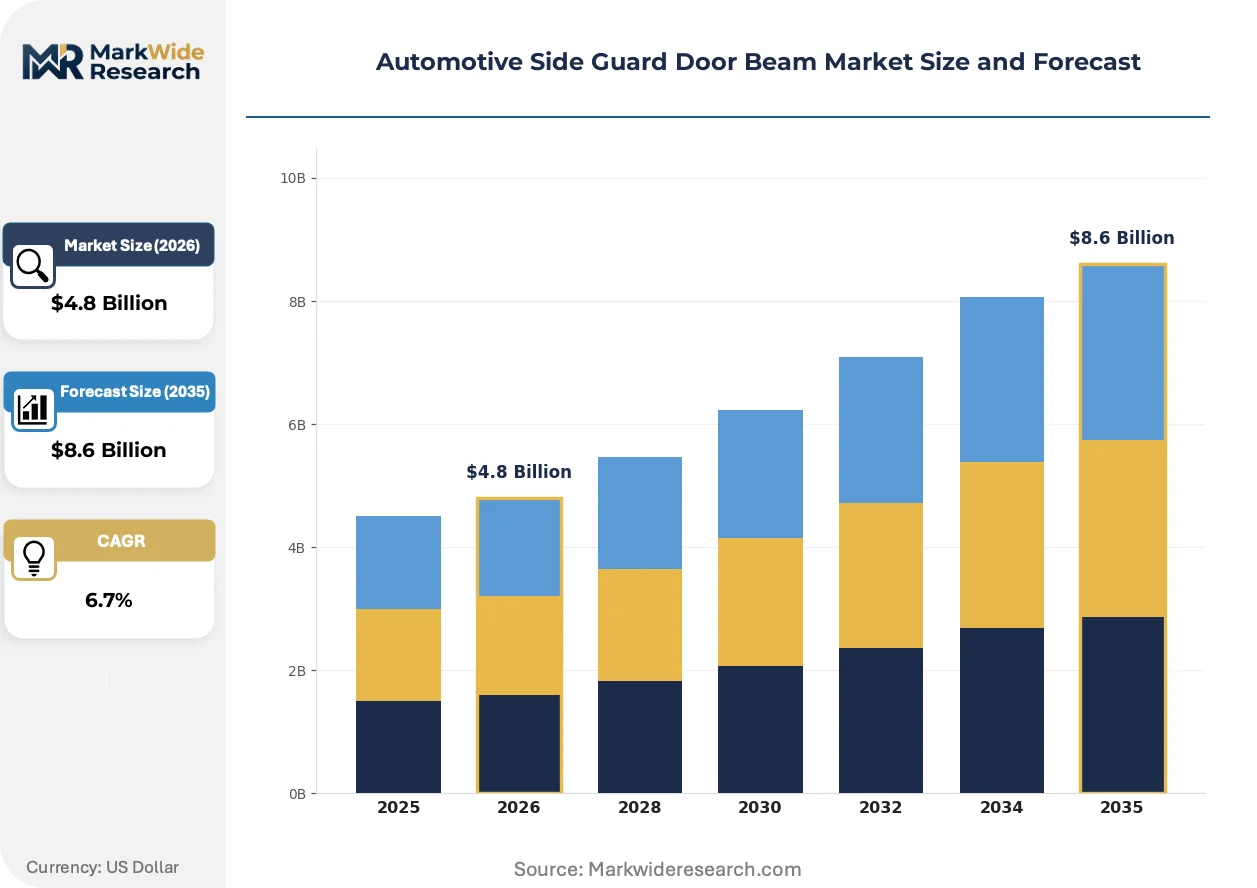
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic Application: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Raw Material Processing, Component Fabrication, Assembly, Quality Testing |
| Companies Covered | H-One Co. Ltd, KVA Stainless, KIRCHHOFF Automotive GmbH, Founder Land CO., LTD., Shiloh Industries, Benteler International AG, GNS America, IFB Automotive Private Limited, Gestamp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Side Guard Door Beam Market Strategic Shifts
Material-process integration is collapsing the traditional separation between beam design and manufacturing feasibility, compressing development cycles and reshaping supplier technical requirements.
Tailored blank technology is unifying laser-welded steel grades of varying thickness into single beam stampings that place mass only where intrusion resistance is critical. European electric vehicle programs are adopting these solutions fastest, with premium German platforms specifying 3-5 zone tailored blanks as standard. This approach is unifying previously separate high-strength and ultra-high-strength steel supply chains into consolidated single-source relationships.
REACH restrictions on hexavalent chromium surface treatments are accelerating conversion to trivalent passivation and zinc-nickel coating systems for corrosion protection. The industrial consequence is qualification delays for new coating chemistries and capital expenditure for line conversion at European stamping facilities. Steel beam suppliers serving EU-bound vehicle programs are responding with dedicated corrosion test protocols that exceed OEM baseline requirements.
Fleet electrification timelines are compressing sourcing decision cycles, with platform engineering teams demanding simultaneous steel and aluminum beam quotes to preserve optionality. Direct RFQ channels between OEM body-in-white engineers and Tier-2 beam specialists are displacing traditional module integrator intermediaries. This pattern is most visible in California and Shanghai, where aggressive zero-emission vehicle mandates force faster component-level decisions.
Automotive Side Guard Door Beam Market Segmentation
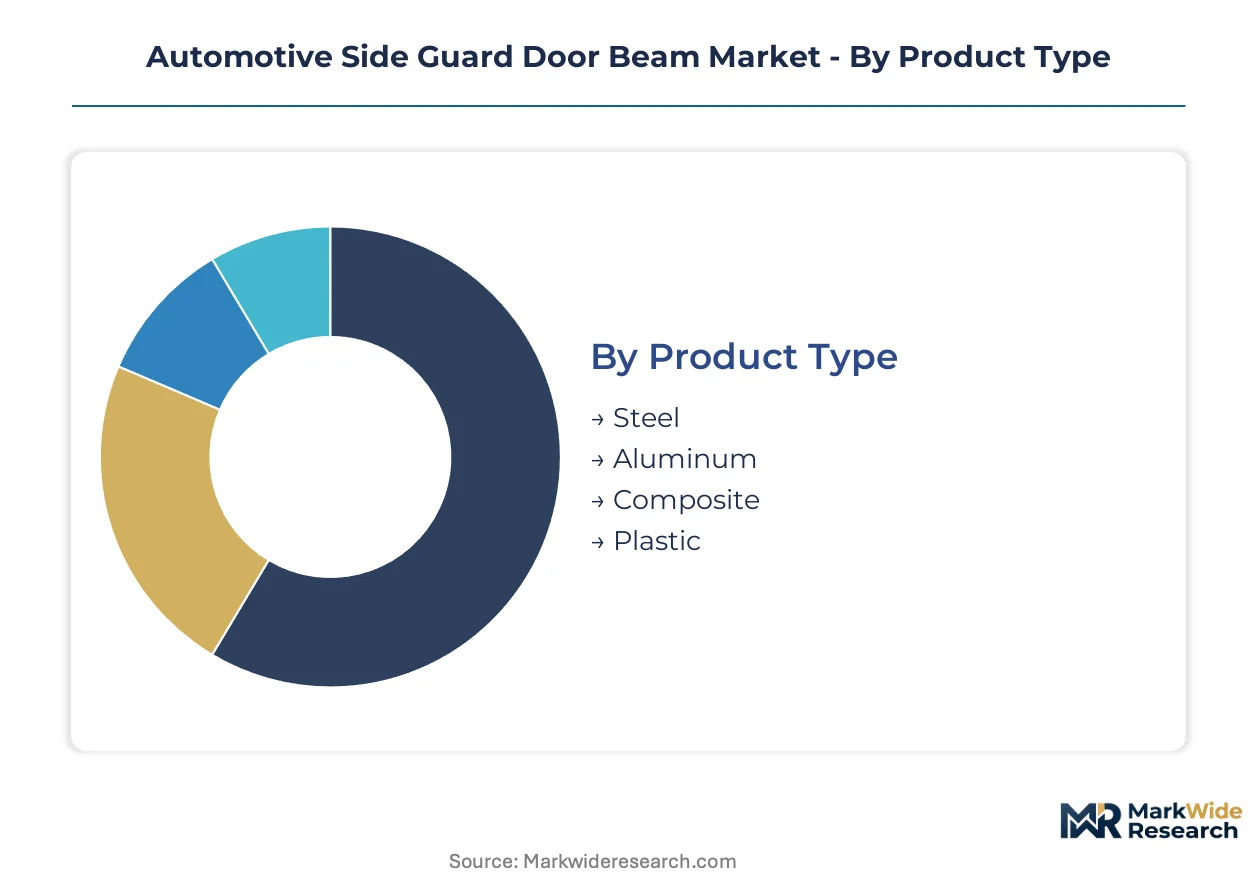
Beam specification varies sharply across vehicle architectures, with material selection and manufacturing stage determining crash-performance outcomes and supply chain positioning. Procurement patterns diverge between legacy internal-combustion platforms and dedicated electric vehicle programs.
Product Type:
Cost-per-kilogram thresholds and repair infrastructure availability separate buyers into distinct material tiers.
- Steel:Press-hardened grades exceeding 1500 MPa tensile strength dominate mass-market passenger cars. German OEM engineering centers in Wolfsburg and Stuttgart specify these beams for their established repair networks and lower raw material volatility.
- Aluminum:6000-series extrusions achieve weight-to-strength ratios critical for battery-electric range extension. Premium electric vehicle platforms in California and Shanghai are accelerating specifications here, though LME-linked input costs create margin pressure.
- Composite:Carbon-fiber reinforced polymers occupy niche positions in premium SUVs where multi-material door architectures justify higher per-vehicle costs.
- Plastic:Glass-filled thermoplastics serve secondary reinforcement roles in lower-impact zones of economy vehicle segments.
Steel leads volumes today; aluminum is gaining share fastest.
Application:
Crash-test protocols and platform electrification timelines reshape demand concentration across vehicle categories.
- Passenger Cars:NHTSA FMVSS 214 mandates drive standardized beam cross-sections across compact and mid-size segments. United States-based OEMs prioritize qualified supplier lists over material innovation here.
- Electric Vehicles:Battery-pack protection requirements and mass-reduction imperatives favor aluminum and hybrid steel-aluminum architectures. Chinese MIIT GB standards and California zero-emission mandates compress sourcing decision cycles.
- SUVs:Higher beltlines and increased curb weights demand reinforced beam geometries, often combining tailored blank steel with aluminum reinforcements.
- Commercial Vehicles:Durability requirements and fleet maintenance economics sustain steel dominance in light-duty trucks and vans.
Passenger cars anchor current procurement volumes; electric vehicles show the steepest expansion trajectory.
End User:
Integration depth and technical specification authority determine how procurement flows through the supply chain.
- OEMs:Direct body-in-white engineering teams at Volkswagen, BMW, and Tesla increasingly issue RFQs to Tier-2 beam specialists, bypassing traditional module integrators.
- Tier-1 Suppliers:Door module integrators like KIRCHHOFF Automotive and Gestamp retain volume leadership in European stamping and roll-forming.
- Vehicle Assemblers:Contract manufacturers and emerging EV startups source pre-certified beam assemblies to compress platform development timelines.
- Aftermarket Providers:Collision repair networks face equipment gaps for ultra-high-strength steel welding, limiting addressable market scope.
Tier-1 suppliers handle the majority of contracted volumes; direct OEM relationships are expanding most quickly.
Manufacturing Stage:
Process control and capital intensity requirements fragment supplier capabilities across the value chain.
- Component Fabrication:Hot-forming press capacity clusters in Upper Austria and southern Germany, creating qualification bottlenecks for new beam programs. Benteler International and Gestamp dominate tubular and roll-formed architectures here.
- Raw Material Processing:Specialty alloy production for automotive structural components is shifting to dedicated electric-arc operations in Japan, decoupling from traditional integrated mill economics.
- Assembly:Friction-stir welding and laser-welding integration enable hybrid steel-aluminum beam production for multi-material door structures.
- Quality Testing:Corrosion validation protocols exceed OEM baselines as REACH restrictions on hexavalent chromium force coating system conversions.
Component fabrication concentrates supplier margins today; raw material processing is climbing the fastest as specialty alloy demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering centers set material-performance benchmarks that cascade through supplier networks, while Chinese electric vehicle platforms compress sourcing cycles to meet aggressive zero-emission timelines.
United States
NHTSA FMVSS 214 mandates drive standardized beam cross-sections across all passenger vehicle classes. The regulation eliminates lower-grade steel options from qualified supplier lists for Detroit-based OEMs. Hot-forming press capacity concentrates in Michigan and Ohio, with Tier-1 stamping facilities clustered around Detroit-Warren-Dearborn.
Germany
Wolfsburg, Munich, and Stuttgart engineering centers specify multi-material door structures that reshape global supplier qualification requirements. ECE R95 regulations enforce side-pole and movable-barrier test protocols that determine beam geometry selection. Upper Austria and southern Germany host specialized press-hardening tooling capacity that creates single-source risk for new beam programs.
China
MIIT GB standards incorporate localized crash-speed parameters that influence supplier qualification timelines for domestic EV platforms. Battery-pack protection requirements favor aluminum beam architectures where range extension drives engineering trade-offs. Shanghai-based platform teams demand simultaneous steel and aluminum beam quotes to preserve material optionality.
Japan
Specialty alloy production for automotive structural components shifts to dedicated electric-arc operations, decoupling from traditional integrated mill economics. METI industrial policy supports lightweight material R&D for next-generation vehicle platforms. Nagoya-area stamping facilities supply hot-formed door beams across multiple Asian OEM programs.
Automotive Side Guard Door Beam Market Competitive Environment
German producers anchor one tier of the supply base; Japanese and Austrian specialists hold differentiated positions in alloy processing and hot-forming tooling. The market structure reflects moderate consolidation around stamping and roll-forming capabilities, with fragmentation in raw material processing. Three archetypes dominate: integrated steel processors with captive alloy supply, dedicated hot-forming specialists with press-hardening expertise, and aluminum extrusion houses serving EV platforms. Capacity expansion and strategic partnerships represent the primary competitive moves, as OEMs seek to qualify secondary sources for critical beam programs.
Among Germany-based fabricators, KIRCHHOFF Automotive GmbH and Benteler International AG exemplify the integrated stamping-to-assembly archetype, while Gestamp occupies a position within the roll-forming and laser-welding specialist tier. These entities represent distinct capability configurations that OEM body-in-white engineers evaluate during platform sourcing decisions.
| Leading Market Players |
|---|
| H-One Co. Ltd |
| KVA Stainless |
| KIRCHHOFF Automotive GmbH |
| Founder Land CO., LTD. |
| Shiloh Industries |
| Benteler International AG |
| GNS America |
| IFB Automotive Private Limited |
| Gestamp |
| Others |
Value Chain & Pricing Dynamics
LME aluminum futures and scrap steel indices cascade through beam manufacturing into three distinct procurement tiers, with OEM direct contracts compressing distributor margins while spot-market volatility feeds through to Tier-2 specialists. Hot-forming die scarcity in Upper Austria and southern Germany concentrates pricing power among press-hardening incumbents, forcing volume buyers into long-term offtake arrangements that lock in alloy grades but expose them to energy-cost pass-through clauses.
Pricing Analysis
Distributor markups of 12-18 percent separate Tier-1 door module integrators from direct OEM contracts, with the gap widening for aluminum extrusions where LME-linked volatility demands inventory risk premiums. Three-tier pricing structure across premium tailored-blank steel, standard press-hardened grades, and economy tubular architectures reflects certification complexity and repair-network compatibility. Cost compression in aluminum segments is intensifying because Chinese EV platforms demand simultaneous steel and aluminum quotes, eroding volume-commitment discounts. Fleet procurement teams at commercial vehicle operators show highest price sensitivity, while German premium OEM body-in-white engineers prioritize crash-performance consistency over per-kilogram savings.
Supply Chain Analysis
Returns of defective hot-formed stampings to Upper Austrian press facilities and scrap aluminum flows back to Japanese electric-arc operations create closed-loop material recovery that buffers raw-input volatility. Component fabrication concentrates in Germany, Austria, and Japan, with raw material processing drawing from dedicated specialty alloy mills in Nagoya and Linz. Supply chain risk centers on single-source hot-forming die capacity for 1500 MPa steel grades, where qualification timelines exceed platform development cycles. Distribution runs through Tier-1 door module integrators for legacy internal-combustion platforms, while direct OEM channels expand fastest in California and Shanghai EV programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where NHTSA FMVSS 214 intrusion mandates and ECE R95 side-pole protocols are elevating material-performance specifications above cost-per-kilogram optimization. Procurement committees now weight crash-test repeatability and coating-system durability as heavily as unit pricing.
For Market Incumbents: Lock in secondary hot-forming press capacity in southern Germany and Upper Austria before qualification bottlenecks harden into structural supply constraints. Secure captive supply of 1500 MPa press-hardened steel grades through backward integration into specialty alloy processing, defending against aluminum extrusion houses capturing EV platform share. Threat of direct OEM-Tier-2 contracting demands channel control investment in body-in-white engineering liaison teams. For New Entrants and Emerging Players: Friction-stir welding for hybrid steel-aluminum tailored blanks offers a technology-first wedge into premium German EV platforms where multi-material door architectures are standardizing fastest. White-space targets include Indian A- and B-segment vehicles facing impending side-impact mandates and North American collision repair networks requiring inert-gas welding equipment for ultra-high-strength steel. Go-to-market angle: pre-certified beam assemblies for contract manufacturers and EV startups compressing platform development timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with hot-forming specialists holding qualified die capacity for next-generation press-hardening grades, as platform consolidation concentrates sourcing decisions among fewer OEM engineering centers. Five-to-ten year viability favors acquisition targets with established corrosion-validation protocols exceeding REACH-mandated coating conversions. Signal to watch: OEM direct RFQ volume to Tier-2 beam specialists displacing traditional module integrator intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Forming Capacity Expansion | Qualification bottlenecks in Upper Austria and southern Germany reward early secondary-source investment by KIRCHHOFF and Gestamp. |
| Hybrid Material Architecture Development | Friction-stir welding integration enables tailored blank solutions optimizing strength-to-weight ratios for BMW and Tesla platforms. |
| Direct OEM Contracting Channel | Platform engineering consolidation opens supply relationships bypassing Tier-1 door module integrators in California and Shanghai. |
| Corrosion System Qualification | Trivalent passivation and zinc-nickel coating protocols exceeding ECE baselines secure EU-bound vehicle program approvals. |
| Aluminum Extrusion Scale-Up | 6000-series capacity expansion serves Chinese MIIT GB-compliant EV platforms where battery range drives mass-reduction priorities. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 door module procurement leads, hot-forming line technicians, and aftermarket collision repair operators with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 214 compliance filings, and ECE R95 test protocol documentation. Bottom-up beam shipment estimates by material grade and vehicle platform were cross-referenced against top-down OEM production schedules and content-per-vehicle assumptions.
Segment-weighting approaches applied differential growth assumptions across steel, aluminum, and composite material categories, with vehicle class, propulsion architecture, and regional production cluster as core modeling dimensions. CAGRs were derived from fitted trend lines across historical shipment data and projected platform mix shifts, incorporating OEM electrification timelines and safety regulation phase-ins as demand-side inputs without specifying implementation years.
The model holds under stable regulatory enforcement timelines and continued OEM platform consolidation; deviation in scrap aluminum price volatility or hot-forming die capacity expansion rates would shift supplier margin trajectories and material substitution patterns. Practitioners should monitor NHTSA side-impact protocol amendments and Chinese MIIT GB standard revisions for early signals of beam specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Airbag Market