
 Automotive Collision Avoidance Systems Market | 2026-2036
Automotive Collision Avoidance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Collision Avoidance Systems Market Outlook
The capability gap between semiconductor-intensive sensor suppliers and legacy tier-one assemblers is unwinding competitive hierarchies in collision avoidance hardware. Continental AG leverages its captive radar and lidar module production to sustain margin control across European OEM programs. Robert Bosch GmbH anchors its position through in-house manufacturing of ultrasonic and camera fusion controllers. Denso Corporation competes aggressively in Japanese and North American lane-keeping system supply through its integrated ECU and sensor packaging.
Automotive collision avoidance systems comprise integrated sensor arrays, processing units, and actuator interfaces that detect impending collisions and autonomously trigger braking, steering, or warning responses; typical configurations fuse 77 GHz radar, solid-state lidar, and CMOS camera inputs processed through ASIC-based domain controllers to achieve sub-100 millisecond reaction latency. Camera-based systems lead installation volume in passenger vehicles but face margin compression as commoditization spreads. Radar technology sustains premium positioning in commercial vehicle applications where all-weather reliability commands higher pricing. Lidar segments are accelerating fastest within autonomous vehicle programs, though unit economics remain constrained by emitter and photodetector yields.
NHTSA mandates on automatic emergency braking for light vehicles and Euro NCAP scoring protocols on vulnerable road user protection are forcing OEMs to standardize multi-feature packages rather than offer discrete options. Japan's Ministry of Land, Infrastructure, Transport and Tourism aligns type approval requirements with UN ECE regulations, reducing friction for Bosch and Denso in cross-border platform deployment. Stakeholders must monitor how EPA fuel economy credits and NHTSA safety rulemakings interact to determine whether collision avoidance hardware investments qualify for compliance offsets or face standalone cost absorption.
Market Dynamics
Multi-sensor fusion architectures are compressing tier-one supplier margins while elevating semiconductor specialists to system-level negotiation parity, restructuring procurement hierarchies across passenger and commercial vehicle programs.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandate:Light vehicle OEMs must standardize AEB hardware across model lines, eliminating optionality and securing baseline volumes for radar and camera module suppliers.
- Euro NCAP Vulnerable Road User Scoring:Pedestrian and cyclist detection protocols force integration of thermal imaging and higher-resolution CMOS arrays into mid-tier vehicle segments.
- Japan's MLIT Type Approval Alignment:UN ECE regulatory harmonization reduces recertification costs for suppliers deploying cross-border platforms between Japanese and European OEM programs.
Market Restraints
- Indium Phosphide Emitter Yield Constraints:Solid-state lidar production remains bottlenecked by compound semiconductor wafer defects, constraining unit economics for autonomous vehicle programs.
- East Asian CMOS Sensor Concentration:Camera module supply chains cluster in Taiwan and South Korea foundries, exposing OEMs to geopolitical disruption risk and single-source dependencies.
- FCC 77 GHz Spectrum Allocation Friction:Radar frequency licensing delays in North America postpone platform homologation timelines for multi-domain sensor suites.
Strategic Opportunities
- Indian Commercial Vehicle Retrofit Segment:ABS-to-AEB upgrade pathways for existing truck fleets create aftermarket hardware demand outside OEM new-vehicle channels.
- 4D Imaging Radar Convergence:Elevation-angle resolution capabilities merge traditional radar reliability with lidar-like object classification, opening mid-price positioning between camera and full lidar stacks.
- German KBA Software-Defined Vehicle Pathway:Over-the-air feature activation permits hardware pre-installation with revenue recognition deferred to software unlock events.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 ASIL-D certification expertise concentrates in German and Japanese engineering centers, constraining supplier expansion timelines.
- Legacy CAN Bus Integration Complexity:Domain controller deployment requires protocol translation layers that introduce latency and validation burden for mixed-architecture vehicle programs.
- Multi-Regulatory Homologation Parallelism:Simultaneous NHTSA, KBA, and MLIT approval processes demand redundant testing matrices that compress development cycle efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Collision Avoidance Systems Market |
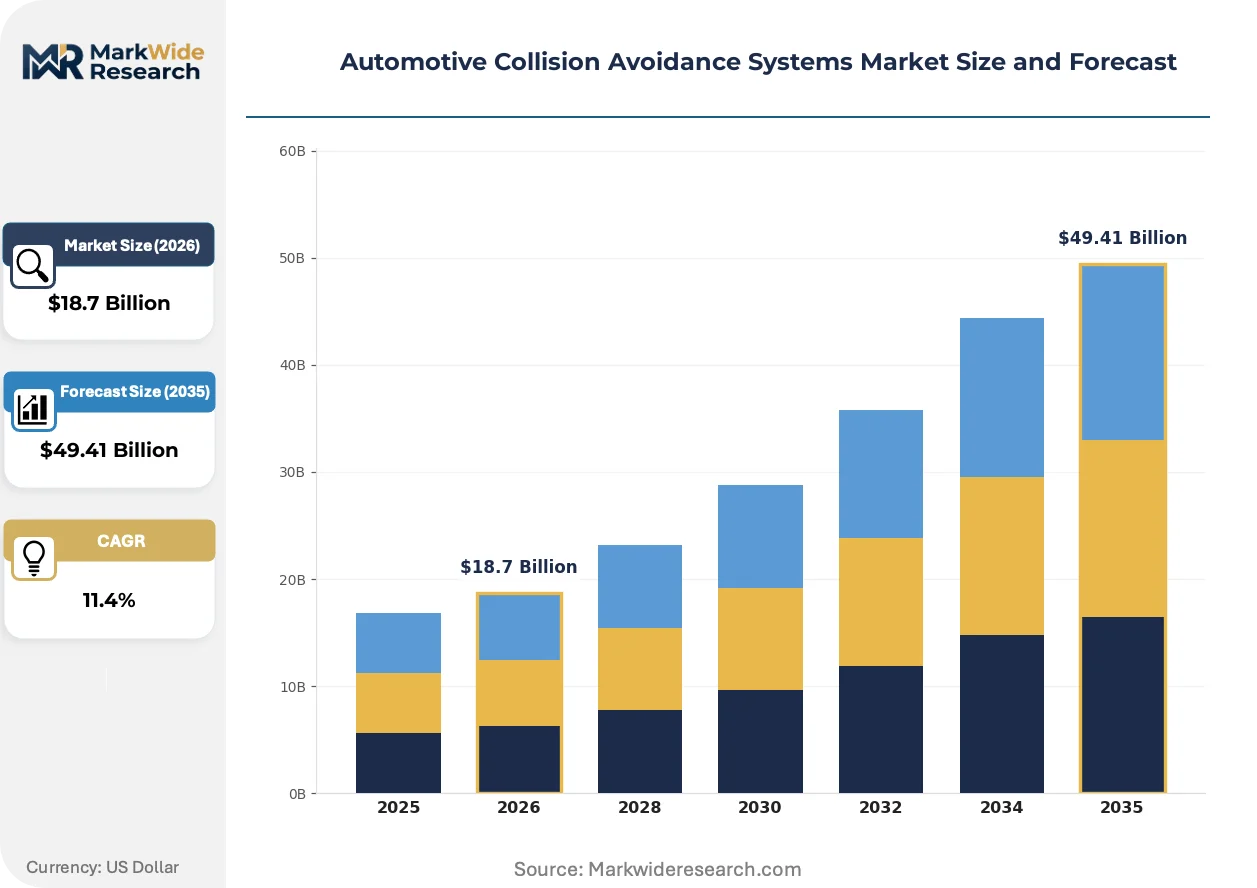
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Camera, Ultrasonic Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Autonomous Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Feature: Automatic Braking, Lane Departure Warning, Adaptive Cruise Control, Collision Detection |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Autoliv Inc., Mobileye, ZF Friedrichshafen AG, Infineon Technologies AG, Aptiv, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Collision Avoidance Systems Market Strategic Shifts
Silicon photonics and software-defined perception stacks are dissolving traditional hardware boundaries, enabling sensor fusion platforms that reconfigure capability through firmware rather than physical module swaps.
Silicon photonics-based coherent lidar is fragmenting the historical radar-lidar dichotomy by delivering Doppler velocity measurement alongside dense point clouds at semiconductor cost structures. Tier-one suppliers in Germany and Japan are integrating these chip-scale sensors into next-generation highway pilot systems. The technology is fragmenting procurement categories previously separated by wavelength and detection physics, forcing OEMs to rewrite supplier qualification frameworks.
EU AI Act risk classification for autonomous decision-making systems imposes conformity assessment burdens on collision avoidance algorithms that exceed traditional component-type approval. German KBA and French ANSM coordination on machine-learning validation protocols is creating precedent for cross-border mutual recognition. Premium passenger vehicle segments face compressed launch windows as software documentation requirements extend homologation timelines by six to nine months.
Fleet operators in North America are consolidating sensor procurement through direct contracts with semiconductor suppliers, bypassing traditional tier-one integrators for volume truck programs. This disintermediation concentrates specification power with logistics companies possessing in-house calibration and maintenance capabilities. The pattern is most visible in long-haul trucking corridors between Texas and California, where operator scale justifies dedicated engineering staff.
Automotive Collision Avoidance Systems Market Segmentation
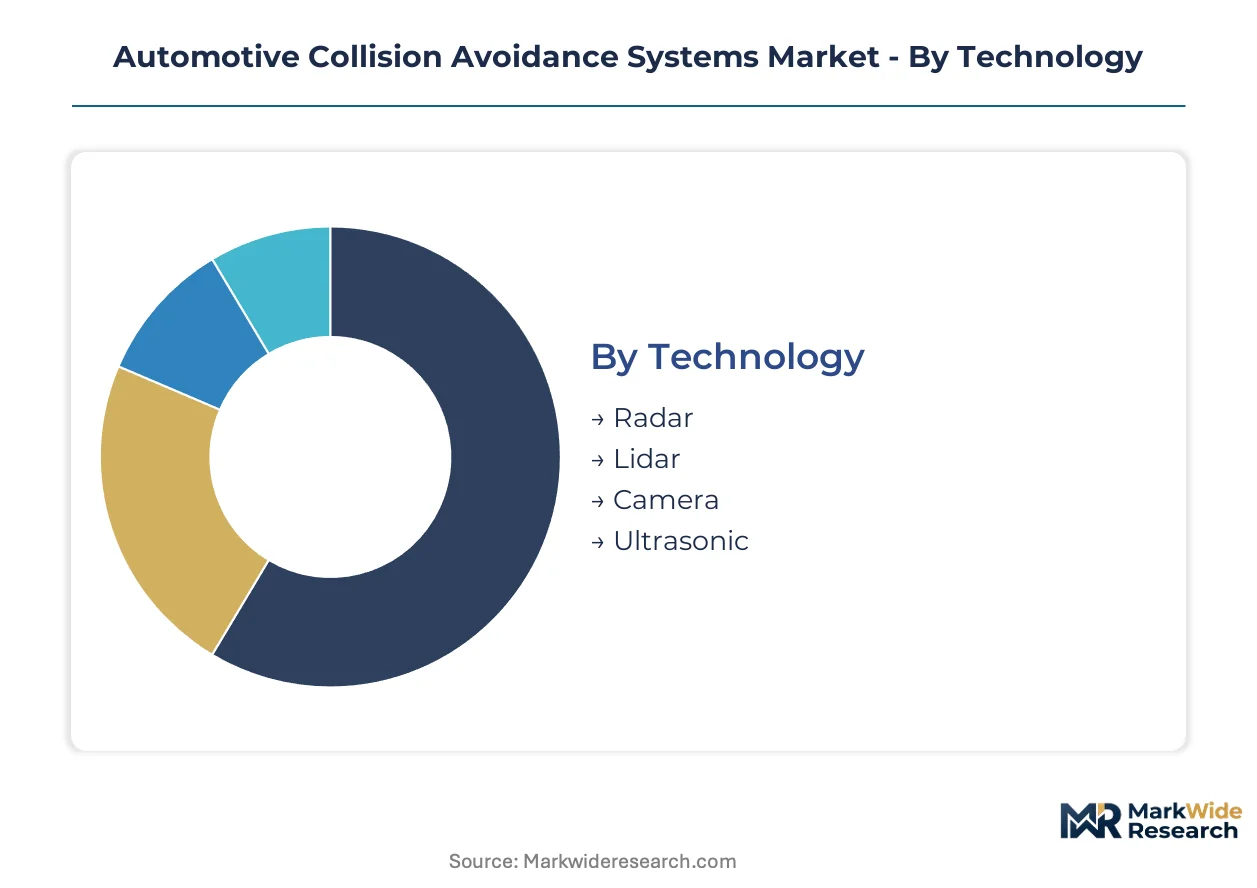
Collision avoidance hardware segments diverge sharply by regulatory trigger points and OEM integration depth. Technology choices determine supply chain exposure to semiconductor foundry capacity, while application splits reveal where mandate-driven standardization overrides consumer optionality.
Technology:
Domestic production clusters in Germany and Japan dominate radar and ultrasonic supply, while lidar and camera modules rely heavily on Taiwanese and South Korean foundry output.
- Radar:77 GHz frequency-modulated continuous-wave architectures deliver all-weather object detection with Doppler velocity resolution. German OEM programs and North American commercial vehicle mandates concentrate procurement of long-range radar for highway-speed automatic braking.
- Lidar:Solid-state coherent detection arrays generate dense point clouds through silicon photonics integration, though indium phosphide emitter yields constrain volume scaling. Autonomous vehicle programs in California and Arizona absorb premium pricing for 1550 nm wavelength units.
- Camera:CMOS image sensors with HDR processing enable lane-keeping and traffic sign recognition at commodity cost structures.
- Ultrasonic:Short-range parking assistance dominates low-speed maneuvering applications with minimal processing overhead.
Radar holds the largest share; momentum sits with lidar as silicon photonics displaces mechanical scanning architectures.
Application:
Volume concentration varies by regulatory enforcement timeline, with passenger vehicles facing earlier mandate deadlines than commercial retrofit channels.
- Passenger Vehicles:NHTSA automatic emergency braking requirements and Euro NCAP scoring protocols force multi-sensor standardization across mid-tier and premium segments. Japanese OEMs integrate lane-keeping and adaptive cruise control as bundled features to maximize NCAP ratings.
- Commercial Vehicles:Long-haul trucking corridors between Texas and California drive fleet-operator procurement of radar-based AEB systems with direct semiconductor supplier contracts bypassing tier-one integrators.
- Motorcycles:Compact radar and camera fusion targets two-wheeler vulnerable road user protection under evolving UN ECE regulations.
- Autonomous Vehicles:Robotaxi programs in Arizona and Texas deploy full sensor stacks combining lidar, radar, and camera arrays for SAE Level 4 operation.
Passenger vehicles dominate installed base; commercial vehicle retrofit demand is expanding most quickly as fleet operators accelerate safety compliance.
End User:
Procurement authority is fragmenting as fleet operators and insurers gain specification influence alongside traditional OEM engineering departments.
- OEMs:Volkswagen, Toyota, and Ford integrate collision avoidance as standard equipment to satisfy NHTSA mandates and optimize NCAP scoring, compressing tier-one supplier margins through volume consolidation.
- Aftermarket Providers:Indian commercial vehicle retrofit specialists upgrade ABS-equipped trucks to AEB capability through add-on radar modules and controller units.
- Fleet Operators:Schneider National and J.B. Hunt negotiate direct sensor supply contracts with semiconductor vendors, disintermediating traditional tier-one channels for calibration and maintenance control.
- Insurance Companies:Progressive and State Farm subsidize AEB hardware installation through usage-based policy discounts, creating alternative demand pathways outside OEM new-vehicle sales.
OEMs retain volume leadership; fleet operators are gaining specification authority fastest through in-house engineering capabilities.
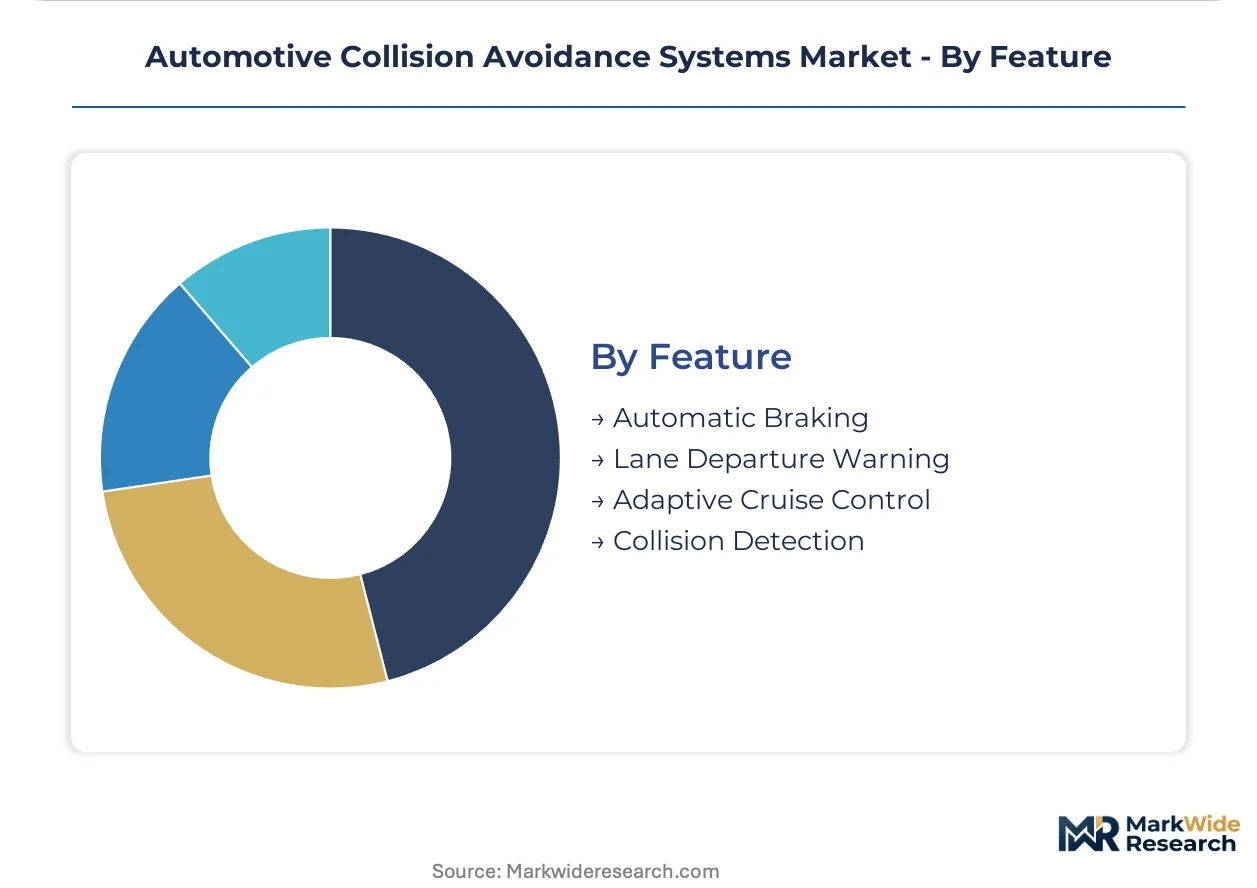
Feature:
Functional bundling accelerates as regulators treat discrete capabilities as interconnected safety systems rather than standalone options.
- Automatic Braking:Radar-camera fusion triggers full brake application when collision probability exceeds calibrated thresholds, with NHTSA mandates eliminating consumer opt-out for light vehicles under 8500 lbs.
- Lane Departure Warning:Camera-based edge detection alerts drivers through haptic steering feedback or audible alarms, with Euro NCAP scoring rewarding corrective steering intervention over passive notification.
- Adaptive Cruise Control:Radar maintains set speed while adjusting for preceding vehicle distance, now standard in Japanese and German premium segments.
- Collision Detection:Multi-sensor fusion classifies object type and trajectory to prioritize pedestrian and cyclist protection under vulnerable road user protocols.
Automatic braking commands the largest installed base; vulnerable road user detection features are climbing the fastest as Euro NCAP scoring weights pedestrian protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States absorb premium pricing for multi-sensor suites without volume hesitation, while Indian commercial vehicle retrofit buyers demand aggressive cost engineering on radar-camera fusion kits.
United States
Long-haul trucking corridors between Texas and California generate concentrated demand for radar-based automatic emergency braking systems. NHTSA mandates on light vehicle AEB standardization compress procurement timelines across Detroit Three OEM programs. Arizona and Texas host autonomous vehicle testing clusters where robotaxi operators deploy full lidar-radar-camera stacks.
Germany
Premium passenger vehicle manufacturers in Stuttgart and Munich integrate multi-sensor fusion as standard equipment to maximize Euro NCAP scoring. KBA software-defined vehicle pathways enable over-the-air feature activation, deferring revenue recognition. Bavaria and Baden-Württemberg concentrate tier-one supplier engineering centers for ISO 26262 ASIL-D certification.
Japan
Domestic OEMs bundle lane-keeping and adaptive cruise control to optimize MLIT type approval alignment with UN ECE regulations. Denso and Bosch leverage reduced recertification friction for cross-border platform deployment. Aichi Prefecture and Tokyo metropolitan clusters anchor integrated ECU and sensor packaging production.
China
Domestic electric vehicle brands accelerate procurement of solid-state lidar for highway pilot systems despite indium phosphide emitter yield constraints. MIIT autonomous driving regulations shape sensor configuration requirements for SAE Level 2+ programs. Yangtze River Delta foundries supply CMOS image sensors with HDR processing for camera-based systems.
South Korea
Hyundai Motor Group and Kia standardize collision avoidance hardware across model lines to satisfy export market homologation requirements. MFDS alignment with international functional safety standards reduces validation burden for semiconductor suppliers. Seoul Capital Area and Busan-Ulsan clusters concentrate camera module assembly and radar subsystem integration.
Automotive Collision Avoidance Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in collision avoidance hardware supply. Continental AG and Robert Bosch GmbH maintain captive production of radar modules and sensor fusion controllers, compressing margins for pure-play assemblers. Three strategic archetypes dominate: vertically integrated tier-one suppliers with in-house semiconductor fabrication, semiconductor specialists negotiating system-level contracts, and fleet operators disintermediating traditional channels through direct procurement. Competitive moves concentrate on backward integration into compound semiconductor wafer production and geographic expansion through regulatory harmonization pathways.
Among German integrated suppliers, Continental AG and Robert Bosch GmbH exemplify the tier-one archetype through captive module production and controller manufacturing. Denso Corporation anchors the Japanese supplier position with integrated ECU and sensor packaging capabilities.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Autoliv Inc. |
| Mobileye |
| ZF Friedrichshafen AG |
| Infineon Technologies AG |
| Aptiv |
| Panasonic Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Wafer fabrication scale economies in Taiwan and South Korea concentrate photodetector and CMOS sensor supply, compressing unit costs for camera modules while elevating price floors for indium phosphide lidar emitters where yield defects persist. This asymmetry forces tier-one suppliers to absorb margin pressure on commoditized radar-camera fusion kits while extracting premiums from autonomous vehicle programs requiring coherent detection arrays.
Pricing Analysis
After-sales service contracts and over-the-air feature activation drive lifetime value capture beyond hardware shipment. The dominant structure combines per-unit transactional pricing for baseline sensor modules with subscription-tiered software unlocks for advanced functionality. Price differentiation rests on ASIL certification grade and volume scale, with D-certified controllers commanding substantial premiums over B-tier alternatives. Cost compression in camera-based systems intensifies as HDR CMOS sensors commoditize, while fleet operators in North American trucking corridors demonstrate lowest price sensitivity due to insurance premium offsets and liability reduction calculus.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for CMOS image sensors and memory components, while Germany and Japan concentrate radar module and controller assembly. The chain draws from indium phosphide wafers for lidar emitters, 77 GHz radar MMICs, and automotive-grade ASICs. Single-source vulnerability concentrates in Taiwanese foundry capacity for neural processing units. Distribution runs through tier-one integrators to OEM assembly plants, with fleet operators increasingly negotiating direct semiconductor contracts for volume truck programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive collision avoidance systems market sits in early-cycle expansion as NHTSA mandates on automatic emergency braking eliminate consumer optionality and secure baseline hardware volumes across light vehicle segments. Regulatory harmonization between UN ECE, MLIT, and KBA frameworks accelerates cross-border platform deployment, reducing recertification friction for integrated suppliers.
For Market Incumbents: Shield margin position through captive production of radar MMICs and sensor fusion controllers, mirroring Continental AG's integration model. Backward integration into compound semiconductor wafer production defends against indium phosphide emitter yield constraints that constrain lidar economics. Prioritize ISO 26262 ASIL-D certification depth to maintain specification authority as semiconductor specialists negotiate system-level contracts.
For New Entrants and Emerging Players: Anchor in the Indian commercial vehicle retrofit segment where ABS-to-AEB upgrade pathways create aftermarket hardware demand outside OEM new-vehicle channels. Target fleet operator direct procurement relationships in Texas-California trucking corridors, where operator scale justifies dedicated engineering staff and bypasses traditional tier-one integrators. Pursue 4D imaging radar convergence as a mid-price positioning strategy between camera and full lidar stacks.
For Investors and Strategic Acquirers: Semiconductor specialists with coherent lidar silicon photonics capabilities represent the most defensible acquisition archetype as the technology fragments traditional radar-lidar procurement categories. Long-term viability hinges on regulatory mandate durability across NHTSA, Euro NCAP, and MLIT jurisdictions rather than discretionary consumer adoption. Watch FCC 77 GHz spectrum allocation resolution as an inflection indicator for North American radar platform homologation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Platform Standardization | Reduces per-vehicle integration cost for OEMs facing NHTSA mandate deadlines. |
| Silicon Photonics Lidar Manufacturing Scale-Up | Enables semiconductor cost structures that displace mechanical scanning architectures. |
| Software-Defined Vehicle Pathway Investment | Permits KBA-compliant over-the-air feature activation with deferred revenue recognition. |
| Direct Fleet Operator Supply Contracting | Disintermediates tier-one integrators for North American long-haul trucking corridors. |
| ASIL-D Functional Safety Certification Expansion | Addresses engineer scarcity constraining supplier expansion in German and Japanese centers. |
Study Parameters
Cross-validation between OEM platform engineering disclosures and tier-one supplier procurement patterns anchors the qualitative findings on competitive positioning and margin structure. Primary interviews with collision avoidance system architects, semiconductor foundry account managers, fleet safety directors, and automotive regulatory homologation specialists combined with secondary validation from NHTSA rulemaking dockets, Euro NCAP test protocols, UN ECE regulation repositories, and vehicle production registration databases. Bottom-up sensor shipment estimates and top-down OEM platform content analysis triangulate market sizing across the forecast period.
Sensitivity analysis on indium phosphide emitter yield trajectories and FCC spectrum allocation timelines frames the projection envelope. The analytical framework models technology segmentation by detection physics, application splits across passenger and commercial vehicles, end-user procurement authority fragmentation, and regional regulatory cluster alignment. CAGRs derive from mandate-driven installation baselines and autonomous vehicle program scaling assumptions, with inputs including semiconductor foundry capacity utilization, ASIL certification pipeline throughput, and fleet operator safety compliance expenditure patterns.
Material uncertainties — compound semiconductor wafer defect rates, geopolitical disruption to East Asian CMOS supply, and multi-regulatory homologation parallelism — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory mandate enforcement timelines and technology cost reduction curves. Recalibration cycles align with material shifts in NHTSA rulemaking, Euro NCAP scoring protocol revisions, and silicon photonics manufacturing yield breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market