
 Global Cardiac Rehabilitation Market | 2026-2036
Global Cardiac Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Rehabilitation Market Foresight
A shortage of certified cardiac rehabilitation specialists is redrawing competitive dynamics across the industry. GE Healthcare leverages its imaging-to-rehabilitation workflow integration to capture institutional contracts. Koninklijke Philips N.V. anchors its position through connected monitoring ecosystems that span hospital and home settings. Technogym specializes in prescription-grade exercise equipment tailored to hemodynamically monitored protocols.
Cardiac rehabilitation encompasses medically supervised programs combining exercise training, risk factor modification, and psychosocial support to restore functional capacity after myocardial infarction, coronary artery bypass grafting, or percutaneous coronary intervention, typically delivered through structured sessions with heart rate and blood pressure surveillance. Exercise training components dominate program delivery due to their established mortality benefit and reimbursement eligibility across Medicare and private payers. Home-based and telehealth segments are expanding fastest as remote physiologic monitoring technology matures and payers relax site-of-service requirements.
The FDA regulates cardiac rehabilitation devices and software under its digital health and cardiovascular device frameworks, while the Centers for Medicare & Medicaid Services governs reimbursement codes that determine program viability. Europe's Medical Device Regulation and CE marking requirements create compliance thresholds for exercise monitoring equipment entering EU markets. Stakeholders must track how payer coverage decisions for remote cardiac rehabilitation will reshape capital allocation between facility-based infrastructure and connected home health platforms.
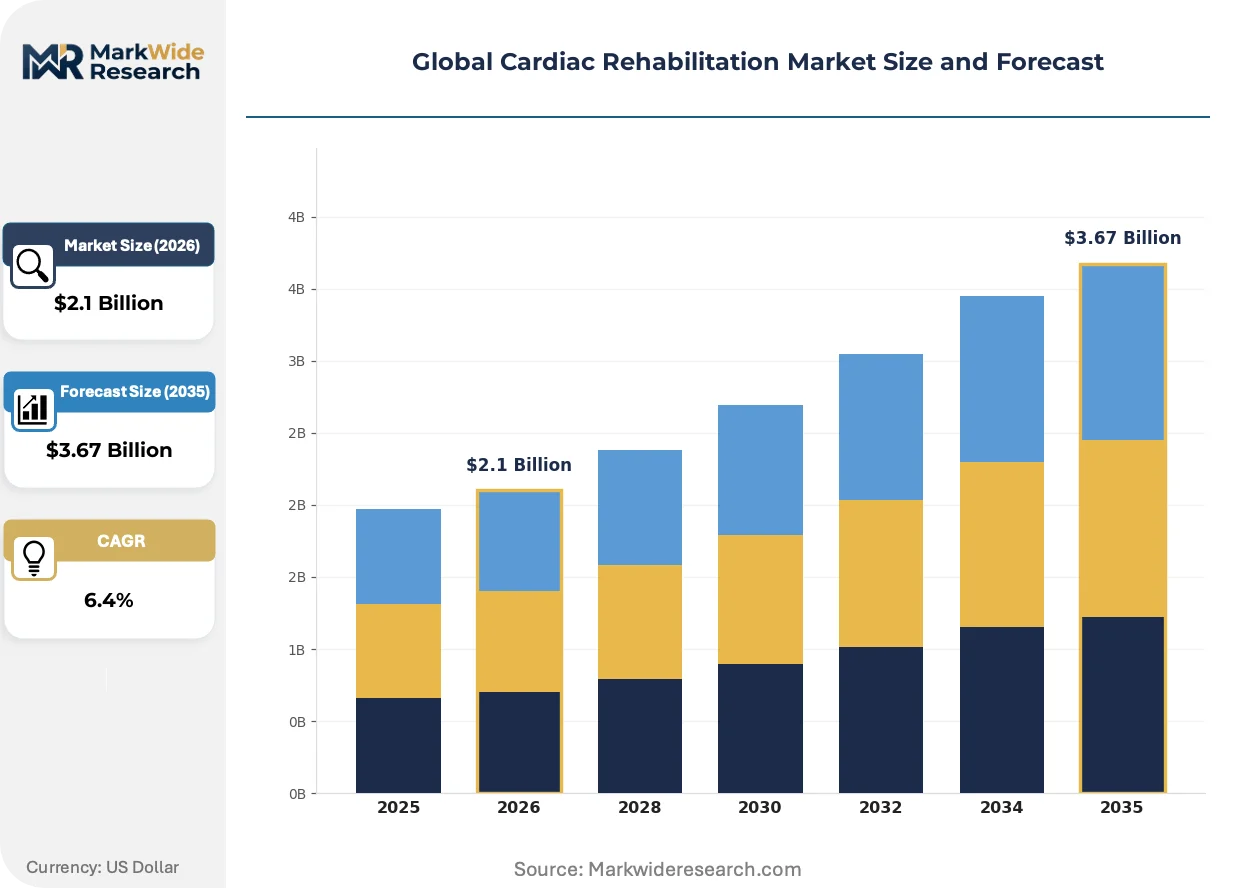
Market Dynamics
Remote physiologic monitoring technology is compressing site-of-service requirements, forcing capital reallocation from hospital infrastructure toward connected home health platforms and telehealth delivery models.
Growth Catalysts
- MDR Compliance Thresholds:Europe's Medical Device Regulation raises barriers for exercise monitoring equipment, favoring established manufacturers with CE marking capabilities and quality management systems.
- Post-Surgical Cohort Expansion:Rising percutaneous coronary intervention volumes in aging populations across Germany, Japan, and the United States expand eligible patient pools for structured rehabilitation programs.
- Remote Monitoring Technology:Wearable heart rate and blood pressure surveillance devices enable home-based program delivery without compromising hemodynamic safety protocols.
Market Restraints
- Specialist Shortage Concentration:Certified cardiac rehabilitation clinicians cluster in metropolitan hospital systems, leaving rural and suburban markets underserved despite patient demand.
- Reimbursement Site Restrictions:Medicare and private payer coverage codes still favor facility-based sessions, creating financial friction for telehealth program adoption.
- Capital Equipment Intensity:Prescription-grade exercise machinery with integrated monitoring systems requires substantial upfront investment, constraining program expansion by smaller healthcare systems.
Strategic Opportunities
- Japan's Aging Demographics:METI-supported digital health initiatives create favorable conditions for connected cardiac rehabilitation platforms targeting the country's expanding elderly population.
- Behavioral Health Integration:Psychosocial support components remain underdeveloped relative to exercise training, offering differentiation for programs addressing depression and anxiety post-cardiac event.
- AI-Enabled Risk Stratification:Machine learning algorithms analyzing physiologic data streams enable personalized exercise prescription adjustments in real time during remote sessions.
Industry Challenges
- Interoperability Fragmentation:Electronic health record systems from different vendors resist seamless integration with third-party cardiac rehabilitation software platforms.
- Workforce Pipeline Constraints:Academic programs produce insufficient exercise physiologists and cardiac nurses to meet program enrollment targets across existing and planned facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Rehabilitation Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Hospital-Based, Home-Based, Community-Based, Telehealth Component: Exercise Training, Psychological Counseling, Nutritional Advice, Risk Factor Management Care Setting: Specialty Clinics, Rehabilitation Centers, Outpatient Facilities, Primary Care Practices End User: Cardiac Patients, Geriatric Population, Post-Surgical Patients, Chronic Disease Patients |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Omron Corporation, Core Health & Fitness, LLC, Honeywell International, Inc., Technogym, Johnson Health Tech, Halma plc, BioTelemetry Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Rehabilitation Market Shifts & Advancements
Digital health regulatory frameworks are maturing simultaneously with remote monitoring hardware capabilities, creating enabling conditions for hybrid delivery models that blend institutional oversight with home-based patient convenience.
Telehealth-enabled cardiac rehabilitation is bifurcating program design between synchronous virtual sessions with live clinician oversight and asynchronous platforms relying on automated physiologic alerts. Hospital systems in the United States pilot blended models where initial assessments occur in-facility while maintenance phases shift home. This technology is bifurcating competitive positioning between institutions investing in integrated remote platforms and those defending traditional facility-based volume.
Europe's MDR framework tightens clinical evidence requirements for software as a medical device, extending approval timelines for algorithm-driven exercise prescription tools. Manufacturers must demonstrate clinical validation through prospective studies rather than retrospective algorithm training. Cardiac rehabilitation platforms with AI components face the steepest compliance burden, with some developers withdrawing from EU markets rather than absorbing certification costs.
Self-referral pathways are displacing physician-mandated enrollment in markets with direct-to-consumer health spending capacity. Patients recovering from myocardial infarction increasingly research program options independently, comparing telehealth accessibility and equipment quality before selecting providers. This behavioral shift is most visible in Germany's statutory health insurance system, where supplementary private coverage enables choice outside primary care gatekeeping.
Global Cardiac Rehabilitation Market Segmentation
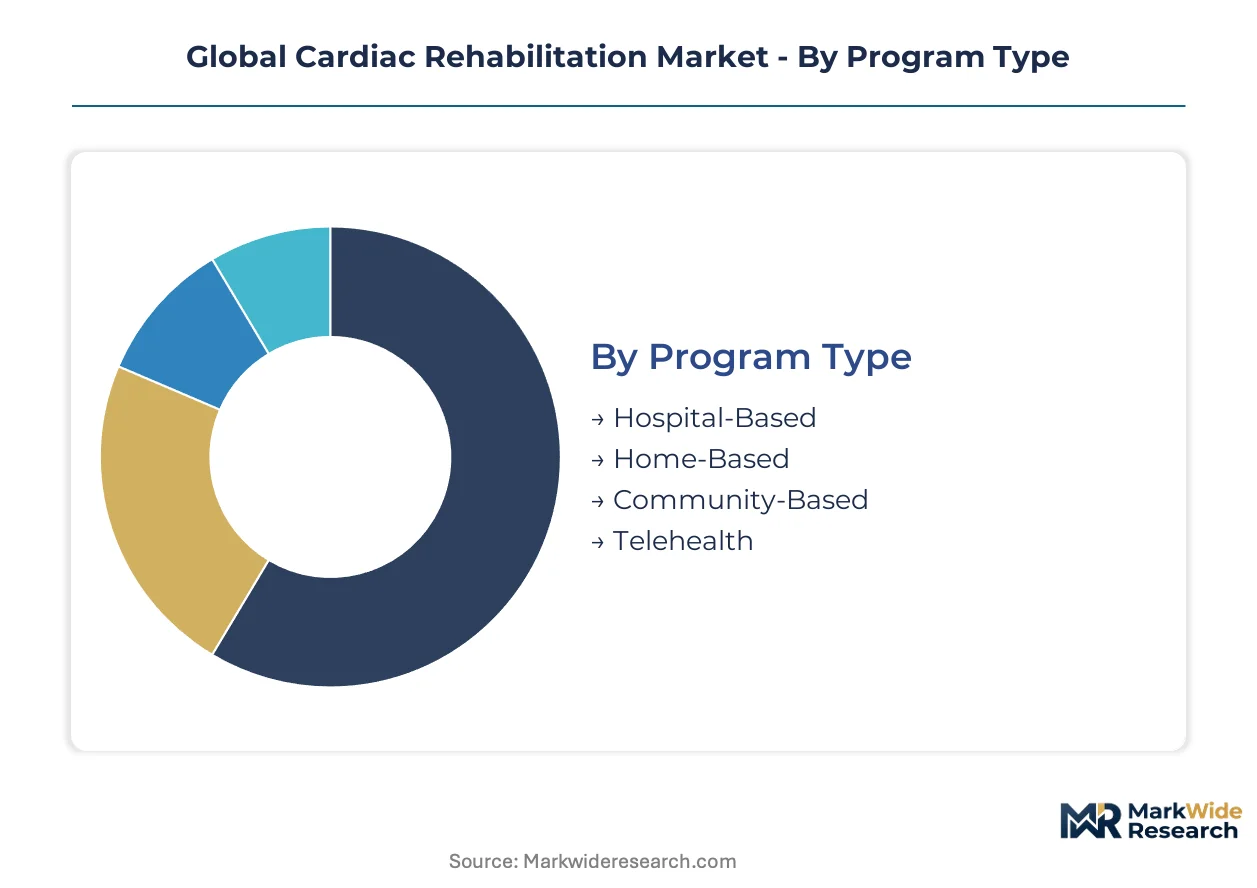
Segmentation in cardiac rehabilitation reveals how reimbursement rules and site-of-service flexibility reshape competitive boundaries. Each dimension exposes different pressure points on capital allocation, workforce deployment, and technology integration.
Program Type:
Telehealth platforms face the strongest substitution pressure as remote physiologic monitoring matures and payers relax location requirements.
- Hospital-Based:Medically supervised programs with continuous electrocardiographic and hemodynamic surveillance during structured exercise sessions. Demand concentrates in metropolitan hospital systems across the United States, Germany, and Japan where aging demographics and established reimbursement codes support high enrollment volumes despite infrastructure costs.
- Telehealth:Remote delivery combining wearable heart rate monitors with virtual clinician oversight through synchronous video or asynchronous data review. Germany's statutory health insurance system and Japan's METI-supported digital health initiatives are accelerating patient self-referral into these platforms as site restrictions loosen.
- Home-Based:Patient-directed exercise protocols with periodic nursing visits and remote device transmission.
- Community-Based:Local facility programs typically housed in fitness centers or municipal recreation spaces.
Hospital-Based retains volume leadership; Telehealth holds the steepest expansion curve.
Component:
Cost tier differentiation separates reimbursable clinical services from ancillary support elements that patients often fund privately.
- Exercise Training:Prescription-grade aerobic and resistance protocols with real-time heart rate and blood pressure surveillance. Medicare and private payer coverage eligibility in the United States drives institutional investment in integrated monitoring equipment despite capital intensity constraints.
- Risk Factor Management:Structured interventions targeting hypertension, dyslipidemia, smoking cessation, and diabetes control through medication optimization and lifestyle modification. Post-surgical patient cohorts in Germany and Japan generate concentrated demand as secondary prevention gains priority in cardiac care pathways.
- Psychological Counseling:Depression and anxiety screening with cognitive behavioral interventions.
- Nutritional Advice:Dietary counseling for sodium restriction, lipid management, and weight control.
Exercise Training commands the largest reimbursement share; Risk Factor Management is climbing the fastest as integrated care models expand.
Care Setting:
Volume concentration in high-acuity venues reflects where capital equipment and certified specialists cluster most densely.
- Rehabilitation Centers:Dedicated facilities with comprehensive exercise machinery, telemetry systems, and multidisciplinary staffing. The United States and Germany host the densest networks of these centers where economies of scale justify investment in prescription-grade monitoring infrastructure.
- Specialty Clinics:Cardiology-focused outpatient units with rehabilitation as a service line extension. Japan's aging population and METI digital health incentives are concentrating demand in urban specialty clinics that blend in-person assessment with remote maintenance phases.
- Outpatient Facilities:General hospital departments or ambulatory surgery centers with rehabilitation capacity.
- Primary Care Practices:Community physician offices with basic exercise counseling and risk factor monitoring.
Rehabilitation Centers retain volume leadership; Specialty Clinics are gaining share fastest through hybrid delivery models.
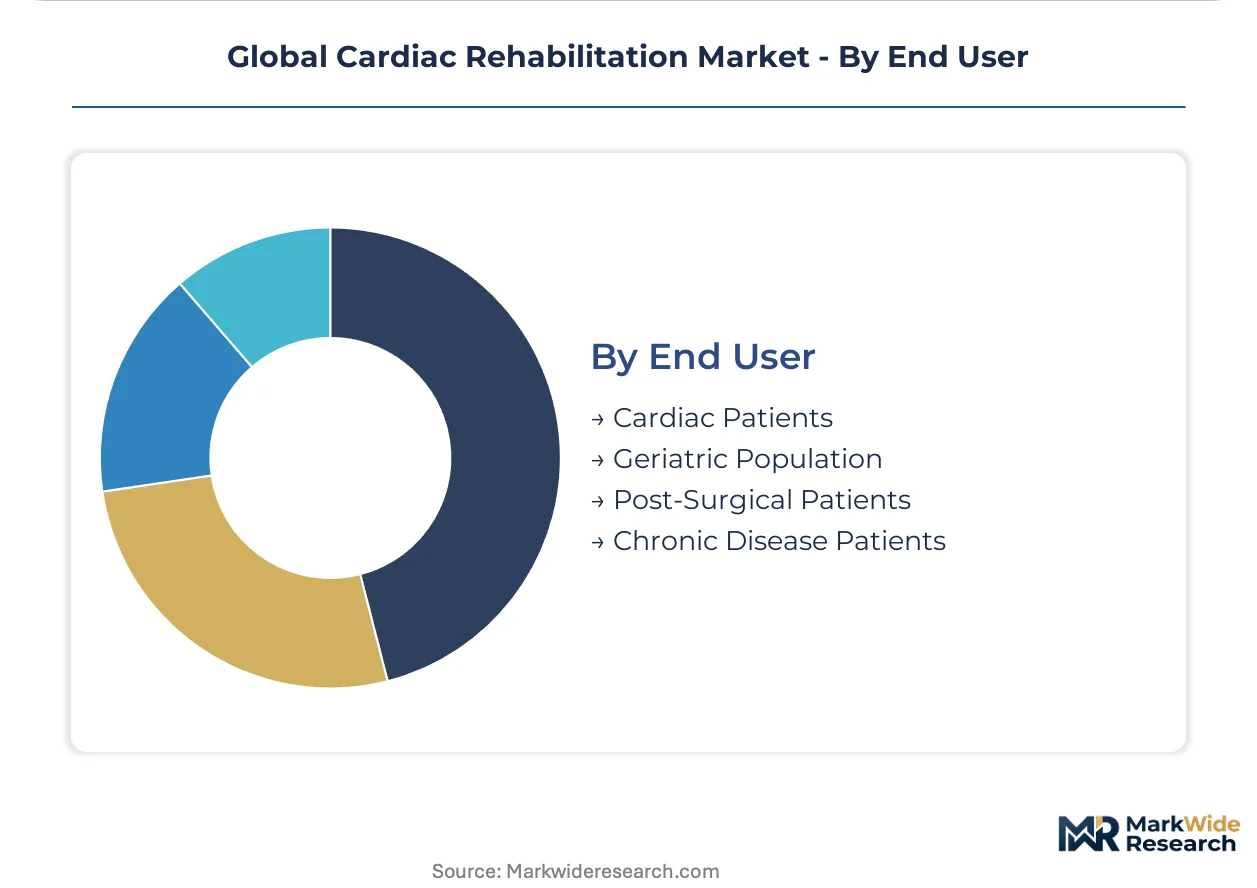
End User:
Customer type segmentation exposes how clinical indication and age demographics intersect with reimbursement eligibility and program design.
- Post-Surgical Patients:Individuals recovering from coronary artery bypass grafting, percutaneous coronary intervention, or valve replacement requiring structured functional restoration. Rising PCI volumes across Germany, Japan, and the United States are expanding this cohort fastest as procedural thresholds broaden.
- Geriatric Population:Adults over 65 with multiple comorbidities requiring modified exercise intensity and enhanced fall precautions. Japan's demographic profile and Germany's statutory insurance structure concentrate demand for age-adapted protocols with integrated remote monitoring.
- Cardiac Patients:Broader category including myocardial infarction survivors and stable angina cases.
- Chronic Disease Patients:Individuals with heart failure or peripheral artery disease seeking functional maintenance.
Post-Surgical Patients retain volume leadership; Geriatric Population represents the steepest expansion trajectory as population aging accelerates across major markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan and Germany where aging demographics and statutory reimbursement frameworks sustain premium program rates, while cost-sensitive expansion markets compress margins through competitive tendering and fragmented provider networks.
United States
Medicare reimbursement codes and commercial payer site-of-service restrictions channel volume toward hospital-based programs despite telehealth expansion. The FDA's digital health guidance creates compliance thresholds for remote monitoring platforms. Major health systems in Cleveland and Houston anchor hybrid delivery pilots blending institutional assessment with home-based maintenance phases.
Germany
Statutory health insurance covers structured rehabilitation with supplementary private options enabling patient choice outside gatekeeping. Europe's MDR framework extends approval timelines for algorithm-driven exercise prescription tools. Berlin and Munich host dense networks of rehabilitation centers where economies of scale justify prescription-grade monitoring infrastructure investment.
Japan
METI-supported digital health initiatives accelerate adoption of connected cardiac rehabilitation platforms targeting the expanding elderly population. The PMDA regulates software as medical device under evolving frameworks. Tokyo and Osaka concentrate specialty clinics blending in-person assessment with remote maintenance phases for post-surgical cohorts.
United Kingdom
NHS long-term plan commitments expand access to cardiac rehabilitation though workforce constraints limit program reach. MHRA post-Brexit regulatory alignment with MDR creates transitional uncertainty for device approvals. London and Manchester anchor regional networks where integrated care systems pilot risk-stratified referral pathways.
Australia
Medicare Benefits Schedule items support both center-based and home-based program delivery with increasing flexibility. The TGA regulates wearable monitoring devices under medical device frameworks. Sydney and Melbourne concentrate rehabilitation capacity with emerging telehealth networks extending reach into rural Queensland and Western Australia.
Global Cardiac Rehabilitation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with imaging-to-rehabilitation integrators commanding institutional contracts while exercise equipment specialists defend margin through prescription-grade positioning. The vendor base separates into three strategic tiers: diversified health technology conglomerates with workflow integration capabilities, connected monitoring ecosystem providers spanning acute and ambulatory settings, and prescription-grade exercise equipment manufacturers with hemodynamic protocol specialization. Dominant competitive moves include strategic partnerships between hardware manufacturers and telehealth platform developers, plus portfolio diversification into remote patient monitoring adjacent categories.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions exemplifying imaging-to-rehabilitation workflow integration and connected monitoring ecosystem strategies respectively. Technogym represents the prescription-grade exercise equipment archetype with hemodynamic protocol specialization. These three anchors illustrate how competitive positioning separates between institutions investing in integrated remote platforms and those defending traditional facility-based volume through capital equipment intensity.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Omron Corporation |
| Core Health & Fitness, LLC |
| Honeywell International, Inc. |
| Technogym |
| Johnson Health Tech |
| Halma plc |
| BioTelemetry Inc. |
| Others |
Supply & Pricing Matrix
Europe's Medical Device Regulation gates both supply qualification and price differentiation simultaneously, extending approval timelines for algorithm-driven exercise prescription tools while creating compliance premiums for established CE marking holders. Manufacturers absorbing certification costs pass these through to hospital systems and telehealth platforms, compressing margins for smaller entrants unable to scale quality management systems.
Pricing Analysis
The customization-premium spread separates prescription-grade exercise machinery with integrated hemodynamic monitoring from standard fitness equipment lacking clinical validation. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, CE marking tier, and after-sales service bundling. Cost compression in the economy tier intensifies as Asian manufacturers enter basic monitoring segments. Post-surgical patient cohorts in Germany and Japan exhibit lowest price sensitivity due to statutory reimbursement coverage, while community-based programs in cost-sensitive markets face procurement consolidation.
Supply Chain Analysis
Semiconductor fabrication capacity in Taiwan, South Korea, and the United States constitutes the critical chokepoint for wearable heart rate and blood pressure surveillance devices. Sensor modules, telemetry chipsets, and lithium-ion power cells draw from concentrated Asian manufacturing hubs. Single-source vulnerability in advanced biosensor arrays threatens production continuity for remote monitoring platforms. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-clinic telehealth platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where CE marking capabilities and FDA clearance histories create switching costs that lock hospital systems into established vendor relationships.
For Market Incumbents: Shield market position by deepening backward integration into sensor manufacturing and securing exclusive GPO contracts with metropolitan hospital systems. The emergence of low-cost Asian monitoring equipment threatens margin compression in standard tiers, making certification investment in Europe's MDR framework the priority defensive lever.
For New Entrants and Emerging Players: Differentiate on AI-enabled risk stratification algorithms that enable real-time exercise prescription adjustments during remote sessions. Japan's METI-supported digital health initiatives and Australia's rural telehealth expansion represent the most penetrable white-space targets, with software-as-medical-device regulatory pathways offering the clearest go-to-market angle.
For Investors and Strategic Acquirers: Europe's MDR implementation reshapes the acquisition landscape by elevating the value of established quality management systems and clinical validation databases. Long-term viability over the projection horizon favors targets with hybrid delivery platform capabilities spanning institutional and home settings. The signal to monitor is CMS reimbursement code expansion for remote cardiac rehabilitation sessions.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Europe's MDR framework extends timelines for algorithm-driven exercise tools, favoring incumbents with quality systems. |
| Hospital System Partnership | Integrated imaging-to-rehabilitation workflows lock institutional contracts through EHR interoperability and capital equipment bundling. |
| Software Companion Development | AI-enabled physiologic data analysis enables personalized exercise prescriptions that differentiate remote platforms from basic monitoring. |
| Reimbursement Strategy | CMS and statutory insurance coverage code expansion determines telehealth program viability and capital allocation between delivery models. |
| Platform Integration | Connected monitoring ecosystems spanning acute and ambulatory settings capture patient data continuity across care transitions. |
Research Methodology
The analysis maps hospital-based programs, telehealth platforms, home-based protocols, and community delivery models, each validated through cardiac rehabilitation program directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up enrollment volume estimates triangulated against top-down healthcare expenditure allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include program type, care setting, component category, and end-user clinical indication. CAGRs derived from patient volume trajectories, reimbursement rate evolution, and technology penetration curves. Forecast inputs incorporated percutaneous coronary intervention procedural volumes, aging demographic projections, and remote monitoring device adoption patterns.
Material uncertainties — regulatory reimbursement shifts, workforce pipeline constraints, interoperability standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions about payer site-of-service flexibility and MDR compliance cost absorption. Practitioners should keep alternative scenarios live as CMS coverage determinations and European notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Tachycardia Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Angina Market
Cardiovascular
Heart Health Products Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market