
 Ethanol Market | 2026-2036
Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Ethanol Market Intelligence
A wide capital-intensity gap between integrated agribusiness giants and standalone biorefiners is bifurcating competitive dynamics in ethanol production. Archer Daniels Midland leverages its grain origination network and captive corn supply to sustain processing margins across North American facilities. POET LLC anchors its position through enzymatic fermentation technology leadership and a dense footprint of Midwestern plants.
Ethanol denotes a volatile, flammable, colorless liquid with the chemical formula C₂H₅OH, typically produced via yeast fermentation of sugars from starch crops or cellulosic biomass at concentrations reaching 95% before dehydration. Its primary industrial purpose centers on oxygenate blending for gasoline octane enhancement and as a renewable transportation fuel precursor. Fuel ethanol dominates volume economics due to mandate-driven offtake, while pharmaceutical solvent applications command premium pricing through stringent purity requirements. Cellulosic production methods remain structurally nascent despite policy support, as enzymatic hydrolysis costs constrain scale economics relative to conventional fermentation pathways.
The US Environmental Protection Agency administers Renewable Fuel Standard volume obligations that directly determine domestic demand floors, while Brazil's ANP enforces RenovaBio carbon intensity targets that favor ethanol over fossil alternatives. REACH compliance in Europe restricts certain denaturant formulations, altering export product specifications for international suppliers. Stakeholders must monitor evolving lifecycle emissions accounting rules, as border-adjusted carbon thresholds will reshape competitive access for agriculturally derived versus cellulosic supply chains.
Market Dynamics
Regulatory mandate density is compressing competitive differentiation in ethanol, as the US EPA's Renewable Fuel Standard and Brazil's ANP carbon intensity targets convert policy floors into volume ceilings that homogenize offtake economics across conventional producers.
Growth Catalysts
- Transportation biofuel mandates:The US EPA administers Renewable Fuel Standard volume obligations that institutionalize gasoline blending floors, locking in baseline demand regardless of crude price volatility.
- RenovaBio carbon intensity targets:Brazil's ANP enforces lifecycle emissions scoring that structurally favors sugarcane ethanol over fossil alternatives, redirecting fuel distributor procurement toward certified low-carbon supply.
- São Paulo state production cluster:Brazil's Center-South region concentrates crushing capacity, logistics infrastructure, and technical expertise, generating feedstock cost advantages that propagate through export supply chains.
Market Restraints
- Corn price volatility:US ethanol margins compress when grain origination costs spike, exposing standalone biorefiners without captive supply to input cost squeezes that integrated agribusinesses absorb internally.
- Cellulosic enzymatic hydrolysis costs:Lignocellulosic feedstock conversion remains economically uncompetitive against starch fermentation, as enzyme loading rates and pretreatment energy requirements erode theoretical yield advantages.
- REACH denaturant restrictions:ECHA compliance mandates in Europe prohibit certain chemical formulations used in US fuel ethanol, forcing export product re-specification that fragments production runs and elevates compliance overhead.
Strategic Opportunities
- Sustainable aviation fuel precursors:Ethanol-to-jet processing pathways are attracting offtake commitments from airlines facing ICAO carbon offset obligations, opening premium pricing tiers beyond road fuel commoditization.
- Pharmaceutical solvent grade purity:USP-grade ethanol commands substantial price premiums through stringent water content and contaminant specifications, rewarding producers with distillation sophistication and quality certification infrastructure.
- Carbon capture and sequestration integration:Fermentation CO₂ capture qualifies for 45Q tax credits under the US IRA, enabling negative-emissions ethanol positioning that differentiates supply for California LCFS markets.
Industry Challenges
- Enzyme formulation expertise scarcity:Cellulosic pilot operations require specialized biochemists capable of optimizing cellulase cocktails for variable feedstock compositions, a talent pool concentrated at national laboratories and select agricultural universities.
- Multi-feedstock facility retooling:Biorefiners seeking operational flexibility face mechanical complexity in switching between corn, sorghum, and cellulosic inputs without yield degradation or equipment damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethanol Market |
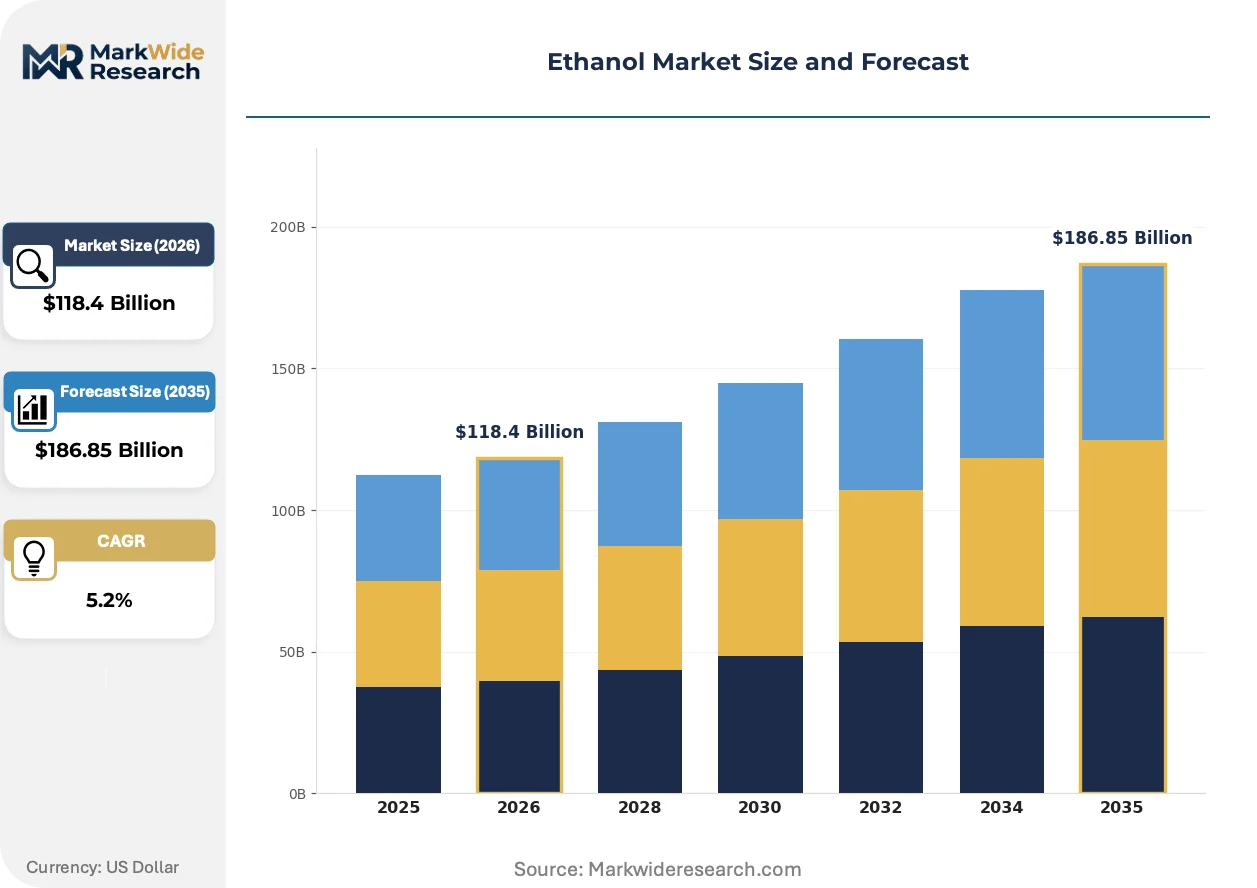
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $186.85 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Ethanol, Beverage Ethanol, Industrial Ethanol, Denatured Ethanol, Absolute Ethanol Application: Biofuel, Pharmaceutical Solvent, Personal Care, Food & Beverage, Chemical Intermediate Production Method: Fermentation, Synthetic, Cellulosic, Agriculturally Derived, Enzymatic End User Industry: Transportation, Pharmaceuticals, Cosmetics, Food Processing, Chemical Manufacturing |
| Companies Covered | Archer Daniels Midland, Green Plains Inc, Cargill, POET LLC, Valero Energy Corporation, Raízen, Cosan, Tereos, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethanol Market Strategic Shifts & Innovations
Process intensification and carbon accounting precision are redefining competitive advantage in ethanol production, as mechanical efficiency gains intersect with policy-driven emissions transparency requirements.
Consolidated bioprocessing technology is supplanting separate hydrolysis and fermentation steps in next-generation cellulosic facilities. Clostridium thermocellum and engineered yeast strains that simultaneously secrete cellulases and convert sugars to ethanol are entering pilot-scale validation. This consolidation collapses capital intensity and energy input requirements that have historically constrained cellulosic scale economics.
REACH authorization timelines are compressing denaturant formulation flexibility for European-bound exports. ECHA's restriction of certain gasoline additives forces US Gulf Coast producers to maintain parallel product streams, segmenting tankage and lengthening changeover intervals. Brazilian exporters to Europe have adapted faster due to existing anhydrous ethanol infrastructure that accommodates specification variance with lower retrofit burden.
Lifecycle emissions verification is reshaping procurement criteria for obligated parties under California's LCFS and Brazil's RenovaBio. Fuel distributors now require satellite-linked farm-level traceability and third-party certified carbon intensity scores, displacing commodity spot purchasing with contracted supply relationships anchored to verified sustainability attributes. This behavioral shift concentrates offtake among producers with integrated origination and audit infrastructure.
Ethanol Market Segmentation
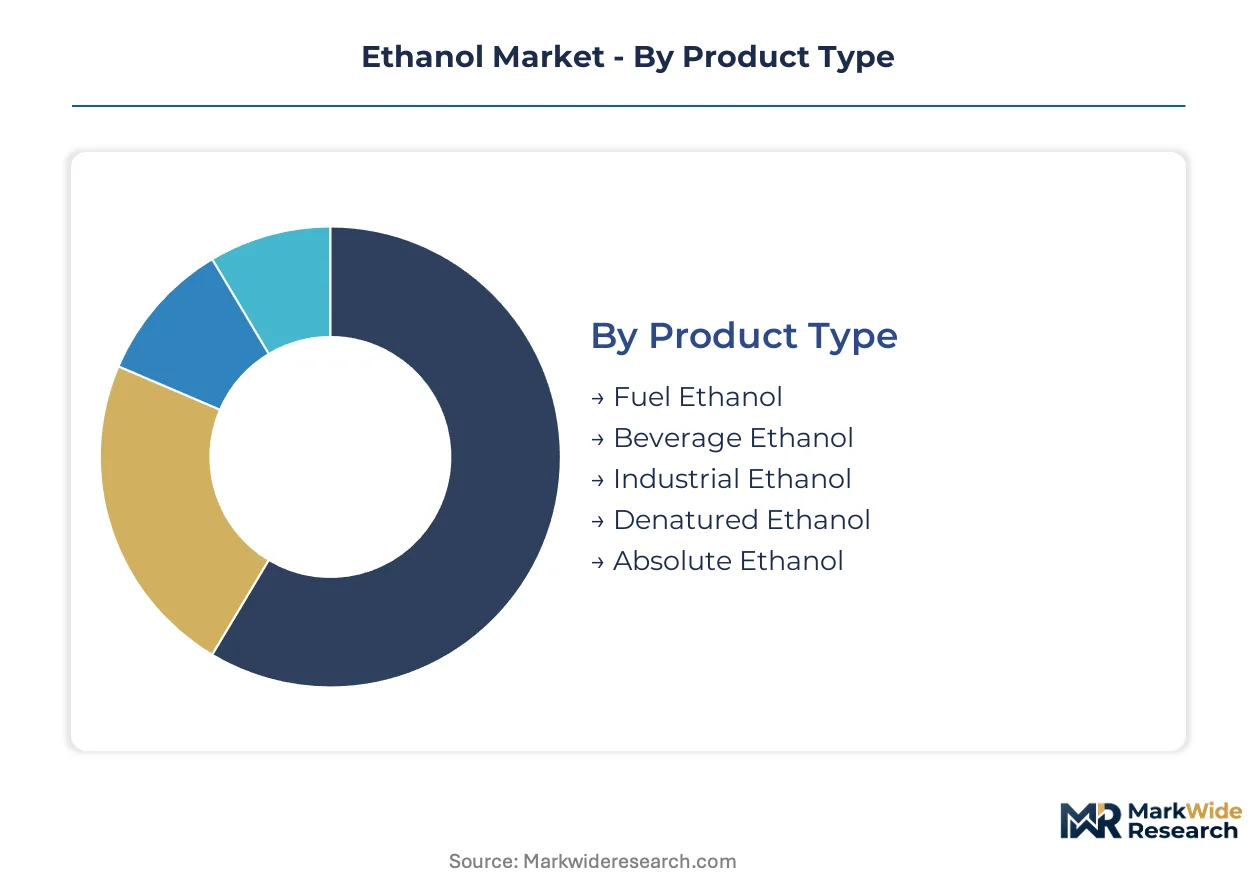
Ethanol demand bifurcates sharply between mandate-driven fuel blending and specification-sensitive industrial applications. Producers face divergent margin structures across these segments, with fuel volumes commoditized by policy floors while pharmaceutical and beverage grades command premiums through purity certification requirements.
Product Type:
Substitution pressure from electrification and alternative biofuels weighs most heavily on fuel-grade segments, while industrial and beverage grades maintain defensive positioning through specification barriers.
- Fuel Ethanol:Blended gasoline oxygenate at concentrations up to E85, produced via starch fermentation with denaturant additives preventing human consumption. Demand concentrates in Brazil's São Paulo state and the US Corn Belt, driven by EPA Renewable Fuel Standard volume obligations and Brazil's ANP carbon intensity targets that structurally favor ethanol over fossil alternatives.
- Industrial Ethanol:Solvent-grade product serving coatings, disinfectants, and chemical synthesis applications, typically supplied at 95% concentration with trace contaminant limits. Procurement clusters in Germany's chemical manufacturing corridor and US Gulf Coast petrochemical complexes, constrained by REACH denaturant restrictions that force export re-specification for European-bound supply.
- Beverage Ethanol:Neutral spirit meeting TTB and FDA purity standards for alcoholic beverage production, requiring organoleptic neutrality and methanol limits below specified thresholds.
- Denatured Ethanol:Fuel and industrial grades rendered unfit for consumption through gasoline or chemical additive incorporation, governed by TTB formulation approvals in the US.
- Absolute Ethanol:Water content below 0.5% achieved through azeotropic distillation or molecular sieve dehydration, serving pharmaceutical and laboratory applications with stringent moisture specifications.
Fuel ethanol anchors the volume base while industrial ethanol gains share at the steepest rate through solvent substitution in green chemistry applications.
Application:
Cost tier stratification separates commodity fuel blending from premium pharmaceutical and personal care specifications, with margin compression risk concentrated in the middle tier.
- Biofuel:Gasoline blending component providing octane enhancement and renewable content compliance, consumed primarily by obligated parties under US EPA and Brazil ANP regulatory frameworks. Volume economics dominate as mandates institutionalize baseline demand regardless of crude price volatility.
- Pharmaceutical Solvent:USP-grade ethanol for drug formulation and extraction, commanding substantial price premiums through water content specifications below 0.2% and comprehensive contaminant testing. Demand concentrates at FDA-regulated manufacturing facilities in New Jersey, North Carolina, and Switzerland's Basel region.
- Personal Care:Cosmetic-grade ethanol for fragrances, sanitizers, and skincare formulations, requiring odor neutrality and heavy metal limits enforced by FDA and EU Cosmetics Regulation.
- Food & Beverage:Flavor extraction and preservation applications governed by TTB and FDA food-grade specifications.
- Chemical Intermediate:Feedstock for ethylene, acetic acid, and derivative production, competing with petrochemical routes on carbon intensity metrics.
Biofuel applications absorb the majority of production volume while pharmaceutical solvent applications deliver the highest margin contribution per liter.
Production Method:
Technology maturity separates established starch fermentation from nascent cellulosic pathways, with capital intensity and yield economics determining competitive viability.
- Fermentation:Conventional yeast-based conversion of corn or sugarcane starches to ethanol, achieving theoretical yields of 90-95% with established enzyme and process technology. Dominates US and Brazilian production through POET LLC and Archer Daniels Midland facilities.
- Cellulosic:Lignocellulosic feedstock conversion via enzymatic hydrolysis and fermentation, remaining structurally uncompetitive due to pretreatment energy requirements and cellulase loading costs despite IRA policy support.
- Synthetic:Petrochemical ethylene hydration producing industrial ethanol, concentrated in Saudi Arabia and US Gulf Coast complexes with integrated olefin infrastructure.
- Agriculturally Derived:Starch or sugar crop fermentation encompassing corn, sugarcane, sorghum, and wheat feedstocks.
- Enzymatic:Advanced cellulase and amylase formulations enabling consolidated bioprocessing, currently pilot-scale with Clostridium thermocellum strains entering validation.
Fermentation methods retain volume dominance while cellulosic approaches expand most quickly through pilot-scale validation and policy-driven carbon intensity advantages.
End User Industry:
Customer concentration varies from fragmented cosmetics procurement to consolidated fuel distributor offtake, with contract structures reflecting buyer power asymmetries.
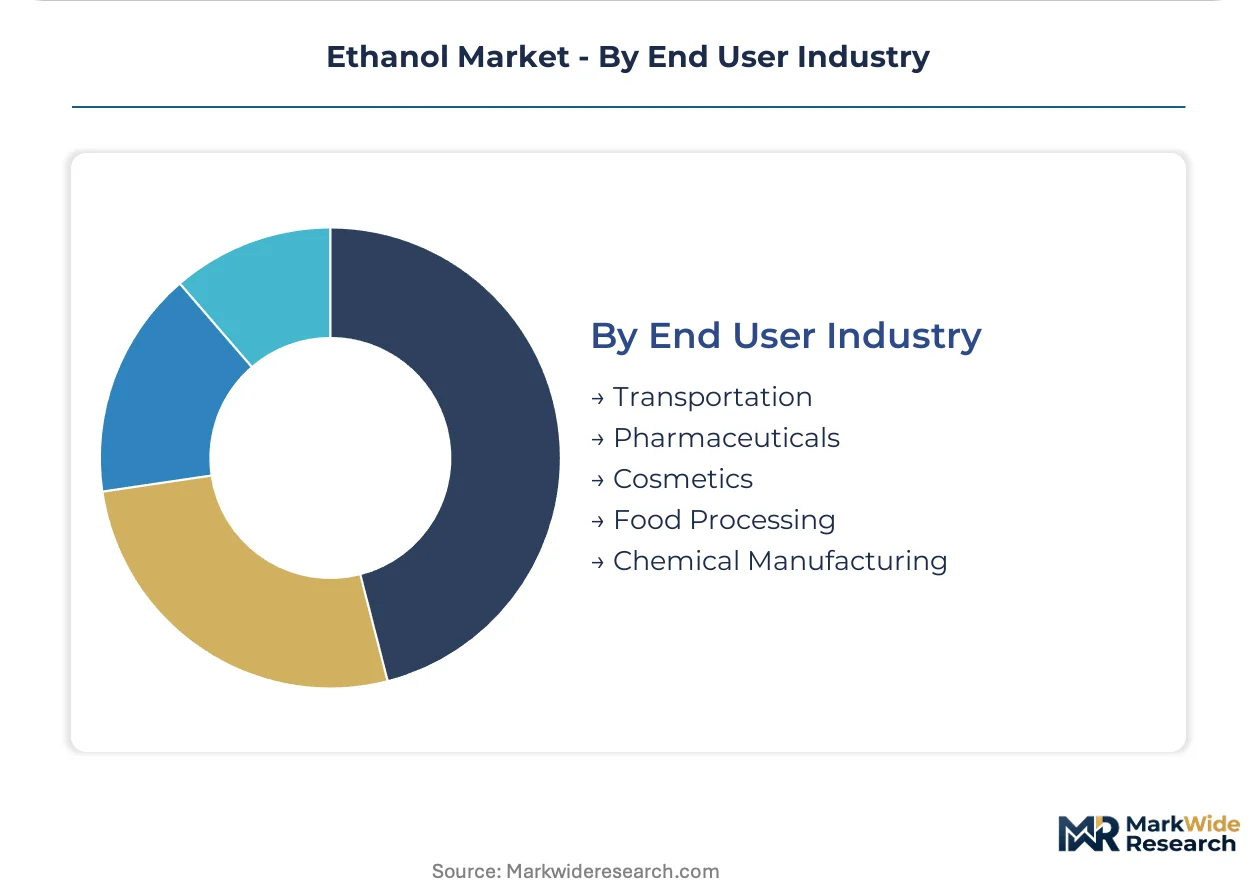
- Transportation:Fuel blenders and retailers meeting EPA Renewable Fuel Standard obligations or Brazil's RenovaBio carbon intensity targets, procuring through long-term contracts with satellite-linked farm traceability requirements. Demand concentrates at Valero, Marathon, and Raízen distribution networks.
- Pharmaceuticals:Drug manufacturers requiring USP-grade ethanol with batch certification and audit documentation, sourcing through qualified supplier relationships with distillation sophistication requirements.
- Cosmetics:Fragrance houses and personal care formulators with odor-specific and heavy metal specifications, procuring through regional distributors with formulation flexibility.
- Food Processing:Flavor extraction and preservation applications with FDA food-grade compliance requirements.
- Chemical Manufacturing:Ethylene and derivative producers with feedstock cost sensitivity and carbon accounting specifications.
Transportation sector procurement anchors volume commitments while pharmaceuticals delivers the steepest margin expansion trajectory through purity premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and the United States consume ethanol through fundamentally different fuel-blending architectures, while European and Asian markets prioritize industrial and pharmaceutical applications over transportation biofuel integration.
United States
Corn Belt biorefineries process over 90% of domestic ethanol volume, with Iowa and Illinois hosting the densest facility concentrations. EPA Renewable Fuel Standard volume obligations institutionalize baseline demand floors regardless of crude price movements. Valero Energy Corporation and Marathon Petroleum distribution networks anchor procurement concentration along Gulf Coast refining corridors.
Brazil
São Paulo state crushing mills supply the majority of Center-South ethanol output, with sugarcane harvest cycles dictating seasonal pricing patterns. ANP RenovaBio carbon intensity scoring structurally favors sugarcane ethanol over fossil alternatives in fuel distributor procurement decisions. Raízen operates integrated logistics infrastructure connecting production clusters to Atlantic export terminals.
Germany
Chemical manufacturing corridors along the Rhine concentrate industrial ethanol demand for coatings and disinfectant applications. ECHA REACH restrictions prohibit certain denaturant formulations common in US fuel ethanol, forcing import re-specification. BASF and Covestro facilities in Ludwigshafen and Leverkusen anchor pharmaceutical-grade solvent procurement clusters.
China
Shandong and Henan provinces host the majority of domestic starch-ethanol fermentation capacity, with sorghum and wheat supplementing corn feedstocks. MIIT industrial policy targets cellulosic ethanol commercialization through state-backed demonstration projects. State-owned energy groups coordinate blending mandates in coastal provinces with petroleum distribution control.
India
Maharashtra and Uttar Pradesh sugar mills are retooling for ethanol production under the national biofuel blending program. FSSAI and BIS specifications govern potable and industrial grades separately from fuel applications. Reliance Industries and Indian Oil Corporation offtake agreements are concentrating supply relationships around verified feedstock traceability.
Ethanol Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with agribusiness conglomerates commanding origination economics and standalone biorefiners competing on processing efficiency. Archer Daniels Midland and Cargill leverage captive grain supply and logistics networks to compress input costs, while POET LLC and Green Plains Inc anchor positions through enzymatic technology and geographic density. Strategic differentiation is concentrating around carbon capture integration and sustainable aviation fuel precursor positioning, with M&A activity targeting cellulosic technology access and long-term offtake contracting.
Within the integrated agribusiness tier, Archer Daniels Midland and Cargill exemplify backward integration into captive corn origination, while POET LLC occupies a position as the largest standalone biorefiner with Midwestern facility density. Raízen anchors the Brazilian market through sugarcane milling and fuel distribution integration. These three companies represent divergent archetypes: grain-trading conglomerates with processing arms, pure-play fermentation specialists, and crop-to-pump vertical integrators.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Green Plains Inc |
| Cargill |
| POET LLC |
| Valero Energy Corporation |
| Raízen |
| Cosan |
| Tereos |
| BP |
| Others |
Cost & Logistics Intelligence
Sixty-day inventory cycles at US Gulf Coast terminals compress margin buffers for exporters facing European REACH re-specification requirements, concentrating pricing power among integrated producers with captive tankage and parallel product streams.
Pricing Analysis
Long-term offtake contracts dominate fuel-grade procurement under EPA Renewable Fuel Standard obligations, locking in volume commitments regardless of crude price movements. Price differentiation separates USP-grade pharmaceutical ethanol from fuel blending grades through water content specifications and contaminant testing protocols. Cost compression in fuel-grade segments is intensifying because corn price volatility squeezes standalone biorefiners without captive grain supply. Obligated parties under Brazil's RenovaBio program exhibit lowest price sensitivity due to carbon intensity scoring requirements, while industrial solvent buyers in Europe face highest sensitivity to specification-driven reformulation costs.
Supply Chain Analysis
Port congestion at Santos and Houston anchors inbound logistics costs for Brazilian sugarcane ethanol and US corn-ethanol export flows, elevating working capital requirements for distributors managing trans-Atlantic delivery windows. Feedstock supply draws from Iowa and Illinois corn belts, São Paulo state sugarcane crushing clusters, and Shandong province starch-ethanol facilities. Single-source vulnerability concentrates in enzymatic fermentation technology licensing, where POET LLC and select agricultural universities control specialized cellulase optimization expertise. Distribution runs through Raízen's Atlantic terminal network, Valero's Gulf Coast refining corridors, and Archer Daniels Midland's river barge systems connecting Midwestern plants to coastal export points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across carbon intensity verification tiers creates niche positioning opportunities as fuel distributors displace commodity spot purchasing with contracted supply relationships anchored to satellite-linked farm traceability.
For Market Incumbents: Fortify origination infrastructure through backward integration into captive corn supply or sugarcane milling partnerships, insulating processing margins from feedstock price spikes that compress standalone biorefiner economics. Prioritize carbon capture and sequestration integration to qualify for 45Q tax credits and differentiate supply for California LCFS markets where negative-emissions positioning commands premium access. For New Entrants and Emerging Players: California LCFS certification fast-track offers the most penetrable entry point for cellulosic ethanol producers, as enzymatic hydrolysis cost barriers constrain incumbent scale expansion. Target sustainable aviation fuel precursor offtake commitments from airlines facing ICAO carbon offset obligations, leveraging ethanol-to-jet processing partnerships with existing biorefiners rather than greenfield capacity builds. For Investors and Strategic Acquirers: Long-term, this sits as a policy-anchored infrastructure play because EPA and ANP mandate structures institutionalize baseline demand floors regardless of energy transition pace. Acquisition targets should prioritize cellulosic technology access and integrated origination-audit infrastructure. The signal to watch is border-adjusted carbon threshold adoption in European markets, which would reshape competitive access for agriculturally derived versus cellulosic supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | 45Q tax credit qualification enables negative-emissions positioning for California LCFS premium access. |
| Cellulosic Technology Licensing | Consolidated bioprocessing partnerships collapse capital intensity barriers constraining next-generation scale economics. |
| Long-term Supply Contracting | RenovaBio and EPA mandate structures institutionalize offtake floors through obligated party procurement obligations. |
| Backward Integration into Feedstock | Captive corn origination or sugarcane milling partnerships compress input costs versus standalone biorefiner exposure. |
| Sustainable Aviation Fuel Partnership | Ethanol-to-jet processing commitments from airlines facing ICAO obligations open premium pricing beyond road fuel commoditization. |
Research Approach
A spread of perspectives from biorefiner operations managers, grain origination specialists, fuel distributor procurement leads, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA Renewable Fuel Standard docket filings, ANP RenovaBio certification databases, ECHA REACH restriction updates, and customs trade flow records. Bottom-up facility capacity tallies triangulated against top-down mandate volume obligations to constrain estimation variance across the analysis window.
Segmentation dimensions modeled include fuel grade versus industrial versus pharmaceutical purity tiers, starch fermentation versus cellulosic production methods, and transportation versus chemical intermediate versus solvent end-use applications. CAGRs were derived from elasticity-adjusted demand projections tied to EPA and ANP regulatory obligation schedules, corn and sugarcane feedstock cost trajectories, and carbon intensity scoring adoption curves. Industry-specific forecast inputs encompass enzyme loading rate improvements and satellite-linked farm traceability penetration rates.
Decision-makers should treat outputs as directional under prevailing EPA volume obligation schedules and ANP carbon intensity scoring frameworks; material deviation in mandate stringency or border-adjusted carbon threshold adoption would warrant model refresh. Practitioners should keep alternative scenarios live as lifecycle emissions accounting rules and enzymatic hydrolysis cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Hard Kombucha Market