
 Wine Production Machinery Market | 2026-2036
Wine Production Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Production Machinery Market Analytics
Subscription-based predictive maintenance for fermentation tanks is broadening what wineries purchase beyond capital equipment. Bucher Vaslin SA leverages its French heritage to dominate premium press technology for estate wineries. Krones AG anchors global bottling line integration with end-to-end automation architectures. GEA Group AG specializes in hygienic process engineering that sustains margin pools in aseptic filling segments.
Wine production machinery encompasses the engineered equipment systems that transform harvested grapes into finished wine through controlled crushing, pressing, fermentation, clarification, and packaging operations, typically constructed from 304 or 316 stainless steel with temperature control precision within 0.5 degrees Celsius to ensure microbial stability and phenolic extraction consistency. Fermentation tanks represent the largest installed base segment due to universal winery demand, while automated bottling lines capture the fastest expansion as labor scarcity intensifies across Mediterranean and New World wine regions. Digital technology segments command premium pricing through IoT-enabled must analysis and remote tank monitoring, whereas traditional equipment retains cost-sensitive vineyard and DIY application share.
FDA regulations govern sanitary design standards for wine exported to the United States, while EU Green Deal carbon accounting rules and REACH chemical compliance frameworks reshape material specifications and water recycling requirements for machinery sold across European markets. CE marking mandates mechanical safety and electromagnetic compatibility certification for all equipment placed within the European Economic Area. Stakeholders must weigh automation capex against opex savings as energy efficiency standards tighten and skilled cellar labor becomes scarcer in established winegrowing belts.
Market Dynamics
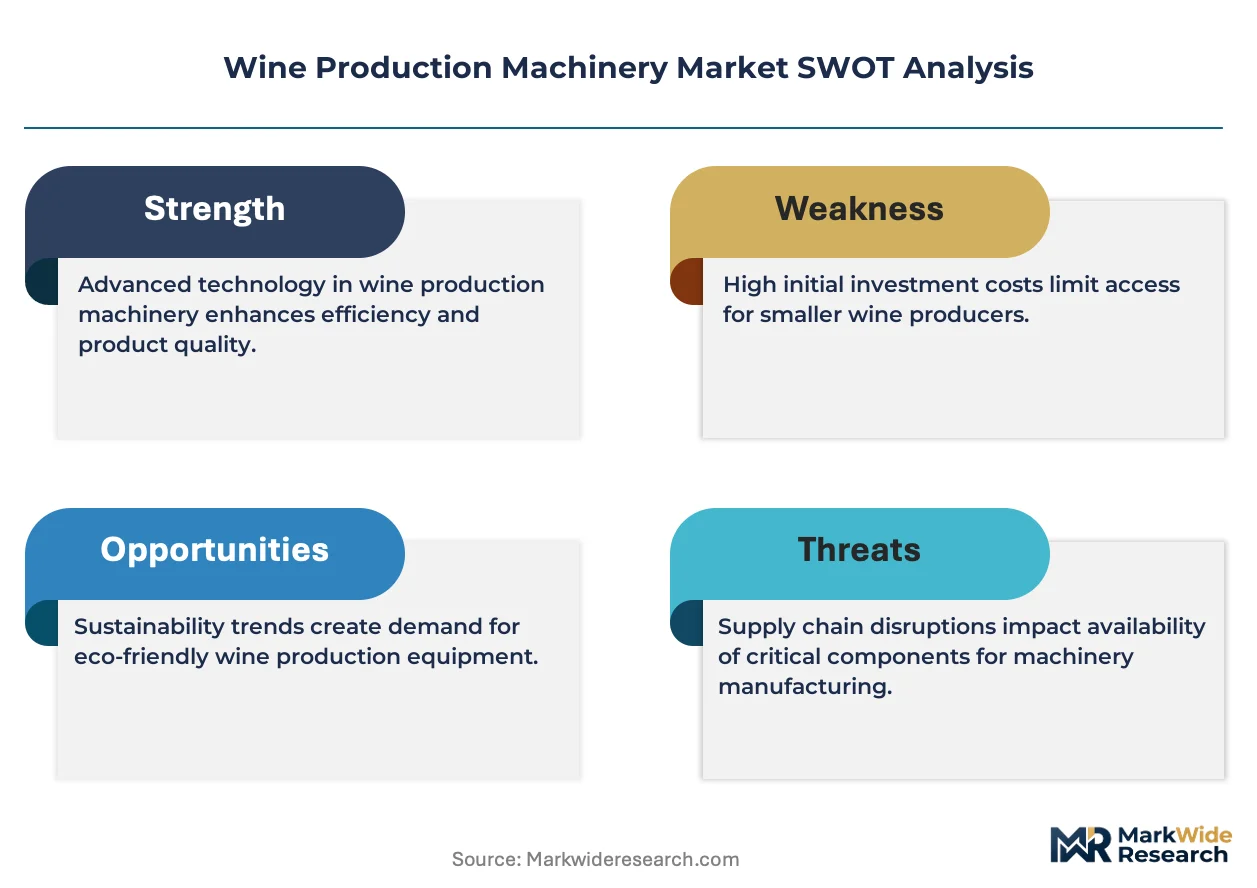
EU Green Deal carbon accounting mandates and water reuse requirements are compressing equipment replacement cycles across fermentation and pressing stages, forcing wineries to retire functional but non-compliant machinery ahead of depreciation schedules.
Growth Catalysts
- EU Green Deal water reuse mandates:European wineries must install closed-loop filtration systems, creating replacement demand for legacy open-vat fermentation equipment.
- Labor scarcity in Mediterranean regions:Declining cellar worker availability across Italy, Spain, and France accelerates adoption of automated crusher-destemmer systems.
- Terroir-preservation technology:Precision temperature control within 0.5 degrees Celsius enables estate wineries to scale output without compromising phenolic extraction consistency.
Market Restraints
- Stainless steel price volatility:304 and 316 grade input costs fluctuate with nickel and molybdenum commodity markets, squeezing fabrication margins.
- Specialized component supply concentration:Precision temperature control systems and hygienic pumps concentrate among German and Italian subsystem suppliers.
- REACH chemical compliance friction:ECHA substance restrictions on certain sealants and coatings extend equipment qualification timelines.
Strategic Opportunities
- Subscription predictive maintenance:IoT-enabled tank monitoring creates recurring revenue streams beyond capital equipment sales.
- New World winery automation gaps:Chilean and Argentine estates present underpenetrated demand for integrated bottling line architectures.
- CE marking convergence with FDA standards:Dual-certification equipment commands premium positioning for export-oriented wineries.
Industry Challenges
- Electromechanical technician shortage:Automated bottling lines require specialized maintenance skills scarce in rural winegrowing belts.
- Legacy system integration complexity:Digital monitoring retrofitting onto existing fermentation tanks demands custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Production Machinery Market |
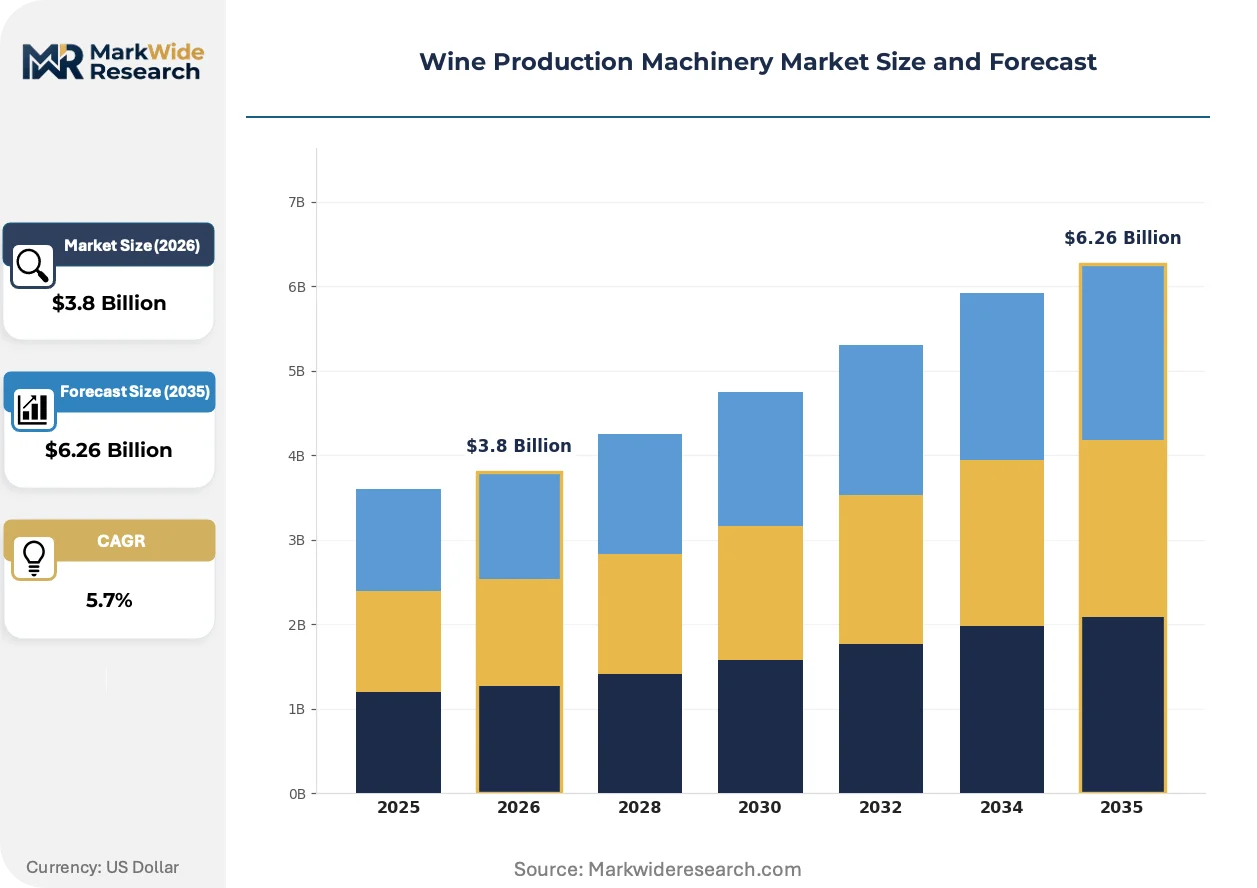
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
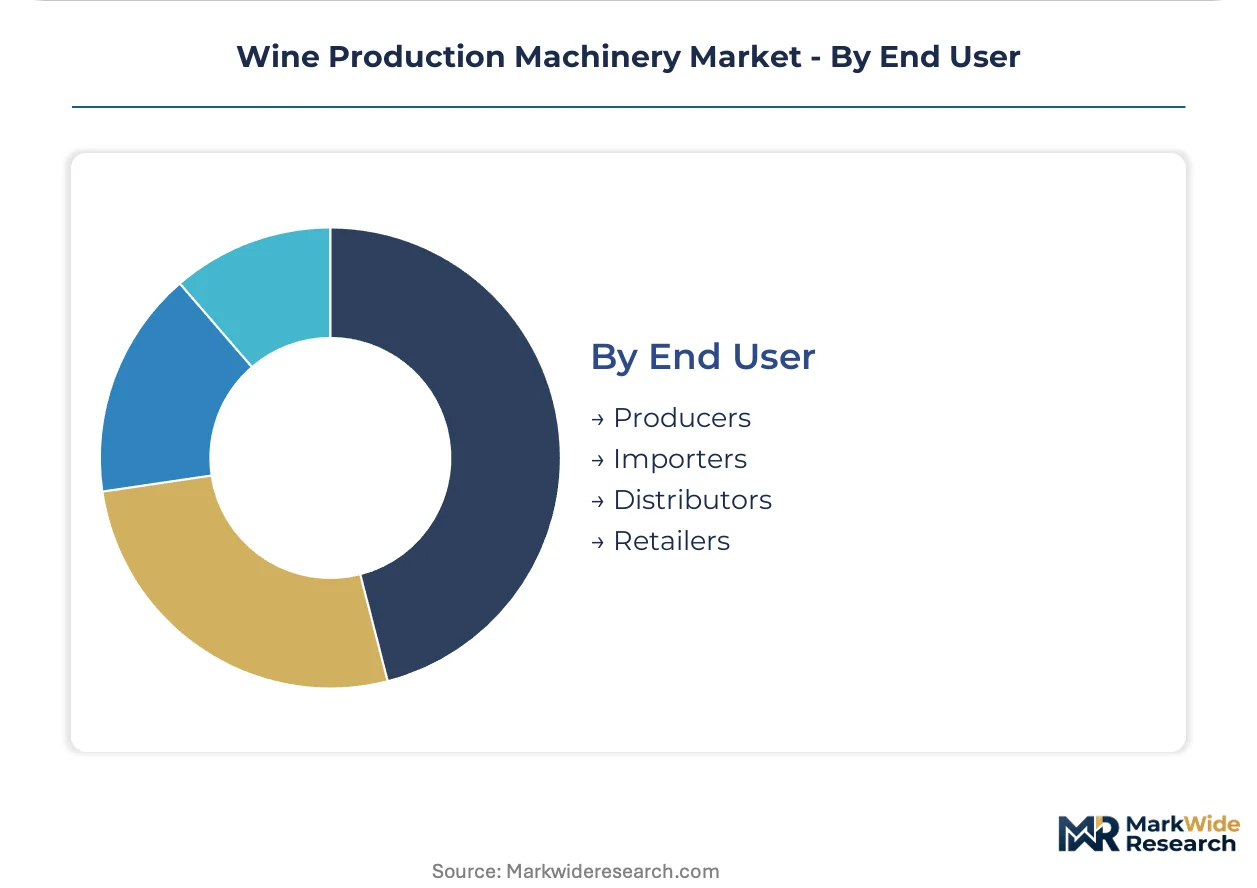
| Segmentation | Product Type: Crushers, Presses, Fermentation Tanks, Bottling Machines Technology: Traditional, Automated, Semi-Automated, Digital Application: Commercial, DIY, Vineyard, Winery End User: Producers, Importers, Distributors, Retailers |
| Companies Covered | Bucher Vaslin SA, Krones AG, GEA Group AG, Alfa Laval AB, JBT Corporation, Criveller Group, Agrovin, Pellenc Group, Della Toffola Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Production Machinery Market Evolving Landscape
Digital instrumentation is collapsing the traditional separation between production equipment and quality assurance systems, embedding sensors directly into crushing, pressing, and fermentation stages for real-time must analysis.
Hyperspectral imaging integrated into optical grape sorters is unifying harvest reception and quality control functions. Premium estate wineries in Napa Valley and Bordeaux deploy these systems to remove compromised fruit before crushing. This convergence is compressing the boundary between vineyard management and cellar operations, forcing equipment suppliers to coordinate with precision agriculture platforms.
REACH chemical compliance frameworks are mandating substitution of certain elastomer sealants and coating compounds in equipment contacting must and wine. Machinery fabricators reformulate material specifications and requalify hygienic designs. Small French and Italian equipment builders face disproportionate testing burdens relative to integrated multinationals with dedicated regulatory affairs teams.
After-sales service unbundling is accelerating as wineries separate maintenance contracts from original equipment purchases. Third-party technical service providers in Australia and California now compete directly with manufacturer-affiliated technicians. This fragmentation is most pronounced among mid-sized cooperatives seeking to reduce total cost of ownership on automated bottling lines.
Wine Production Machinery Market Segmentation
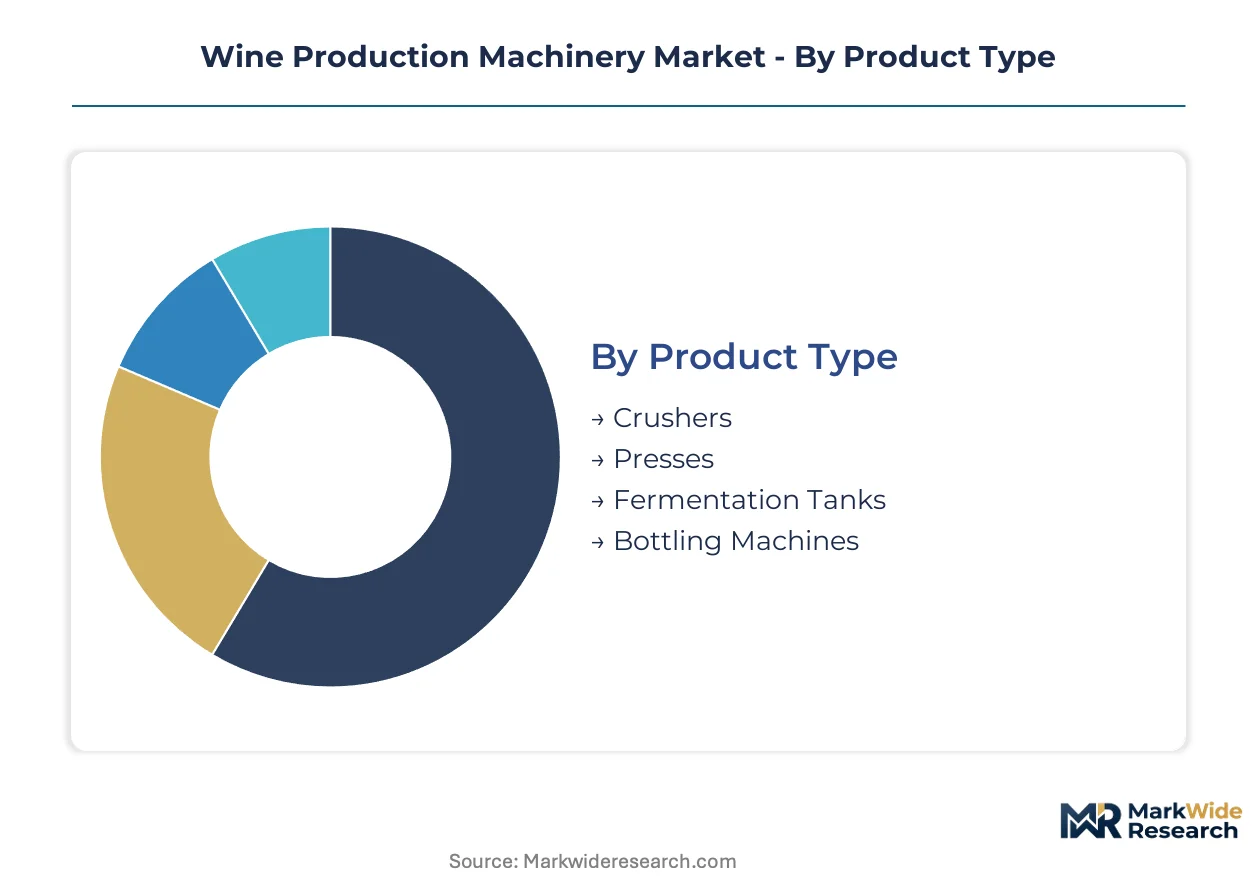
Equipment segmentation in wine production machinery reveals how capital deployment priorities diverge between estate wineries scaling terroir-driven output and bulk producers optimizing unit economics. Technical specifications, automation levels, and end-use applications each create distinct margin pools and competitive dynamics across the value chain.
Product Type:
Supply concentration among specialized fabricators in Germany and Italy shapes availability and lead times for precision-engineered components across all four equipment categories.
- Fermentation Tanks:Constructed from 304 or 316 stainless steel with temperature control precision within 0.5 degrees Celsius to ensure microbial stability and phenolic extraction consistency. Estate wineries in Napa Valley and Bordeaux prioritize these systems to preserve terroir integrity while scaling output. Fermentation tanks absorb the bulk of installed capacity; digital-enabled tank monitoring is expanding most quickly.
- Bottling Machines:Integrated automated lines handle rinsing, filling, corking, capping, and labeling with end-to-end synchronization. Labor scarcity across Mediterranean regions accelerates replacement of manual bottling operations with continuous-flow architectures.
- Crushers:Crusher-destemmer systems process harvested grapes through adjustable roller configurations that separate berries from stems while minimizing seed fracture. Demand concentrates in automated variants as cellar labor costs climb in traditional winegrowing belts.
- Presses:Pneumatic and basket press technologies extract juice through controlled pressure application, with Bucher Vaslin SA dominating premium press specifications for estate wineries leveraging French heritage positioning.
Fermentation tanks command the largest replacement cycles; bottling machines face the steepest automation-driven upgrade pressure.
Technology:
Cost tier differentiation separates capital-intensive digital installations from maintenance-focused traditional equipment, with semi-automated systems capturing mid-sized cooperative demand.
- Digital:IoT-enabled must analysis and remote tank monitoring embed sensors directly into production stages for real-time quality assurance. Premium estate wineries deploy these systems to collapse the traditional separation between equipment and laboratory functions. Digital technology commands premium pricing through predictive maintenance subscriptions that create recurring revenue beyond capital sales.
- Automated:Fully integrated control systems manage crushing, pressing, fermentation, and packaging with minimal operator intervention. New World wineries in Chile and Argentina present underpenetrated demand for these architectures.
- Semi-Automated:Hybrid configurations retain manual oversight for critical quality decisions while automating repetitive material handling tasks. Mid-sized cooperatives in Spain and Italy favor this tier to balance labor reduction against capital constraints.
- Traditional:Mechanical systems without electronic control modules serve cost-sensitive vineyard operations and DIY enthusiasts. This segment retains share in emerging wine regions where technical service infrastructure remains undeveloped.
Traditional equipment maintains installed base dominance in rural winegrowing belts; digital systems are gaining share fastest among export-oriented estates.
Application:
Volume concentration among commercial wineries creates procurement scale advantages that reshape supplier relationships and service bundling practices.
- Commercial:Large-scale production facilities processing volumes exceeding 500,000 cases annually demand continuous-operation equipment with redundant systems and rapid-changeover capabilities. These operations drive standardization pressures across supplier engineering teams.
- Winery:Estate-based operations integrating vineyard and cellar functions under single ownership prioritize equipment that preserves stylistic consistency across vintage variation. Precision temperature control and gentle handling specifications dominate procurement criteria.
- Vineyard:Grower-producers selling bulk wine or grapes require portable, multi-purpose equipment adaptable to varying harvest conditions. Mobile crusher-destemmer units serve this segment with trailer-mounted configurations.
- DIY:Hobbyist and small-batch producers operate manual or minimally automated systems with capacity below 1,000 cases. Price sensitivity and simplicity requirements limit supplier margins in this tier.
Commercial applications anchor equipment revenue; winery applications are climbing the fastest as estate branding intensifies.
End User:
Customer type fragmentation across the value chain creates divergent service expectations, with producers demanding technical integration and retailers prioritizing packaging flexibility.
- Producers:Winemaking operations from estate boutiques to bulk cooperatives purchase equipment as capital assets with depreciation schedules tied to harvest cycles. These buyers negotiate service contracts and spare parts availability as critical procurement terms.
- Distributors:Logistics intermediaries handling bulk wine transport and storage require flexible filling and packaging equipment to accommodate varied client specifications and container formats.
- Importers:Cross-border traders sourcing finished wine or bulk shipments for domestic bottling invest in laboratory and quality control equipment to verify compliance with destination market regulations including FDA sanitary design standards.
- Retailers:Private label and direct-to-consumer wine merchants purchase small-scale bottling and labeling systems for contract packaging operations, prioritizing rapid format changeover over throughput maximization.
Producers represent the core equipment demand base; distributor investment in flexible packaging systems is accelerating most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wine production machinery demand concentrates in established winegrowing belts where terroir-driven estate expansion meets regulatory pressure on water and energy use. Equipment procurement patterns diverge sharply between Old World compliance retrofit cycles and New World greenfield automation investments.
France
Estate wineries in Bordeaux and Champagne drive demand for precision fermentation tanks with 0.5-degree Celsius temperature control. EU Green Deal carbon accounting mandates accelerate replacement of legacy open-vat equipment. Bucher Vaslin SA anchors premium press supply from its French manufacturing base.
Italy
Cooperative wineries in Piedmont and Veneto prioritize semi-automated crusher-destemmer systems as cellar labor availability declines. REACH chemical compliance frameworks force reformulation of elastomer sealants in equipment contacting must. Fabrication clusters in Emilia-Romagna concentrate hygienic pump subsystem supply.
United States
Napa Valley boutique wineries expand automated bottling lines to preserve terroir integrity while scaling output. FDA sanitary design standards govern equipment specifications for export-bound production. Third-party technical service providers in California now compete directly with manufacturer-affiliated maintenance contracts.
Germany
Precision temperature control system suppliers concentrate fabrication in Baden-Württemberg and Bavaria. CE marking mandates mechanical safety certification for equipment placed throughout the European Economic Area. Krones AG anchors integrated bottling line architectures from its German engineering base.
Spain
Labor scarcity across La Rioja and Catalonia accelerates adoption of automated material handling equipment. Water reuse mandates under EU Green Deal directives compress replacement cycles for fermentation infrastructure. Mid-sized cooperatives favor hybrid semi-automated configurations to balance capital constraints against throughput needs.
Wine Production Machinery Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through heritage engineering and integrated automation architectures, while mid-cap specialists occupy niche fabrication segments. The vendor base stratifies across three functional tiers: multinational system integrators commanding end-to-end bottling lines, regional stainless steel fabricators serving estate winery specifications, and component specialists concentrating precision subsystems. Competitive moves concentrate on geographic expansion into underpenetrated New World markets and service unbundling to capture recurring maintenance revenue.
Among European heritage engineering groups, Bucher Vaslin SA exemplifies premium press technology positioning rooted in French winemaking tradition. Krones AG and GEA Group AG occupy the integrated-systems tier, with the former representing end-to-end bottling automation and the latter anchoring hygienic process engineering for aseptic applications. These three entities collectively illustrate how competitive positioning in wine production machinery derives from technical specialization depth rather than scale alone.
| Leading Market Players |
|---|
| Bucher Vaslin SA |
| Krones AG |
| GEA Group AG |
| Alfa Laval AB |
| JBT Corporation |
| Criveller Group |
| Agrovin |
| Pellenc Group |
| Della Toffola Pacific |
| Others |
Value Network & Pricing Analysis
Stainless steel grade 304 and 316 input costs trace directly from nickel and molybdenum commodity markets through fabrication margins to final equipment pricing tiers, with European estate wineries absorbing premium positioning while emerging-region cooperatives face compressed procurement budgets.
Pricing Analysis
Cost-down pressure on mid-tier equipment accelerates because REACH chemical compliance extends qualification timelines and testing burdens for smaller fabricators. Three-tier pricing structure across premium, standard, and economy levels separates CE-FDA dual-certified systems from single-market equipment and basic mechanical configurations. Price differentiation hinges on IoT-enabled predictive maintenance bundling and precision temperature control certification. Bulk cooperatives in Spain and Italy exhibit highest price sensitivity; Napa Valley estate wineries prioritize terroir-preservation specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for precision temperature control systems and hygienic pumps now dominate procurement protocols as wineries mitigate single-source vulnerability. Fabrication concentrates in Germany, Italy, and France, with Baden-Württemberg and Emilia-Romagna anchoring subsystem supply. Raw material dependencies span nickel-alloy stainless steel, specialized elastomer sealants, and precision sensor arrays. Tariff exposure on Chinese electronic components presents structural risk. Distribution runs through manufacturer-direct channels for large estates and regional distributor networks for mid-sized cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled tank monitoring is displacing legacy manual cellar operations, compressing the traditional separation between production equipment and quality assurance functions across estate and commercial wineries alike.
For Market Incumbents: Anticipate margin compression from third-party technical service providers in California and Australia by deepening aftermarket control through captive predictive maintenance platforms. Backward integration into precision sensor manufacturing reduces exposure to German and Italian subsystem supplier concentration. CE-FDA dual-certification investment defends premium positioning against regional fabricators lacking regulatory affairs scale.
For New Entrants and Emerging Players: Capture automation gaps among Chilean and Argentine estates where integrated bottling line penetration remains underdeveloped relative to Mediterranean benchmarks. Mobile crusher-destemmer configurations for vineyard grower-producers present accessible entry points with lower capital barriers. Subscription-based remote monitoring services offer recurring revenue models distinct from capital-intensive equipment sales.
For Investors and Strategic Acquirers: EU Green Deal water reuse mandate enforcement is the leading indicator that replacement cycle acceleration will sustain equipment demand beyond traditional depreciation schedules. Acquisition targets should prioritize mid-cap fabricators with hygienic process engineering capabilities and established CE marking pathways. Watch for consolidation signals when REACH compliance testing burdens force smaller French and Italian builders toward strategic exit.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Subscription revenue from IoT-enabled tank monitoring creates recurring income beyond capital equipment sales for fermentation infrastructure providers. |
| Dual-Certification Investment | CE-FDA aligned equipment specifications capture premium positioning among export-oriented wineries in Napa Valley and Bordeaux. |
| Backward Integration into Sensor Manufacturing | In-house production of precision temperature control components reduces dependency on concentrated German subsystem suppliers. |
| Geographic Expansion into South America | Chilean and Argentine greenfield winery investments present underpenetrated demand for automated bottling line architectures. |
| Service Unbundling and Third-Party Competition | Independent technical providers in Australia and California fragment aftermarket revenue pools previously captured by manufacturer-affiliated technicians. |
Research Methodology
Document review covered trade association filings, EU regulatory databases, and customs records, complemented by interviews with winery operations directors, equipment procurement managers, and aftermarket service heads. Primary fieldwork engaged fermentation specialists at estate wineries in France and the United States, alongside fabrication engineers at German and Italian subsystem suppliers. Secondary validation drew from SEC filings of listed machinery vendors, REACH substance restriction updates, and FDA sanitary design guidance documents. Bottom-up equipment shipment data triangulated against top-down winery capital expenditure surveys.
Cross-referencing historical replacement cycle patterns with panel input from winery finance officers established the analytical framework across the projection horizon. Segmentation modeling spanned equipment type, automation technology tier, and end-use application scale. CAGRs derived from vintage-adjusted capacity expansion rates and regulatory-driven equipment retirement schedules. Forecast inputs incorporated EU Green Deal implementation timelines and labor scarcity indices across Mediterranean winegrowing regions.
The model holds under stable nickel alloy pricing and gradual REACH enforcement; deviation in commodity volatility or accelerated ECHA substance restrictions would shift the outlook materially. Forecasts reflect documented assumptions regarding winery automation adoption curves and regulatory compliance deadlines. Specific risk factors include electromechanical technician shortages in rural winegrowing belts and legacy system integration complexity for digital retrofitting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Australia and New Zealand Tequila Market