
 Middle East and Africa Wine Market | 2026-2036
Middle East and Africa Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Wine Market Foresight
South African vineyard operators is consolidating around estate-level production to secure grape supply for premium labels. Distell Group Holdings anchors the domestic market through its control of heritage brands and distillation infrastructure. Castel Group leverages its North African bottling networks to compete across Morocco and Tunisia. Treasury Wine Estates positions its Penfolds portfolio in Gulf duty-free channels, targeting transit retail consumers in Dubai and Abu Dhabi.
Wine denotes fermented grape juice typically containing 12-15% alcohol by volume, produced through controlled yeast conversion of sugars followed by aging in stainless steel tanks or oak barrels for flavor development. Red Wine commands the largest volume share across the Middle East and Africa, though Sparkling Wine generates disproportionate margin in Gulf hospitality settings. Online Retail channels are expanding fastest in South Africa and Nigeria, while Supermarkets remain the dominant route for Economy and Mid-Range tiers across North Africa.
South Africa's Wine and Spirit Board enforces origin certification and production standards that shape export eligibility for regional producers. The UAE's strict alcohol licensing framework administered by individual emirate authorities limits on-premise distribution and shapes channel strategy for inbound suppliers. Saudi Arabia maintains complete prohibition, creating supply diversion into neighboring Bahrain and Qatar markets. Stakeholders must monitor licensing liberalization signals in Gulf Cooperation Council jurisdictions to time market entry investments.
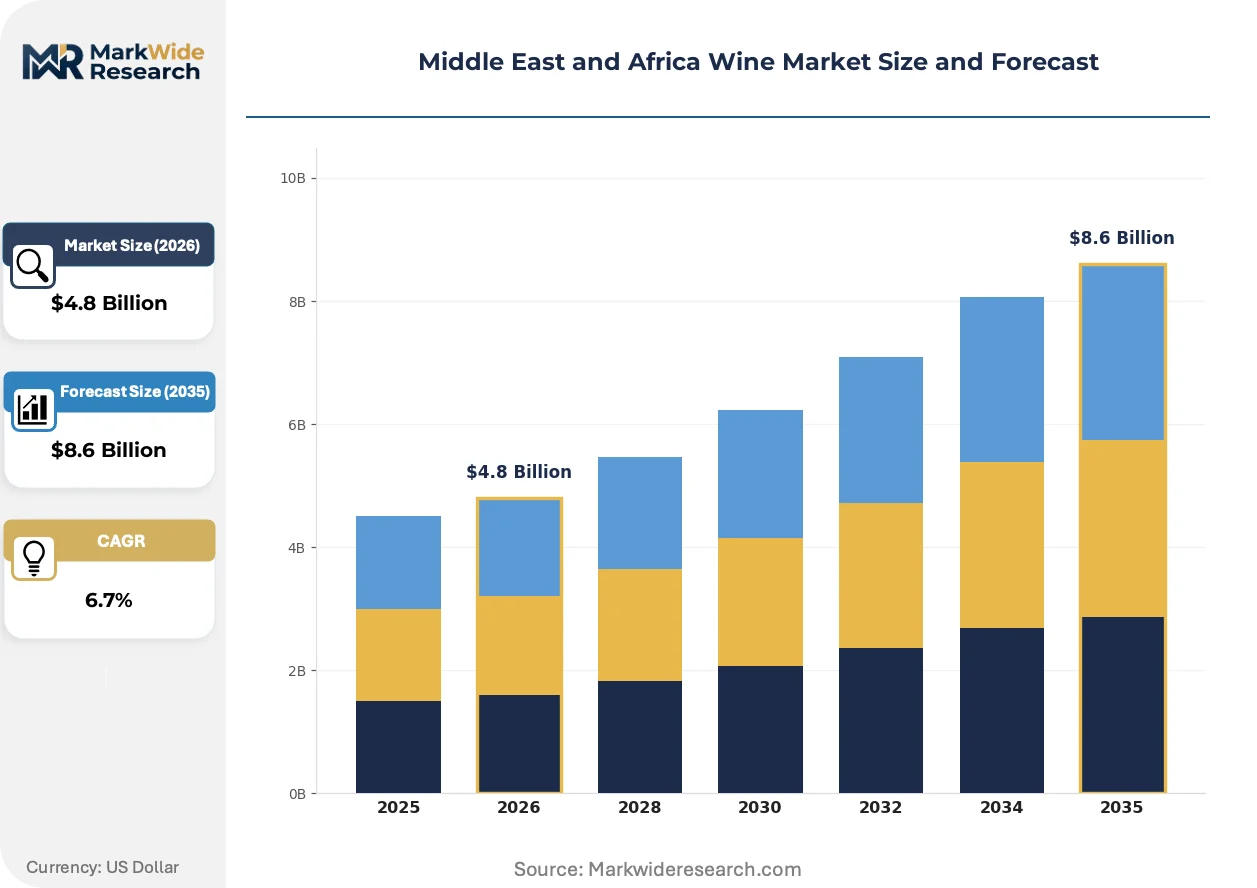
Market Dynamics
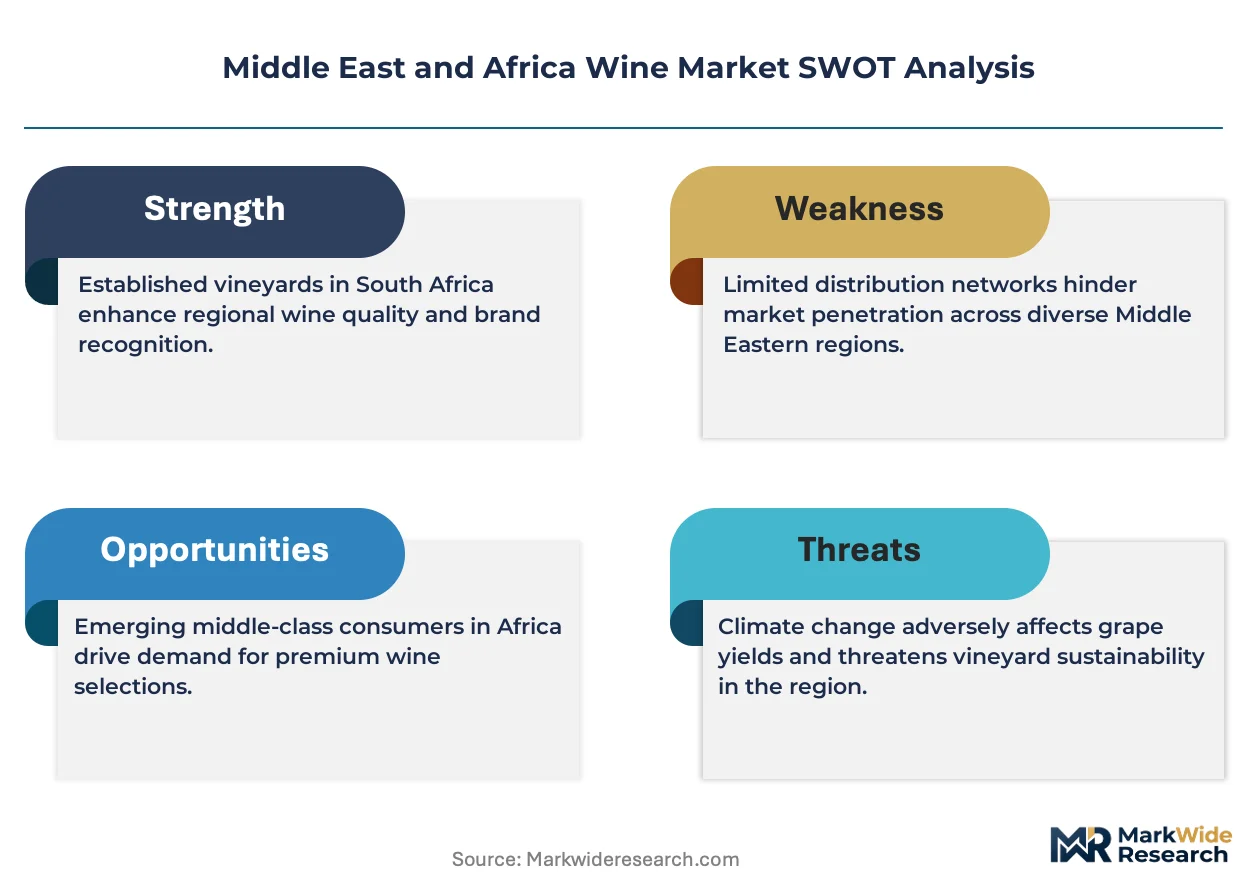
Consolidation among South African vineyard estates is tightening grape supply chains for premium label production, while Gulf licensing fragmentation forces suppliers to navigate emirate-specific distribution frameworks that reshape market entry economics.
Growth Catalysts
- Tourism-driven hospitality expansion:Dubai and Cape Town luxury hotels are enlarging wine programs to capture international visitor spend, directly lifting on-premise volume.
- South Africa's Wine and Spirit Board certification:Mandatory origin and production standards create export-ready quality tiers that unlock European and Asian market access for certified producers.
- Sparkling Wine premiumization:Gulf duty-free channels and celebratory consumption occasions in UAE and Qatar hospitality venues are elevating margin capture for effervescent categories.
Market Restraints
- Input cost volatility:Oak barrel and imported yeast prices fluctuate with euro and dollar exchange rates, compressing margin on aged red wine production.
- Supply concentration risk:Western Cape vineyard infrastructure dominates regional grape supply, exposing buyers to climate disruption in a single geography.
- Regulatory friction:Saudi Arabia's prohibition regime and UAE's emirate-level licensing create supply diversion complexity and compliance overhead for inbound distributors.
Strategic Opportunities
- Nigeria's underpenetrated online retail:E-commerce wine sales remain nascent in Lagos and Abuja, offering first-mover positioning for direct-to-consumer platforms.
- Morocco's emerging vineyard investment:Atlas Mountain terroirs and Castel Group bottling infrastructure create expansion terrain for Mediterranean-style varietals.
- Licensing liberalization monitoring:Gulf Cooperation Council jurisdictions signal potential duty and permit reforms that would lower market entry capital requirements.
Industry Challenges
- Sommelier and viticulture talent scarcity:Trained enology professionals and certified hospitality staff are concentrated in Cape Town and Dubai, limiting program quality in secondary markets.
- Cold chain capex intensity:Temperature-controlled storage and transport infrastructure demands substantial capital outlay for distributors serving Nigeria and East African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Wine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé Wine, Sparkling Wine Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Price Tier: Premium, Economy, Mid-Range, Super Premium End User: Restaurants, Retail Consumers, Hotels, Bars |
| Companies Covered | Constellation Brands, Castel Group, Accolade Wines, Suntory Holdings, Distell Group Holdings, Pernod Ricard, Treasury Wine Estates, The Wine Group, E. & J. Gallo Winery, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Wine Market Shifts & Advancements
Premium hospitality venues across the Gulf are reconfiguring beverage programs around experience-centric consumption, while digital channels and certification-driven sourcing reshape how wine reaches end consumers in the region.
Precision viticulture using drone-mounted sensors and soil moisture analytics is absorbing capital from established Western Cape estates seeking yield optimization and water stress mitigation. Mid-sized vineyard operators are deploying these systems to reduce input waste and improve harvest timing decisions. The technology is absorbing manual scouting labor and compressing the information lag between field conditions and harvest execution.
South Africa's Wine and Spirit Board is tightening additive disclosure and sulfite labeling requirements that align with European Union import standards. This regulatory convergence is forcing reformulation of entry-level exports and accelerating certification investment among cooperatives. Producers targeting German and Dutch markets are prioritizing organic conversion to meet dual jurisdiction compliance.
Duty-free transit retail in Dubai and Abu Dhabi airports is displacing traditional import-dependent distribution for premium Australian and South African labels. Gulf-based buyers are negotiating direct allocation agreements with estate producers, bypassing layered wholesale structures. This channel pivot is most visible among Penfolds-tier portfolios targeting Chinese tourist transit corridors.
Middle East and Africa Wine Market Segmentation
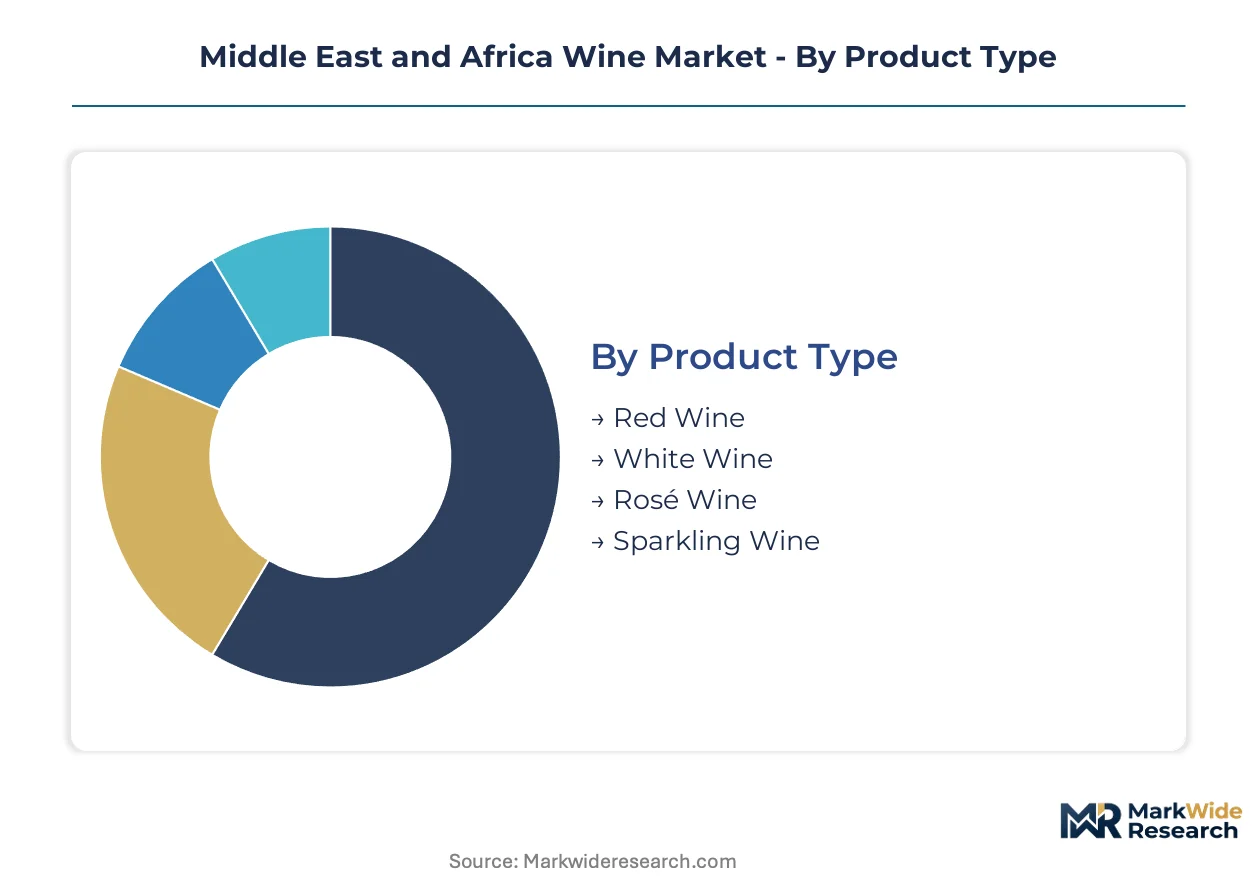
Wine suppliers across the Middle East and Africa navigate divergent consumption occasions and channel economics that reward granular portfolio positioning. Segmentation discipline separates operators capturing Gulf hospitality premiums from those competing on volume in North African retail.
Product Type:
Consumer upgrade cycles in the region pivot from entry-level table wines toward differentiated varietals and celebratory formats as purchasing power and occasion sophistication advance.
- Red Wine:Fermented with grape skins intact, delivering tannin structure and depth through malolactic aging in oak or stainless steel. Demand concentrates in South Africa's Western Cape export programs and Dubai steakhouse beverage programs, where Cabernet Sauvignon and Shiraz anchor by-the-glass pricing power. Climate volatility in single-origin supply geography constrains vintage consistency.
- Sparkling Wine:Carbonated through secondary fermentation, achieving effervescence via traditional method or tank processes. Gulf duty-free channels in Dubai and Abu Dhabi and celebratory hospitality occasions in Doha and Riyadh (via neighboring supply) generate disproportionate margin capture for Prosecco and Cap Classique tiers. MOHAP licensing frameworks shape on-premise availability.
- White Wine:Pressed and fermented without skin contact, preserving acidity and aromatic clarity. Coastal Mediterranean dining in Casablanca and Tunis drives Sauvignon Blanc and Chenin Blanc placement.
- Rosé Wine:Produced through limited skin maceration, yielding pale to salmon coloration. Provence-style consumption patterns are emerging in Cape Town summer hospitality and Marrakech resort venues.
Volume placements concentrate in Red Wine; the faster expansion belongs to Sparkling Wine.
Distribution Channel:
Channel selection in this market maps directly to capital intensity and regulatory compliance burden, with digital infrastructure gaps creating divergent entry economics across geographies.
- Supermarkets:Self-service retail with ambient or limited climate-controlled display, dominating Economy and Mid-Range tier movement in Morocco, Tunisia, and South African mass retail. Carrefour and Pick n Pay footprints anchor volume.
- Online Retail:Direct-to-consumer platforms and aggregator marketplaces with last-mile delivery capability. Lagos and Abuja e-commerce penetration remains nascent, offering positioning terrain for platform-first entrants willing to absorb cold-chain capex.
- Specialty Stores:Curated inventory with sommelier consultation and temperature-controlled cellaring. Cape Town's Long Street and Dubai's Jumeirah clusters concentrate knowledgeable trade.
- Wholesale:Licensed distributors supplying on-premise accounts with volume pricing and regulatory clearance handling. UAE's emirate-specific licensing fragments wholesale concentration.
Supermarkets still move the most cases; Online Retail is climbing the fastest.
Price Tier:
Price architecture in the region reflects certification grade and origin labeling more than production cost alone, with South Africa's Wine and Spirit Board tiers creating export-ready quality demarcations.
- Premium:Estate-bottled wines with origin certification and controlled yield limits, commanding placement in Dubai International Airport duty-free and Cape Town fine dining. Penfolds and established Western Cape estates anchor this tier.
- Mid-Range:Cooperative or mid-size estate production with regional appellation compliance, filling hotel beverage programs and retail shelves across North Africa.
- Economy:Bulk-blended or non-certified wines priced for daily consumption, dominant in Tunisian and Moroccan domestic markets with limited export eligibility.
- Super Premium:Single-vineyard or limited-release allocations with provenance documentation, targeting collector markets and trophy hospitality placements in Doha and Abu Dhabi.
Mid-Range captures the widest geographic footprint; Premium is gaining share fastest.
End User:
End-user targeting requires matching certification status and packaging format to occasion-specific consumption rituals that vary sharply between Gulf prohibition-adjacent markets and South Africa's mature domestic trade.
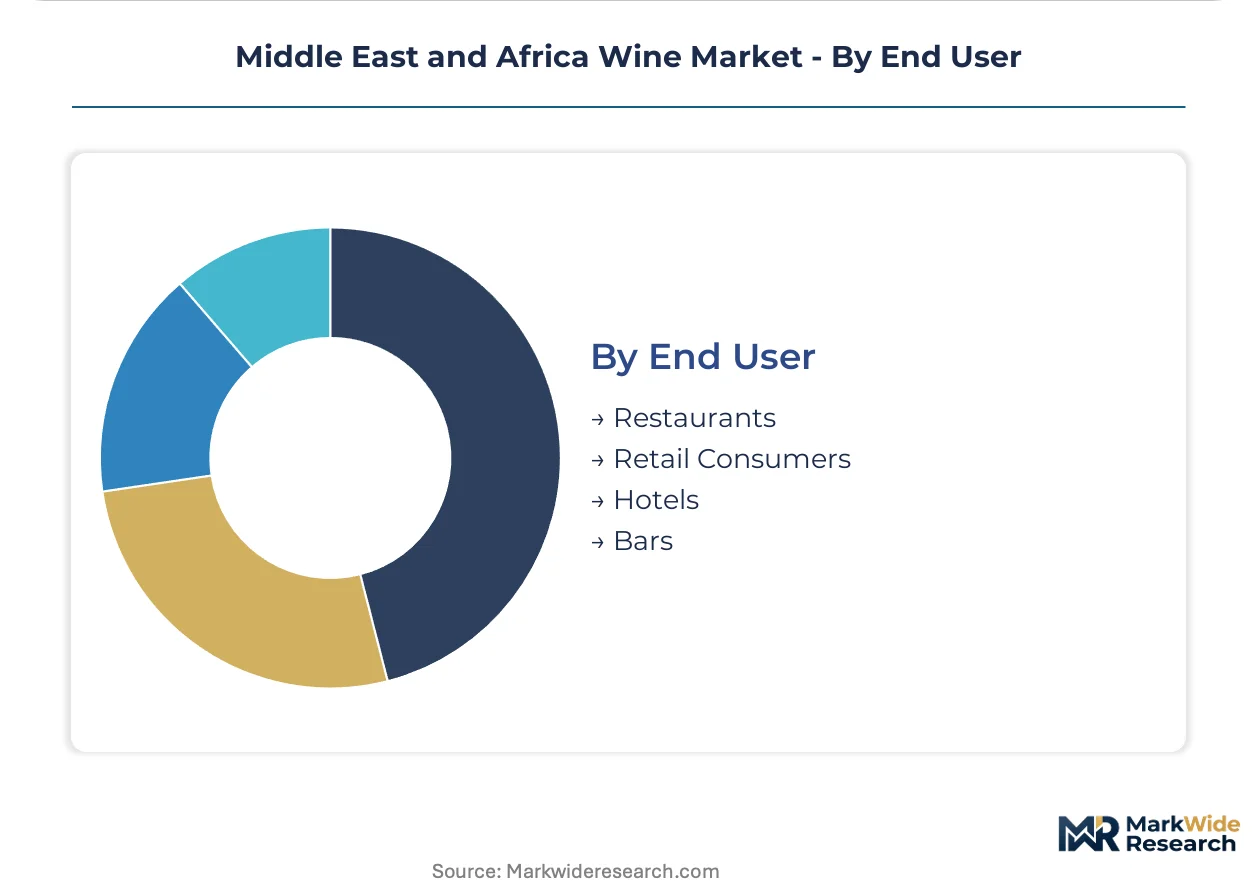
- Hotels:Licensed hospitality venues with beverage program oversight and international guest profiles. Dubai and Cape Town luxury property expansions are enlarging wine list depth and by-the-glass variety.
- Restaurants:On-premise dining with food pairing requirements and sommelier service. Steakhouse and Mediterranean concepts in Abu Dhabi and Johannesburg drive red wine and sparkling placement.
- Bars:Licensed on-premise with cocktail integration and social consumption positioning. Limited in Saudi Arabia; concentrated in Bahrain and Qatar as diversion destinations.
- Retail Consumers:Individual purchasers for home consumption, served through supermarkets, specialty stores, or permitted e-commerce in South Africa and Nigeria.
Hotels command the highest per-occasion spend; Restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Cape vineyard estates anchor grape supply across the region, while Gulf hospitality expansion and North African retail modernization create divergent demand poles.
South Africa
Western Cape export programs and Cape Town luxury hotel beverage expansions drive premium placement. The Wine and Spirit Board enforces origin certification and sulfite disclosure standards that unlock European market access. Stellenbosch and Paarl vineyard clusters concentrate precision viticulture investment and estate-level consolidation activity.
United Arab Emirates
Dubai International Airport duty-free channels and Abu Dhabi luxury hospitality programs attract transit retail spend and celebratory consumption occasions. MOHAP licensing frameworks administer emirate-specific alcohol permits that fragment wholesale distribution. Jumeirah and Downtown Dubai hotel clusters anchor sommelier-led wine program depth.
Morocco
Atlas Mountain terroir development and Mediterranean dining culture in Casablanca expand vineyard investment and rosé consumption. Castel Group bottling infrastructure provides regional distribution leverage. Marrakech resort venues and Rabat retail modernization concentrate Mid-Range tier placement.
Nigeria
Lagos and Abuja e-commerce penetration remains nascent, offering positioning terrain for platform-first direct-to-consumer entrants. Cold chain infrastructure gaps constrain import-dependent supply. Victoria Island hospitality clusters absorb Premium tier allocations despite distribution friction.
Saudi Arabia
Complete prohibition regime diverts supply into neighboring Bahrain and Qatar markets, creating diversion destination demand. Regulatory liberalization signals in Gulf Cooperation Council jurisdictions warrant monitoring for duty and permit reform timing. Eastern Province proximity to Bahrain concentrates cross-border consumption patterns.
Middle East and Africa Wine Market Competitive Landscape
Global majors compete with regional champions across certification-grade and channel-access dimensions. The vendor base stratifies between heritage estate operators with Wine and Spirit Board credentials and multinational portfolios leveraging duty-free transit retail scale. Three archetypes dominate: Western Cape estate consolidators with captive grape supply, North African bottling-network operators, and Australian premium-label marketers targeting Gulf hospitality. Competitive moves concentrate on estate acquisition for vertical control and direct allocation agreements that bypass layered wholesale structures.
Among heritage estate consolidators, Distell Group Holdings and Treasury Wine Estates exemplify divergent geographic anchoring strategies. Castel Group occupies a position bridging North African production infrastructure with Mediterranean market access. These three operators represent the competitive tension between origin-certified domestic production and multinational portfolio scale.
| Leading Market Players |
|---|
| Constellation Brands |
| Castel Group |
| Accolade Wines |
| Suntory Holdings |
| Distell Group Holdings |
| Pernod Ricard |
| Treasury Wine Estates |
| The Wine Group |
| E. & J. Gallo Winery |
| Others |
Supply & Pricing Matrix
Dubai and Abu Dhabi luxury hotel procurement committees now mandate estate-level provenance documentation for by-the-glass placements, forcing South African cooperatives to absorb Wine and Spirit Board certification costs or surrender Premium tier positioning to consolidated Western Cape estates with captive supply.
Pricing Analysis
Warranty-like service bundling separates Premium tier positioning from unbundled Economy alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and sommelier consultation inclusion. Cost compression in Mid-Range bulk placements is intensifying because oak barrel and imported yeast prices fluctuate with euro exchange rates. Economy buyers in Moroccan and Tunisian supermarkets exhibit highest price sensitivity; Gulf duty-free transit consumers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from UAE hospitality procurement teams mandate qualifying both South African and Australian estate suppliers to mitigate vintage failure risk. Grape supply draws from Western Cape, Margaret River, and Languedoc-Roussillon production zones. Oak barrel, imported yeast, and temperature-controlled shipping container dependencies tether margins to dollar and euro volatility. Single-source vulnerability concentrates in Western Cape climate exposure. Distribution runs through emirate-specific licensed wholesalers with fragmented permit frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision viticulture sensor networks are displacing manual scouting labor across Western Cape estates, compressing harvest timing information lags and reshaping competitive economics for laggard cooperatives.
For Market Incumbents: Hedge against climate concentration risk by securing Atlas Mountain vineyard development rights in Morocco alongside Western Cape estate consolidation. Invest in Wine and Spirit Board organic conversion to meet EU sulfite disclosure convergence. Channel control through direct allocation agreements with Dubai duty-free operators reduces wholesale layer dependency. For New Entrants and Emerging Players: Launch via platform-first direct-to-consumer models in Lagos and Abuja e-commerce corridors, absorbing cold-chain capex that incumbents avoid. Nigeria's underpenetrated online retail offers positioning terrain for celebratory format specialists. Target Premium tier hotel beverage programs in Victoria Island with certified provenance storytelling. For Investors and Strategic Acquirers: The window for entry favors Western Cape estate consolidators with Wine and Spirit Board credentials and Gulf duty-free allocation relationships. Long-term viability hinges on climate adaptation infrastructure and emirate licensing liberalization timing. Monitor MOHAP permit reform signals as inflection indicator for wholesale distribution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Estate Acquisition for Vertical Control | Captive grape supply secures Premium tier positioning against cooperatives in Dubai duty-free channels. |
| Organic Certification Investment | Wine and Spirit Board organic conversion unlocks German and Dutch market access compliance. |
| Direct Allocation Agreement | Bypasses fragmented UAE emirate wholesale layers for Penfolds-tier portfolio margin capture. |
| Precision Viticulture Deployment | Drone-mounted sensors reduce water stress losses in Western Cape single-origin supply geography. |
| E-Commerce Platform Buildout | First-mover positioning in Lagos cold-chain infrastructure gaps defends against incumbent reaction. |
Research Methodology
Independent corroboration across vineyard estate operators, UAE hospitality procurement directors, and Nigerian e-commerce platform founders underwrites the qualitative findings. Primary interviews with Western Cape winemakers, Dubai sommelier program managers, and Moroccan Castel Group bottling facility supervisors combined with secondary validation from Wine and Spirit Board certification databases, UAE customs import records, and South African agricultural export statistics. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level assumptions.
Rate-of-change decomposition across the analysis window isolates tourism-driven hospitality expansion, certification-driven export eligibility, and channel shift acceleration effects. Segmentation dimensions modeled include product type, distribution channel, price tier, and end-user occasion. CAGRs derive from historical trajectory analysis adjusted for structural break points. Forecast inputs incorporate Western Cape climate volatility indices and Gulf licensing liberalization probability assessments.
Climate disruption in Western Cape, MOHAP permit regime changes, and naira exchange rate collapse are the dominant revision risks. Deviation in Western Cape rainfall patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Rose Wine Market