
 Alcoholic Tea Market | 2026-2036
Alcoholic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Tea Market Analysis
The EU Green Deal is repositioning packaging and sourcing priorities across the alcoholic tea value chain. Suntory leverages its integrated beverage R&D infrastructure to develop lower-carbon canning processes. Twisted Tea anchors the North American mass-market channel through dominant retail shelf placement. Kirin Holdings competes in Asia-Pacific through specialized brewed formats with extended fermentation protocols.
Alcoholic tea denotes tea leaves infused with ethanol, typically achieving alcohol-by-volume concentrations between 4% and 8% through fermentation, blending, or fortification processes. The beverage serves commercial hospitality and off-premise retail channels seeking differentiated alternatives to beer and hard seltzer. Ready-to-drink canned formats lead volume due to convenience-store and outdoor-event consumption patterns, while sparkling variants capture premium positioning in specialty retail. Citrus flavor profiles dominate mainstream adoption, though herbal infusions attract health-oriented segments seeking reduced-sugar positioning.
FDA labeling requirements and TTB formula approvals govern product entry in the United States, while EFSA additive thresholds and EU-wide alcohol duty structures shape European formulation economics. The EU AI Act's emerging supply-chain traceability provisions will soon extend to ingredient provenance documentation. Stakeholders must monitor evolving state-level distribution franchise laws and deposit-return scheme expansions that threaten margin structures in core growth channels.
Market Dynamics
EU Green Deal packaging mandates are compressing formulation timelines across the alcoholic tea value chain, forcing simultaneous transitions in canning substrates, label adhesives, and supply-chain traceability systems.
Growth Catalysts
- EU Green Deal packaging mandates:The regulation accelerates material transitions toward recycled aluminum and bio-based linings, creating first-mover advantages for compliant producers in German and Dutch retail channels.
- Ready-to-drink canning infrastructure:Contract packagers in the United States are expanding dedicated hard tea lines to capture convenience-store and sports venue demand from Millennial and Gen-Z consumers.
- Festival and outdoor event consumption:Seasonal activation models in urban nightlife clusters drive volume spikes and brand trial rates that sustain year-round retail placement negotiations.
Market Restraints
- Aluminum price volatility:Input cost swings for can sheet metal compress margin structures, particularly for mid-tier producers lacking long-term supply contracts with rolling mills.
- TTB formula approval timelines:FDA and Alcohol and Tobacco Tax and Trade Bureau review cycles extend product launch windows by 6-12 months, freezing innovation pipelines.
- Hard seltzer substitution threat:Established seltzer brands in US convenience stores capture overlapping consumer occasions through aggressive price positioning and flavor breadth.
Strategic Opportunities
- Extended fermentation protocols:Specialized brewing techniques enabling 8% ABV positioning without fortification open premium shelf space in Japanese and South Korean specialty retail.
- Deposit-return scheme expansion:EU-wide DRS rollout creates reverse-logistics partnerships that lock in circular-economy credentials and secure preferential listing terms.
- Herbal infusion health positioning:Reduced-sugar formulations with adaptogenic ingredients target wellness-oriented consumers in California and New York metro health-food channels.
Industry Challenges
- Flavor stability chemistry:Maintaining citrus and botanical integrity across 12-month shelf life requires specialized antioxidant systems and accelerated aging validation protocols.
- Cross-functional compliance talent:Shortage of professionals conversant in both beverage formulation and TTB labeling requirements delays product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Tea Market |
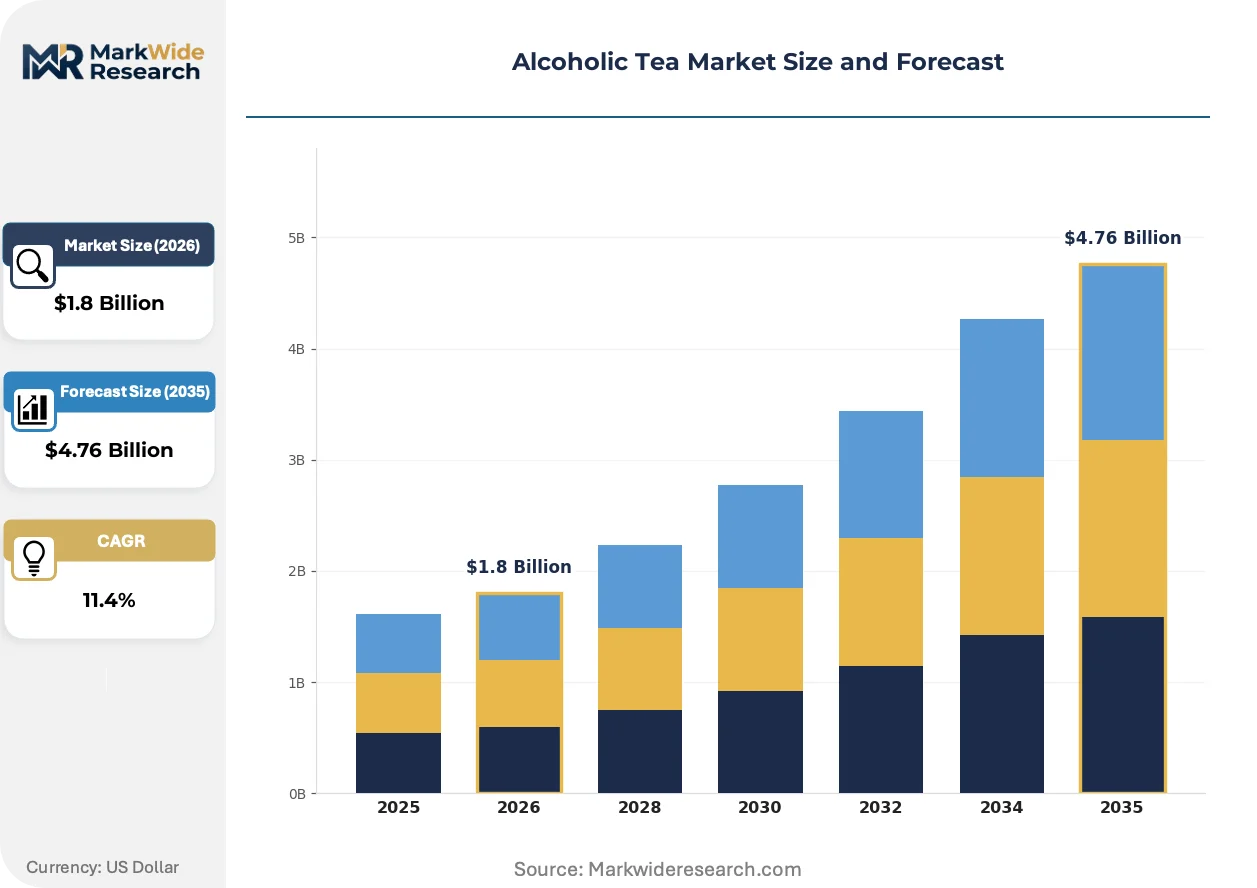
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Brewed, Sparkling, Concentrate Flavor Profile: Citrus, Herbal, Spiced, Fruity Packing Type: Canned, Bottled, Tetra Pak, Keg Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Bars |
| Companies Covered | Teez Tea, Suntory, Twisted Tea, Ceylon Tea, Kirin Holdings, BrewDog, Naked Turtle, Craft Brew Alliance, Hard Tea Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Tea Market Emerging Trajectories
Active reformulation of packaging substrates and fermentation protocols is compressing traditional production timelines while opening premium positioning corridors previously occupied by craft beer and spirits.
Nitrogen dosing technology for widget-free cascading pours is absorbing development resources at European canning equipment suppliers. UK and Irish pub-channel buyers are specifying nitrogen-compatible formats for draft-style canned releases. This capability is absorbing market share from traditional carbonated hard teas by replicating the mouthfeel expectations of stout drinkers.
EFSA additive threshold revisions are tightening permissible preservative loads in EU-bound formulations. Manufacturers are responding with accelerated adoption of high-pressure processing and aseptic filling lines. German and Dutch retail buyers are now requiring additive-free certifications as listing prerequisites.
Direct-to-consumer subscription models are fragmenting traditional three-tier distribution in US metropolitan markets. Urban Millennials are bypassing state franchise systems through winery-direct loopholes and licensed delivery apps. California and Texas regulators are drafting responses that will determine channel legality through 2026.
Alcoholic Tea Market Segmentation
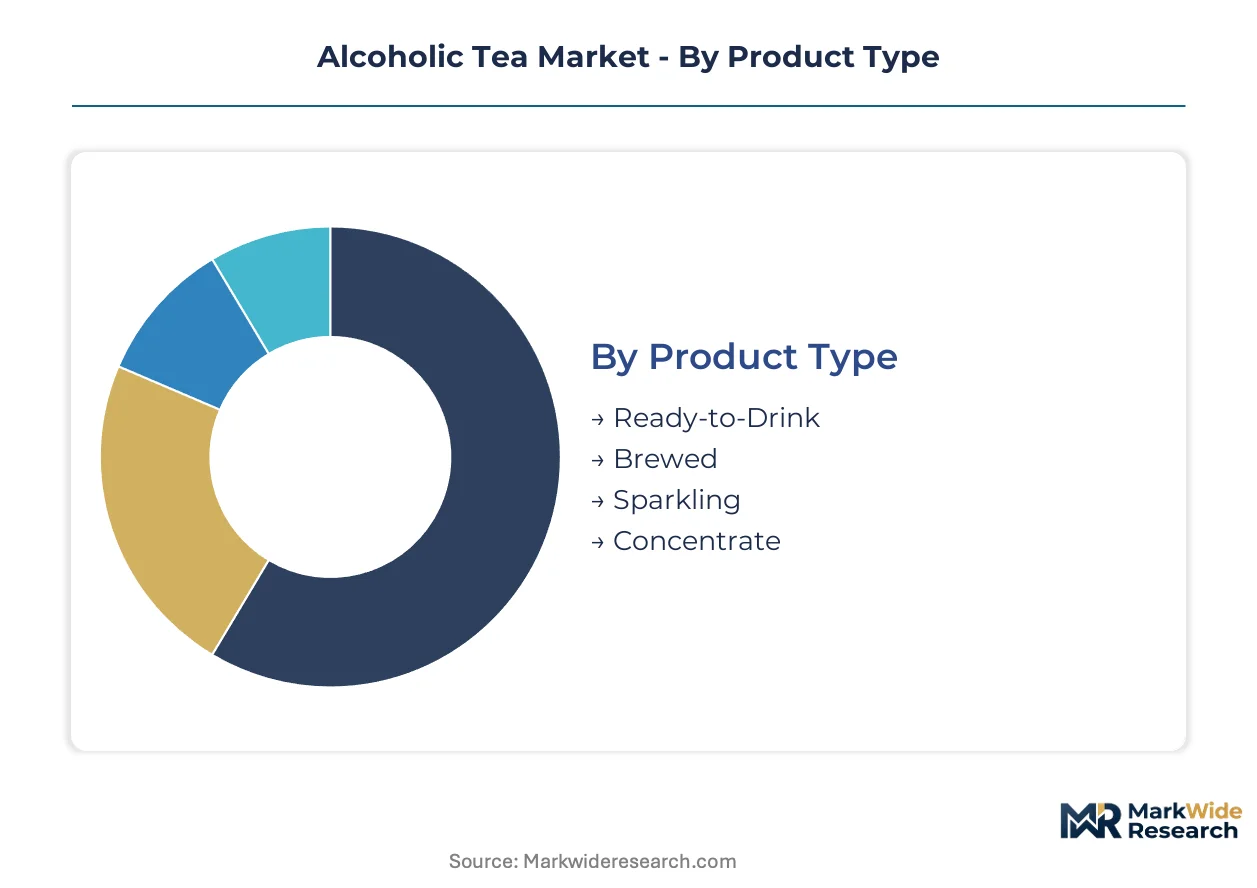
Alcoholic tea segmentation reveals how producers navigate competing pressures from convenience-driven consumption, sustainability mandates, and channel-specific margin structures. Format and packaging choices directly determine regulatory exposure and logistics economics across the value chain.
Product Type:
Supply concentration in canning infrastructure tilts manufacturing investment toward formats compatible with existing contract packager capacity.
- Ready-to-Drink:Pre-mixed formulations in single-serve containers dominate convenience-store and festival channels. Millennial and Gen-Z consumers in US urban nightlife clusters drive volume through grab-and-go purchase patterns.
- Brewed:Extended fermentation protocols produce higher ABV positioning through natural processes rather than fortification. Japanese and South Korean specialty retail buyers specify these formats for premium shelf placement.
- Sparkling:Carbonated variants command price premiums in European specialty retail.
- Concentrate:Dilution-required formats serve on-premise hospitality with storage efficiency advantages.
Today's leader: Ready-to-Drink. Tomorrow's challenger: Brewed.
Flavor Profile:
Cost tier differentiation separates mass-market citrus formulations from premium herbal positioning targeting wellness-oriented consumers.
- Citrus:Lemon and lime-infused bases anchor mainstream adoption through familiar taste profiles. US convenience stores and sports venues specify citrus SKUs as volume drivers.
- Herbal:Adaptogenic and botanical infusions target reduced-sugar positioning in California and New York metro health-food channels. EFSA additive thresholds are accelerating clean-label reformulation.
- Spiced:Cinnamon and ginger variants capture seasonal activation opportunities.
- Fruity:Berry and tropical profiles compete directly with hard seltzer flavor breadth.
Citrus dominates volume. Herbal gains share fastest in premium channels.
Packing Type:
Application requirements from outdoor events to on-premise draft service fragment packaging specifications across the value chain.
- Canned:Recyclable aluminum dominates ready-to-drink formats. EU Green Deal mandates are accelerating transitions toward recycled content and bio-based linings in German and Dutch retail.
- Bottled:Glass containers serve premium positioning in specialty retail and gift channels.
- Tetra Pak:Aseptic cartons offer logistics efficiency for concentrate formats.
- Keg:Stainless steel vessels serve festival and bar-channel draft service.
Canned formats lead volume. Deposit-return scheme expansion favors aluminum recovery economics.
Distribution Channel:
Customer type fragmentation between impulse purchasers and planned buyers shapes channel-specific assortment and pricing strategies.
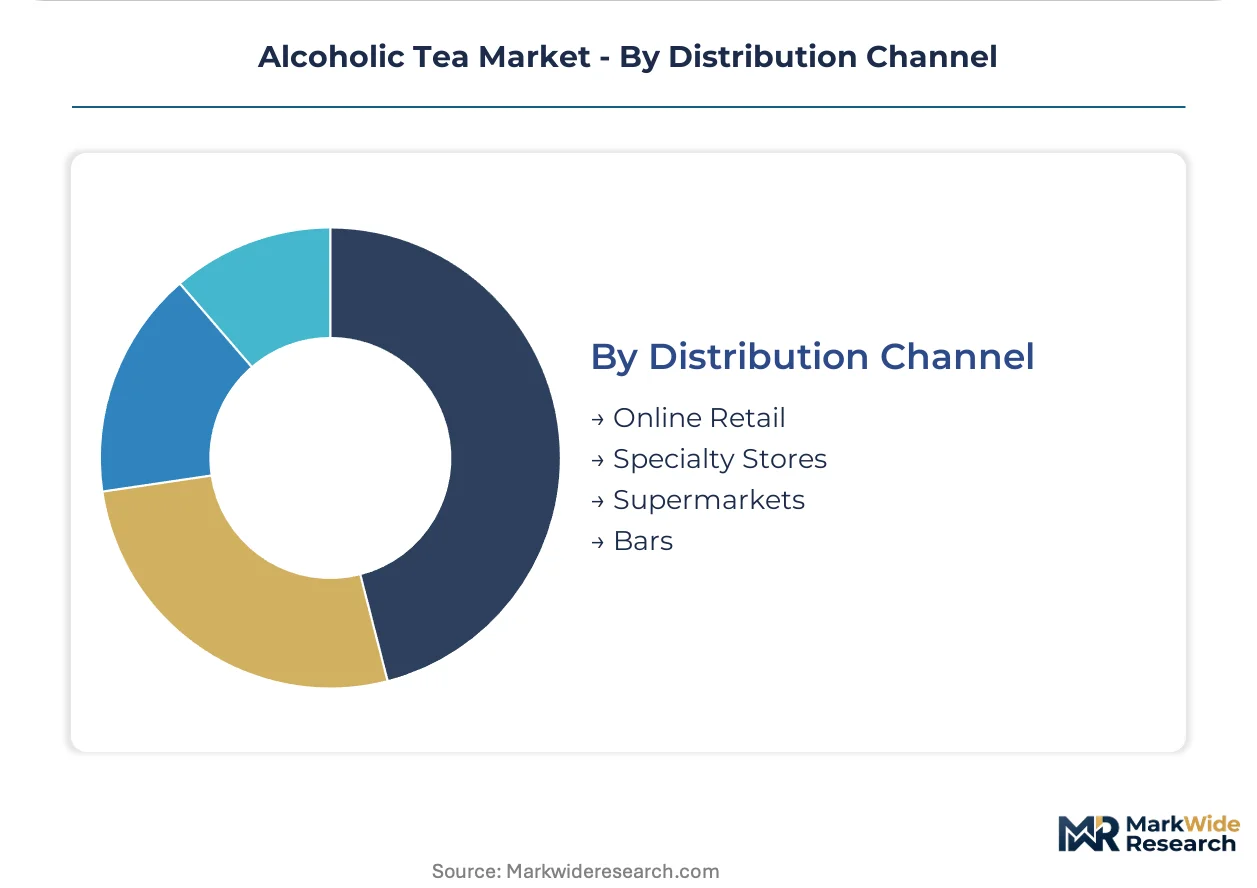
- Online Retail:Direct-to-consumer subscription models exploit winery-direct loopholes in California and Texas. State franchise law revisions will determine channel legality through 2026.
- Specialty Stores:Curated assortments in health-food and beverage-focused retailers support premium herbal and brewed format trials.
- Supermarkets:Mass-market shelf placement negotiations hinge on proven velocity data from convenience-store and venue channels.
- Bars:On-premise trial drives brand awareness that converts to off-premise purchase.
Supermarkets anchor volume. Online retail climbs the fastest amid regulatory uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alcoholic tea originated in Japan's post-war brewing industry, where tea fermentation techniques merged with emerging RTD alcohol production. The format migrated to North American convenience retail during the 1990s, establishing the template for contemporary global expansion.
United States
Millennial and Gen-Z consumers in urban nightlife clusters drive volume through convenience-store and sports venue channels. TTB formula approval timelines extend product launch windows by 6-12 months, freezing innovation pipelines for mid-tier entrants. Texas and California regulators are drafting responses to direct-to-consumer subscription models that exploit winery-direct loopholes.
Germany
EU Green Deal packaging mandates accelerate transitions toward recycled aluminum and bio-based linings in retail channels. EFSA additive thresholds are tightening permissible preservative loads, forcing adoption of high-pressure processing lines. Berlin and Hamburg buyers now require additive-free certifications as listing prerequisites for specialty retail placement.
Japan
Extended fermentation protocols enabling 8% ABV positioning through natural processes command premium shelf space in specialty retail. METI standards govern brewing equipment specifications for commercial-scale production. Tokyo and Osaka clusters host integrated beverage R&D infrastructure supporting lower-carbon canning process development.
United Kingdom
Nitrogen dosing technology for widget-free cascading pours absorbs development resources at canning equipment suppliers. UK and Irish pub-channel buyers specify nitrogen-compatible formats for draft-style canned releases. London-based contract packagers are expanding dedicated hard tea lines to capture festival and outdoor event consumption spikes.
South Korea
Specialized brewed formats with extended fermentation protocols attract premium positioning in Seoul metropolitan retail. MFDS labeling requirements govern alcohol content disclosure and health claim restrictions. Busan-Ulsan industrial corridors concentrate aseptic filling line manufacturing for regional export markets.
Alcoholic Tea Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure. Integrated beverage conglomerates with captive canning infrastructure occupy the scale-driven tier, while craft specialists exploit niche fermentation protocols for premium positioning. Strategic archetypes separate into mass-market retail anchors, premium brewed-format specialists, and contract-manufacturing intermediaries. Competitive moves concentrate on M&A for distribution access and dedicated production line expansion at contract packagers.
Within the integrated conglomerate tier, Suntory and Kirin Holdings exemplify the capital-heavy archetype with beverage R&D infrastructure spanning multiple alcohol categories. Twisted Tea anchors the North American mass-market position through dominant retail shelf placement negotiations. Among craft-oriented specialists, BrewDog occupies a position exemplifying portfolio diversification into alternative fermentation beverages.
| Leading Market Players |
|---|
| Teez Tea |
| Suntory |
| Twisted Tea |
| Ceylon Tea |
| Kirin Holdings |
| BrewDog |
| Naked Turtle |
| Craft Brew Alliance |
| Hard Tea Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates are forcing German and Dutch retail buyers to specify recycled aluminum and bio-based linings, compelling suppliers to absorb material transition costs while mid-tier producers without long-term rolling mill contracts face margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extended fermentation brewed formats from mass-market citrus SKUs and entry-level private-label alternatives. Price differentiation hinges on ABV positioning and additive-free certification status, with Berlin specialty retailers commanding premiums for EFSA-compliant clean-label formulations. Cost compression in the standard tier is intensifying because aluminum sheet metal volatility outpaces contract hedging coverage. Festival-channel buyers exhibit highest price sensitivity, while Japanese specialty retail purchasers show lowest elasticity for provenance-documented products.
Supply Chain Analysis
Domestic-content requirements under EU Green Deal traceability provisions are reshaping sourcing patterns, forcing manufacturers to document tea leaf provenance and canning substrate origin. Supply concentration centers on China for tea extract processing, Germany for aseptic filling equipment, and the United States for contract canning capacity. Raw material dependencies include Sri Lankan black tea leaf, Brazilian cane ethanol, and recycled aluminum sheet. Single-source vulnerability runs through Chinese tea extractors serving multiple European brands. Distribution runs through three-tier wholesale networks in the United States and direct retail relationships in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shifts toward extended fermentation protocols and nitrogen-dosed formats that command specialty retail placement premiums.
For Market Incumbents: Extend captive canning infrastructure into dedicated hard tea lines at contract packagers to lock in sports venue and convenience-store shelf space against hard seltzer substitution. Deepen backward integration into tea leaf sourcing to satisfy EU AI Act provenance documentation requirements and secure additive-free certifications for German retail listings. Control channel access through exclusive festival activation partnerships that generate velocity data for supermarket placement negotiations. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models exploiting winery-direct loopholes in California and Texas before state franchise law revisions close the channel. Target herbal infusion segments in New York and California metro health-food channels where reduced-sugar positioning faces less established competition than citrus-dominated convenience retail. Pursue white-space in nitrogen-compatible draft-style formats for UK and Irish pub channels specifying widget-free cascading pour technology. For Investors and Strategic Acquirers: Asymmetric upside sits with contract packagers expanding dedicated hard tea production lines to capture Millennial and Gen-Z volume concentration in urban nightlife clusters. Five-to-ten year viability favors asset-light designers with specialized fermentation IP over capital-heavy integrated conglomerates facing aluminum price volatility. Watch TTB formula approval timeline compression as signal for innovation pipeline thaw and new product velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Extended Fermentation Protocol Development | Enables 8% ABV natural positioning in Japanese and South Korean premium retail without fortification costs. |
| Nitrogen Dosing Technology Adoption | Replicates stout mouthfeel for UK pub-channel buyers specifying draft-style canned releases. |
| Recycled Aluminum Transition | Satisfies EU Green Deal mandates for German and Dutch retail listing prerequisites. |
| Direct-to-Consumer Channel Launch | Exploits winery-direct loopholes in California and Texas ahead of regulatory clarification. |
| Aseptic Filling Line Investment | Meets EFSA additive threshold revisions through high-pressure processing certification. |
Methodological Framework
Direct dialogue with beverage R&D directors, TTB compliance officers, German retail category buyers, and contract packaging executives grounded qualitative findings in operational reality. Secondary validation drew from FDA formula approval databases, EFSA additive threshold documentation, EU Green Deal implementation guidance, and TTB labeling requirement updates. Bottom-up volume modeling across format, flavor, and channel segments triangulated against top-down category spend analysis.
Segment-level projections across product type, flavor profile, packaging format, and distribution channel dimensions fed into consolidated market sizing over the projection horizon. CAGRs derived from historical velocity data, channel expansion trajectories, and regulatory implementation timelines. Forecast inputs included aluminum price index correlation, TTB approval queue length, and EU deposit-return scheme rollout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TTB formula approval backlog extension or aluminum supply disruption scenarios. Forecasts reflect documented assumptions on regulatory implementation pace and consumer occasion substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Beer Bottling Kit Market