
 Hard Kombucha Market | 2026-2036
Hard Kombucha Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Kombucha Market Intelligence
The prevalence of asset-light contract brewing models, often backed by venture capital, is reshaping competitive positioning for new entrants. This structure allows brands like JuneShine to scale rapidly without heavy capital expenditure on brewing and canning facilities. In contrast, established players such as GT's leverage their existing non-alcoholic kombucha infrastructure and powerful brand recognition. Boochcraft, a key specialist, differentiates through its commitment to certified organic ingredients and high-ABV craft offerings.
Hard kombucha is a fermented tea beverage with an alcohol content over 0.5% ABV, derived from a symbiotic culture of bacteria and yeast (SCOBY). A secondary fermentation using additional sugar and specific yeast strains creates the final alcoholic product, positioned as a functional alternative to beer and hard seltzers. Ginger and berry flavor profiles exhibit strong consumer uptake, aligning with wellness trends. Cans are the leading packaging type, facilitating broad distribution through supermarkets, which form the largest retail channel.
Producers navigate a complex regulatory environment, including the US FDA and TTB for alcohol content verification and labeling. In Europe, compliance involves national food safety standards and EFSA rules on health claims, while Health Canada governs the Canadian market. Future growth depends on a brand's ability to manage supply chain consistency and secure shelf space in mainstream retail.
Market Dynamics
The central structural force in the hard kombucha market is the convergence of consumer demand for functional, wellness-oriented products with brewing innovations that enable consistent alcohol production, creating a distinct alternative to traditional alcoholic beverage categories.
Growth Catalysts
- Proprietary Yeast Development:Advances in the cultivation of specific yeast strains allow for precise control over alcohol by volume (ABV) during secondary fermentation, enabling producers to scale production while ensuring product consistency and regulatory compliance.
- Functional Beverage Demand:Millennial and Gen Z consumers are increasingly seeking alcoholic beverages with perceived wellness attributes, driving consumption in urban centers like San Diego and Austin where health-conscious lifestyles are prevalent.
- Mainstream Retail Expansion:The widespread adoption of cans as the primary packaging format facilitates easier distribution and stocking, allowing hard kombucha brands to secure shelf space in large supermarket chains, the dominant retail channel.
Market Restraints
- Complex Regulatory Oversight:Producers must navigate a dual regulatory framework, adhering to food safety standards from bodies like the US FDA and Health Canada, while also meeting alcohol-specific labeling and content rules from agencies such as the TTB.
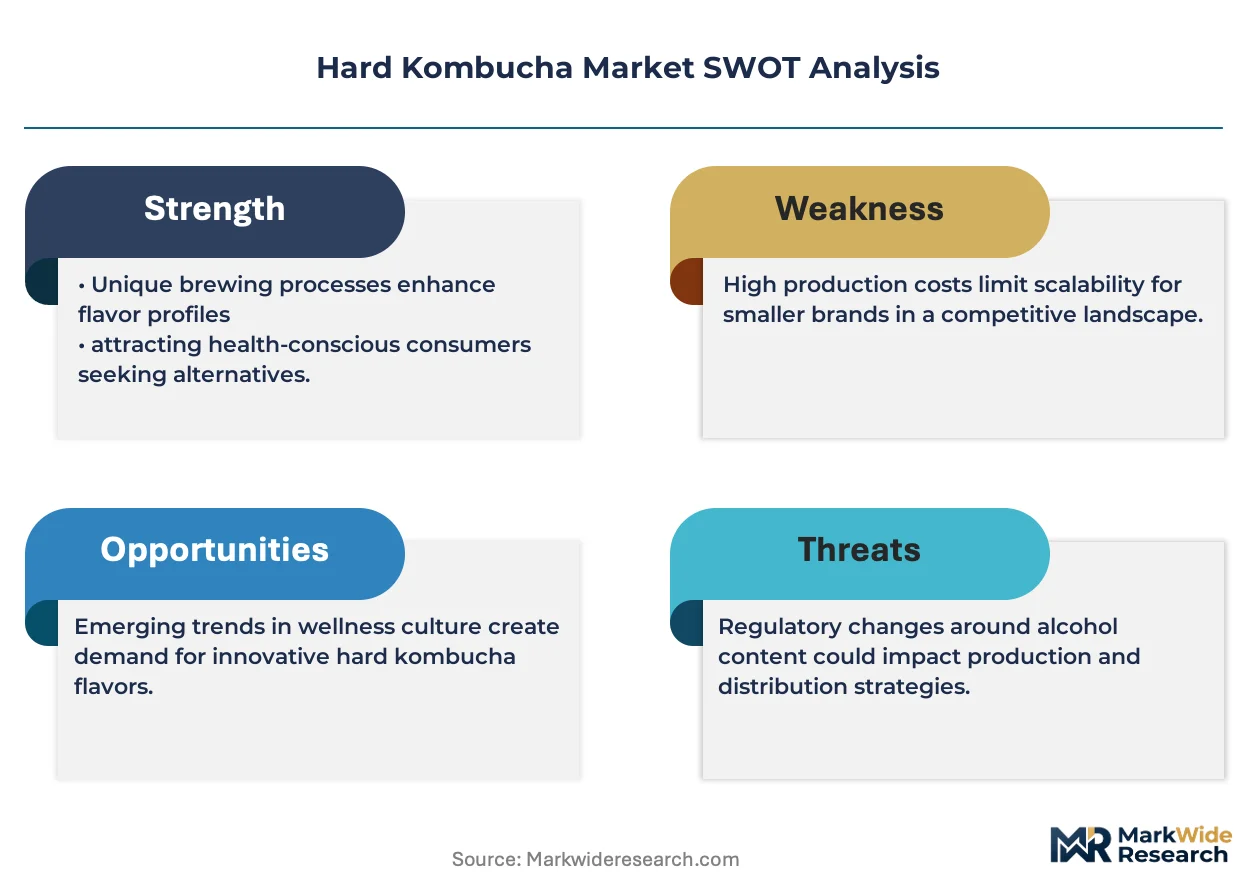
- Input Cost Volatility:Reliance on certified organic ingredients, a key differentiator for premium and craft brands, exposes producers to price fluctuations and supply chain inconsistencies for raw materials like tea, sugar, and flavorings.
- Substitution from Incumbents:The market faces intense competition from established categories, particularly hard seltzers and craft beers, which possess significant brand loyalty, extensive distribution networks, and large marketing budgets.
Strategic Opportunities
- European Market Penetration:Significant white space exists in European countries with strong wellness cultures, such as Germany and the United Kingdom, where consumer interest in fermented products and low-alcohol options presents a clear expansion opportunity.
- Flavor Profile Diversification:Moving beyond common ginger and berry flavors to more complex, culinary-inspired profiles using herbs, spices, and exotic fruits can attract a wider consumer base and create premium, high-margin product tiers.
- On-Premise Channel Development:Introducing hard kombucha on draft in bars, taprooms, and restaurants offers a valuable channel for consumer trial and brand building, positioning the beverage as a craft alternative alongside beer and cider.
Industry Challenges
- SCOBY Management at Scale:Maintaining the health and consistency of the symbiotic culture of bacteria and yeast (SCOBY) across large-scale commercial batches is a significant operational challenge, impacting final product quality and flavor stability.
- Competition for Retail Placement:Securing and retaining shelf space in major retail chains is a capital-intensive challenge, requiring substantial investment in slotting fees, promotional activity, and distributor relationships to compete against established beverage giants.
- Consumer Education Requirement:A persistent challenge involves educating mainstream consumers on the definition, taste profile, and potential benefits of hard kombucha, differentiating it from both non-alcoholic kombucha and other alcoholic beverages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Kombucha Market |
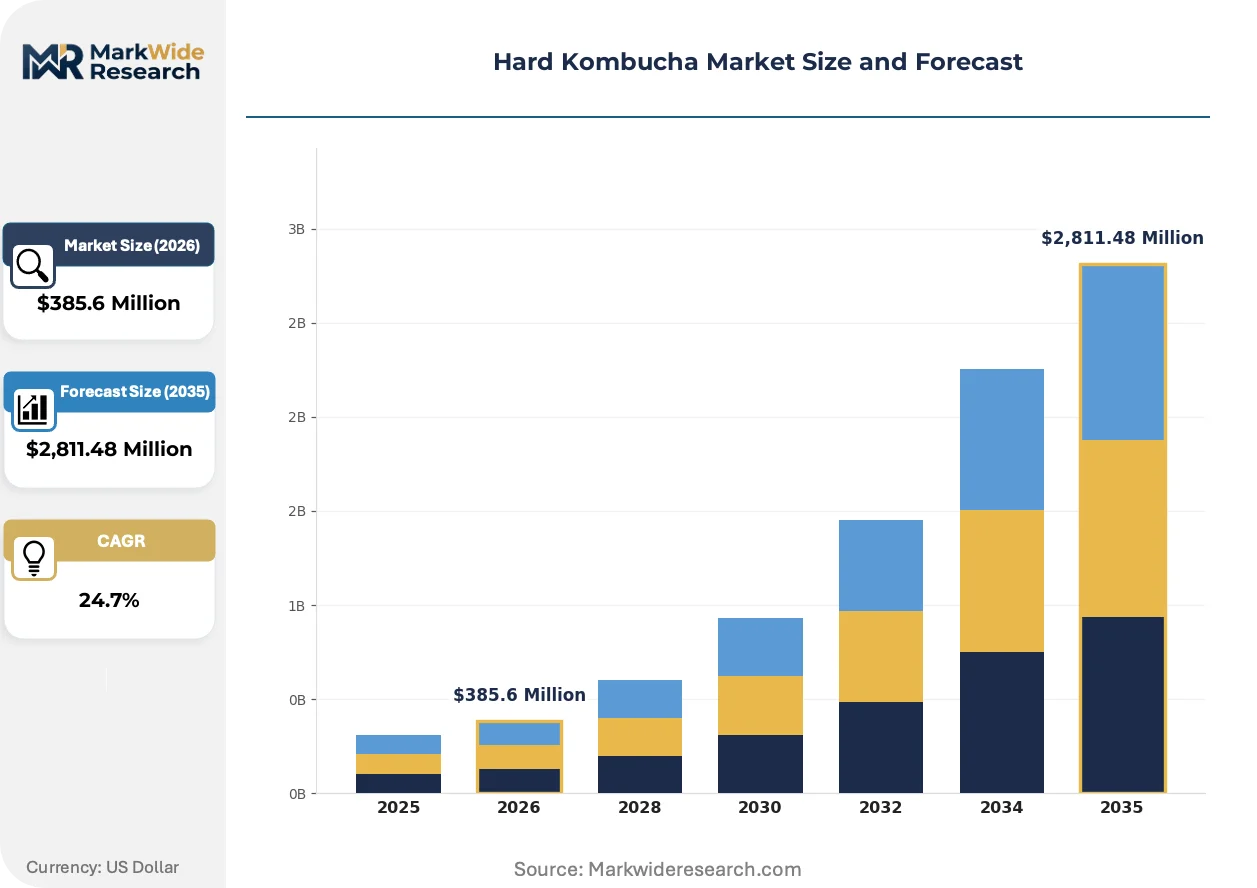
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,811.48 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Profile: Ginger, Berry, Citrus, Herbal Alcohol Content: Low, Medium, High, Craft Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Restaurants Packaging Type: Cans, Bottles, Kegs, Draft |
| Companies Covered | KYLA Hard Kombucha, Wild Tonic, GT's, JuneShine, New Holland Brewing, Kombrewcha, Flying Embers, Unity Vibration, Boochcraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Kombucha Market Strategic Shifts & Innovations
Product formulation is evolving to satisfy a dual mandate from consumers for both functional attributes and more sophisticated, craft-oriented flavor experiences. This shift pushes brands to innovate beyond simple fruit infusions into more complex, culinary-driven recipes that justify a premium price point.
Advanced proprietary yeast strains are engineered for precise control over alcohol creation and flavor expression during fermentation. Brewers targeting scalable production are rapidly adopting these cultures to ensure consistent ABV levels in every batch. This technology is rendering obsolete the wild, unpredictable fermentation outcomes of early craft methods, which created significant barriers to commercialization and regulatory approval.
European Food Safety Authority (EFSA) regulations place strict limits on making unsubstantiated health claims on food and beverage packaging. This regulatory pressure forces brands entering the EU to pivot their marketing away from functional benefits toward attributes like organic certification, craft brewing techniques, and unique flavor profiles. Consequently, producers targeting markets like France and the Netherlands are emphasizing lifestyle branding over wellness messaging.
Consumer preference is shifting toward "sessionable" low-ABV beverages that align with social occasions without causing excessive intoxication. This behavioral change directly challenges segments like high-gravity craft beer, with drinkers substituting for lighter options like hard kombucha. The trend is most visible among health-aware consumers in major North American and Australian cities seeking balanced and mindful consumption habits.
Hard Kombucha Market Segmentation
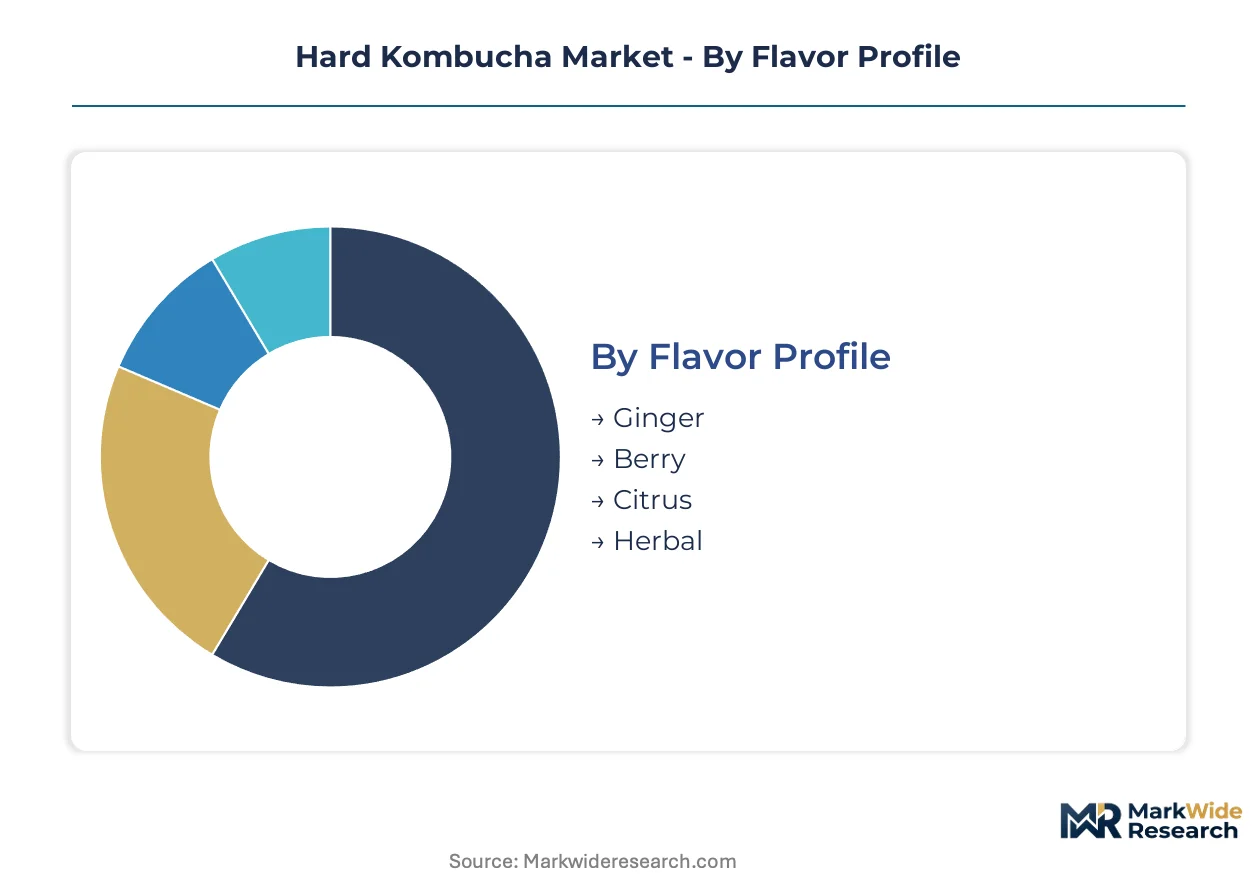
Hard kombucha market segmentation reveals distinct consumer preferences and operational strategies across product types and distribution methods. Understanding these segments helps producers tailor product development, distribution networks, and marketing efforts. This analysis categorizes the market by key attributes influencing purchasing decisions and market access.
Flavor Profile:
The dimension of consumer taste preferences drives product differentiation within the hard kombucha market.
- Ginger:Characterized by a spicy, pungent taste derived from ginger root, often providing a warming sensation. Demand concentrates in health-conscious urban centers like San Diego, driven by perceived digestive benefits and a preference for bold flavors.
- Berry:Features sweet and tart notes from various berries such as raspberry, blueberry, or strawberry, offering broad appeal. European markets, including the United Kingdom, show strong uptake for these accessible and refreshing flavor profiles.
- Citrus:Offers bright, refreshing profiles from lemon, lime, or grapefruit, appealing to consumers seeking crisp, clean tastes, particularly in warmer climates.
- Herbal:Incorporates botanical notes from ingredients like lavender, mint, or hibiscus, targeting adventurous palates in specialty retail and craft beverage segments.
Berry flavors hold installed capacity. Ginger is rotating up the share rankings.
Alcohol Content:
Product formulation varies significantly based on alcohol by volume (ABV) targets, influencing consumer occasion and regulatory classification.
- Craft:Represents higher ABV offerings, often exceeding 6% ABV, with complex flavor profiles from specialized fermentation techniques. Demand concentrates in taprooms and specialty stores across the United States, appealing to craft beverage enthusiasts seeking unique experiences.
- Low:Typically ranges from 0.5% to 3% ABV, designed for sessionable consumption and mindful drinking trends. Australian consumers in major cities are increasingly seeking these lighter options for social occasions without significant intoxication.
- Medium:Contains 3% to 5% ABV, balancing flavor with moderate alcohol content for broad appeal in mainstream retail channels.
- High:Exceeds 5% ABV but remains below craft levels, providing a stronger alcoholic kick for consumers transitioning from other high-ABV alcoholic beverages.
The low ABV segment is expanding most quickly. Craft offerings maintain premium pricing.
Distribution Channel:
Market access and consumer reach are primarily defined by the diverse distribution channels leveraged by hard kombucha brands.
- Supermarkets:Large-format grocery stores offering wide product selection and high consumer traffic. This channel is the largest retail avenue for hard kombucha, facilitating broad consumer exposure in regions like Germany.
- Online Retail:E-commerce platforms and direct-to-consumer sales, providing convenience and access to niche brands for consumers. Growth in this channel is significant in urban centers of Canada, driven by digital-native consumers.
- Specialty Stores:Includes health food stores, liquor stores, and independent grocers, catering to consumers seeking premium or organic beverage options.
- Restaurants:On-premise consumption in dining establishments and bars, offering opportunities for consumer trial and brand building through draft options.
Supermarkets dominate current sales volume. Online retail is gaining share fastest.
Packaging Type:
Packaging format directly impacts product stability, consumer convenience, and logistical efficiency across the supply chain.
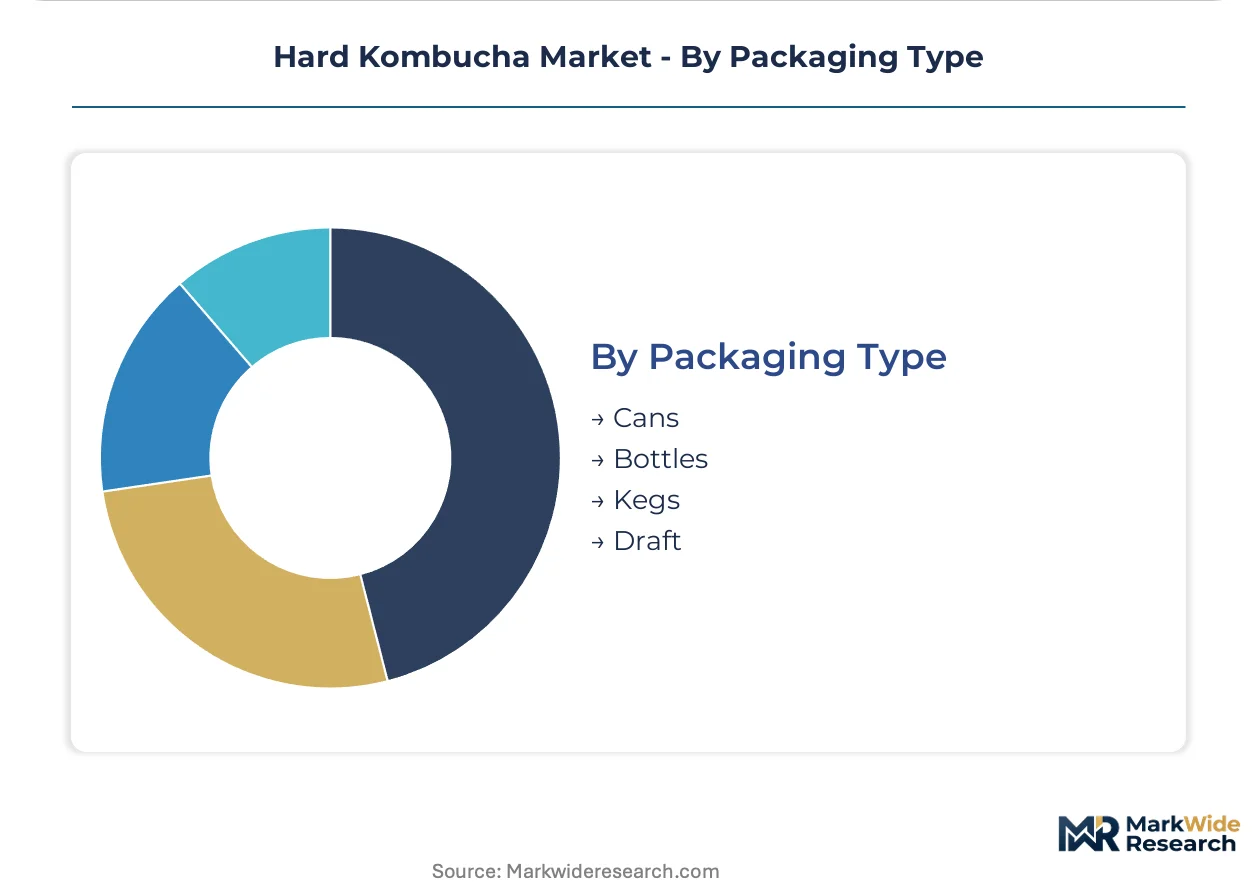
- Cans:Lightweight, durable aluminum containers offering superior light protection and recyclability. Cans are the leading packaging type, enabling broad distribution and shelf space in mainstream retail across the United States.
- Draft:Bulk format dispensed from kegs, primarily for on-premise consumption in bars and taprooms. This format offers a unique consumer experience and reduces packaging waste in cities like Austin.
- Bottles:Glass containers providing a premium aesthetic and traditional feel, often used for smaller batch or specialty hard kombucha offerings.
- Kegs:Large containers for commercial use, supplying draft systems in restaurants and event venues, ensuring freshness and reducing individual packaging needs.
Cans represents the fastest-growing trajectory in packaging. Draft formats enhance on-premise visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for hard kombucha exhibits regional disparities, with premium offerings in the United States commanding higher margins compared to the more price-sensitive European markets. This asymmetry influences market entry strategies and product positioning across different geographies. Consumer demand for functional alcoholic beverages drives growth in health-conscious urban centers globally.
United States
Millennial and Gen Z consumers in the United States increasingly seek functional alcoholic beverages, driving significant demand. The US FDA and TTB regulate product safety and alcohol content verification for these beverages. Wellness-focused urban centers like San Diego and Austin demonstrate high consumption rates, reflecting a strong health-conscious lifestyle trend.
Germany
Germany presents a significant expansion opportunity due to its strong wellness culture and consumer interest in fermented products. Compliance with EFSA rules and national food safety standards is crucial for market entry. Urban hubs such as Berlin are emerging as key consumption areas, with growing demand for low-alcohol options.
United Kingdom
The United Kingdom shows strong uptake for accessible and refreshing berry flavor profiles in hard kombucha. Producers navigate national food safety standards and EFSA regulations for product claims. London's health-aware consumers contribute to the rising demand for mindful consumption habits and sessionable beverages.
Canada
Digital-native consumers in Canada contribute to the significant growth of online retail for hard kombucha. Health Canada governs the market, ensuring product safety and labeling compliance. Major urban centers like Toronto and Vancouver are seeing increased adoption, driven by convenience and functional beverage trends.
Australia
Australian consumers in major cities increasingly seek sessionable low-ABV options for social occasions, aligning with mindful drinking trends. The TGA oversees health claims, alongside national food standards. Sydney and Melbourne represent key markets where balanced consumption habits are influencing beverage choices.
Hard Kombucha Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on niche ingredients or fermentation technologies. The market structure exhibits a dynamic tension between established beverage giants and agile, asset-light new entrants. Strategic archetypes include large-scale infrastructure players, venture-backed contract brewers, and organic-focused craft specialists. Competitive moves center on rapid scaling through distribution and leveraging existing brand recognition.
Established players like GT's leverage their extensive non-alcoholic kombucha infrastructure and powerful brand recognition to enter the hard kombucha segment. JuneShine exemplifies the asset-light contract brewing model, enabling rapid scaling without heavy capital expenditure on facilities. Boochcraft, a key specialist, differentiates itself through a commitment to certified organic ingredients and higher-ABV craft offerings, targeting a premium consumer base.
| Leading Market Players |
|---|
| KYLA Hard Kombucha |
| Wild Tonic |
| GT's |
| JuneShine |
| New Holland Brewing |
| Kombrewcha |
| Flying Embers |
| Unity Vibration |
| Boochcraft |
| Others |
Cost & Logistics Intelligence
European distribution networks, crucial for market penetration, influence cost dynamics that connect raw material sourcing to downstream price differentiation. This affects premium positioning in diverse regional hard kombucha markets.
Pricing Analysis
Customization-premium spreads define hard kombucha pricing, differentiating craft offerings from mass-market products. The dominant model reflects a tiered structure, with certified organic ingredients and unique culinary-inspired flavor profiles driving premium price differentiation. Pricing experiences downward pressure from intense competition with established hard seltzers and craft beers. European consumers exhibit greater price sensitivity compared to health-conscious US urban buyers seeking premium experiences.
Supply Chain Analysis
Input cost volatility, particularly for certified organic ingredients like tea and sugar, represents a primary supply chain risk. Raw materials draw from diverse international sources, including specific fruit flavorings and aluminum for cans. Maintaining SCOBY health and consistency across large commercial batches presents a significant operational challenge. Distribution runs through major supermarkets globally, complemented by growing online retail channels in Canada and on-premise draft options in US cities like Austin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hard kombucha market requires a robust substitution defense against established alcoholic beverage categories. Incumbents must strategically navigate the persistent threat posed by popular hard seltzers.
For Market Incumbents: Build brand recognition moats by extending existing non-alcoholic kombucha infrastructure into hard kombucha. Invest in proprietary yeast strain development to ensure consistent ABV and flavor profiles, mitigating the threat from craft beer incumbents. Secure extensive supermarket shelf space through strategic partnerships and promotional activities. Control over distribution networks remains a critical lever against emerging competitors.
For New Entrants and Emerging Players: European countries with strong wellness cultures, such as Germany and the United Kingdom, represent a penetrable entry point for new hard kombucha brands. Flavor profile diversification into culinary-inspired options attracts adventurous palates and premium segments. Asset-light contract brewing models enable rapid scaling and market entry without heavy capital expenditure. Developing the on-premise channel, particularly draft options in urban centers, offers a valuable go-to-market angle for brand building.
For Investors and Strategic Acquirers: Carve-out targets emerge from established non-alcoholic kombucha brands seeking hard kombucha market entry or from venture-backed contract brewers demonstrating rapid scalability. The market exhibits strong long-term viability, projected to expand significantly over the next decade. Acquisition archetypes include organic-focused craft specialists with strong brand loyalty and asset-light players with efficient distribution. Sustained growth in online retail share, particularly in digital-native markets like Canada, signals robust consumer adoption and future potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Yeast R&D | Ensures consistent ABV control and unique flavor expression across production batches. |
| European Market Entry | Captures demand from wellness-focused consumers in Germany and the United Kingdom. |
| On-Premise Channel Expansion | Facilitates consumer trial and brand building in bars and taprooms. |
| Organic Ingredient Certification | Differentiates premium offerings and attracts health-conscious consumers. |
| Supermarket Shelf Space Negotiation | Secures broad consumer access in the dominant retail channel. |
Research Approach
Cross-validation between primary interviews and secondary market intelligence anchors the qualitative findings within this hard kombucha analysis. Primary research involved conversations with brewing executives, marketing directors, retail category managers, and regulatory affairs specialists. Secondary validation drew from US FDA and TTB filings, EFSA guidelines, and supermarket sales data. This approach ensured robust bottom-up and top-down triangulation of market insights.
The forecast framework calibrates historical data against future projections across the analysis window. Segmentation dimensions modeled include flavor profile, alcohol content, distribution channel, and packaging type. Compound Annual Growth Rates were derived from proprietary quantitative models integrating these segments. Proprietary yeast development trends and consumer wellness trend adoption rates informed market expansion projections.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income or ingredient supply chain stability would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and sustained consumer interest in functional beverages. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
F-Style Jugs Market