
 Bahrain Bakery Product Market | 2026-2036
Bahrain Bakery Product Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Bakery Product Market Outlook
Whole wheat and multigrain flour blends are repositioning traditional white-flour formulations across Bahrain's commercial bakeries. Almarai Co Ltd leverages its integrated dairy-bakery supply chain to dominate fresh bread distribution through modern retail. Mondelez International anchors the premium biscuit segment with specialized production lines serving Gulf Cooperation Council markets. Eastern Bakery competes through localized recipes adapted to Bahraini palate preferences in traditional khubz and regag.
Bakery products encompass leavened and unleavened goods manufactured through mechanical mixing, fermentation, thermal baking, and post-bake finishing, with formulations specified by moisture content, crumb structure, and preservative load to achieve targeted shelf stability. Bread and pastries lead volume throughput across Bahrain's retail and food service channels, where artisan sourdough and laminated dough varieties command premium positioning. Online retail and convenience stores represent the fastest-growing distribution channels as digital ordering platforms and smaller-format retail expand beyond Manama's core districts.
Bahrain's national health regulator enforces food additive limits and nutritional labeling standards aligned with Gulf Standardization Organization technical regulations, while municipal authorities inspect hygiene compliance across production facilities and point-of-sale locations. The Ministry of Industry and Commerce oversees commercial registration and import licensing for wheat and milling inputs, shaping market access for foreign suppliers. Stakeholders must monitor evolving sugar-reduction mandates and packaging sustainability requirements that will reshape formulation and material sourcing decisions across the supply chain.
Market Dynamics
Quick-service restaurant expansion across Manama and Muharraq is compressing procurement cycles and forcing bakery suppliers to reconfigure production schedules around just-in-time delivery mandates. This operational pressure sits at the center of competitive positioning in Bahrain's bakery sector.
Growth Catalysts
- Gulf Standardization Organization alignment:Bahrain's national food safety regulator enforces unified shelf-life labeling standards that reduce cross-border friction for imported wheat and milling inputs.
- Artisan bread demand:Premium pastry and sourdough segments within the capital governorate's retail corridor are pulling capacity upgrades from commercial bakeries.
- Digital ordering platforms:Online retail channels beyond Manama's core districts are opening last-mile access for frozen dough and par-baked products.
Market Restraints
- Wheat import concentration:Bahrain relies on external milling inputs with limited domestic grain storage, exposing margins to Black Sea and Australian supply volatility.
- Technical shelf-life limitations:Clean-label formulations without chemical preservatives face compressed distribution windows in Bahrain's high-humidity climate.
- Substitution pressure:Fresh bread competes with imported long-life flatbreads from Saudi and UAE producers at lower price points.
Strategic Opportunities
- Muharraq governorate underpenetration:Convenience store density in northern Bahrain lags Manama, creating whitespace for automated micro-bakery installations.
- Regulatory tailwind:Sugar-reduction mandates under Ministry of Health guidelines are opening formulation contracts for alternative sweetener suppliers.
- Technology convergence:Cold chain logistics and e-wallet payment systems are enabling direct-to-consumer frozen pastry subscriptions.
Industry Challenges
- Artisan skill scarcity:Laminated dough specialists and sourdough culture management expertise command premium wages that smaller commercial bakeries cannot absorb.
- Capex intensity:Automated packaging lines compliant with Gulf Standardization Organization traceability requirements demand seven-figure investments.
- Legacy system integration:ERP upgrades for batch tracking and allergen management create downtime risks during peak Ramadan production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Bakery Product Market |
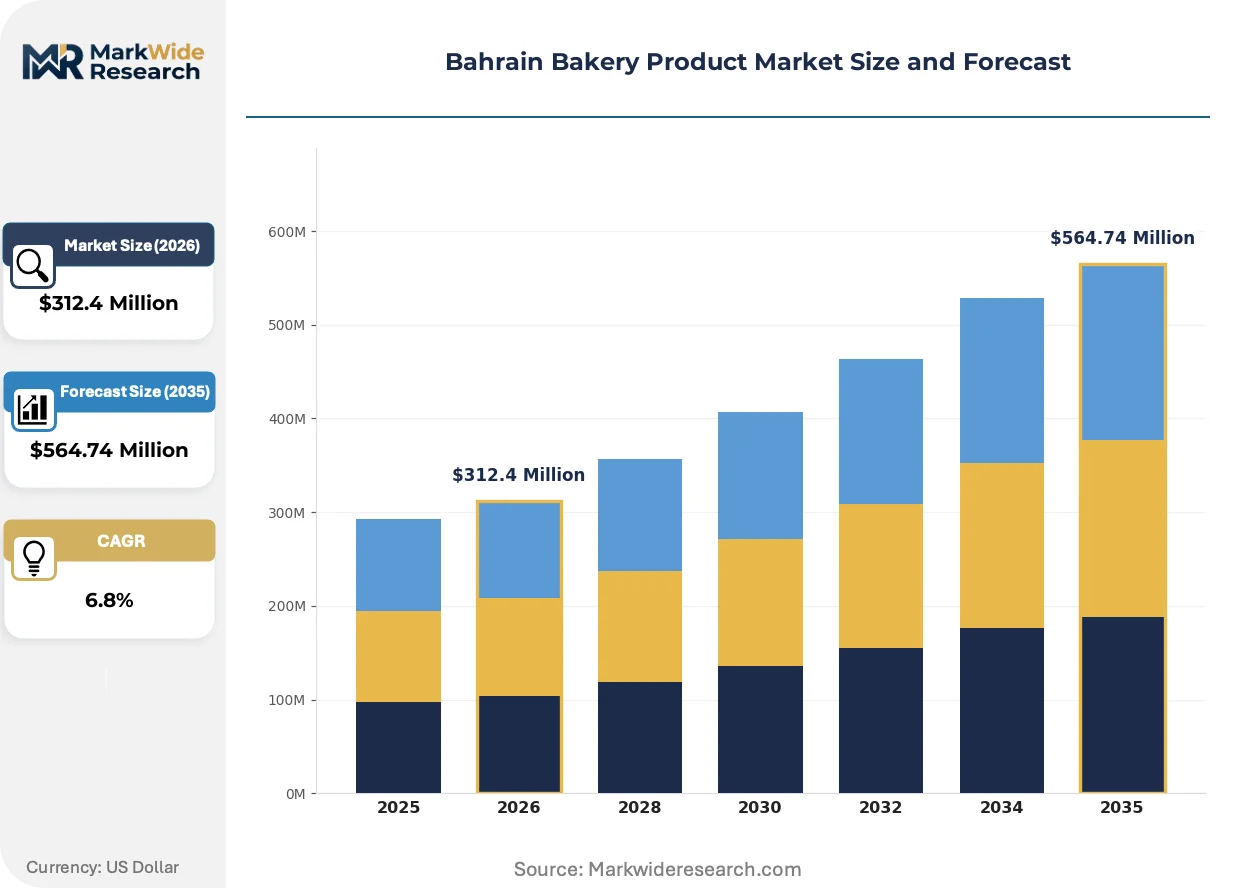
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cookies, Cakes Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Bakeries Customer Type: Retail Consumers, Wholesale Buyers, Food Service, Catering Services Packaging Type: Bags, Boxes, Trays, Wrappings |
| Companies Covered | Kellogg's Company, Eastern Bakery, Mondelez International, Lilou Artisan Patisserie, Grotta Bakery, Almarai Co Ltd, Red Croissant Bakery, Americana Group, PepsiCo Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Bakery Product Market Strategic Shifts
Formulation science and distribution technology are compressing traditional production-delivery timelines while regulatory pressure on ingredient transparency forces recipe restructuring across Bahrain's bakery supply base.
Retarder-prover technology is modularizing fermentation control in commercial bakery operations. Mid-scale producers in Sitra and Riffa are adopting programmable proofing cabinets to stage production across 24-hour cycles. This equipment is modularizing batch scheduling and reducing overnight labor costs without sacrificing artisan texture claims.
Bahrain's national health regulator is tightening enforcement of Gulf Standardization Organization nutritional labeling standards for sodium and added sugar content. Reformulation timelines for traditional khubz recipes now extend 8-12 months for sensory validation. Industrial bakeries serving hotel chains are accelerating clean-label pilot programs to preempt compliance deadlines.
Convenience store operators are consolidating bakery procurement through centralized distribution hubs rather than direct supplier relationships. Smaller-format retail in Askar and Hamad Town is shifting toward frozen-thaw-and-bake models. This pattern is most visible in the Northern Governorate where real estate constraints limit on-site production space.
Bahrain Bakery Product Market Segmentation
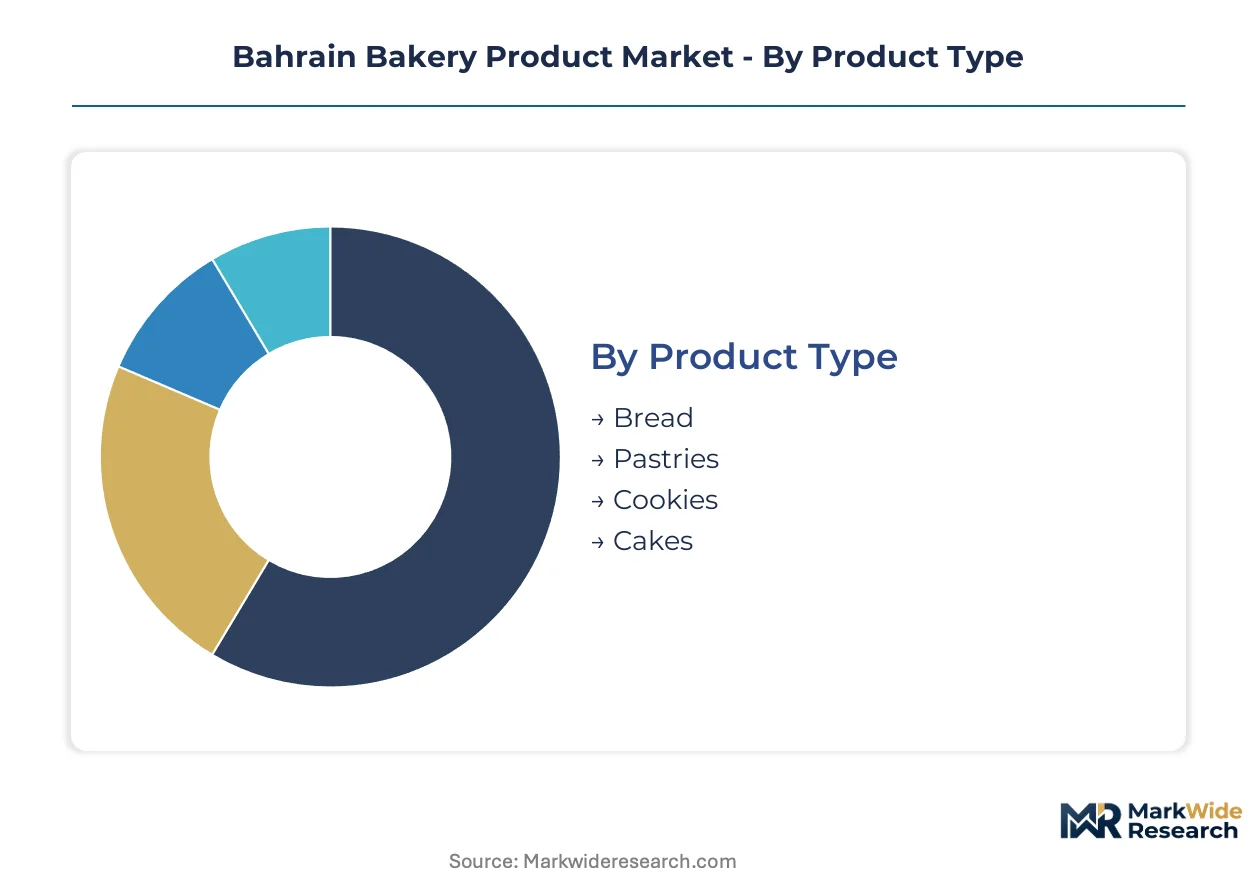
Segmentation in Bahrain's bakery market reveals how capital deployment, regulatory compliance, and channel economics concentrate competitive advantage. Understanding these divides exposes where margin pools form and which operational configurations sustain profitability across Manama's retail corridor and Muharraq's emerging trade zones.
Product Type:
Capital intensity varies sharply across production formats, with fermentation-controlled lines demanding substantially higher upfront investment than ambient-stable alternatives.
- Bread:Automated mixing and retarder-prover systems dominate commercial-scale output. Demand concentrates in Manama's hotel chains and quick-service restaurants, where just-in-time delivery mandates compress procurement cycles and favor suppliers with integrated cold-chain logistics.
- Pastries:Laminated dough production requires specialized sheeting equipment and temperature-controlled environments. Artisan sourdough and premium laminated varieties command premium positioning in the capital governorate's retail corridor, though skill scarcity for laminated dough specialists constrains smaller commercial bakeries.
- Cookies:Ambient-stable formulations suit centralized production with extended distribution windows. Bahrain's national health regulator enforces Gulf Standardization Organization nutritional labeling standards that extend reformulation timelines for traditional recipes.
- Cakes:Custom decoration and shorter shelf-life requirements favor localized production or frozen-import models. Convenience store operators in Askar and Hamad Town increasingly adopt frozen-thaw-and-bake approaches.
Bread absorbs the bulk of installed capacity; pastries are expanding most quickly.
Distribution Channel:
Channel economics reshape supplier relationships, with centralized procurement hubs displacing direct supplier ties in smaller-format retail.
- Supermarkets:Modern retail chains consolidate bakery procurement through integrated dairy-bakery supply chains. Almarai Co Ltd leverages this structure to dominate fresh bread distribution across Manama and Muharraq.
- Online Retail:Digital ordering platforms and e-wallet payment systems enable direct-to-consumer frozen pastry subscriptions beyond Manama's core districts. Cold chain logistics investments separate viable competitors from marginal players.
- Convenience Stores:Northern Governorate real estate constraints limit on-site production space, driving frozen-thaw-and-bake consolidation. Automated micro-bakery installations present whitespace opportunities in underpenetrated Muharraq governorate locations.
- Bakeries:Traditional point-of-sale production persists in heritage districts, though municipal hygiene inspections and Gulf Standardization Organization traceability requirements raise compliance costs.
Supermarkets command the largest revenue share; online retail is climbing the fastest.
Customer Type:
Buyer concentration and contract structures determine working capital requirements and production scheduling flexibility.
- Retail Consumers:Individual purchase patterns favor grab-and-go formats and smaller pack sizes. Convenience store density gaps in northern Bahrain create access challenges for fresh product categories.
- Wholesale Buyers:Volume commitments and standardized specifications suit industrial-scale producers with automated packaging lines compliant with Gulf Standardization Organization requirements.
- Food Service:Hotel chains and quick-service restaurants impose just-in-time delivery mandates that force bakery suppliers to reconfigure production schedules around compressed procurement cycles.
- Catering Services:Event-driven demand spikes require flexible capacity and rapid scaling capabilities, favoring producers with retarder-prover technology for 24-hour batch staging.
Food service locks in the longest contract tenors; catering services show the steepest expansion trajectory.
Packaging Type:
Material specifications and sustainability mandates increasingly influence sourcing decisions and cost structures.
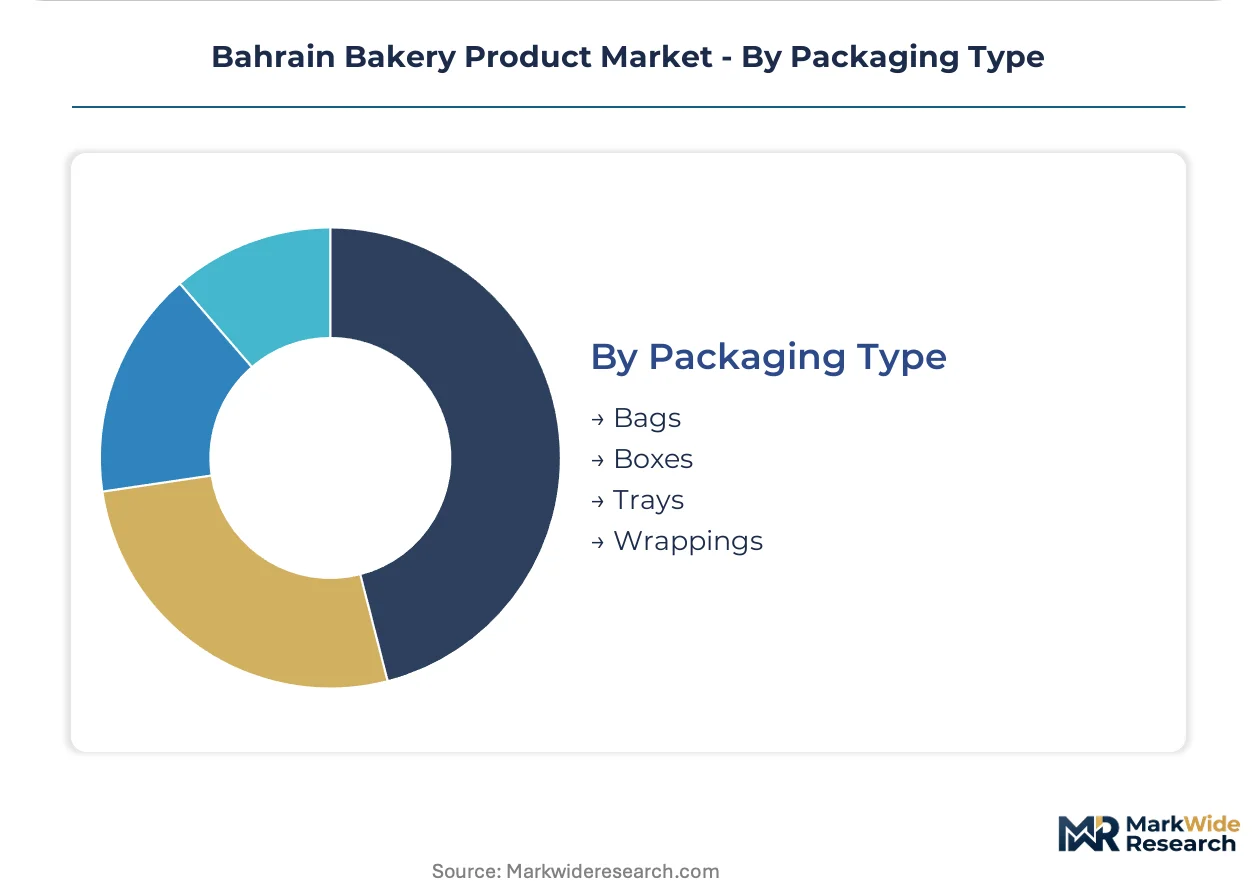
- Bags:Primary packaging for bread and ambient-stable products, with polyethylene and paper-based alternatives competing on moisture barrier performance and recyclability credentials.
- Boxes:Structural protection for cakes and premium pastries, where presentation quality influences retail positioning in modern trade channels.
- Trays:Display-oriented formats for convenience store and supermarket bakery sections, requiring shelf-life extension through modified atmosphere sealing.
- Wrappings:Individual portion control for food service and catering applications, with Gulf Standardization Organization alignment driving standardization across imported and domestic supply.
Bags constitute the highest volume application; boxes are gaining share fastest on premiumization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama's retail corridor concentrates the highest bakery consumption intensity, while Muharraq and the Northern Governorate represent underpenetrated expansion zones where convenience store density and automated micro-bakery deployment lag the capital.
Capital Governorate
Hotel chains and quick-service restaurants in Manama compress procurement cycles through just-in-time delivery mandates. The Ministry of Industry and Commerce oversees commercial registration for wheat import licensing that shapes supplier market access. Artisan sourdough and laminated dough varieties command premium positioning across Seef and Adliya districts.
Muharraq Governorate
Convenience store density in northern Bahrain trails Manama by a significant margin, creating whitespace for frozen-thaw-and-bake consolidation. Municipal hygiene inspections enforce Gulf Standardization Organization traceability requirements across production facilities. Automated micro-bakery installations present expansion opportunities in underpenetrated retail corridors.
Northern Governorate
Real estate constraints in Askar and Hamad Town limit on-site production space, driving centralized distribution hub adoption. The national health regulator enforces nutritional labeling standards for sodium and added sugar content that extend reformulation timelines. Smaller-format retail increasingly shifts toward par-baked and frozen dough models.
Southern Governorate
Industrial bakeries serving catering services and event-driven demand require flexible capacity scaling through retarder-prover technology. Gulf Standardization Organization alignment on shelf-life labeling reduces cross-border friction for imported milling inputs. Sitra and Riffa production clusters adopt programmable proofing cabinets for 24-hour batch staging.
Bahrain Bakery Product Market Competitive Environment
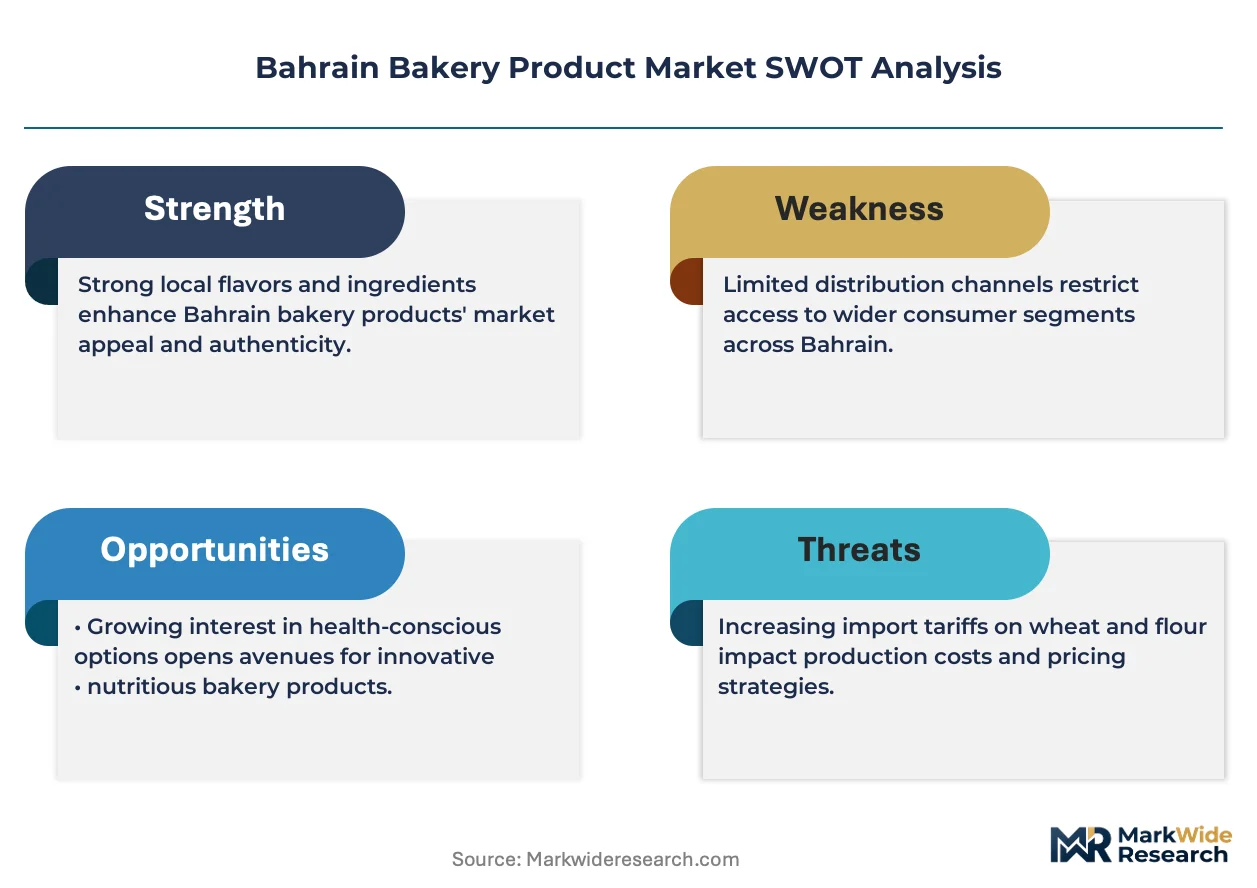
Capacity expansion dominates the current landscape as suppliers reconfigure production schedules around compressed procurement cycles from quick-service restaurants and hotel chains. The vendor base stratifies across integrated dairy-bakery supply chains, regional artisan specialists, and multinational packaged goods operators. Three strategic archetypes prevail: vertically integrated fresh bread distributors, premium laminated dough artisans, and ambient-stable biscuit manufacturers. M&A activity and cold chain logistics investments separate viable competitors from marginal players.
Within the integrated supply chain tier, Almarai Co Ltd leverages its dairy-bakery infrastructure to anchor fresh bread distribution through modern retail channels. Mondelez International occupies a position exemplifying multinational packaged goods concentration in premium biscuit segments. Eastern Bakery represents the localized specialist archetype, competing through heritage recipe adaptation rather than scale economies.
| Leading Market Players |
|---|
| Kellogg's Company |
| Eastern Bakery |
| Mondelez International |
| Lilou Artisan Patisserie |
| Grotta Bakery |
| Almarai Co Ltd |
| Red Croissant Bakery |
| Americana Group |
| PepsiCo Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive milling operations anchors Almarai Co Ltd's supply position and pricing power across Bahrain's fresh bread segment. This structural choice insulates margin pools from wheat import volatility while compressing procurement cycles for quick-service restaurant clients.
Pricing Analysis
Volume throughput concentrates in standardized khubz and sandwich bread formats where per-unit margins compress under Saudi and UAE import competition. Premium-mid-economy pricing differentiation separates artisan sourdough and laminated pastries in Manama's retail corridor from commodity flatbreads in convenience channels. Cost compression in the economy tier intensifies because Black Sea supply disruptions feed directly into landed wheat costs. Food service buyers exhibit lowest price sensitivity due to just-in-time delivery mandates and quality specifications.
Supply Chain Analysis
Single-source vulnerability sits with Australian and Black Sea wheat origins that Bahrain's milling sector draws from exclusively. Milling inputs, vegetable shortening, and paper-based packaging materials rest on import channels through Jebel Ali and Dammam port hubs. Tariff exposure runs through Gulf Cooperation Council customs alignment shifts that could reclassify bakery ingredient duties. Distribution runs through Almarai's integrated dairy-bakery cold chain and third-party logistics networks serving Northern Governorate convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's bakery sector constitutes a consolidation play where automated packaging compliance costs and retarder-prover technology investments force sub-scale artisan operations toward acquisition or exit.
For Market Incumbents: Cement market position by acquiring laminated dough specialists in Muharraq to preempt skill scarcity premiums, while upgrading ERP systems for Gulf Standardization Organization batch traceability before Ramadan peak cycles expose downtime risks. Almarai's integrated supply chain model demonstrates how backward integration into milling buffers margin pressure from import volatility. For New Entrants and Emerging Players: Capture whitespace in automated micro-bakery installations across underpenetrated Northern Governorate convenience corridors, where real estate constraints block on-site production and frozen-thaw-and-bake consolidation creates service gaps. Direct-to-consumer frozen pastry subscriptions enabled by e-wallet payment systems offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Gulf dairy-bakery groups seeking Bahraini manufacturing footprints. Five-to-ten year viability favors targets with retarder-prover technology and existing quick-service restaurant contract tenors. The signal to watch is Ministry of Health sugar-reduction mandate enforcement timelines that will force reformulation capex on legacy producers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Micro-Bakery Deployment | Addresses Northern Governorate convenience store density gaps without on-site production real estate. |
| Cold Chain Logistics Investment | Separates viable frozen dough competitors from marginal players in direct-to-consumer channels. |
| Clean-Label Reformulation Program | Preempts Gulf Standardization Organization sodium and added sugar enforcement deadlines. |
| Retarder-Prover Technology Adoption | Enables 24-hour batch staging for catering services and Ramadan demand spikes in Sitra clusters. |
| Integrated Dairy-Bakery Supply Chain Expansion | Replicates Almarai's margin insulation model through captive milling and distribution control. |
Study Parameters
Independent corroboration across bakery operations managers, quick-service restaurant procurement leads, and Ministry of Industry and Commerce licensing officials underwrites the qualitative findings. Secondary validation draws from Gulf Standardization Organization technical regulations, Bahrain customs wheat import records, and modern retail chain category management disclosures. Bottom-up capacity estimates from Sitra and Riffa production clusters triangulate against top-down consumption models derived from supermarket and convenience store channel audits.
Comparable historical periods anchored the projection framework to pre-pandemic baseline demand patterns and post-recovery channel shifts across the analysis window. Segmentation dimensions span product type, distribution channel, customer archetype, and packaging format, with CAGRs derived from elasticity-adjusted volume projections and value-per-unit trend extrapolation. Wheat import price volatility coefficients and humidity-adjusted shelf-life degradation curves inform scenario boundaries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf Cooperation Council customs policy shifts and Ministry of Health reformulation mandate timing. Forecasts reflect documented assumptions about quick-service restaurant expansion rates and digital ordering platform penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Europe Bakery Products Market
Bakery Products
Fondant Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Bread Mix Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Flatbread Market
Bakery Products
Biscuits Market
Bakery Products
Pizza Crust Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Cake Base Discs Market
Bakery Products
Teaseed Cake Market