
 Global Premium Gin Market | 2026-2036
Global Premium Gin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premium Gin Market Outlook
The gap between premium and commodity gin is restructuring around botanical sourcing transparency and provenance verification rather than price alone. William Grant & Sons leverages its Scottish distillation heritage to command shelf positioning in duty-free channels. Diageo sustains global volume through controlled distribution networks spanning multiple continents. Pernod Ricard differentiates via terroir-specific botanical programs that anchor consumer willingness to trade up.
Premium gin denotes a juniper-forward spirit distilled with select botanicals, typically bottled at 37.5% to 57% ABV, and distinguished by batch production methods that emphasize flavor complexity over neutral alcohol efficiency. Its primary commercial purpose is to capture margin in the spirits category through brand storytelling and mixology credibility in both on-premise and retail environments. London Dry maintains volume leadership due to its regulatory-defined production standards that signal authenticity to consumers. Citrus and herbal flavor profiles are expanding fastest as bartenders drive cocktail menu innovation. The glass bottle packaging segment still occupies the dominant margin pool, though eco-friendly alternatives are gaining shelf space in European supermarkets.
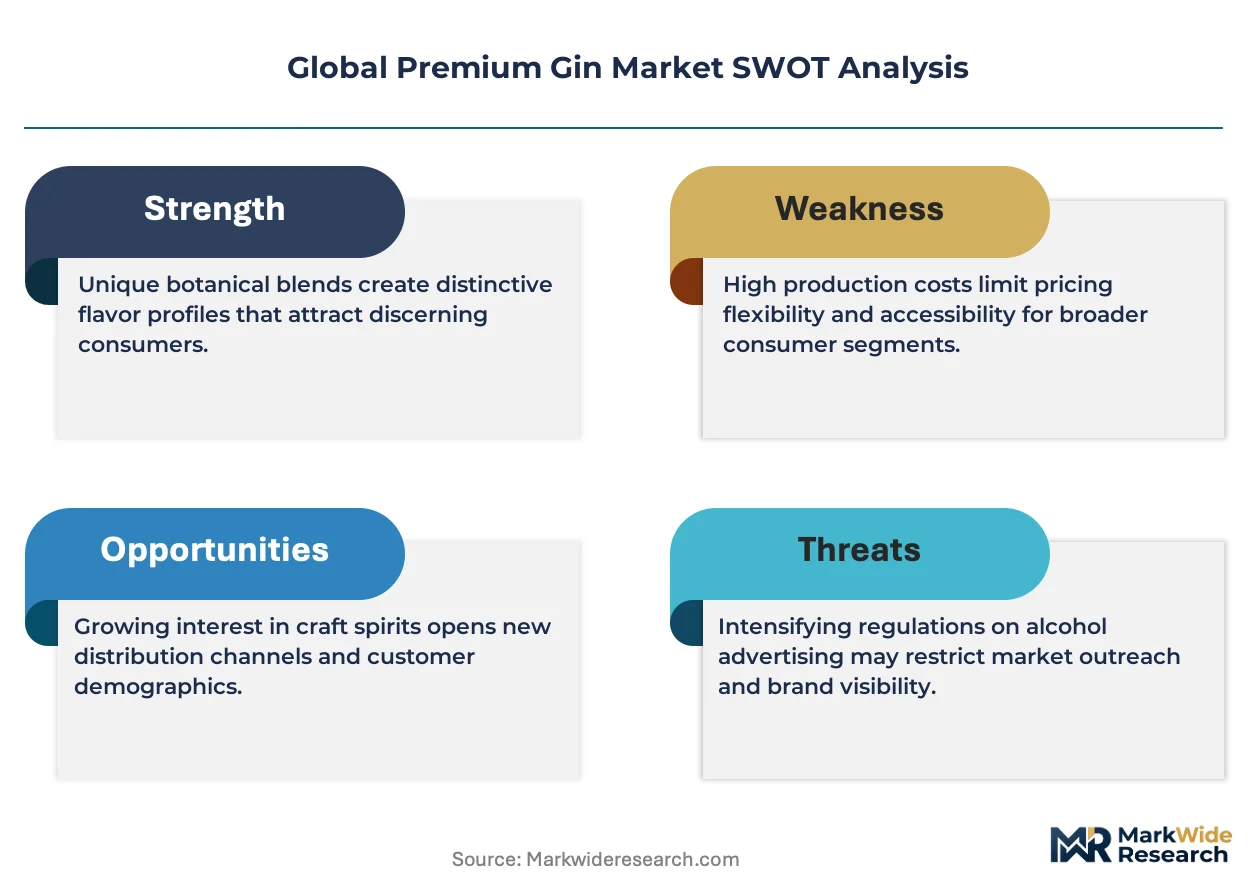
The EU's spirit drinks regulation framework, alongside FDA labeling requirements in the United States and EFSA health claim oversight, creates compliance thresholds that favor established distillers with dedicated regulatory affairs capacity. These bodies shape demand by defining what constitutes authentic gin versus flavored neutral spirit, directly affecting market access and premium pricing justification. Stakeholders must monitor evolving low-and-no-alcohol tax classifications and carbon border adjustments affecting glass and botanical supply chains.
Market Dynamics
The EU's spirit drinks regulation framework is compressing production methods across distilleries, forcing batch-process authenticity verification as the primary competitive differentiator in shelf positioning and export licensing.
Growth Catalysts
- On-premise mixology credentialing:Bartenders in London, Barcelona, and Berlin are driving super-premium adoption through cocktail menu innovation that demands complex botanical profiles. This channel validates trade-up willingness before retail expansion.
- REACH-compliant botanical traceability:EU chemical registration requirements are creating compliance moats for established distillers with dedicated regulatory affairs capacity. Smaller competitors face barrier-to-entry expansion.
- Low-and-no-alcohol distillation methods:Vacuum distillation and dealcoholization technologies are opening adjacent category positioning. These methods capture health-conscious consumers without sacrificing brand equity.
Market Restraints
- Juniper berry supply concentration:Wild harvesting in Macedonia, Bulgaria, and Albania dominates raw material sourcing. Climate volatility and foraging labor shortages create input cost instability.
- Glass packaging carbon border exposure:EU carbon border adjustment mechanisms targeting imported glass bottles are squeezing margin structures for distilleries without captive furnace partnerships.
- Flavor-neutral spirit substitution:Compound gin production using purchased ethanol and synthetic flavoring undercuts authentic distillation economics in price-sensitive retail channels.
Strategic Opportunities
- Indian metropolitan duty-free penetration:Mumbai, Delhi, and Bangalore airports show underdeveloped premium spirits allocation relative to passenger affluence curves. Diageo and Pernod Ricard are expanding travel retail exclusives.
- CSRD-aligned sustainability storytelling:EU corporate sustainability reporting requirements create regulatory tailwinds for carbon-negative botanical programs and regenerative agriculture partnerships that command shelf premium.
- Direct-to-consumer subscription channels:Limited-edition releases and tasting club models bypass traditional three-tier distribution constraints in the United States and United Kingdom.
Industry Challenges
- Master distiller talent scarcity:Traditional apprenticeship pipelines in Scotland and Netherlands are failing to replace retiring expertise. Technical knowledge transfer lags behind production capacity expansion.
- Multi-jurisdiction label approval timelines:FDA, EFSA, and national regulator submissions for new botanical expressions require 18-24 month compliance cycles that compress innovation-to-market velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premium Gin Market |
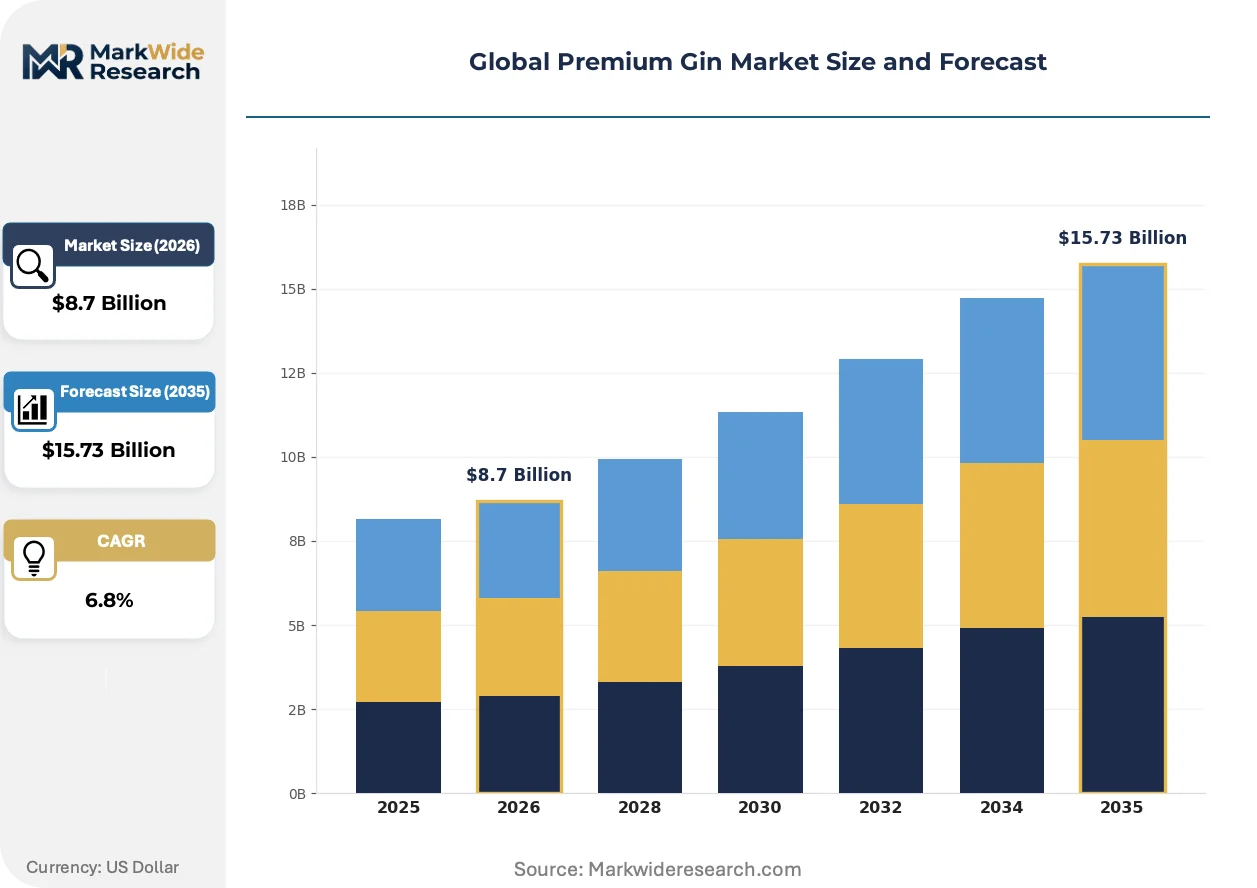
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: London Dry, Old Tom, Sloe, Navy Strength Flavor Profile: Citrus, Herbal, Spiced, Floral Packaging Type: Glass Bottle, Canned, Eco-Friendly, Miniature Sales Channel: Online, Liquor Stores, Supermarkets, Bars |
| Companies Covered | William Grant & Sons, Lucas Bols, Diageo, Beam Suntory, Davide Campari-Milano, Bacardi, Suntory, Sipsmith, Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premium Gin Market Strategic Shifts
Batch production methods are fragmenting competitive positioning, with regulatory-defined authenticity standards now separating premium from commodity offerings more decisively than price architecture.
Vacuum distillation technology is unifying low-alcohol and full-strength production lines within single facilities. William Grant & Sons and smaller Scottish craft distillers are adopting these hybrid systems to capture health-conscious segments without duplicating capital infrastructure. This convergence is compressing the traditional separation between premium and no-alcohol supply chains.
EU spirit drinks regulation revisions are mandating stricter botanical sourcing disclosure and prohibiting certain flavor additives previously common in compound gin. Distillers with established provenance documentation systems are capturing shelf space as retailers face liability exposure from non-compliant suppliers. Germany and Spain are showing the fastest compliance adaptation curves among major markets.
Consumer verification behaviors are shifting toward blockchain-anchored provenance checking. United Kingdom supermarkets and specialist retailers are piloting QR-linked batch records that disclose harvest dates, distillation runs, and botanical origins. This transparency expectation is most visible among London and Edinburgh urban demographics with disposable income above category median.
Global Premium Gin Market Segmentation
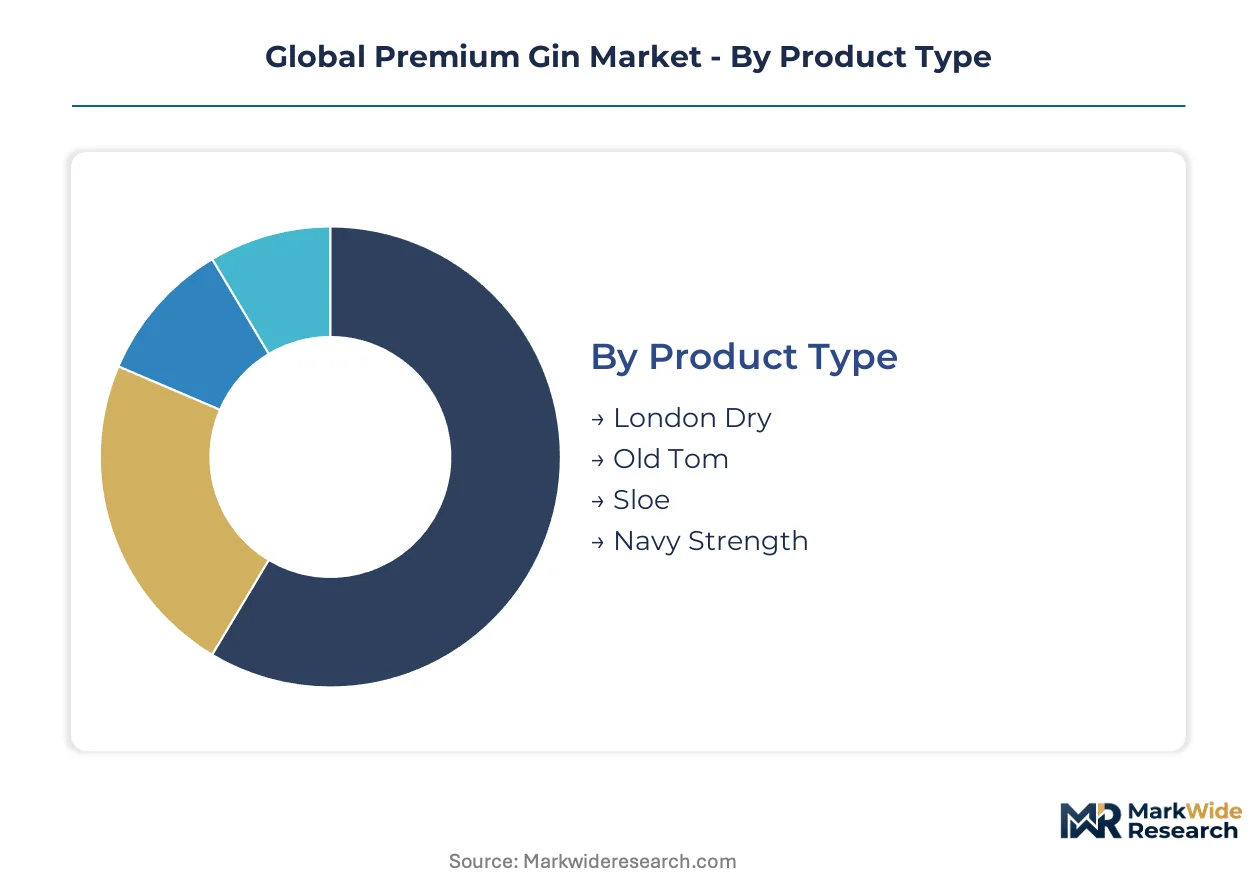
Premium gin segmentation separates volume-driven heritage formats from emerging expressions that command trade-up pricing through botanical complexity and packaging innovation. Distillers configure production assets around these divisions to optimize margin capture across channel tiers.
Product Type:
London Dry anchors volume throughput while craft formats capture super-premium shelf positioning through batch authenticity signaling.
- London Dry:Juniper-forward spirit produced under strict EU regulatory protocols prohibiting post-distillation additives. United Kingdom on-premise channels validate authenticity before retail expansion into Germany and Spain.
- Old Tom:Historically sweetened style experiencing revival through bartender-driven cocktail programs. Barcelona and Berlin mixology scenes concentrate current demand for this heritage format's versatility in stirred drinks.
- Sloe:Fruit-infused variant with seasonal production constraints.
- Navy Strength:High-ABV expression bottled at 57% minimum.
Mature deployment sits with London Dry. Newer deployment is concentrated in Old Tom.
Flavor Profile:
Botanical differentiation now drives trade-up willingness more decisively than base spirit provenance alone.
- Citrus:Bright, peel-forward formulations from Mediterranean botanicals. Bartenders in London and Barcelona favor these profiles for summer cocktail menus and spritz-style serves.
- Herbal:Complex expressions incorporating indigenous European botanicals like sage, rosemary, and thyme. German specialist retailers report strongest consumer receptivity for terroir-specific herbal programs.
- Spiced:Warming profiles with cardamom, cassia, and pepper notes.
- Floral:Delicate expressions featuring rose, lavender, and elderflower.
Citrus profiles dominate current mixology adoption. Herbal expressions show steepest expansion trajectory among connoisseur segments.
Packaging Type:
Glass maintains margin leadership while sustainability pressures reshape European supermarket procurement criteria.
- Glass Bottle:Traditional format commanding premium shelf positioning through weight, closure quality, and label embossing. United Kingdom duty-free channels allocate disproportionate space to heritage glass presentations.
- Eco-Friendly:Lightweight and recycled-content alternatives gaining traction. German and Spanish retailers pilot these formats under CSRD-aligned sustainability mandates affecting supplier selection.
- Canned:Single-serve format for outdoor and festival occasions.
- Miniature:Trial-size packaging for airline and hotel minibars.
Glass bottle deployment saturates established markets. Eco-friendly alternatives concentrate in German and Spanish retail channels.
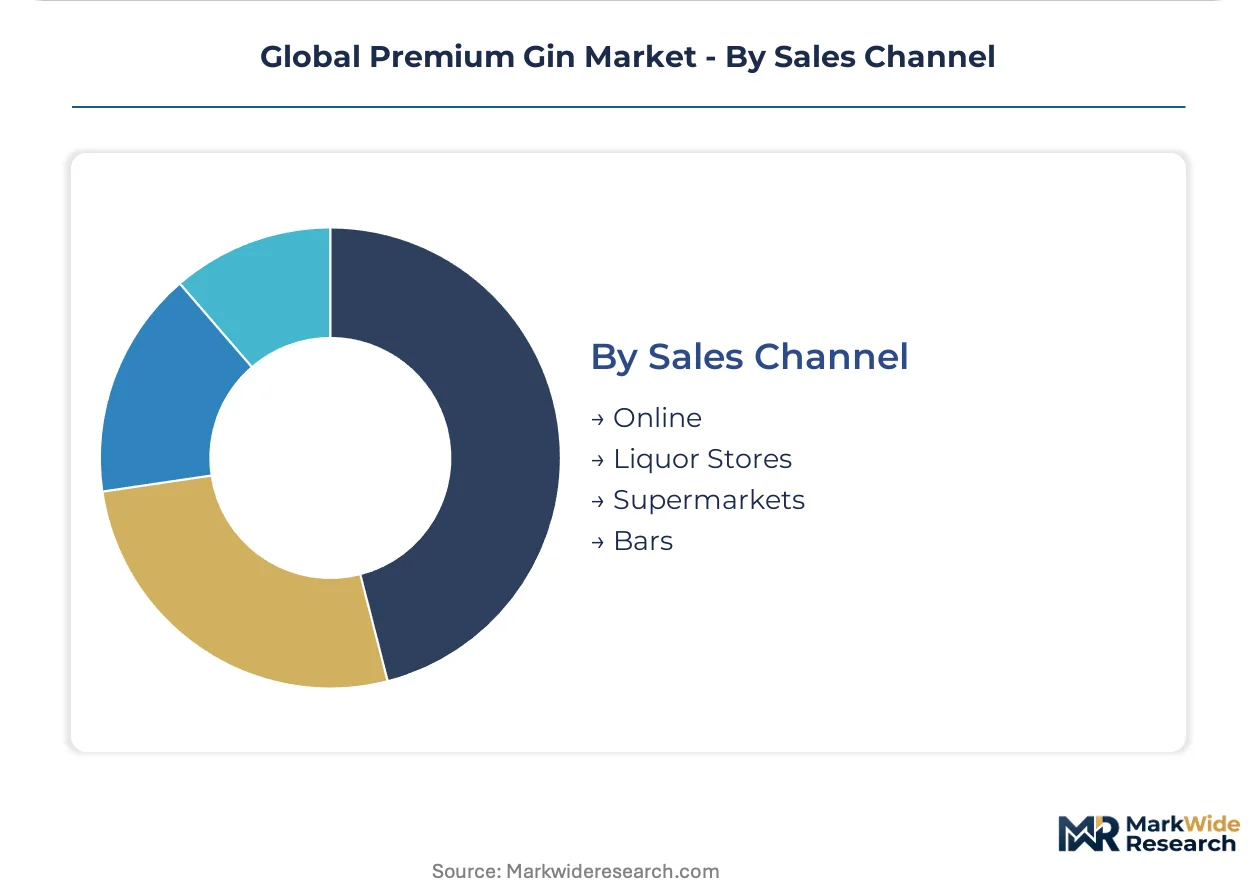
Sales Channel:
Channel strategy separates validation-driven on-premise adoption from volume-scaling retail penetration.
- Bars:Primary credentialing channel where bartender endorsement validates botanical complexity and justifies trade-up pricing. London, Barcelona, and Berlin concentrate super-premium adoption velocity.
- Online:Direct-to-consumer and aggregator platforms expanding fastest in United Kingdom and Germany. Subscription models and limited releases bypass traditional three-tier constraints.
- Liquor Stores:Specialist retail with educated staff driving premium conversion.
- Supermarkets:Volume channel where price architecture and promotional mechanics dominate.
Bar channel deployment anchors brand credibility. Online expansion is gaining share fastest among urban demographics with above-median disposable income.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors super-premium gin adoption through bartender-driven mixology credentialing that validates trade-up pricing before retail expansion. The United Kingdom, Spain, and Germany concentrate demand velocity, with EU spirit drinks regulation and national sustainability mandates reshaping competitive positioning across production and distribution channels.
United Kingdom
London's on-premise bar scene drives super-premium validation through cocktail menu innovation demanding complex botanical profiles. The UK's Food Standards Agency enforces strict labeling protocols under retained EU spirit drinks regulation. Edinburgh and Scottish Lowlands distilleries leverage heritage provenance to command duty-free shelf positioning.
Spain
Barcelona's mixology culture concentrates Old Tom revival demand and citrus-forward expression adoption. Spanish food safety regulator AESAN implements EU-aligned spirit drinks frameworks with accelerated compliance timelines. Basque Country and Madrid metropolitan areas show fastest specialist retail expansion for terroir-specific herbal programs.
Germany
Berlin bartenders validate super-premium botanical complexity through stirred cocktail programs and sustainability-focused procurement. Germany's Federal Ministry of Food and Agriculture enforces REACH-compliant botanical traceability requirements. Bavaria and North Rhine-Westphalia specialist retailers report strongest consumer receptivity for CSRD-aligned eco-friendly packaging alternatives.
United States
New York and Los Angeles metropolitan areas concentrate on-premise mixology credentialing that drives super-premium trade-up willingness. The FDA maintains 18-24 month label approval timelines for new botanical expressions that compress innovation-to-market velocity. California and Texas direct-to-consumer subscription channels bypass traditional three-tier distribution constraints.
India
Mumbai, Delhi, and Bangalore airports show underdeveloped premium spirits allocation relative to passenger affluence curves. The Food Safety and Standards Authority of India (FSSAI) governs import licensing and labeling requirements for international spirits. Maharashtra and Karnataka urban demographics drive fastest online aggregator platform adoption for limited-edition releases.
Global Premium Gin Market Competitive Environment
Premium-margin players sit above commodity-margin players across botanical sourcing transparency and provenance verification rather than price architecture alone. The vendor base clusters around heritage distillers with regulatory affairs capacity, scale-driven multinational spirits houses, and craft specialists leveraging batch authenticity signaling. Three archetypes dominate: Scottish heritage houses with duty-free channel control, diversified global portfolios with multi-continent distribution networks, and terroir-focused craft distillers with direct-to-consumer reach. Competitive moves concentrate on M&A for botanical supply security and hybrid vacuum distillation technology licensing.
Within the heritage distiller archetype, William Grant & Sons leverages Scottish provenance to anchor duty-free shelf positioning. Diageo and Pernod Ricard exemplify scale-driven multinational structures with controlled distribution spanning multiple continents and travel retail exclusives. These three occupy positions where regulatory compliance capacity and botanical traceability systems create defendable margin tiers against compound gin substitution.
| Leading Market Players |
|---|
| William Grant & Sons |
| Lucas Bols |
| Diageo |
| Beam Suntory |
| Davide Campari-Milano |
| Bacardi |
| Suntory |
| Sipsmith |
| Pernod Ricard |
| Others |
Value Chain & Pricing Dynamics
Juniper berry spot indices from Macedonian and Bulgarian harvest cooperatives cascade through distillation economics into three-tier pricing structure across premium, standard, and economy levels. REACH-compliant botanical traceability costs compress margins at the craft tier while heritage houses absorb compliance overhead through duty-free channel premiums.
Pricing Analysis
Botanical complexity and provenance verification anchor value-based pricing tiers rather than alcohol content alone. Price differentiation rests on batch authenticity documentation and terroir-specific sourcing programs versus compound gin substitution. Pricing pressure stems from carbon border adjustment exposure on imported glass packaging. Super-premium buyers show lowest price sensitivity; price-conscious retail channels drive fastest volume erosion.
Supply Chain Analysis
Three-tier distribution channels handle United States volume while direct-to-consumer platforms bypass traditional constraints in United Kingdom and Germany. Wild juniper harvesting concentrates in Macedonia, Bulgaria, and Albania with climate volatility creating input instability. Glass furnace partnerships in Germany and Spain mitigate carbon border risks. Supply chain vulnerability centers on single-source botanical dependency and foraging labor shortages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU spirit drinks regulation and REACH botanical traceability create compliance moats that favor established distillers with dedicated regulatory affairs capacity. The cost-of-compliance story rewards players who invested early in provenance documentation systems.
For Market Incumbents: Extend batch authenticity verification systems into blockchain-anchored consumer interfaces before regulatory mandates harden. Acquire juniper supply security through long-term foraging cooperative contracts in Macedonia and Bulgaria. Vacuum distillation technology licensing offers hybrid production line consolidation against craft competitor capacity expansion. For New Entrants and Emerging Players: Capture underdeveloped Indian duty-free allocation at Mumbai, Delhi, and Bangalore airports through travel retail exclusives. Target direct-to-consumer subscription channels in California and Texas where three-tier constraints weakest. Lead with CSRD-aligned sustainability storytelling to differentiate against heritage houses with legacy carbon footprints. For Investors and Strategic Acquirers: The window for entry favors craft distillers with established botanical traceability systems and hybrid vacuum distillation infrastructure. Long-term viability hinges on regulatory compliance capacity rather than brand nostalgia alone. Watch for EU carbon border adjustment implementation on glass imports as margin compression trigger for non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Supply Security Agreement | Long-term juniper contracts with Macedonian foraging cooperatives lock input cost stability. |
| Hybrid Vacuum Distillation Deployment | Unified production lines capture low-alcohol segments without duplicative capital infrastructure. |
| Blockchain Provenance Integration | QR-linked batch records meet United Kingdom retailer transparency mandates and consumer verification. |
| CSRD-Aligned Sustainability Certification | Carbon-negative botanical programs command German supermarket shelf premium under reporting requirements. |
| Indian Duty-Free Channel Expansion | Mumbai and Delhi airport allocation gaps relative to passenger affluence offer first-mover positioning. |
Study Parameters
Independent corroboration across master distillers, regulatory affairs directors, and on-premise beverage managers underwrites the qualitative findings. Secondary validation draws from EU spirit drinks regulation filings, ECHA REACH registration databases, and United Kingdom Food Standards Agency enforcement records. Bottom-up production capacity estimates triangulate against top-down channel volume assessments across the analysis window.
Comparable historical reference periods anchor volume and value projections throughout the forecast period. Segmentation dimensions span product type, flavor profile, packaging format, and sales channel with regional regulatory cluster overlays. CAGRs derive from trend extrapolation moderated by input cost volatility and compliance timeline assumptions. Juniper harvest yield variability and glass packaging carbon border exposure feed sensitivity analyses.
The model holds under stable EU regulatory enforcement; deviation in REACH implementation timelines or carbon border adjustment scope would shift competitive positioning. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
N-Hexyl Alcohol Market