
 Beer Keg System Market | 2026-2036
Beer Keg System Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Keg System Market Outlook
The EU Green Deal and national deposit-return mandates is pivoting European brewers toward reusable stainless steel kegs over single-use alternatives. Blefa GmbH leverages its German manufacturing base to dominate reusable stainless steel supply for premium European brands. THIELMANN - The Container Company anchors its position through advanced welding automation that cuts production cycle times. American Keg Company competes on domestic sourcing, sustaining tariff-advantaged delivery to U.S. craft breweries.
A beer keg system comprises pressurized vessels, tapping mechanisms, couplers, and regulators engineered to store, transport, and dispense carbonated beverages while maintaining CO₂ equilibrium at 10-12 psi serving pressure. Stainless steel kegs withstand hundreds of cleaning and refill cycles, making them the standard for commercial draft operations. Kegs command the largest product share due to replacement cycles tied to inspection intervals, while mini kegs represent the fastest-growing size segment as home draft systems gain traction. Plastic kegs carve a niche in event and outdoor applications where weight reduction outweighs durability concerns.
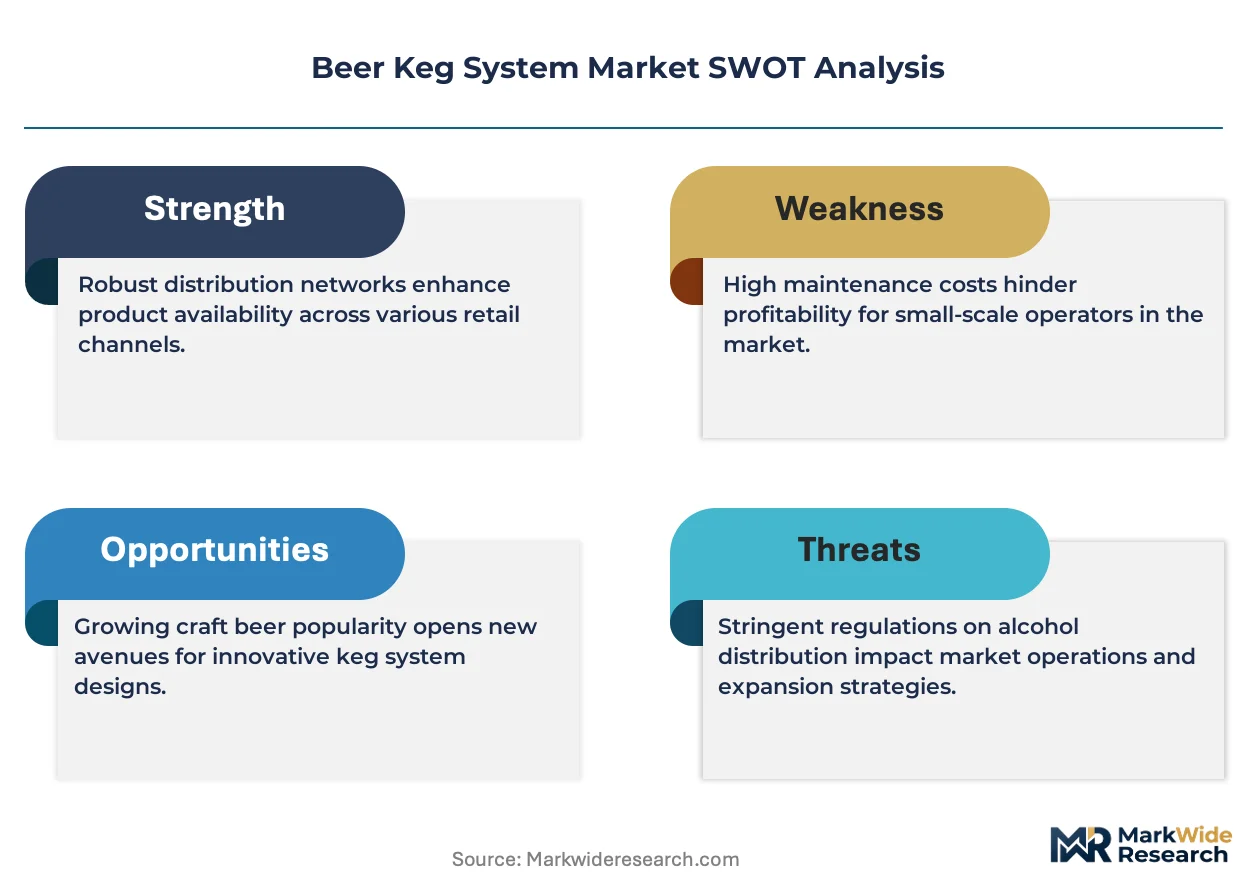
Germany's national packaging ordinance enforces strict deposit-return compliance, forcing keg manufacturers to embed tracking technology and standardize valve interfaces. The U.S. FDA regulates food-contact surfaces under 21 CFR, while OSHA mandates pressure vessel handling protocols that shape workplace training and equipment design. Buyers must weigh total cost of ownership against upfront capital outlay as regulatory compliance costs escalate across both European and North American markets.
Market Dynamics
The EU Green Deal's packaging waste mandates are forcing brewers to abandon single-use plastic kegs, triggering a wholesale infrastructure pivot toward reusable stainless steel systems with embedded tracking technology.
Growth Catalysts
- Deposit-return mandates:Germany's national packaging ordinance enforces strict keg tracking and valve standardization, creating compliant supply bottlenecks that favor established manufacturers.
- Craft brewery expansion:Small-batch brewers across the United States are installing direct-draw systems, driving demand for sixth-barrel and slim quarter keg formats.
- Welding automation:Robotic seam welding cuts production cycle times for stainless steel vessels, compressing delivery windows for premium European brands.
Market Restraints
- Nickel price volatility:Stainless steel input costs swing with London Metal Exchange nickel futures, squeezing margin predictability for keg fabricators.
- German supply concentration:Blefa GmbH and THIELMANN dominate reusable stainless steel output, creating single-source vulnerability for craft brewers seeking rapid scale.
- Pressure vessel certification:EU PED 2014/68/EU compliance timelines stretch 14-18 months for new keg designs, freezing product iteration cycles.
Strategic Opportunities
- Home draft systems:Mini keg formats for residential use remain underpenetrated in Japan and South Korea, where apartment-dwelling consumers seek premium beer experiences.
- IoT-enabled fleet management:RFID and cellular tracking convergence allows brewers to optimize keg utilization rates and reduce loss.
- American Keg Company's tariff advantage:Domestic U.S. sourcing shields craft brewery buyers from Section 301 duty exposure on imported vessels.
Industry Challenges
- CO₂ system integration:Brewers struggle to align legacy dispensing infrastructure with new keg valve interfaces mandated by German standardization rules.
- Inspection technician shortage:Qualified pressure vessel inspectors are scarce in emerging craft brewing clusters, delaying keg return-to-service cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Keg System Market |
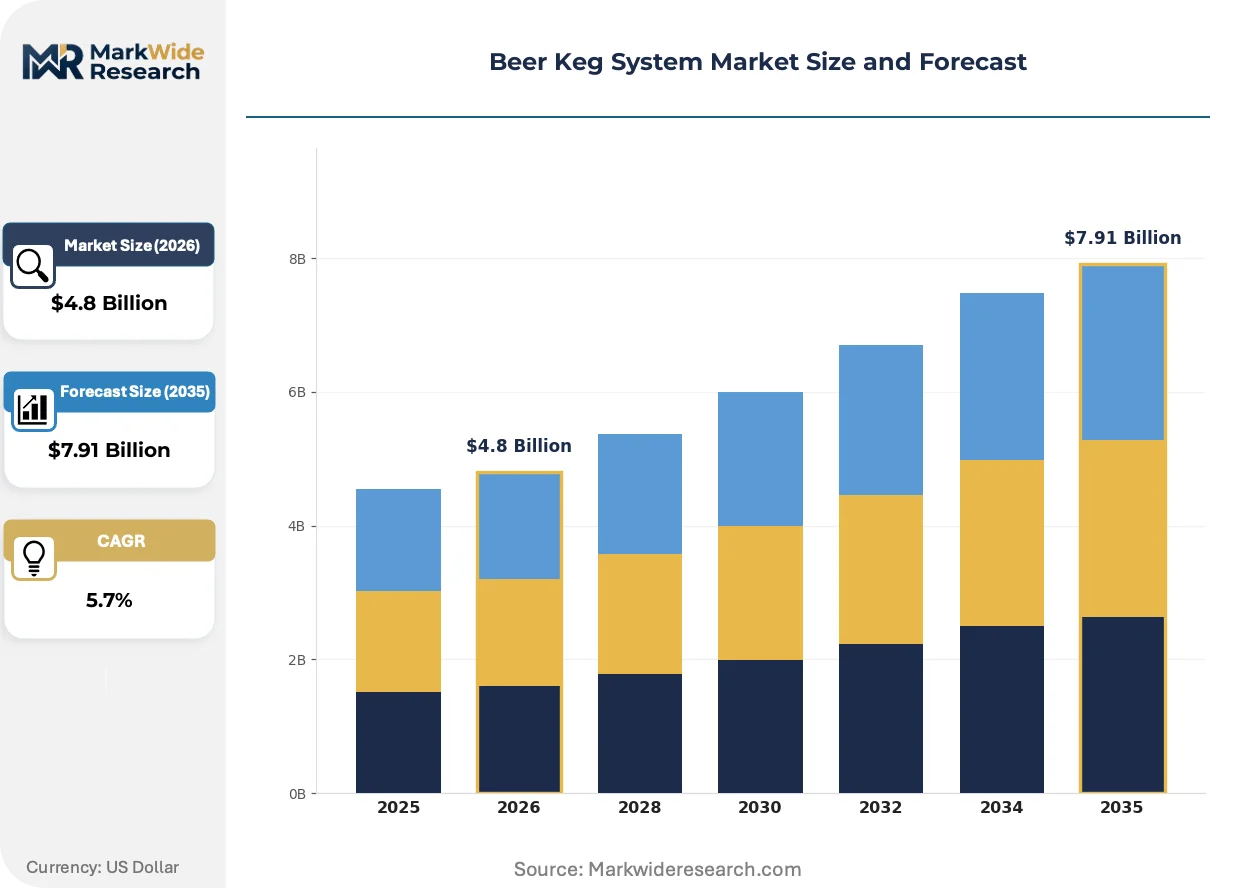
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kegs, Taps, Couplers, Regulators End User: Pubs, Restaurants, Breweries, Events Material: Stainless Steel, Plastic, Aluminum, Hybrid Size: Quarter Barrel, Half Barrel, Full Barrel, Mini Kegs |
| Companies Covered | Blefa GmbH, American Keg Company, THIELMANN - The Container Company, NDL Keg Inc., Schaefer Container Systems, Shinhan Industrial Co., Ltd., Petainer, Ningbo BestFriends Beverage Containers Co., Ltd., Julius Kleemann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Keg System Market Strategic Shifts
Smart keg technology and regulatory packaging mandates are compressing replacement cycles while fragmenting procurement patterns across on-premise and off-premise channels.
RFID-enabled keg tracking is converging with cloud-based fleet management platforms to deliver real-time location and fill-level data. Mid-sized craft breweries in Belgium and the Netherlands are adopting these systems fastest, seeking to reduce keg loss rates that previously consumed 8-12% of fleet value annually. The technology is converging with traditional asset management to create subscription-based keg pooling services that displace direct ownership models.
REACH chemical restrictions and EU Green Deal circular economy targets are banning certain polymer linings in disposable kegs. This regulatory pressure forces event-focused brewers toward lightweight aluminum alternatives or returnable stainless steel logistics. Outdoor festival operators in France and Spain face the steepest compliance cliffs, accelerating vendor transitions before 2027 enforcement deadlines.
Direct procurement from keg manufacturers is displacing traditional distributor intermediaries among U.S. craft breweries with volumes above 10,000 barrels annually. These buyers now negotiate specification customization and extended warranty terms directly with fabricators. The shift is most visible in Colorado and Oregon, where brewery density supports manufacturer sales office investments and same-day technical service dispatch.
Beer Keg System Market Segmentation
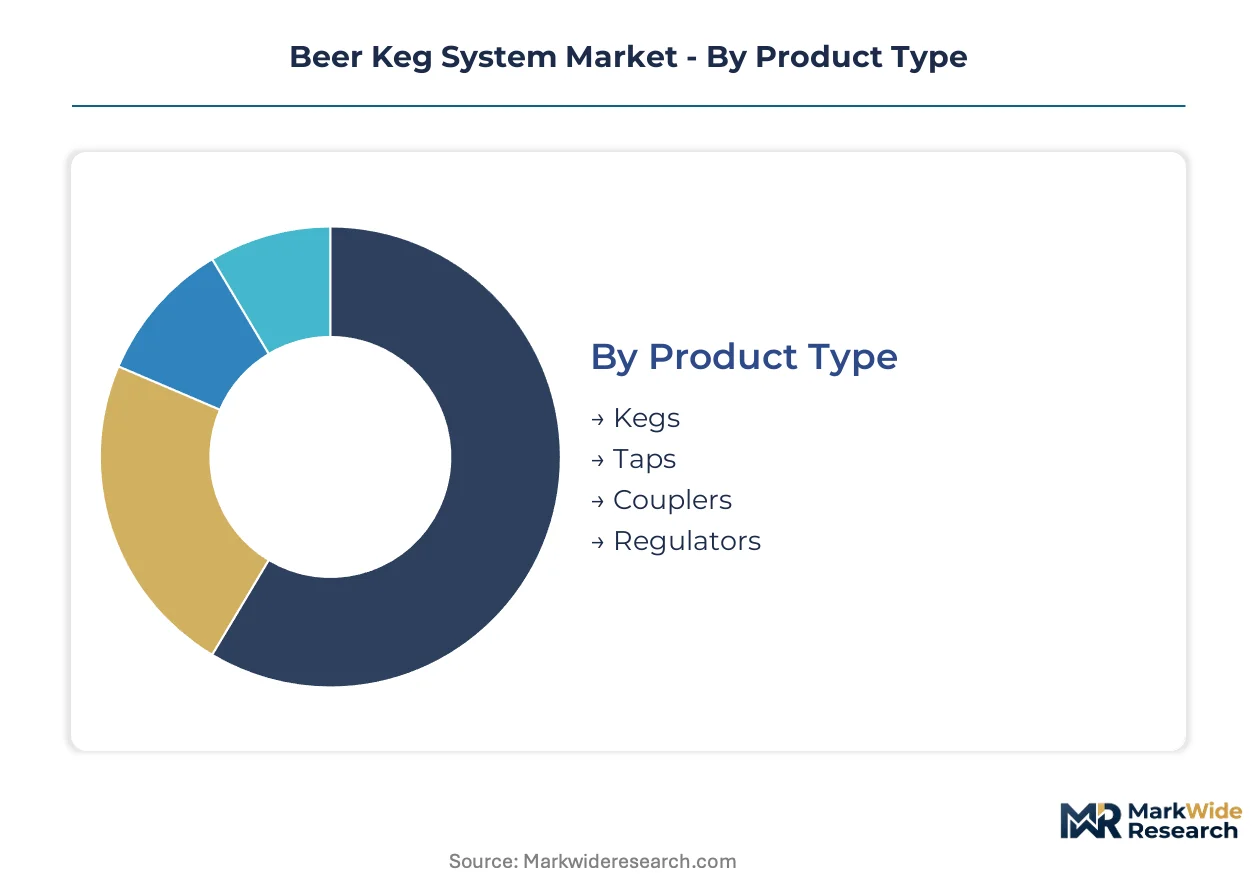
Beer keg system procurement patterns diverge sharply between high-volume commercial operations and specialized niche applications. Understanding these segment boundaries clarifies where manufacturers must optimize for durability versus flexibility.
Product Type:
The volume versus premium split separates commodity vessel replacement from precision dispensing component sales.
- Kegs:Pressurized stainless steel vessels engineered for hundreds of cleaning and refill cycles. Demand concentrates in German breweries where EU Green Deal mandates enforce deposit-return compliance and embedded tracking requirements.
- Taps:Direct-draw dispensing mechanisms that maintain CO₂ equilibrium at 10-12 psi serving pressure. U.S. craft breweries in Colorado and Oregon drive specification customization as direct procurement from fabricators displaces traditional distributor channels.
- Couplers:Valve interface components standardized under German national packaging ordinances.
- Regulators:Pressure control devices essential for carbonated beverage equilibrium maintenance.
Mature deployment sits with kegs. Newer deployment is concentrated in precision-engineered taps.
End User:
Application context dictates whether buyers prioritize throughput capacity or event portability.
- Pubs:High-frequency dispensing operations requiring durable stainless steel infrastructure and rapid return-to-service cycles.
- Restaurants:Establishments balancing draft program footprint against kitchen space constraints.
- Breweries:Integrated production-to-dispensing operations where inspection technician availability shapes fleet utilization rates.
- Events:Outdoor festival operators in France and Spain facing REACH chemical restrictions and polymer lining bans ahead of 2027 enforcement deadlines.
Mature deployment sits with pubs. Newer deployment is concentrated in event applications.
Material:
Cost tier stratification separates capital-intensive reusable systems from single-use alternatives facing regulatory phase-out.
- Stainless Steel:Reusable vessels withstanding hundreds of cleaning cycles. German manufacturers Blefa GmbH and THIELMANN dominate output, creating supply concentration as EU PED 2014/68/EU compliance timelines stretch 14-18 months for new designs.
- Plastic:Lightweight single-use kegs now banned under EU Green Deal circular economy targets and REACH restrictions on certain polymer linings.
- Aluminum:Intermediate-weight alternative gaining traction among event-focused brewers seeking compliance without full stainless steel logistics investment.
- Hybrid:Composite constructions balancing durability against transport weight.
Mature deployment sits with stainless steel. Newer deployment is concentrated in aluminum alternatives.
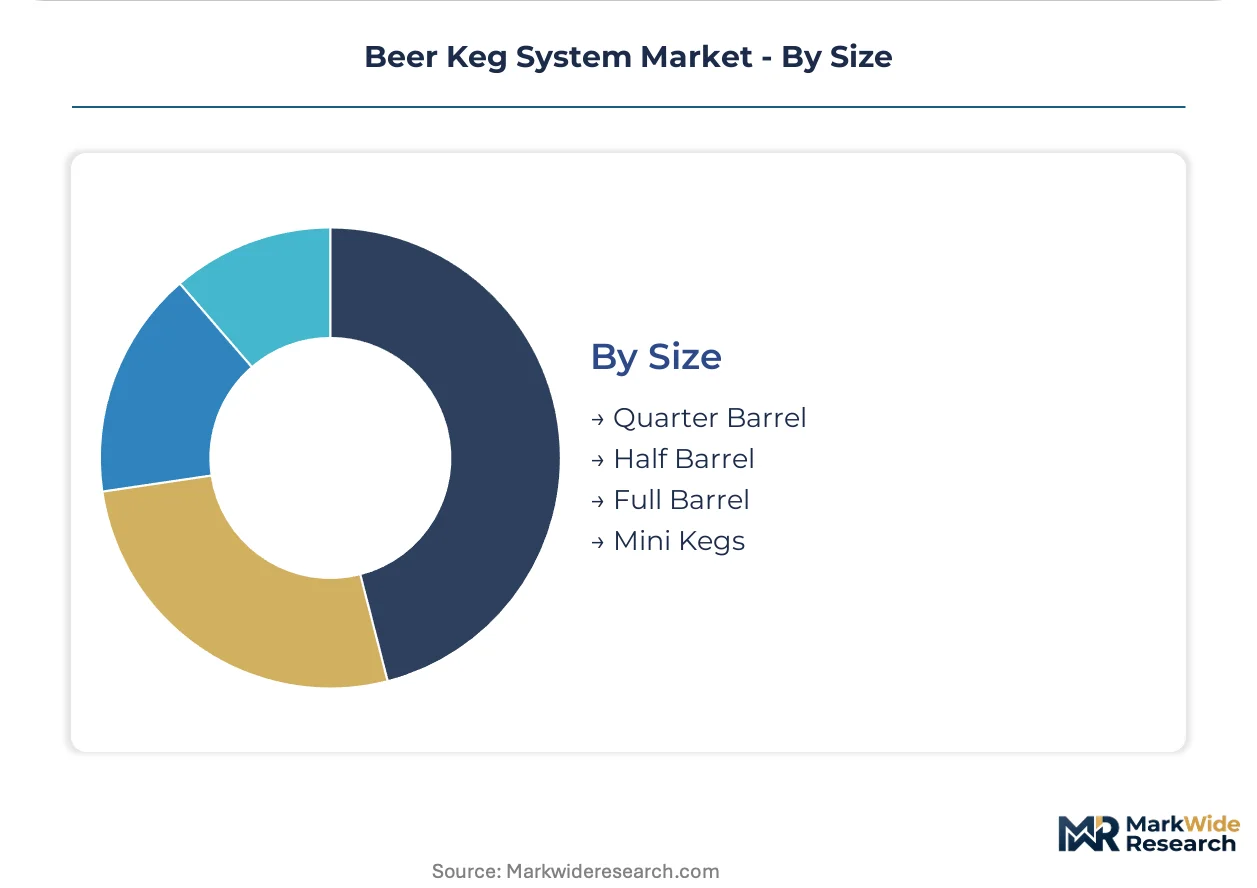
Size:
Customer type differentiation separates industrial-scale operations from residential experience seekers.
- Quarter Barrel:Compact format suited to space-constrained restaurants and small-batch brewery taprooms.
- Half Barrel:Standard commercial volume for high-throughput pub and restaurant dispensing.
- Full Barrel:Maximum-capacity vessels for industrial brewing operations and major event deployment.
- Mini Kegs:Residential-scale formats for home draft systems. Apartment-dwelling consumers in Japan and South Korea represent underpenetrated demand as premium beer experiences expand beyond commercial venues.
Mature deployment sits with half barrel formats. Newer deployment is concentrated in mini kegs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European keg manufacturing through Blefa GmbH and THIELMANN production facilities serving deposit-return infrastructure across Germany.
United States
Colorado and Oregon brewery clusters drive direct procurement from fabricators as craft producers above 10,000 annual barrels negotiate specification customization. OSHA pressure vessel handling protocols shape workplace training requirements. American Keg Company leverages domestic sourcing to supply tariff-shielded vessels to these mountain and Pacific Northwest brewing corridors.
Germany
Traditional beer culture sustains refill rates through embedded tracking technology and standardized valve interfaces under national packaging ordinance mandates. EU PED 2014/68/EU compliance timelines stretch 14-18 months for new stainless steel designs. Bavarian brewing centers around Munich maintain dense keg return logistics networks.
Belgium
Mid-sized craft breweries adopt RFID-enabled fleet management fastest to reduce 8-12% annual keg loss rates. REACH chemical restrictions accelerate transitions away from polymer-lined disposable alternatives. Flemish brewing operations around Leuven and Ghent deploy cloud-based tracking convergence for real-time utilization data.
France
Outdoor festival operators face 2027 enforcement deadlines for EU Green Deal circular economy compliance on disposable keg phase-outs. Aluminum alternatives gain traction among event-focused brewers seeking weight reduction without full stainless steel logistics. Provence-Alpes-Côte d'Azur summer festival circuits drive seasonal demand spikes.
Japan
Apartment-dwelling consumers in Tokyo and Osaka represent underpenetrated demand for residential mini keg formats as premium beer experiences expand beyond commercial venues. METI standards govern pressure vessel certification timelines. Kanto region distribution networks remain optimized for commercial rather than home draft system fulfillment.
Beer Keg System Market Competitive Environment
Premium-margin players sit above commodity-margin players across welding automation and tracking technology integration tiers. The vendor base stratifies between German-engineered reusable stainless steel specialists and regional fabricators competing on tariff-adjusted delivery windows. Three archetypes dominate: automation-heavy European manufacturers, domestic-sourced North American suppliers, and Asian-scale producers of intermediate formats. Competitive moves concentrate on direct procurement channel capture and IoT-enabled fleet management service layering.
Among German GmbH-structured manufacturers, Blefa GmbH and THIELMANN - The Container Company occupy positions exemplifying premium-tier automation investment, while American Keg Company represents tariff-advantaged domestic sourcing archetypes for U.S. craft brewery procurement.
| Leading Market Players |
|---|
| Blefa GmbH |
| American Keg Company |
| THIELMANN - The Container Company |
| NDL Keg Inc. |
| Schaefer Container Systems |
| Shinhan Industrial Co., Ltd. |
| Petainer |
| Ningbo BestFriends Beverage Containers Co., Ltd. |
| Julius Kleemann GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Nickel futures volatility on the London Metal Exchange transmits directly through stainless steel keg fabrication costs, compressing margin buffers for manufacturers serving craft brewery buyers while rewarding automated welding investments that shorten production cycles.
Pricing Analysis
Yield-based pricing anchors commercial keg procurement, with brewers calculating total cost of ownership across hundreds of cleaning and refill cycles rather than upfront vessel cost. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered reusable systems with embedded tracking from commodity imports and lightweight aluminum festival alternatives. Pricing pressure stems from nickel price swings squeezing fabricator margins, while U.S. craft breweries above 10,000 annual barrels show lowest price sensitivity due to direct procurement leverage and specification customization demands.
Supply Chain Analysis
Direct-to-brewery channels handle high-volume craft buyer demand in Colorado and Oregon, displacing traditional distributor intermediaries for specification-heavy orders. Manufacturing concentrates in Germany, the United States, and South Korea, with Bavarian production clusters anchoring European reusable stainless steel output. Raw material flows draw from nickel mining operations, cold-rolled steel mills, and precision valve component foundries. Single-source vulnerability concentrates around Blefa GmbH and THIELMANN dominating compliant European supply, while tariff exposure shapes sourcing decisions for North American buyers seeking tariff-shielded domestic fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's packaging waste mandates erect a compliance moat that rewards PED-certified manufacturers while freezing out uncertified competitors facing 14-18 month approval timelines for new vessel designs.
For Market Incumbents: Anchor market position through backward integration into precision welding automation and captive RFID tracking technology production. Defend against emerging aluminum alternative suppliers by embedding IoT fleet management services that lock in brewery customer switching costs. Expand technical service dispatch capabilities in brewery-dense corridors to capture direct procurement relationships.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium German stainless steel and economy Asian imports opens viable entry space for South Korean and Japanese fabricators targeting METI-certified mini keg formats. Target underpenetrated residential demand in Tokyo and Osaka apartment markets through home draft system bundling. Pursue aluminum vessel specialization for French and Spanish festival operators facing 2027 disposable keg phase-out deadlines.
For Investors and Strategic Acquirers: RFID-enabled fleet management adoption rates among Belgian and Dutch mid-sized craft breweries are the leading indicator that subscription-based keg pooling services will displace direct ownership models. Long-term viability favors manufacturers with vertical control over welding automation and embedded tracking integration. Monitor German packaging ordinance enforcement intensity as the signal for compliance-cost barrier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Welding Automation Investment | Robotic seam welding cuts production cycle times for THIELMANN and Blefa GmbH serving premium European brands. |
| IoT Fleet Management Launch | Cloud-based tracking convergence reduces Belgian brewery keg loss rates from 8-12% annually through real-time utilization data. |
| Domestic Sourcing Expansion | American Keg Company's tariff-shielded Colorado and Oregon supply shields craft buyers from Section 301 duty exposure. |
| Aluminum Alternative Development | Lightweight vessel formats capture French and Spanish festival operators ahead of REACH chemical restriction deadlines. |
| Mini Keg Format Introduction | Residential-scale systems penetrate Tokyo and Osaka apartment markets where commercial draft infrastructure remains dominant. |
Study Parameters
Multi-period observation of keg fleet utilization rates, regulatory compliance timelines, and raw material input costs anchored the trend analysis, supplemented by interviews with brewery operations directors, pressure vessel inspectors, keg fabricator procurement leads, and distributor channel managers. Secondary validation drew from EU PED certification databases, German packaging ordinance enforcement records, London Metal Exchange nickel futures data, and OSHA pressure vessel handling protocol filings. Bottom-up brewery demand modeling triangulated against top-down stainless steel vessel production capacity estimates.
Segment-weighting across material tiers, size formats, and end-use applications structured the analytical framework over the projection horizon. CAGRs derived from iterative reconciliation of replacement cycle frequencies, inspection interval regulations, and craft brewery expansion trajectories. Forecast inputs incorporated EU Green Deal implementation pace, deposit-return mandate adoption curves, and welding automation diffusion rates across manufacturer facilities.
Inputs from regulatory certification databases and brewery trade associations were available through the study window; gaps in real-time keg loss rate reporting and unreported informal vessel refurbishing introduce uncertainty bands around fleet size estimates. Forecasts reflect documented assumptions regarding compliance timeline adherence and nickel price regime stability. Periodic stress-testing of base assumptions against German ordinance enforcement intensity and U.S. craft brewery consolidation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Craft Spirits Market