
 Glue Applied Automotive Labels Market | 2026-2036
Glue Applied Automotive Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Glue Applied Automotive Labels Market Foresight
The EU Green Deal is expanding requirements for sustainable materials across automotive supply chains, directly elevating demand for low-VOC and recyclable label adhesives. Avery Dennison Corporation leverages its materials science portfolio to develop pressure-sensitive adhesives with reduced solvent content. CCL Industries anchors its position through specialized printing capabilities that serve premium automotive branding requirements. 3M Company differentiates via advanced acrylic adhesive platforms engineered for under-hood thermal endurance.
Glue applied automotive labels are pressure-sensitive or wet-applied identification substrates, typically 50–175 microns in thickness, that bond to painted metal, plastic, or glass surfaces through mechanical interlocking and chemical adhesion; they convey regulatory compliance data, branding, and operational warnings in environments exposed to fuels, temperatures from −40°C to 150°C, and pressure-wash cycles. Polyester labels dominate instrumentation panel applications due to dimensional stability and optical clarity under dashboard lighting. Water-based adhesives represent the fastest-expanding chemistry segment as OEMs eliminate solvent-borne systems from interior specifications. Hot melt formulations retain strong positions in engine component tagging where immediate tack and oil resistance prove critical.
EPA regulations govern volatile organic compound emissions from adhesive manufacturing and application processes in the United States, while REACH restricts hazardous substance use across European supply chains. ECHA substance evaluations and RoHS compliance requirements are forcing reformulation of legacy adhesive chemistries and driving substitution toward UV-curable and water-based platforms. Stakeholders must monitor evolving chemical restriction lists and validate alternative adhesive performance against OEM durability protocols before specification lock-in occurs.
Market Dynamics
The automotive label adhesives sector is experiencing a chemistry transition as OEMs systematically purge solvent-borne systems from their approved materials lists. This shift is compressing formulation windows and forcing adhesive suppliers to validate water-based and UV-curable alternatives against legacy performance benchmarks before specification lock-in occurs.
Growth Catalysts
- REACH substance restrictions:ECHA evaluations of hazardous adhesive components are accelerating reformulation investments across European supply chains. OEM procurement teams now mandate low-VOC alternatives for all interior applications.
- Battery system labeling:Electric vehicle powertrains require high-durability identification substrates that withstand thermal cycling from −40°C to 150°C. This application category is expanding faster than traditional engine-bay specifications.
- German OEM specification leadership:Volkswagen, BMW, and Mercedes-Benz procurement consortiums are driving unified solvent-free labeling standards that Tier-1 suppliers must adopt across all manufacturing locations.
Market Restraints
- Petrochemical input volatility:Acrylic monomer and polyester film prices fluctuate with crude oil derivatives, compressing margin predictability for adhesive compounders.
- Technical performance gaps:Water-based adhesives still fail oil-resistance protocols required for transmission and differential component tagging, limiting substitution in powertrain applications.
- Substitution threat from direct marking:Laser etching and inkjet printing systems are displacing physical labels in traceability applications where substrate permanence is paramount.
Strategic Opportunities
- Recyclable adhesive platforms:The EU Green Deal's circular economy mandates are creating first-mover advantage for suppliers developing delaminable label constructions that separate cleanly during vehicle shredding operations.
- India automotive production expansion:Maruti Suzuki and Hyundai Motor India are localizing component sourcing, creating demand for pressure-sensitive labels that comply with BIS automotive material standards.
- UV-curable chemistry convergence:Combining UV curing with digital printing workflows enables on-demand label production with zero solvent emissions, aligning with EPA NESHAP compliance requirements.
Industry Challenges
- OEM validation timelines:Automotive material qualification protocols require 18-24 months of accelerated aging and environmental testing before adhesive approval, delaying revenue realization for reformulated products.
- Skills fragmentation in polymer science:Formulation chemists with expertise in both acrylic rheology and automotive durability testing are concentrated at a small number of suppliers, constraining R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue Applied Automotive Labels Market |
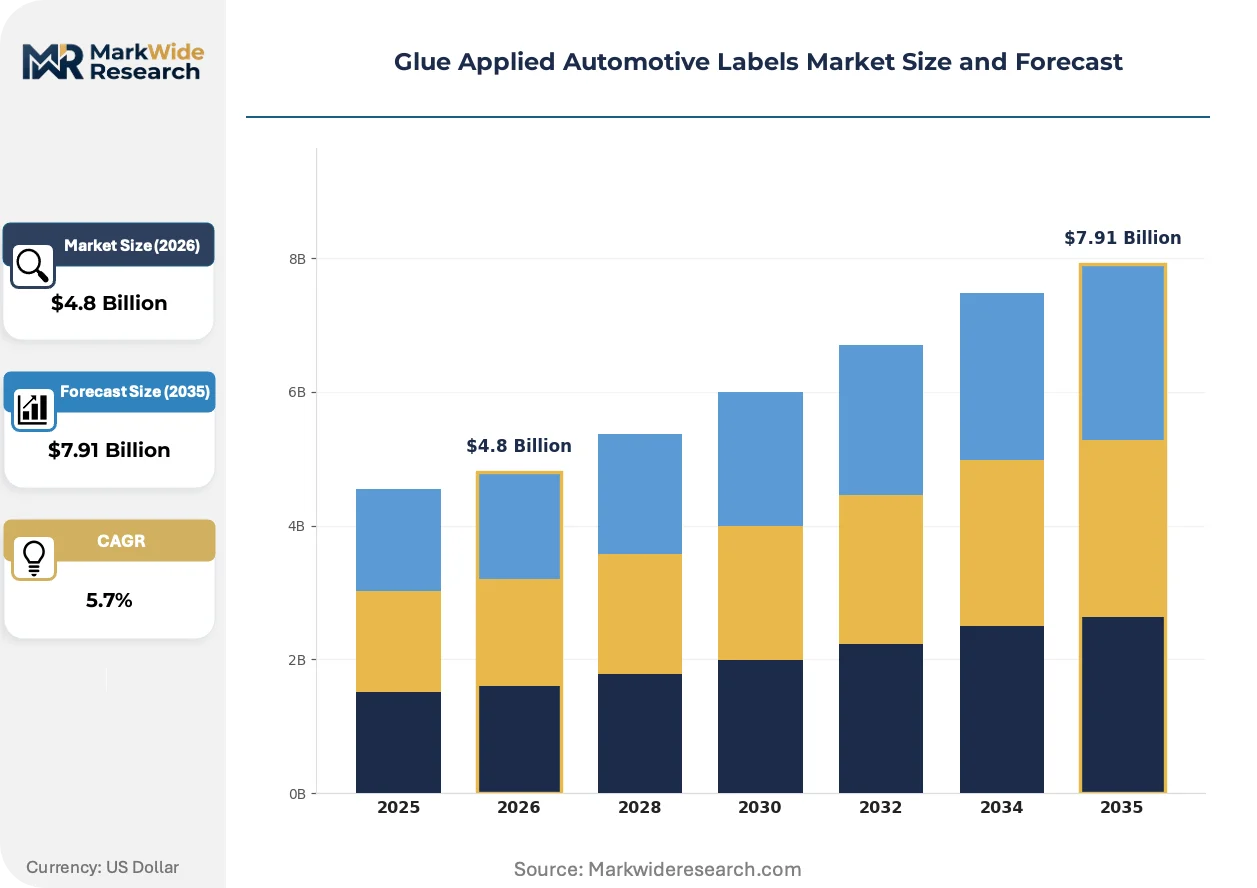
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure Sensitive, Water-Based, Hot Melt, UV Curable, Solvent-Based Material: Polyester, Vinyl, Polypropylene, Paper, Polycarbonate Application: Instrumentation Panels, Engine Components, Door Panels, Lighting Equipment, HVAC Systems End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers |
| Companies Covered | Avery Dennison Corporation, CCL Industries, 3M Company, Multi-Color Corporation, Resource Label Group, Huhtamaki Oyj, Fort Dearborn Company, Skanem AS, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue Applied Automotive Labels Market Shifts & Advancements
Digital printing workflows and sustainable chemistry platforms are converging to redefine how automotive labels are specified, produced, and validated across multi-tier supply chains.
Water-based acrylic adhesives are overtaking solvent-borne systems in dashboard and interior trim applications. BMW and Mercedes-Benz procurement teams have eliminated solvent-containing materials from their 2026 model year specifications. This chemistry shift is compressing the supplier base to compounders with validated aqueous polymerization capabilities and OEM-approved testing protocols.
EPA NESHAP standards for hazardous air pollutant emissions from adhesive manufacturing are tightening discharge limits at production facilities. Coatings operations in Michigan, Ohio, and South Carolina must install thermal oxidizers or carbon capture systems to maintain operating permits. This regulatory pressure is accelerating consolidation toward integrated adhesive suppliers with capital reserves for environmental compliance infrastructure.
Fleet operators and leasing companies are consolidating procurement decisions at the corporate level rather than delegating to individual service centers. This buyer concentration is compressing label supplier margins through volume-based contracting while demanding extended durability warranties that cover the full vehicle lifecycle. The phenomenon is most visible in North American commercial vehicle segments where rental fleet standardization programs specify uniform branding and compliance labeling across thousands of units.
Glue Applied Automotive Labels Market Segmentation
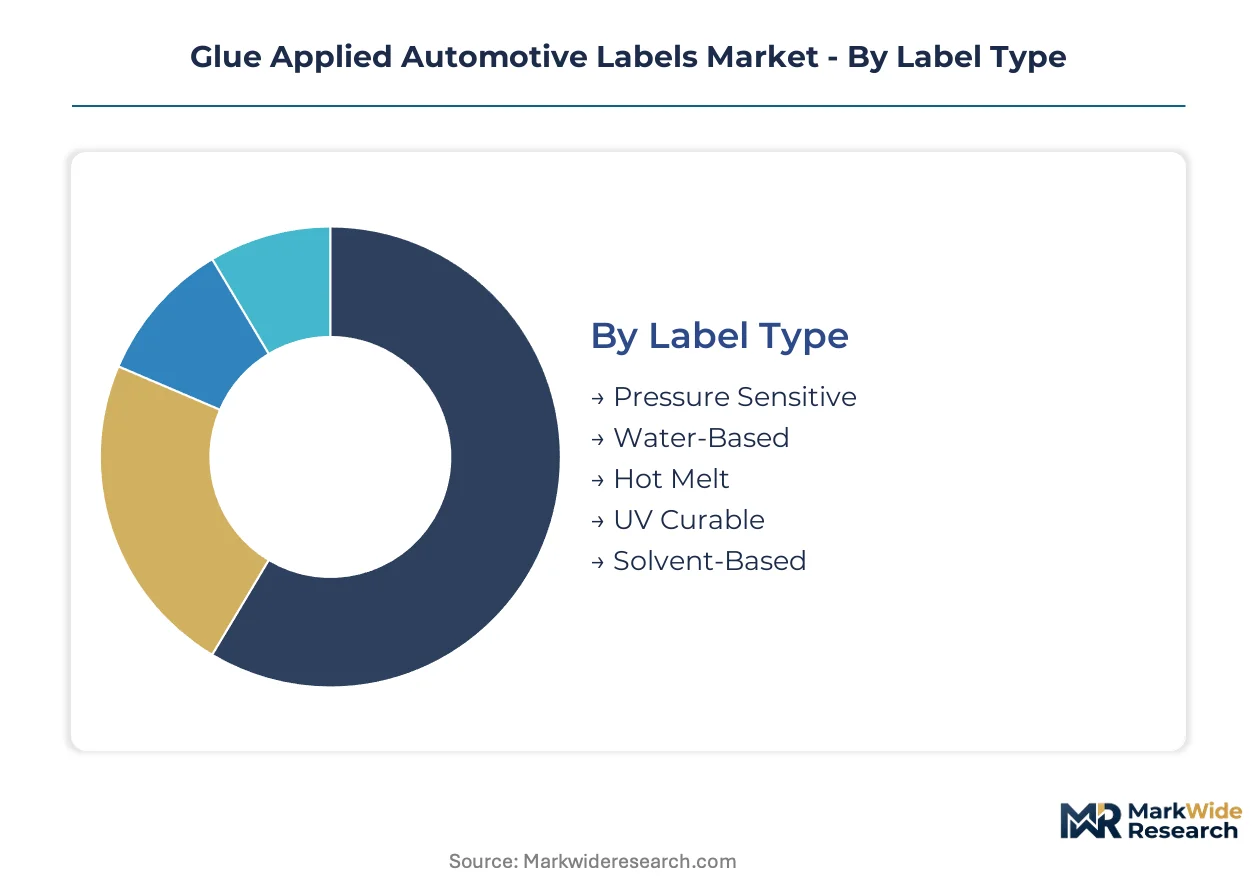
Glue applied automotive labels serve distinct functional roles across vehicle subsystems, with specification requirements varying sharply by exposure conditions and regulatory jurisdiction. Procurement decisions hinge on thermal endurance, chemical resistance, and compliance with evolving VOC restrictions in manufacturing geographies.
Label Type:
Buyers prioritize chemistry platforms based on curing speed, emission profiles, and compatibility with existing coating lines at Tier-1 supplier facilities.
- Pressure Sensitive:These self-adhesive constructions bond immediately upon application without additional curing, utilizing acrylic or rubber-based tackifiers. German OEM consortiums specify pressure-sensitive formats for 70% of interior trim applications due to elimination of thermal curing equipment and alignment with solvent-free mandates.
- Water-Based:Aqueous acrylic dispersions replace solvent carriers with water as the primary vehicle, achieving comparable peel adhesion after moisture evaporation. BMW and Mercedes-Benz procurement teams have mandated water-based systems for all dashboard labeling from the 2026 model year, forcing compounders to validate aqueous formulations against legacy solvent-borne benchmarks.
- Hot Melt:Thermoplastic adhesives applied molten that solidify upon cooling, delivering immediate handling strength. These formulations dominate engine component tagging where oil resistance and rapid tack prove critical.
- UV Curable:Photoinitiator-activated systems that polymerize instantly under ultraviolet exposure, enabling inline digital printing with zero solvent emissions. EPA NESHAP compliance requirements are accelerating adoption at Michigan and Ohio coating facilities.
- Solvent-Based:Traditional systems utilizing organic carriers that evaporate to form adhesive films. REACH substance restrictions and OEM approved-materials-list purges are systematically eliminating this chemistry from European and North American specifications.
Pressure Sensitive leads on scale; Water-Based leads on momentum.
Material:
Substrate selection tracks environmental exposure severity, with cost-performance tradeoffs dictating specification tiers across vehicle zones.
- Polyester:Biaxially oriented polyethylene terephthalate films deliver dimensional stability and optical clarity under dashboard lighting and thermal cycling. Instrumentation panel applications in Volkswagen and BMW vehicles specify polyester exclusively for gauge cluster overlays.
- Vinyl:Polyvinyl chloride formulations offer conformability to complex curves and resistance to plasticizer migration. Door panel branding and decorative trim applications favor vinyl for its deep-color saturation and embossing compatibility.
- Polypropylene:Lightweight olefin films with excellent moisture resistance and recyclability credentials. HVAC system labels specify polypropylene for its compatibility with foam insulation substrates and alignment with EU Green Deal circular economy targets.
- Paper:Cellulose-based substrates with limited durability, restricted to temporary protective labels and shipping documentation. Aftermarket parts distribution utilizes paper for cost-sensitive applications with short service lifespans.
- Polycarbonate:High-impact thermoplastic with exceptional optical properties and heat deflection temperatures. Lighting equipment labels specify polycarbonate for headlamp and taillamp applications where clarity under thermal load is paramount.
Polyester dominates revenue contribution; Polypropylene gains share fastest on sustainability positioning.
Application:
Functional requirements diverge sharply by vehicle zone, with thermal exposure and chemical contact dictating adhesive specification intensity.
- Instrumentation Panels:Labels for gauge clusters, warning indicators, and decorative trim requiring optical clarity and resistance to dashboard temperatures. German OEM specifications mandate 10-year durability with no visible degradation under cyclic heat and UV exposure.
- Engine Components:Identification substrates for transmission housings, fluid reservoirs, and belt routing diagrams. Hot melt adhesives retain specification here due to water-based formulations failing oil-resistance protocols.
- Door Panels:Branding emblems, regulatory placards, and trim identification on interior and exterior surfaces. Vinyl labels dominate this zone for conformability to compound-curved door structures.
- Lighting Equipment:Headlamp, taillamp, and signal lamp labels requiring transparency and thermal endurance. Polycarbonate substrates with UV-curable adhesives are displacing traditional constructions.
- HVAC Systems:Climate control interface labels and ductwork identification. Polypropylene constructions align with foam insulation substrates and moisture exposure conditions.
Instrumentation Panels generates highest value per unit; Engine Components faces substitution pressure from direct laser marking.
End User:
Procurement authority concentration varies across the value chain, with specification control increasingly centralized at OEM level.
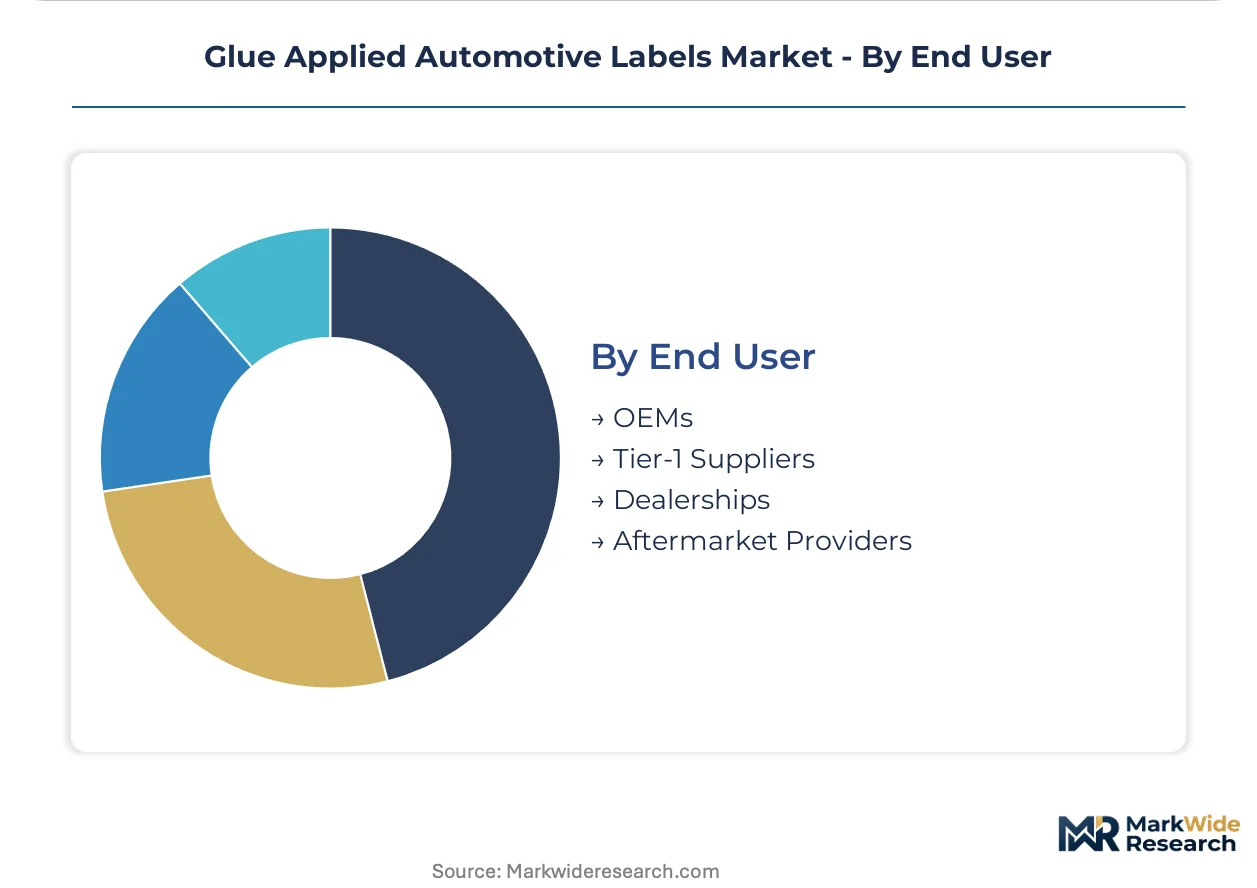
- OEMs:Vehicle manufacturers including Volkswagen, BMW, Mercedes-Benz, and Ford that dictate approved-materials lists and durability protocols. OEM procurement consortiums now mandate solvent-free labeling standards across all manufacturing locations.
- Tier-1 Suppliers:Component integrators such as Bosch, Continental, and Magna that purchase labels for subassembly integration. These suppliers must maintain dual inventory—solvent-free for German OEM programs, legacy systems for other customers.
- Dealerships:Authorized retail networks sourcing replacement labels for warranty repairs and customization services. Fleet standardization programs are compressing dealership autonomy in procurement decisions.
- Aftermarket Providers:Independent distributors and service chains supplying repair and restoration markets. Price sensitivity dominates here, with paper and economy vinyl constructions prevailing.
OEMs command specification authority; Tier-1 Suppliers absorb compliance transition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The glue applied automotive labels industry traces its modern scale to post-war German automotive manufacturing, where adhesive identification systems first achieved industrial standardization for Volkswagen and Mercedes-Benz assembly lines.
Germany
Volkswagen, BMW, and Mercedes-Benz procurement consortiums mandate solvent-free labeling standards across all manufacturing locations. REACH substance restrictions through ECHA accelerate reformulation investments throughout Bavarian and Baden-Württemberg supply chains. Stuttgart's automotive cluster drives specification leadership for UV-curable and water-based adhesive platforms.
United States
EPA NESHAP standards tighten hazardous air pollutant discharge limits at Michigan, Ohio, and South Carolina coating facilities. Ford and General Motors procurement teams systematically purge solvent-borne systems from approved materials lists. Detroit's Tier-1 supplier corridor absorbs compliance transition costs while validating aqueous alternatives.
China
Electric vehicle manufacturers expand high-durability label specifications for battery systems and powertrain components. The country's national environmental regulator enforces dual carbon goals that elevate demand for low-VOC adhesive formulations. Shanghai and Guangzhou automotive clusters concentrate domestic label production capacity.
India
Maruti Suzuki and Hyundai Motor India localize component sourcing, creating demand for pressure-sensitive labels complying with BIS automotive material standards. The Bureau of Indian Standards mandates durability testing protocols for interior trim applications. Tamil Nadu and Gujarat manufacturing corridors attract adhesive compounders seeking export access.
Japan
Toyota and Honda procurement specifications emphasize thermal endurance for under-hood labeling applications. METI industrial standards govern chemical compliance for adhesive formulations used in domestic vehicle production. Nagoya's automotive supplier cluster maintains specialized expertise in hot melt formulations for engine component tagging.
Glue Applied Automotive Labels Market Competitive Landscape
Capital-heavy adhesive compounders compete with asset-light label converters across distinct value chain positions. The market structure concentrates specification authority among integrated materials suppliers with validated OEM testing protocols. Three archetypes dominate: diversified materials conglomerates with polymer science depth, specialized label converters with printing capabilities, and regional adhesive compounders serving aftermarket channels. Competitive moves center on chemistry platform diversification and geographic expansion into emerging automotive production zones.
Among North American diversified materials suppliers, Avery Dennison Corporation and 3M Company exemplify the integrated archetype combining adhesive formulation with substrate manufacturing. CCL Industries occupies a position within the specialized converter tier, leveraging printing capabilities to serve premium automotive branding requirements. These three anchors represent distinct strategic postures: materials science depth, vertical integration into polymer production, and specialized conversion expertise.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries |
| 3M Company |
| Multi-Color Corporation |
| Resource Label Group |
| Huhtamaki Oyj |
| Fort Dearborn Company |
| Skanem AS |
| H.B. Fuller Company |
| Others |
Supply & Pricing Matrix
Acrylic monomer price indices cascade through adhesive compounding tiers, compressing margins at mid-scale compounders while concentrating pricing power among integrated suppliers with captive petrochemical supply. This input-cost transmission shapes a three-tier pricing structure across premium, standard, and economy levels, where OEM-specified formulations command substantial premiums over aftermarket alternatives.
Pricing Analysis
Contract-based long-term offtake arrangements dominate OEM procurement, with price differentiation hinging on ISO automotive certification tier and volume scale commitments. Cost compression in standard-grade formulations is intensifying because water-based adhesive validation requires extended OEM qualification timelines. Fleet operators exhibit the least price sensitivity due to lifecycle durability warranties, while aftermarket distributors remain highly elastic to per-unit costs.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States operate hub-and-spoke patterns to serve Tier-1 supplier clusters. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, South Korean polyester film production, and German acrylic monomer synthesis. Single-source vulnerability concentrates in specialized photoinitiators for UV-curable platforms. Distribution runs through automotive supplier parks co-located with OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glue applied automotive labels market functions as a stable compounder, with regulatory-driven chemistry transitions ensuring sustained replacement demand across vehicle production cycles.
For Market Incumbents: Anticipate laser etching substitution threats in engine-component traceability by accelerating development of delaminable recyclable adhesives that direct marking cannot replicate. Prioritize backward integration into aqueous polymerization capacity to capture margin from solvent-free mandate compliance. Lock in multi-year supply agreements with German OEM consortiums before specification windows close. For New Entrants and Emerging Players: UV-curable digital printing workflows offer entry into on-demand label production with zero capital-intensive coating infrastructure. Target India's Tamil Nadu and Gujarat manufacturing corridors where BIS automotive material standards are elevating compliance barriers for unvalidated imports. Lead with sustainability credentials aligned with EU Green Deal circular economy mandates to bypass incumbent relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized adhesive compounders possessing validated OEM testing protocols and aqueous formulation expertise. The five-to-ten-year viability window favors targets with demonstrated REACH compliance pathways and established relationships with Volkswagen, BMW, or Mercedes-Benz procurement consortiums. Monitor ECHA substance restriction announcements as inflection indicators for accelerated reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive supply secures margin stability against petrochemical volatility for German OEM specifications. |
| UV-Curable Chemistry Platform Launch | Zero solvent emissions align with EPA NESHAP compliance requirements at Michigan coating facilities. |
| Long-term Supply Agreement with OEM Consortiums | Multi-year contracts with Volkswagen, BMW, and Mercedes-Benz procurement teams lock specification authority. |
| Geographic Expansion into India Manufacturing Corridors | Tamil Nadu and Gujarat localization captures Maruti Suzuki and Hyundai Motor India component sourcing demand. |
| Recyclable Adhesive Certification Program | Delaminable label constructions satisfy EU Green Deal circular economy mandates for vehicle shredding operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and adhesive formulation chemists with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from listed materials suppliers. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Historical reference periods anchored the projection horizon to established automotive production cycles and regulatory implementation timelines. The analytical framework modeled segmentation across label chemistry platforms, substrate materials, vehicle application zones, and regional production clusters. CAGRs derived from trend extrapolation of OEM specification adoption curves and electric vehicle powertrain labeling intensity. Industry-specific inputs included REACH substance restriction schedules and EPA NESHAP compliance phase-ins.
The model holds under stable regulatory implementation schedules; deviation in ECHA evaluation acceleration or OEM qualification timeline compression would shift volume realization patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Direct Thermal Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Heat Shrink Sleeve Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
Global Waterproof Labels Market
Labels
Coated Wet Glue Label Market
Labels
Wire Marking Labels Market
Labels
Safety Labels Market
Labels
Eco-Friendly Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Wrap Around Labels Market
Labels
Foil Labels Market
Labels
Primary Packaging Labels Market
Labels
Multi-Part Labels Market
Labels
Self-Laminating Tags Market
Labels
Industrial Label Printers Market