
 Wire Marking Labels Market | 2026-2036
Wire Marking Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Marking Labels Market Analysis
Aftermarket label replacement revenue is narrowing toward original equipment specification contracts as manufacturers extend traceability requirements across product lifecycles. Brady Corporation leverages its channel control across safety identification to sustain premium positioning in industrial compliance. Panduit Corporation anchors its position through vertical integration into cable management systems. HellermannTyton competes on manufacturing scale in heat-shrink identification across European automotive supply chains.
Wire marking labels are pressure-sensitive or heat-shrinkable identification media, typically manufactured from halogen-free polymers with print resolutions of 300 dpi or higher, designed to maintain legibility across temperature ranges from minus 40 degrees Celsius to 150 degrees Celsius for cable and harness management in electrical infrastructure. Self-adhesive labels occupy the largest volume share in telecommunications patch panel applications where frequent reconfiguration demands peel-and-replace convenience. Heat-shrink labels represent the fastest-expanding product category as automotive wiring complexity multiplies connector density in electric vehicle architectures. Polyester labels concentrate margin pools in industrial equipment where chemical resistance and UV stability command specification premiums.
UL 969 standards in the United States and REACH chemical restrictions in the European Union constrain adhesive formulations and substrate choices, compelling reformulation investments that filter smaller suppliers from approved vendor lists. China's GB standards and MIIT directives on halogen-free materials reshape import requirements for foreign label manufacturers serving domestic electrical installation markets. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized production or certified import pathways offer lower total compliance cost.
Market Dynamics
Automotive electrification is compressing wire harness complexity into denser connector architectures, forcing identification systems to shrink while maintaining legibility across thermal cycling. This structural pressure cascades through material specifications, print resolution requirements, and adhesive chemistry investments.
Growth Catalysts
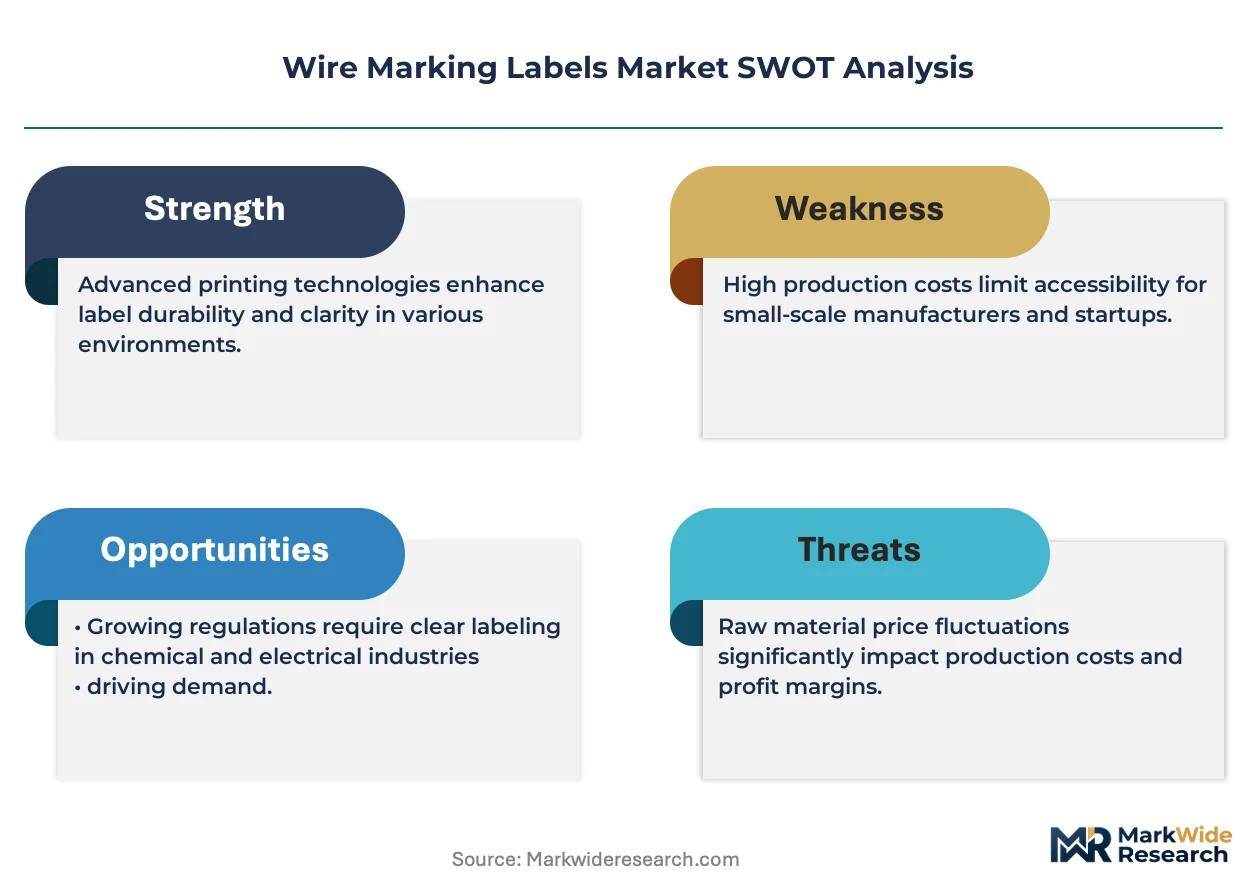
- REACH chemical restrictions:European ECHA mandates on halogen-free substrates are filtering non-compliant suppliers from approved vendor lists, consolidating procurement toward certified manufacturers.
- Automotive wiring harness production:China's eastern manufacturing corridor is scaling electric vehicle assembly, multiplying connector density and label-per-vehicle counts.
- UL 969 standard revisions:North American updates to permanence and legibility testing are extending specification requirements across industrial equipment lifecycles.
Market Restraints
- Halogen-free polymer feedstock concentration:Specialty resin supply concentrates among Asian petrochemical producers, exposing converters to input cost volatility and allocation risk.
- Adhesive formulation complexity:Multi-jurisdiction chemical compliance requires parallel certification tracks, extending product development timelines and raising fixed compliance costs.
- Heat-shrink sleeve substitution:Laser-marked cable jackets in high-volume automotive applications are displacing applied labels in select harness segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic wiring harness manufacturing incentives are creating import substitution demand for localized label production.
- Digital print-on-demand systems:Distributed manufacturing cells are enabling make-to-order label production at contract assembler facilities, compressing lead times.
- CE marking convergence with IEC standards:Harmonized testing protocols are reducing duplicative certification costs for multi-market product launches.
Industry Challenges
- Print technician skill gaps:Thermal transfer and UV inkjet calibration expertise is scarce in emerging manufacturing hubs, constraining quality consistency.
- Legacy inventory system integration:Automated label data feeds require API development with decades-old ERP installations at tier-one automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Marking Labels Market |
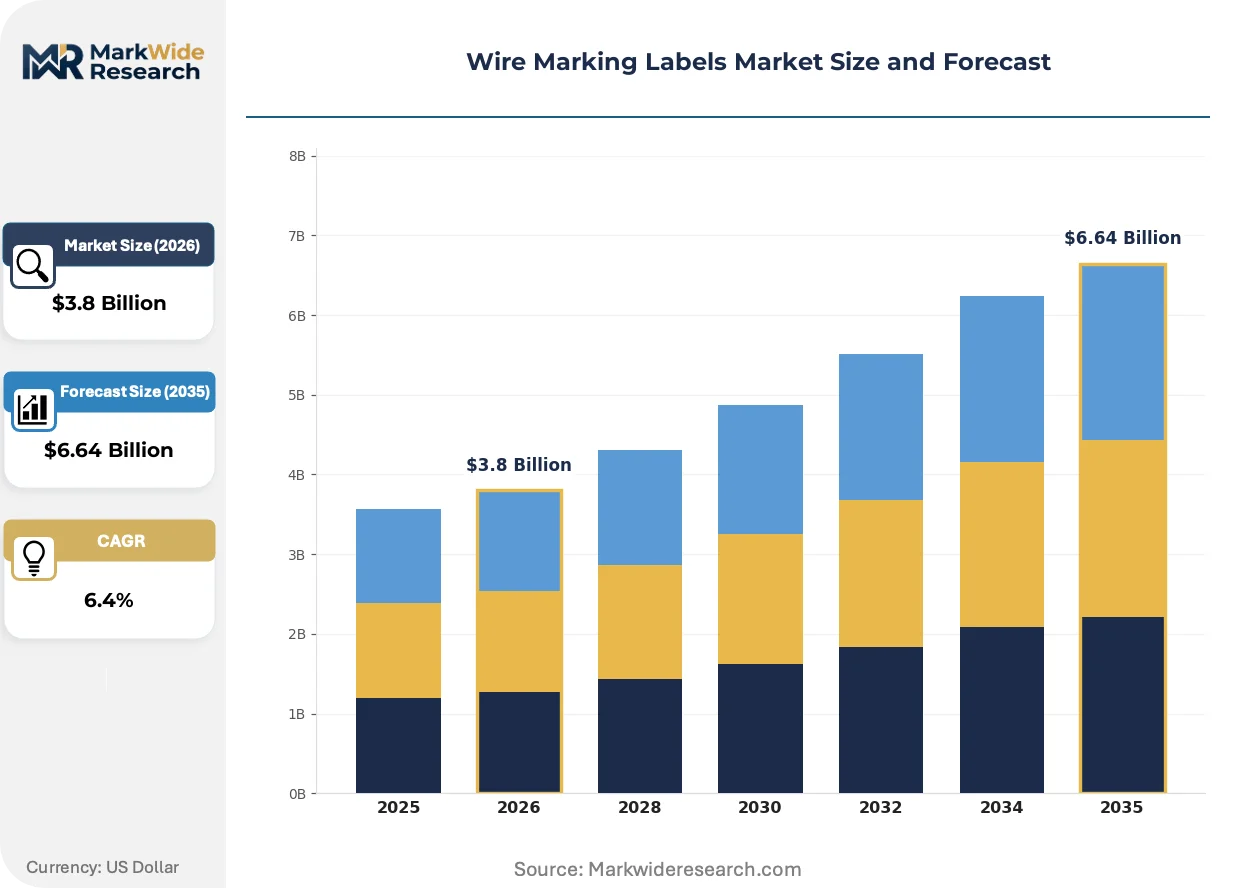
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Labels, Heat-Shrink Labels, Vinyl Labels, Polyester Labels Application: Telecommunications, Electrical Installation, Automotive Wiring, Industrial Equipment Material: PVC, Polyethylene, Nylon, Non-Woven Fabric Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Panduit Corporation, Lapp Group, Brady Corporation, Eaton, Legrand, 3M Company, HellermannTyton, Seton Identification Products, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Marking Labels Market Emerging Trajectories
Cloud-based design-to-print workflows are collapsing the traditional separation between engineering specification and shop-floor execution. This convergence is redrawing competitive boundaries around software integration rather than substrate manufacturing alone.
RFID-embedded wire markers are virtualizing physical inventory tracking into digital twin architectures. Automotive OEMs in Germany and the United States are piloting these systems for warranty traceability. This virtualization is compressing recall response timelines from weeks to hours while raising the technical bar for label converters.
REACH authorization requirements for specific adhesive chemistries are forcing systematic substance inventory audits across European supply chains. Industrial equipment manufacturers are now demanding full material disclosure upstream of component procurement. Heat-shrink identification products face the steepest reformulation costs given their polymer-solvent complexity.
Specification contracts are displacing spot aftermarket purchases as manufacturers extend traceability mandates across product lifecycles. Original equipment suppliers are capturing label revenue streams previously fragmented across maintenance channels. This shift is most visible in German industrial machinery and US electrical infrastructure markets where regulatory liability drives documentation rigor.
Wire Marking Labels Market Segmentation
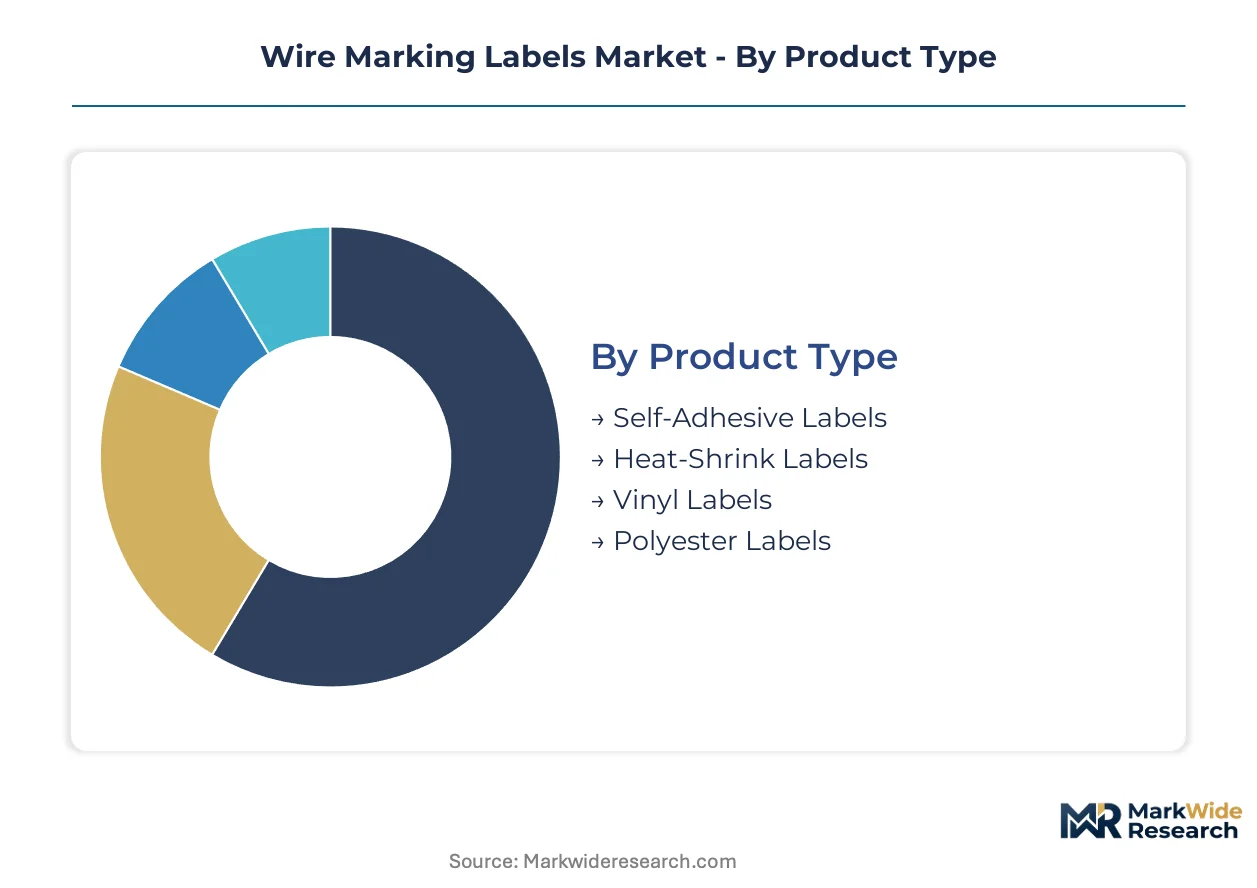
Wire marking labels fragment across four structural dimensions that determine specification requirements, margin pools, and channel economics. Product type and application concentration dominate procurement decisions, while material chemistry and distribution access shape competitive positioning.
Product Type:
Application demands and thermal performance requirements divide the product landscape into four distinct technology platforms.
- Self-Adhesive Labels:Pressure-sensitive identification media using acrylic or rubber-based adhesives on polyester or vinyl substrates. Telecommunications patch panels in Germany and the United States absorb the largest volumes where frequent reconfiguration demands peel-and-replace convenience without residue.
- Heat-Shrink Labels:Cross-linked polyolefin sleeves that conform to cable diameters upon thermal activation. Automotive wiring harness production in China's eastern manufacturing corridor is scaling fastest as electric vehicle architectures multiply connector density per vehicle.
- Vinyl Labels:Flexible PVC-based identification with conformable backing for irregular surfaces. General electrical contractors specify these for cost-sensitive commercial installations where chemical exposure remains moderate.
- Polyester Labels:High-performance PET substrates with solvent-resistant topcoats. Industrial equipment manufacturers in Germany command specification premiums for UV stability and abrasion resistance in outdoor or harsh environment deployments.
Self-adhesive labels hold installed capacity. Heat-shrink labels are rotating up the share rankings.
Application:
End-use sectors impose divergent technical specifications that filter supplier qualification and pricing power.
- Telecommunications:Data center and network infrastructure labeling requiring frequent reconfiguration cycles. Patch panel density in the United States and Germany is compressing label dimensions while maintaining 300 dpi legibility standards.
- Automotive Wiring:Harness identification systems for thermal cycling endurance across minus 40 to 150 degrees Celsius. China's electric vehicle assembly plants are multiplying label-per-vehicle counts as high-voltage architectures add circuit complexity.
- Industrial Equipment:Machinery and control panel marking with extended lifecycle traceability mandates. REACH compliance in the European Union and UL 969 revisions in North America are tightening material disclosure requirements.
- Electrical Installation:Building wire and conduit marking for commercial and residential construction. China's GB standards on halogen-free materials are reshaping import requirements for foreign manufacturers.
Telecommunications anchors volume throughput. Automotive wiring is climbing the fastest.
Material:
Substrate chemistry determines regulatory compliance pathways and thermal performance ceilings.
- Polyethylene:Cross-linked polyolefin formulations dominating heat-shrink sleeve production. REACH authorization requirements for specific adhesive chemistries are forcing systematic substance audits across European supply chains.
- PVC:Cost-optimized vinyl compounds for general-purpose marking where halogen content remains permissible. China's MIIT directives on halogen-free materials are constraining domestic market access for conventional formulations.
- Nylon:High-temperature resistant substrates for engine compartment and industrial process applications. Automotive OEMs in Germany specify these for thermal endurance in powertrain harness segments.
- Non-Woven Fabric:Flexible, tear-resistant identification for temporary or low-durability installations. Maintenance and repair operations in the United States consume volumes for quick-turn field labeling.
Polyethylene holds installed capacity. Nylon is rotating up the share rankings.
Distribution Channel:
Channel structure shapes customer access economics and specification control.
- Direct Sales:Manufacturer-to-OEM contracts for original equipment specification. Automotive and industrial equipment producers in Germany and the United States are consolidating procurement toward certified vendors with full material disclosure.
- Distributors:Electrical and industrial supply houses carrying broad SKU ranges for contractor and maintenance demand. Channel control in North America sustains premium positioning for compliance-certified products.
- Online Retail:E-commerce platforms serving small-volume and aftermarket replacement demand. Procurement of flame-retardant identification systems through digital channels is narrowing toward specification-contract volumes.
- Specialty Stores:Local electrical supply outlets for immediate-need contractor purchases. China's eastern manufacturing corridor maintains these for wiring harness production support.
Direct sales holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Germany and the United States prioritize flame-retardant identification systems for industrial compliance, while China's eastern manufacturing corridor absorbs heat-shrink volumes for automotive wiring harness production at scale unmatched elsewhere.
United States
Industrial equipment manufacturers and data center operators drive specification-grade demand. UL 969 standard revisions on permanence and legibility testing extend compliance requirements across electrical infrastructure lifecycles. Dallas-Fort Worth and Chicago manufacturing corridors concentrate procurement of flame-retardant identification systems for OEM integration.
Germany
Automotive OEMs and industrial machinery producers mandate full material disclosure upstream of component procurement. REACH authorization requirements for specific adhesive chemistries force systematic substance audits across European supply chains. Bavaria's automotive supplier ecosystem anchors heat-shrink identification demand for powertrain harness segments.
China
Electric vehicle assembly plants in the eastern manufacturing corridor multiply label-per-vehicle counts as high-voltage architectures add circuit complexity. MIIT directives on halogen-free materials reshape import requirements for foreign manufacturers serving domestic electrical installation markets. Shanghai and Suzhou wiring harness production scales fastest.
India
Domestic wiring harness manufacturing incentives under the PLI scheme for automotive components create import substitution demand for localized label production. BIS certification requirements on electrical safety materials constrain market access for uncertified imports. Tamil Nadu and Maharashtra automotive clusters absorb growing volumes for EV assembly integration.
Japan
Precision manufacturing and robotics industries specify high-temperature resistant substrates for process automation applications. METI industrial standards on electrical component traceability extend documentation requirements across product lifecycles. Kansai and Chubu industrial belts concentrate demand for nylon-based identification in harsh environment deployments.
Wire Marking Labels Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates into specification-certified suppliers serving OEM direct contracts and volume-oriented converters feeding distributor channels. Three archetypes dominate: integrated cable management specialists, safety identification platform owners, and heat-shrink manufacturing scale players. Consolidation pressures filter smaller suppliers from approved vendor lists as material disclosure requirements tighten. Geographic expansion and backward integration into polymer feedstocks represent the dominant competitive vectors.
Among North American safety identification specialists, Brady Corporation occupies a position exemplifying channel control across industrial compliance markets. Panduit Corporation represents the integrated cable management archetype through upstream control over connector and routing systems. HellermannTyton anchors the European heat-shrink manufacturing tier with scale positioning across automotive supply chains.
| Leading Market Players |
|---|
| Panduit Corporation |
| Lapp Group |
| Brady Corporation |
| Eaton |
| Legrand |
| 3M Company |
| HellermannTyton |
| Seton Identification Products |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Specialty halogen-free polymer feedstock concentration among South Korean and Chinese petrochemical producers anchors margin capture at the substrate conversion tier, while downstream label converters face compressed spreads on standardized adhesive formulations.
Pricing Analysis
Long-term offtake contracts dominate procurement between certified label converters and automotive OEMs, insulating volume commitments from spot resin volatility. Price differentiation separates REACH-compliant specification grades from general-purpose inventory, with certification premiums widening as ECHA substance restrictions tighten. Pricing pressure stems from laser-marked cable jacket substitution in high-volume harness segments. Tier-one automotive suppliers exhibit lowest price sensitivity due to traceability liability exposure, while electrical contractors in commercial construction remain most cost-responsive.
Supply Chain Analysis
Extended payment terms from European automotive OEMs cascade through supply-chain finance facilities to Asian resin producers, concentrating working capital pressure on mid-tier converters. Manufacturing capacity clusters in China, Germany, and the United States, with cross-linked polyolefin feedstock drawing from South Korean and Japanese chemical producers. Single-source vulnerability concentrates in specialty adhesive polymer supply. Distribution runs through direct OEM contracts for specification-grade volumes and electrical distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based design-to-print workflow integration is shifting competitive boundaries toward platform economics, with interoperability between label design software and automotive PLM systems becoming the decisive ecosystem battleground.
For Market Incumbents: Build certification moats through backward integration into halogen-free polymer compounding to secure REACH-compliant feedstock certainty. Defensive consolidation should target digital print-on-demand system providers to capture distributed manufacturing cells at contract assembler facilities. Laser-marked cable jacket substitution and emerging software-centric competitors threaten specification control.
For New Entrants and Emerging Players: India's PLI-scheme automotive clusters offer underpenetrated white-space for localized heat-shrink label production serving wiring harness import substitution. Secondary opportunities sit in RFID-embedded wire marker pilots for German and US automotive OEM digital twin architectures. Go-to-market positioning should emphasize API-native integration with cloud-based engineering specification platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cable management specialists seeking add-on identification capabilities to deepen specification control. Long-term viability favors converters with captive polymer supply and software-integrated production workflows. Watch for ECHA authorization list expansions on adhesive chemistries as margin compression inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant feedstock security reduces ECHA authorization exposure for European automotive supply. |
| Cloud-Based Design-to-Print Platform Launch | API integration with Siemens and Dassault PLM systems collapses engineering-to-production lead times. |
| RFID-Embedded Wire Marker Scale-Up | Automotive OEM digital twin pilots in Germany compress recall response timelines from weeks to hours. |
| Localized Production in India PLI Clusters | Tamil Nadu and Maharashtra automotive hubs create import substitution demand for certified label supply. |
| Heat-Shrink Sleeve Formulation Repositioning | Halogen-free polymer R&D investment addresses MIIT directives constraining conventional PVC market access. |
Methodological Framework
Initial hypotheses were tested against primary input from wire harness procurement managers at Tier 1 automotive suppliers, thermal transfer print technicians at contract assembly facilities, and regulatory affairs leads at industrial equipment OEMs, then refined through secondary validation across SEC 10-K filings, ECHA substance authorization databases, MIIT directive releases, and customs trade data on halogen-free polymer imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, material chemistry, and distribution channel dimensions.
Demand-supply balance framing anchored the forecast framework, with segment-level CAGRs derived from wiring harness production scaling in China's eastern manufacturing corridor, electric vehicle architecture complexity trajectories, and regulatory compliance cost pass-through elasticity. Modeled dimensions spanned product technology platforms, end-use sector concentration, substrate material chemistry, and regional production cluster development across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-cap converters or accelerated laser-marking adoption by automotive OEMs would shift outcomes. Macroeconomic deviation in Asian petrochemical feedstock pricing, unanticipated ECHA substance restrictions, or breakthroughs in direct-part-marking alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Self-Adhesive Labels Market
Labels
Syringe Labels Market
Labels
Global Cryogenic Label Market
Labels
Ethical Label Market
Labels
Europe Self Adhesives Label Market
Labels
Multi-Part Labels Market
Labels
Retro-Reflective Labels Market
Labels
Global Label Market
Labels
Wet Glue Labels Market
Labels
Sheeted Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Global Pressure Labels Market
Labels
GHS Labels Market
Labels
Repositionable Labels Market
Labels
Global in-Mold Labels Market