
 Power Sled Market | 2026-2036
Power Sled Market Size, Share, and Industry Trends Forecast 2026-2036
Power Sled Market Analytics
Military training facilities is reorganizing procurement patterns across the power sled landscape, displacing traditional fitness-center dominance. Ski-Doo leverages its heritage in extreme-terrain engineering to anchor credibility with tactical conditioning programs. Rogue Fitness sustains manufacturing scale through in-house steel fabrication and direct-to-consumer channel control. Arctic Cat competes by extending its snow-vehicle chassis expertise into weighted drag platforms for cold-weather military exercises.
A power sled is a load-bearing resistance training apparatus consisting of a flat or angled platform mounted on runners or skids, typically constructed from welded steel tubing with replaceable rubber or composite contact surfaces, designed to be pushed or pulled across turf, rubber flooring, or snow while loaded with plate weights or sandbags to develop lower-body power and anaerobic capacity. Steel-framed units dominate institutional sales due to durability under repeated 400-pound loads, while aluminum and composite variants gain share in mobile military deployments where transport weight constrains logistics. Rehabilitation facilities represent the fastest-growing end-user segment as post-surgical and neurological recovery protocols integrate progressive sled-based gait retraining.
OSHA workplace safety guidelines and ISO 20957-1 stationary training equipment standards govern product liability and facility insurance requirements, compelling manufacturers to certify weld integrity and anti-tip stability. The US military's updated Army Combat Fitness Test specifications directly specify weighted drag events, embedding power sleds into federal procurement pipelines. Stakeholders must monitor evolving defense budget allocations and commercial gym chain consolidation patterns to anticipate volume shifts between institutional and retail channels.
Market Dynamics
Military procurement standardization is compressing supplier margins while expanding volume pipelines for certified manufacturers. The Army Combat Fitness Test mandate for weighted drag events embeds power sleds into federal acquisition frameworks, creating institutional demand locks that reshape competitive positioning.
Growth Catalysts
- OSHA workplace safety guidelines:Facility insurance requirements now mandate certified weld integrity and anti-tip stability for load-bearing equipment, accelerating replacement cycles in commercial gyms and rehabilitation centers.
- Rehabilitation facilities:Post-surgical and neurological recovery protocols integrate progressive sled-based gait retraining, expanding addressable demand beyond traditional strength-training verticals.
- Steel-framed institutional units:Durability under repeated 400-pound loads satisfies military procurement durability specifications, anchoring premium pricing power in defense contracting corridors.
Market Restraints
- Aluminum and composite material costs:Volatility in aerospace-grade aluminum pricing compresses margins for mobile military deployment variants where transport weight constrains logistics.
- Welding certification concentration:AWS D1.1 structural welding certification capacity concentrates in Midwestern US fabrication hubs, creating supplier bottlenecks for institutional orders.
- ISO 20957-1 compliance timelines:Third-party testing for stationary training equipment standards extends product launch cycles by 4-6 months for new market entrants.
Strategic Opportunities
- Cold-weather military exercises:Weighted drag platforms engineered for snow and ice penetration remain underdeveloped relative to turf-focused commercial offerings, creating white space for specialized chassis designs.
- Direct-to-consumer channel control:Manufacturers bypassing distributor markups through owned e-commerce capture margin expansion while building proprietary customer data assets.
- US Department of Defense physical fitness standards:Updated functional strength assessment mandates embed sled-based conditioning into permanent training infrastructure, creating recurring replacement demand cycles.
Industry Challenges
- AWS-certified welder scarcity:Institutional-grade steel fabrication requires specialized structural welding expertise that outpaces vocational training program output in key manufacturing regions.
- Defense budget allocation volatility:Congressional appropriation timing uncertainty disrupts multi-year procurement planning for military-focused suppliers dependent on federal spending cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Sled Market |
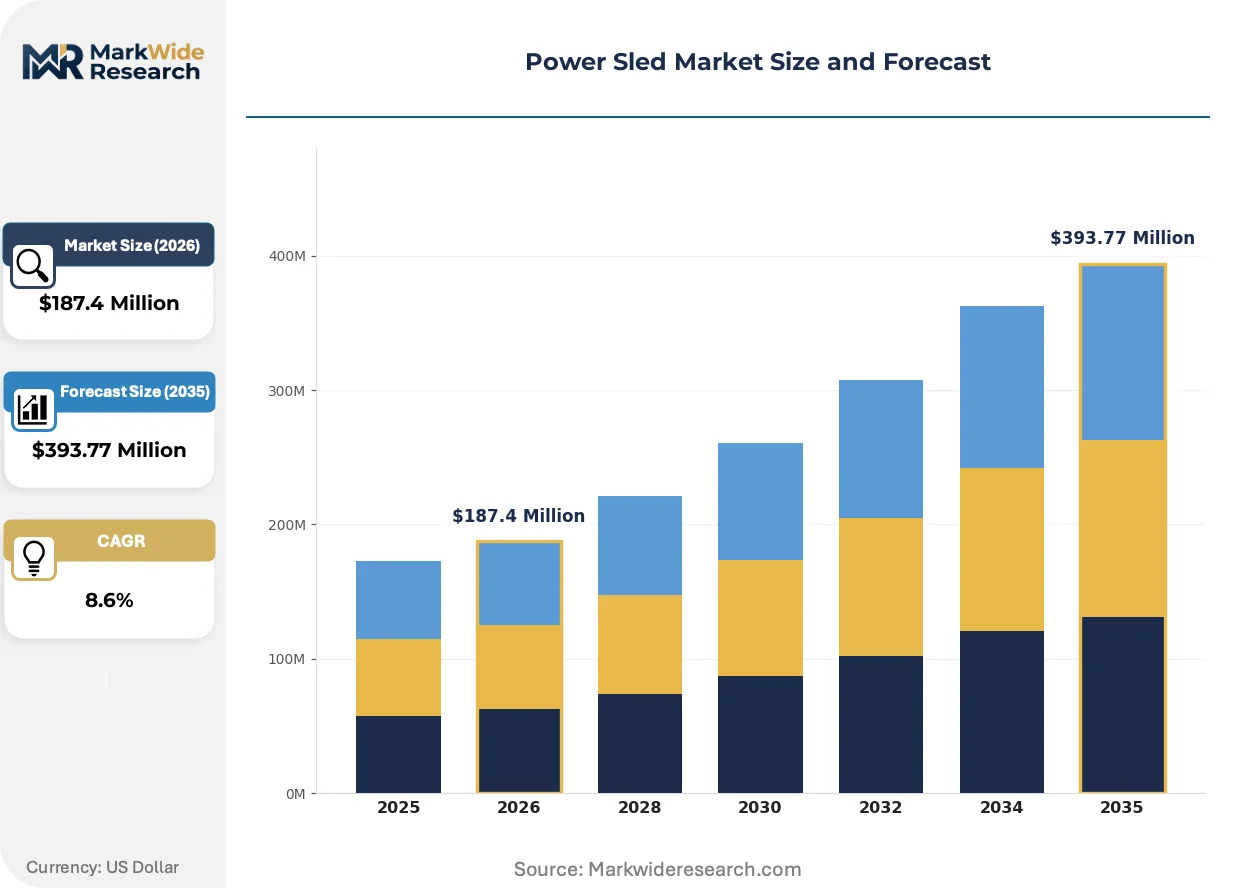
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Hydraulic, Pneumatic, Manual End User: Fitness Centers, Military Training, Professional Athletes, Rehabilitation Facilities Capacity: 100 lbs, 200 lbs, 300 lbs, 400 lbs Material: Steel, Aluminum, Composite, Rubber |
| Companies Covered | Ski-Doo, Rogue Fitness, Arctic Cat, Shogun Sports, Titan Fitness, Polaris, REP Fitness, Xebex Fitness, Lynx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Sled Market Evolving Landscape
Material substitution and procurement model evolution are restructuring how power sleds reach end-users. Manufacturers now balance institutional durability requirements against mobile deployment constraints while navigating compressed certification timelines.
Composite-reinforced polymer runners are supplanting traditional steel skids in cold-weather military variants. Arctic warfare training units adopt these platforms for snow-terrain drag exercises where corrosion resistance and weight reduction outweigh absolute load capacity. This substitution is compressing the addressable market for conventional steel-skid designs in defense applications.
OSHA workplace safety guidelines now explicitly reference load-bearing conditioning equipment in facility audit protocols. Commercial gym chains face elevated liability exposure for uncertified apparatus, driving consolidation toward suppliers with documented weld inspection records. North American facility operators respond by mandating manufacturer certification documentation in procurement specifications.
Defense contracting now favors multi-year framework agreements over transactional purchase orders. Military procurement officers consolidate vendor relationships to reduce qualification overhead, displacing smaller fabricators from federal supply schedules. This concentration is most visible in procurement corridors surrounding Fort Bragg and San Diego, where prime contractors absorb subcontractor capacity through exclusive supply arrangements.
Power Sled Market Segmentation
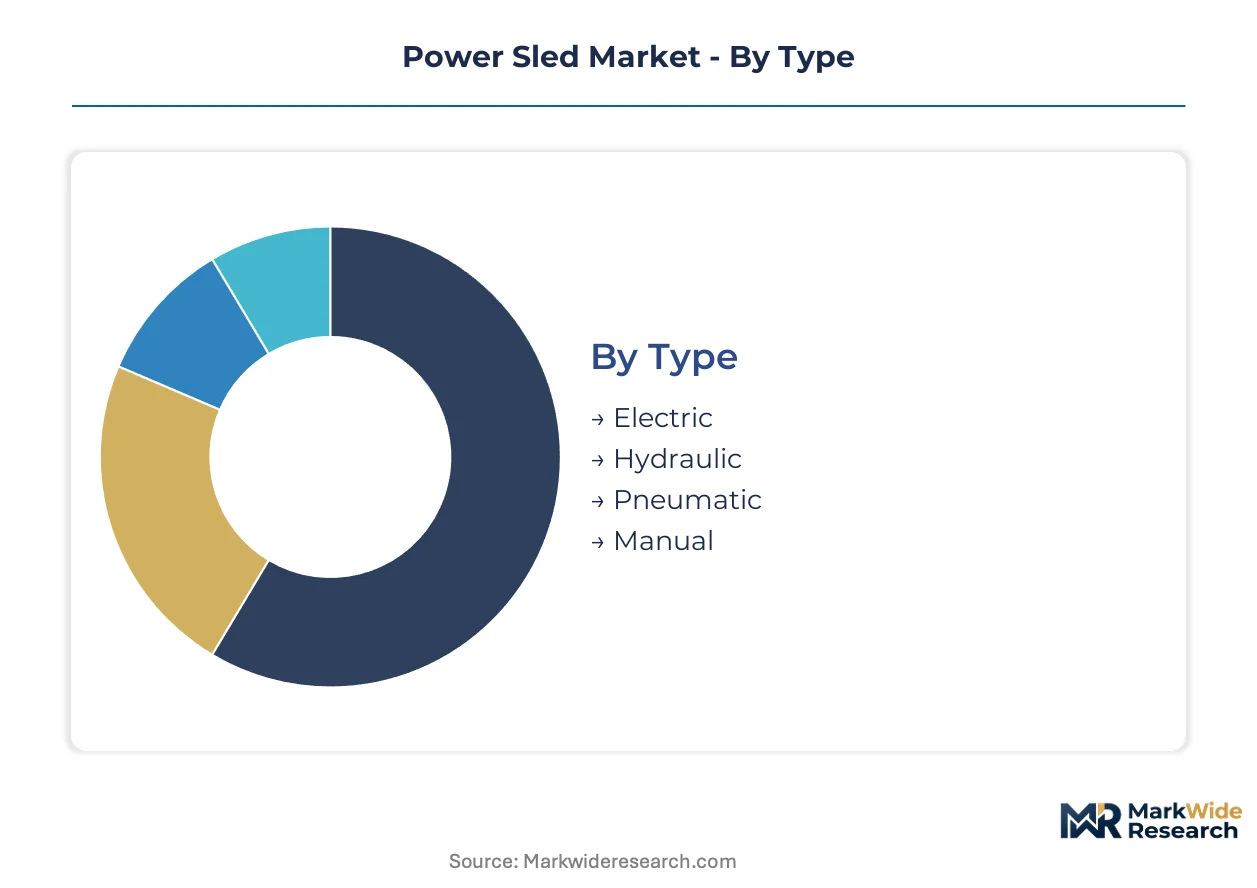
Power sled procurement patterns diverge sharply across institutional versus consumer contexts, with material selection and load capacity determining contract eligibility for federal supply schedules. Manufacturers must align production configurations against distinct certification requirements and durability specifications that vary by end-use environment.
Type:
Margin pools concentrate in powered variants where electronic control systems and precision load modulation justify premium positioning against basic mechanical alternatives.
- Electric:Motorized resistance platforms integrate programmable load curves and real-time performance telemetry for data-driven training protocols. Demand clusters in professional athlete facilities and high-budget military conditioning centers where quantified progression tracking justifies capital expenditure.
- Hydraulic:Fluid-based resistance systems deliver smooth, adjustable drag without external power requirements, suiting field-deployable military units and outdoor training installations. Procurement officers favor these for expeditionary conditioning programs where generator dependence creates operational vulnerability.
- Pneumatic:Compressed-air resistance mechanisms enable rapid load adjustments through valve control, appealing to rehabilitation settings requiring progressive resistance protocols.
- Manual:Unpowered plate-loaded designs dominate commercial gym price-sensitive procurement through minimal mechanical complexity and maintenance burden.
The dominant share belongs to Manual systems, while Electric configurations are closing the gap fastest.
End User:
Application context dictates durability certification tiers, with federal procurement standards creating the steepest barrier to entry among customer categories.
- Military Training:Federal acquisition frameworks mandate AWS D1.1 weld certification and ISO 20957-1 compliance for apparatus deployed in Army Combat Fitness Test preparation. The US Department of Defense's updated physical fitness standards embed weighted drag events into permanent infrastructure, generating recurring replacement cycles.
- Rehabilitation Facilities:Post-surgical and neurological recovery protocols integrate progressive sled-based gait retraining, expanding addressable demand beyond traditional strength verticals. OSHA workplace safety guidelines now explicitly reference load-bearing conditioning equipment in facility audit protocols, accelerating certified equipment replacement.
- Fitness Centers:Commercial gym chains face elevated liability exposure for uncertified apparatus, driving consolidation toward suppliers with documented weld inspection records.
- Professional Athletes:Individual and team training facilities prioritize programmable resistance curves and performance analytics integration.
Military Training commands the dominant procurement volume, though Rehabilitation Facilities are expanding most quickly.
Capacity:
Load rating determines institutional eligibility, with 400-pound specifications serving as the threshold for federal defense contracting.
- 400 lbs:Steel-framed institutional units satisfy military procurement durability specifications under repeated maximum loads, anchoring premium pricing power in defense contracting corridors surrounding Fort Bragg and San Diego.
- 300 lbs:Intermediate platforms serve commercial gym chains and collegiate athletic programs requiring durability without federal-grade certification overhead.
- 200 lbs:Mid-range capacities dominate rehabilitation facility procurement where patient progression protocols emphasize incremental load advancement.
- 100 lbs:Entry-level ratings concentrate in consumer direct-to-consumer channels and light commercial applications.
The 400 lbs segment holds dominant institutional share, while 300 lbs configurations are gaining share fastest among commercial operators.
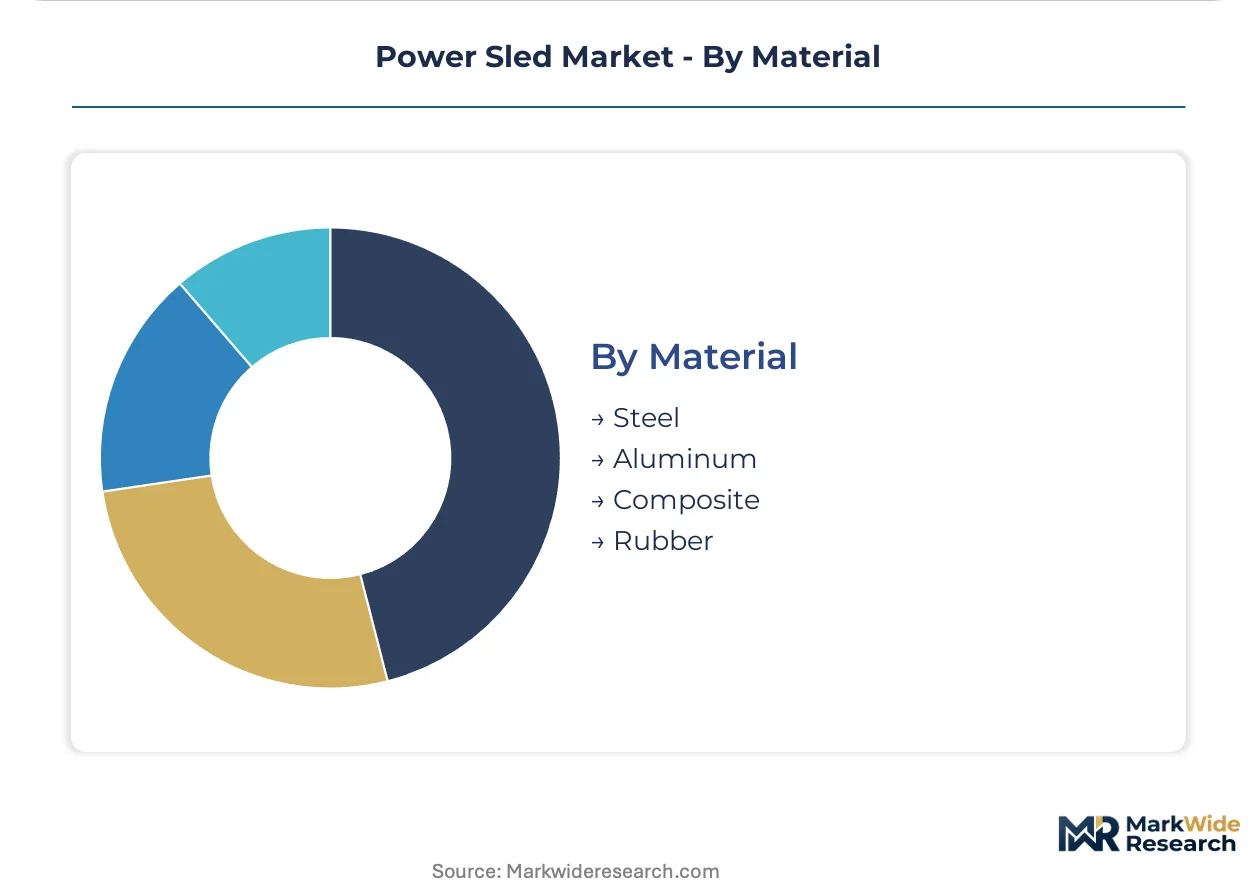
Material:
Transport weight constraints and corrosion exposure create divergent material optimization paths between mobile military deployments and fixed commercial installations.
- Steel:Welded tubular steel construction dominates institutional sales due to durability under repeated 400-pound loads and weld inspection traceability required by federal procurement officers.
- Aluminum:Aerospace-grade aluminum variants address mobile military deployments where transport weight constrains logistics, though volatility in aluminum pricing compresses margins for these configurations.
- Composite:Polymer-reinforced runners supplant steel skids in cold-weather military variants where corrosion resistance and weight reduction outweigh absolute load capacity.
- Rubber:Replaceable contact surfaces on runners and skids reduce facility flooring damage and extend platform service life across all construction types.
Steel retains dominant share in institutional procurement, while Composite materials are climbing the fastest in defense applications requiring snow-terrain penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Midwestern US industrial corridors, with AWS-certified welding infrastructure anchoring institutional-grade production. Defense procurement corridors surrounding major military installations concentrate demand for load-bearing conditioning equipment.
United States
The US Department of Defense's updated physical fitness standards mandate functional strength assessments through weighted drag events, embedding power sleds into federal procurement pipelines. OSHA workplace safety guidelines now explicitly reference load-bearing conditioning equipment in facility audit protocols, accelerating certified equipment replacement cycles. Demand concentrates in defense contracting corridors surrounding Fort Bragg, North Carolina and San Diego, California, where prime contractors absorb subcontractor capacity through exclusive supply arrangements.
Germany
Industrial machinery heritage and precision engineering capabilities position German fabricators to supply cold-weather military variants for NATO expeditionary forces. REACH regulations and CE marking requirements govern material composition and weld integrity for equipment deployed in European defense training facilities. Manufacturing activity clusters in Bavaria and North Rhine-Westphalia, where automotive-tier steel fabrication expertise transfers to institutional-grade conditioning apparatus.
Canada
Arctic warfare training requirements drive demand for snow-terrain penetration platforms, with composite-reinforced runners supplanting steel skids in cold-weather variants. Health Canada guidelines align with ISO 20957-1 stationary training equipment standards, compelling manufacturers to certify anti-tip stability for rehabilitation facility deployments. Procurement concentrates in Alberta and Quebec, where ski-vehicle engineering heritage from recreational markets transfers to tactical conditioning programs.
Australia
Professional athlete facilities and military special operations conditioning programs generate demand for programmable resistance platforms with real-time performance telemetry. The Therapeutic Goods Administration (TGA) and national workplace safety regulators enforce equipment certification for rehabilitation facility deployments. Activity clusters in New South Wales and Victoria, where high-performance training centers for elite sports programs anchor premium equipment procurement.
United Kingdom
Ministry of Defence physical training standards and commercial fitness chain consolidation patterns reshape procurement toward suppliers with documented weld inspection records. The UK's Health and Safety Executive references load-bearing equipment standards in facility liability assessments, driving consolidation toward certified manufacturers. Defense and commercial demand concentrates around military installations in Wiltshire and fitness clusters in Greater London, where procurement officers mandate manufacturer certification documentation.
Power Sled Market Competitive Landscape
Concentration sits with diversified sporting goods manufacturers and specialized fitness equipment fabricators. The vendor base spans snow-vehicle engineering heritage companies, in-house steel fabrication specialists, and direct-to-consumer channel operators. Two strategic archetypes dominate: extreme-terrain engineering specialists leveraging recreational vehicle expertise, and manufacturing-scale operators controlling captive steel supply. Competitive moves center on multi-year defense framework agreements and exclusive subcontractor absorption arrangements.
Among North American heritage brands, Ski-Doo and Arctic Cat occupy positions reflecting snow-vehicle chassis expertise, while Rogue Fitness anchors the manufacturing-scale archetype through in-house fabrication control. These three represent distinct competitive vectors: terrain-engineering credibility, cold-weather platform specialization, and supply chain verticalization. Each archetype captures different procurement channels—defense conditioning contracts, expeditionary military deployments, and commercial fitness institutional sales.
| Leading Market Players |
|---|
| Ski-Doo |
| Rogue Fitness |
| Arctic Cat |
| Shogun Sports |
| Titan Fitness |
| Polaris |
| REP Fitness |
| Xebex Fitness |
| Lynx |
| Others |
Value Network & Pricing Analysis
Multi-year defense framework agreements lock in supply access and price visibility for institutional-grade fabricators, insulating certified manufacturers from spot-market volatility while compressing margins for non-compliant competitors excluded from federal procurement pipelines.
Pricing Analysis
Volume-discount tiering structures separate AWS D1.1-certified institutional units from uncertified commercial alternatives. Pricing stratifies across premium, standard, and economy tiers based on weld certification traceability and load capacity ratings. Cost compression in aluminum-reinforced mobile variants is intensifying because aerospace-grade material volatility outpaces contract escalation clauses. Rehabilitation facilities exhibit highest price sensitivity due to budget constraints, while defense procurement officers prioritize certification documentation over unit cost.
Supply Chain Analysis
AWS D1.1 structural welding certification capacity concentrates in Midwestern US fabrication hubs, creating supplier bottlenecks for institutional orders. Production draws from domestic steel mills, regional aluminum processors, and polymer composite suppliers. Single-source vulnerability sits with certified welder availability outpacing vocational training output. Distribution runs through prime contractor networks surrounding Fort Bragg and San Diego, with direct-to-consumer channels bypassing traditional fitness equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resistance band systems and bodyweight suspension trainers pose substitution threats that power sled incumbents must neutralize through embedded data analytics and irreplaceable load-bearing specificity.
For Market Incumbents: Consolidate subcontractor welding capacity through exclusive supply arrangements near defense procurement corridors. Capture backward integration into steel tubing fabrication to secure margin control against raw material volatility. Deepen ISO 20957-1 certification portfolios to disqualify emerging competitors from commercial gym chain consolidation.
For New Entrants and Emerging Players: ISO 20957-1 fast-track certification unlocks rehabilitation facility procurement where post-surgical gait retraining demand outpaces established supplier attention. Cold-weather military variants for snow-terrain penetration remain underdeveloped relative to turf-focused offerings. Pursue direct-to-consumer channel control to build proprietary customer data assets before institutional credentialing completes.
For Investors and Strategic Acquirers: Specialized AWS-certified fabricators with documented defense contracting relationships offer consolidation targets as procurement officers reduce vendor qualification overhead. Long-term viability hinges on recurring replacement cycles embedded in Army Combat Fitness Test infrastructure permanence. Monitor congressional defense appropriation timing as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AWS D1.1 Certification Investment | Unlocks federal supply schedule eligibility for Army Combat Fitness Test procurement. |
| Direct-to-Consumer Channel Launch | Bypasses distributor markups while capturing proprietary training performance data assets. |
| Cold-Weather Platform Development | Addresses Arctic warfare training gaps where composite runners displace steel skids. |
| Rehabilitation Protocol Integration | Aligns progressive load modulation with post-surgical neurological recovery standards. |
| Multi-Year Defense Framework Agreement | Insulates certified manufacturers from spot-market volatility through volume commitments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of defense procurement databases, OSHA facility audit protocols, and ISO certification registries. Interviews with military conditioning officers, rehabilitation facility directors, commercial gym procurement managers, and AWS-certified welding supervisors inform demand-side validation. Trade customs data, federal supply schedule awards, and stationary training equipment safety filings provide supply-side triangulation. Bottom-up unit shipment estimates cross-check against top-down addressable market sizing.
Segmentation dimensions modeled include resistance mechanism type, end-user application context, load capacity tier, and material composition across the analysis window. CAGRs derive from regression analysis against defense budget trajectories and commercial fitness chain expansion patterns. Rehabilitation protocol adoption curves and military physical fitness standard revision timelines serve as industry-specific forecast inputs.
Underlying assumptions cover defense appropriation continuity and aluminum pricing stability, with deviation risk concentrated in congressional spending cycle disruptions and vocational welding program output shortfalls. Practitioners should keep alternative scenarios live as Army Combat Fitness Test equipment refresh schedules and OSHA enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global UPS Market
Power
Harmonic Filter Market
Power
Smart Power Market
Power
Japan Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Gabon Power Market
Power
Power Shelf Market
Power
Electric Arc Furnaces Market
Power
Modular PSA Nitrogen Generator Market
Power
Wind Turbine Drivetrain Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Critical Power Market
Power
Compact Substation Market
Power
Temporary Load Bank Rental Market
Power
Marine Thermal Fluid Heaters Market
Power
Gas Freeing Fan Market