
 Europe E-Waste Management Market | 2026-2036
Europe E-Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Waste Management Market Insights
Certified e-waste dismantling labor is bifurcating the competitive landscape between high-automation recyclers and manual-sorting operators. Veolia leverages its pan-European collection infrastructure to anchor market presence across France and Benelux. Umicore SA specializes in precious metal recovery from complex circuit boards, while Aurubis AG competes on copper and tin refining scale at its Hamburg facility.
Europe E-Waste Management encompasses the systematic collection, dismantling, and material recovery of discarded electrical and electronic equipment containing recoverable fractions of copper, gold, rare earth elements, and flame-retardant plastics, operating under mandated recycling quotas to reinsert secondary raw materials into industrial supply chains. Processing technique selection determines margin outcomes, with hydrometallurgical recovery capturing value from low-grade fractions that pyrometallurgical routes cannot economically treat. Product type dynamics favor IT equipment streams for their concentrated precious metal content, whereas household appliances generate volume but thinner unit economics due to ferrous dominance and lower rare element loading.
The EU WEEE Directive, the EU Green Deal circular economy action plan, and national implementations by Germany's EAR foundation collectively mandate producer financing obligations and collection targets that structurally guarantee feedstock availability for licensed operators. ECHA REACH restrictions on hazardous substance thresholds in recovered plastics further shape processing technology investment priorities. Stakeholders must monitor upcoming EU battery regulation integration with e-waste frameworks, as this interface will determine which recyclers secure permitted capacity for the emerging electric vehicle electronics retirement wave.
Market Dynamics
The EU WEEE Directive's tightening collection targets and the EU Green Deal's circular economy mandates are structurally guaranteeing feedstock flows toward licensed operators while compressing margins for informal dismantlers operating outside compliance frameworks.
Growth Catalysts
- Producer financing obligations:Germany's EAR foundation and parallel national schemes mandate manufacturer-funded collection, eliminating feedstock acquisition risk for permitted recyclers.
- IT hardware retirement waves:Enterprise data center refreshes and cloud migration cycles are accelerating high-grade circuit board availability with concentrated precious metal content.
- Hydrometallurgical recovery scale-up:France and Italy concentrate investment in aqueous processing routes that extract value from low-grade fractions pyrometallurgy cannot treat.
Market Restraints
- Copper price volatility:Ferrous-dominant household appliance streams generate thinner unit economics when base metal benchmarks swing, compressing recycler margins on volume-heavy categories.
- Collection infrastructure fragmentation:Municipal waste streams in Eastern Europe remain under-integrated with licensed processing networks, creating feedstock leakage to unpermitted operators.
- REACH compliance costs:ECHA thresholds for hazardous substance recovery in plastics require capital-intensive separation equipment that smaller dismantlers cannot finance.
Strategic Opportunities
- Electric vehicle electronics retirement:The upcoming EU battery regulation integration with e-waste frameworks will create permitted capacity scarcity for lithium-ion recovery from retired automotive power electronics.
- Poland and Romania collection gaps:Underpenetrated municipal systems in these markets offer first-mover positioning for integrated collection-to-refining operators.
- Blockchain-tracked material provenance:Digital chain-of-custody systems are emerging as a channel innovation to secure premium pricing from OEMs requiring conflict-mineral-free secondary supply.
Industry Challenges
- Certified dismantling labor scarcity:ECHA-compliant hazardous substance handling qualifications remain concentrated in Germany and France, limiting facility expansion in peripheral markets.
- Multi-stream integration complexity:Battery regulation convergence requires recyclers to reconfigure legacy WEEE-licensed lines for combined electronics and power cell processing without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Waste Management Market |
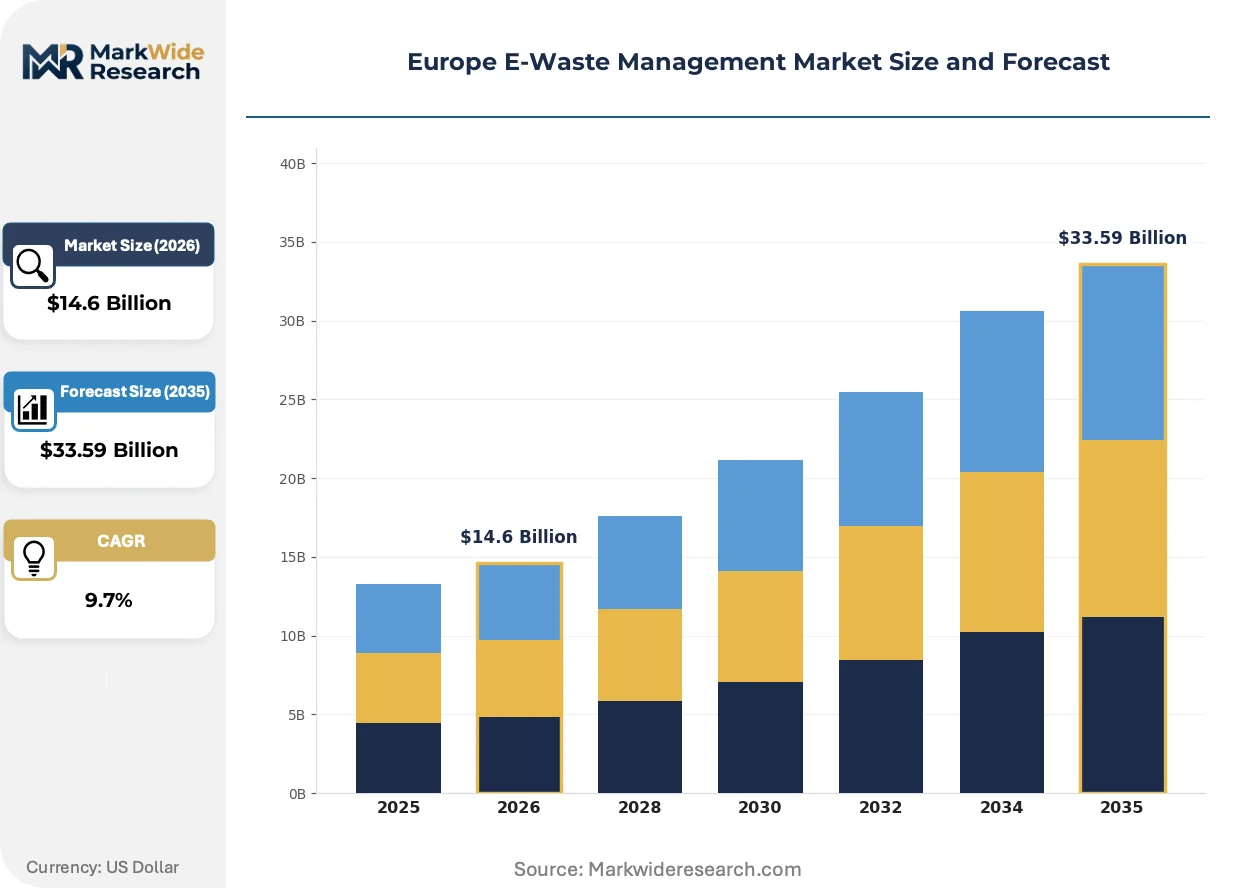
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $33.59 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IT Equipment, Household Appliances, Consumer Electronics, Telecommunication Devices Collection Method: Drop-off Centers, Curbside Collection, Retail Take-back, Collection Events Processing Technique: Manual Dismantling, Mechanical Separation, Pyrometallurgical Recovery, Hydrometallurgical Recovery End User: Households, Enterprises, Retailers, Municipalities |
| Companies Covered | Veolia, Suez Group, Biffa Group, Remondis SE & Co. KG, Umicore SA, Stena Technoworld, Aurubis AG, Kuusakoski Oy, Tetronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Waste Management Market Trends and Innovations
Processing technology selection and regulatory interface design are bifurcating competitive positioning between capital-intensive hydrometallurgical specialists and high-volume mechanical sorting operators.
Robotic dismantling systems equipped with AI-driven component recognition are displacing manual sorting labor in high-throughput facilities. German and French recyclers are deploying these systems for IT equipment streams where precision separation preserves precious metal integrity. The technology is displacing mid-scale manual operators who cannot amortize automation capex against thinner household appliance margins.
CSRD reporting obligations are mandating granular disclosure of recycled content percentages across corporate supply chains. Large electronics manufacturers must now verify and document secondary raw material sourcing, creating audit-trail requirements that favor vertically integrated recyclers with in-house assay capabilities. IT hardware OEMs with German manufacturing footprints are most affected, driving contracted offtake agreements with certified refiners.
Certification-driven procurement is consolidating buyer preference around R2 and e-Stewards accredited facilities. Enterprise IT asset disposition managers are eliminating non-certified vendors from approved supplier lists, compressing the addressable market for uncertified dismantlers. France and Benelux enterprise sectors exhibit the strictest accreditation requirements, with public sector tenders now mandating dual certification.
Europe E-Waste Management Market Segmentation
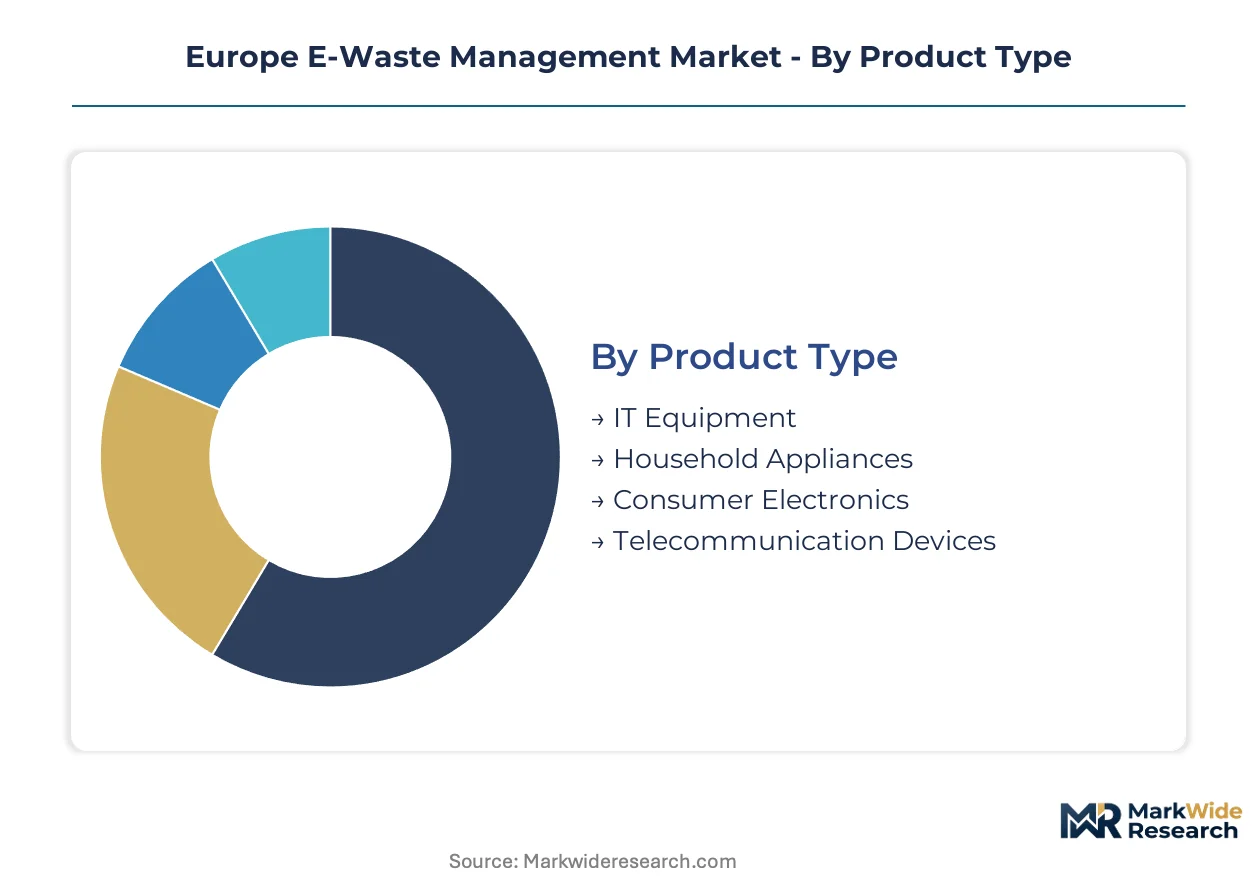
Segmentation in Europe e-waste management determines which processing technologies achieve viable returns and which collection channels capture compliant feedstock. Distinct material compositions across product categories drive divergent investment profiles for recyclers targeting precious metal recovery versus volume-based ferrous processing.
Product Type:
Channel-mix dynamics route high-value streams through certified enterprise ITAD channels while municipal programs capture lower-grade household flows.
- IT Equipment:Servers, laptops, and data center hardware contain concentrated gold, palladium, and rare earth loadings in circuit boards and memory modules. German enterprise refresh cycles and French cloud migration projects supply this premium feedstock to hydrometallurgical refiners under contracted offtake agreements.
- Household Appliances:Refrigerators, washing machines, and air conditioners dominate collection tonnage through municipal curbside programs but carry thinner unit economics due to ferrous metal dominance and flame-retardant plastic disposal costs. Italian and Spanish recyclers struggle with margin compression on these volume-heavy categories when copper benchmarks fluctuate.
- Consumer Electronics:Smartphones, tablets, and wearables generate moderate precious metal yields per unit through retail take-back schemes operated by major electronics chains.
- Telecommunication Devices:Network infrastructure and base station equipment enters secondary markets through operator-managed retirement programs with specialized logistics requirements.
Household Appliances dominates installed base. IT Equipment is where expansion concentrates.
Collection Method:
Cost-tier stratification separates capital-intensive retail integration from low-infrastructure municipal alternatives.
- Drop-off Centers:Fixed collection points at recycling yards and civic amenity sites handle mixed waste streams requiring downstream sorting investment. Poland and Romania rely heavily on this lower-cost model, creating feedstock leakage risks to unpermitted operators.
- Curbside Collection:Scheduled residential pickup services for bulky waste capture household appliance volume but generate high logistics costs and contamination rates. Benelux municipalities operate the most integrated curbside-to-refinery networks in Europe.
- Retail Take-back:Store-based return programs for consumer electronics and small IT equipment achieve highest collection rates for portable devices under EU WEEE Directive one-to-one exchange mandates.
- Collection Events:Periodic community drives and corporate IT asset disposition days concentrate high-grade enterprise equipment for certified dismantlers with R2 accreditation.
Drop-off Centers anchor municipal infrastructure. Retail Take-back is climbing the fastest as producer compliance obligations tighten.
Processing Technique:
Technology selection bifurcates the competitive landscape between labor-dependent dismantlers and capital-intensive metallurgical specialists.
- Manual Dismantling:Skilled labor separates hazardous components and preserves precious metal integrity in circuit boards before downstream refining. ECHA-compliant certification requirements concentrate this capability in Germany and France, limiting facility expansion elsewhere.
- Mechanical Separation:Shredding and magnetic sorting systems process high-volume household appliance streams for ferrous and aluminum recovery at lower unit costs.
- Pyrometallurgical Recovery:High-temperature smelting routes treat copper-rich fractions and complex residues at large-scale facilities like Aurubis AG's Hamburg operation.
- Hydrometallurgical Recovery:Aqueous leaching processes extract value from low-grade IT equipment fractions that pyrometallurgy cannot economically treat, with France and Italy concentrating investment in this higher-margin technology.
Mechanical Separation handles the greatest throughput volume. Hydrometallurgical Recovery is gaining share fastest among technology investments.
End User:
Customer-type differentiation drives service-level requirements from audit-intensive enterprise contracts to standardized municipal procurement.
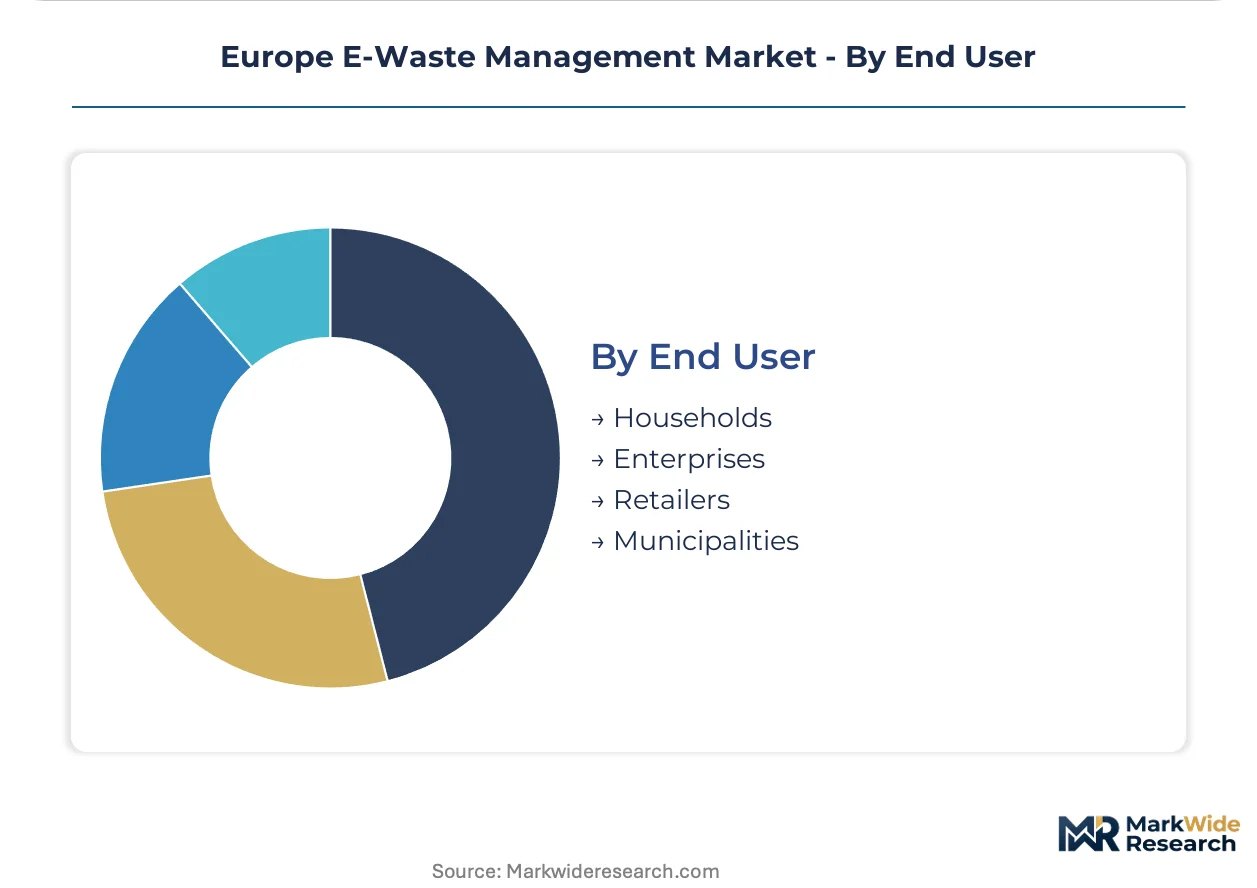
- Households:Residential generators produce fragmented, low-visibility waste streams requiring public education and convenient access points to prevent diversion to informal channels.
- Enterprises:Corporate IT departments demand chain-of-custody documentation, data destruction certificates, and conflict-mineral-free sourcing verification under CSRD reporting obligations.
- Retailers:Electronics merchants and supermarket chains operate compliance-driven take-back programs with reverse logistics integration into existing distribution networks.
- Municipalities:Local government waste authorities procure collection and preprocessing services through tender processes that increasingly mandate dual R2 and e-Stewards certification.
Households represent the largest generator base. Enterprises is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes e-waste management services through enterprise ITAD channels with intensive data-destruction requirements, while Southern European markets route higher household appliance volumes through municipal drop-off networks with thinner recovery economics.
Germany
Enterprise data center refreshes and cloud migration cycles generate concentrated high-grade circuit board feedstock. The EAR foundation mandates producer financing obligations that eliminate feedstock acquisition risk for licensed operators. Hamburg hosts Aurubis AG's large-scale copper refining complex serving Northern European pyrometallurgical demand.
France
Public sector tenders now mandate dual R2 and e-Stewards certification for IT asset disposition contracts. CSRD reporting obligations drive granular recycled content disclosure from electronics manufacturers with French assembly footprints. The Paris metropolitan corridor concentrates hydrometallurgical investment for precious metal recovery from complex residues.
Italy
Municipal bulky waste collection captures high volumes of refrigerators and washing machines with ferrous-dominant economics. REACH compliance costs for flame-retardant plastic separation compress margins for smaller dismantlers. Northern industrial clusters around Milan and Turin specialize in manual circuit board preprocessing for downstream refiners.
Poland
Underpenetrated municipal collection systems create feedstock leakage risks to unpermitted operators outside licensed networks. EU cohesion fund investments are upgrading civic amenity sites toward WEEE Directive compliance. The Silesian industrial region attracts first-mover positioning for integrated collection-to-refining operations.
Netherlands
Benelux municipalities operate the most integrated curbside-to-refinery networks in Europe with reverse logistics density. Retail take-back programs achieve highest collection rates for portable consumer electronics under one-to-one exchange mandates. The Rotterdam port cluster serves as a transshipment hub for bulk WEEE feedstock moving to German and Belgian processors.
Europe E-Waste Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe's e-waste management structure. Pan-European waste utilities leverage collection infrastructure density to anchor feedstock security, while metallurgical specialists compete on refining technology selection for precious metal recovery. Strategic archetypes divide between high-automation dismantlers pursuing scale economies and manual-sorting operators preserving component integrity for premium material streams. Competitive moves concentrate on permitted capacity expansion ahead of EU battery regulation integration and backward integration into collection networks to secure compliant feedstock flows.
Within the integrated utility tier, Veolia and Suez Group exemplify pan-European operators leveraging waste management infrastructure across multiple national compliance frameworks. Among specialized refiners, Umicore SA occupies a position representing the hydrometallurgical recovery archetype focused on complex circuit board fractions, while Aurubis AG anchors the pyrometallurgical scale segment at its Hamburg facility.
| Leading Market Players |
|---|
| Veolia |
| Suez Group |
| Biffa Group |
| Remondis SE & Co. KG |
| Umicore SA |
| Stena Technoworld |
| Aurubis AG |
| Kuusakoski Oy |
| Tetronics |
| Others |
Pricing and Supply Chain Analysis
Scale economies at Aurubis AG's Hamburg copper refinery anchor price floors across Northern European pyrometallurgical processing, compressing margins for smaller operators unable to amortize capital intensity against volatile copper benchmarks. This concentration of refining capacity shapes contract structures and collection network investments throughout the licensed operator tier.
Pricing Analysis
Long-term offtake agreements dominate enterprise IT asset disposition channels, with German data center operators locking in hydrometallurgical recovery services under multi-year contracts indexed to precious metal benchmarks. Spot-market exposure concentrates in municipal household appliance streams where Italian and Spanish recyclers absorb copper price volatility on ferrous-dominant tonnage. Certification tier creates price stratification: dual R2 and e-Stewards accredited facilities command premiums from CSRD-reporting OEMs, while uncertified dismantlers compete on thin margins in underpenetrated Eastern European markets. Price erosion runs through household appliance processing as REACH compliance costs for flame-retardant plastic separation outpace recovery value.
Supply Chain Analysis
Inventory buffers at Rotterdam port transshipment hubs extend lead times for bulk WEEE feedstock moving to German and Belgian processors, creating working capital intensity for collection-to-refining operators. Supply concentrates in Germany, France, and the Netherlands, with Benelux municipalities operating Europe's most integrated curbside-to-refinery networks. The chain draws from copper concentrate imports, rare earth element feedstock, and certified dismantling labor concentrated in Germany and France. Single-source vulnerability sits with ECHA-compliant hazardous substance handling qualifications, which limit facility expansion beyond core Western European markets. Distribution runs through producer responsibility organizations like Germany's EAR foundation, which mandate manufacturer-funded collection and eliminate feedstock acquisition risk for permitted recyclers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU WEEE Directive compliance and ECHA REACH certification creates durable defensive moats for licensed operators, with producer financing obligations structurally guaranteeing feedstock flows that informal dismantlers cannot replicate.
For Market Incumbents: Consolidate collection infrastructure density in underpenetrated Polish and Romanian municipal systems ahead of EU cohesion fund upgrades, while expanding hydrometallurgical capacity to capture lithium-ion recovery demand from electric vehicle electronics retirement. Threat of battery regulation integration with e-waste frameworks demands reconfiguration of legacy processing lines for combined electronics and power cell handling without cross-contamination. For New Entrants and Emerging Players: Anchor in Poland's Silesian industrial region where EU cohesion fund investments are upgrading civic amenity sites toward WEEE Directive compliance, creating first-mover positioning for integrated collection-to-refining operations. The penetrable segment lies in blockchain-tracked material provenance systems that secure premium pricing from OEMs requiring conflict-mineral-free secondary supply. Go-to-market through contracted offtake agreements with French public sector tenders mandating dual R2 and e-Stewards accreditation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hydrometallurgical specialists with contracted enterprise ITAD relationships and in-house assay capabilities serving CSRD-reporting manufacturers. Long-term viability over the projection horizon favors vertically integrated operators with backward control over collection networks and permitted capacity for battery-e-waste convergence. The acquisition target archetype is mid-scale manual dismantlers in Italy and Spain with circuit board preprocessing expertise that larger refiners seek to internalize. Watch EU battery regulation implementation timelines as the inflection signal for permitted capacity scarcity in lithium-ion recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Veolia-style pan-European infrastructure density secures compliant feedstock flows under EAR foundation mandates. |
| Hydrometallurgical Capacity Expansion | Aqueous processing routes capture value from low-grade IT fractions that pyrometallurgy cannot economically treat. |
| Dual Certification Investment | R2 and e-Stewards accreditation unlocks French public sector tenders and enterprise ITAD contracts. |
| Battery-E-Waste Line Reconfiguration | Combined electronics and power cell processing without cross-contamination addresses EU battery regulation integration. |
| Blockchain Provenance Systems | Digital chain-of-custody documentation satisfies OEM conflict-mineral-free sourcing requirements under CSRD obligations. |
Research Methodology
A spread of perspectives from licensed e-waste facility operators, EAR foundation administrators, enterprise IT asset disposition managers, and hydrometallurgical process engineers converged on the working assumptions around feedstock availability and recovery yield benchmarks. Primary fieldwork combined structured interviews with secondary validation through EU WEEE Directive implementation reports, ECHA REACH regulatory filings, national producer responsibility organization disclosures, and customs data on secondary raw material trade flows. Bottom-up triangulation across collection channel volumes and top-down reconciliation against mandated recycling quotas anchored the analytical framework.
Segmentation dimensions modeled include product type, collection method, processing technique, and end-user category across the analysis window. CAGRs were derived from trend extrapolation of historical collection rates, producer financing obligation expansion, and technology adoption curves for robotic dismantling systems. Industry-specific forecast inputs incorporated enterprise IT hardware retirement cycle timing, copper price volatility bands, and EU battery regulation integration scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained EU WEEE Directive enforcement and stable precious metal benchmark levels; material deviation in regulatory stringency or base metal prices would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
E-Waste Management Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
Smart Waste Collection Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Aluminum Cans Recycling Market