
 Global Habitat Restoration Market | 2026-2036
Global Habitat Restoration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Habitat Restoration Market Analysis
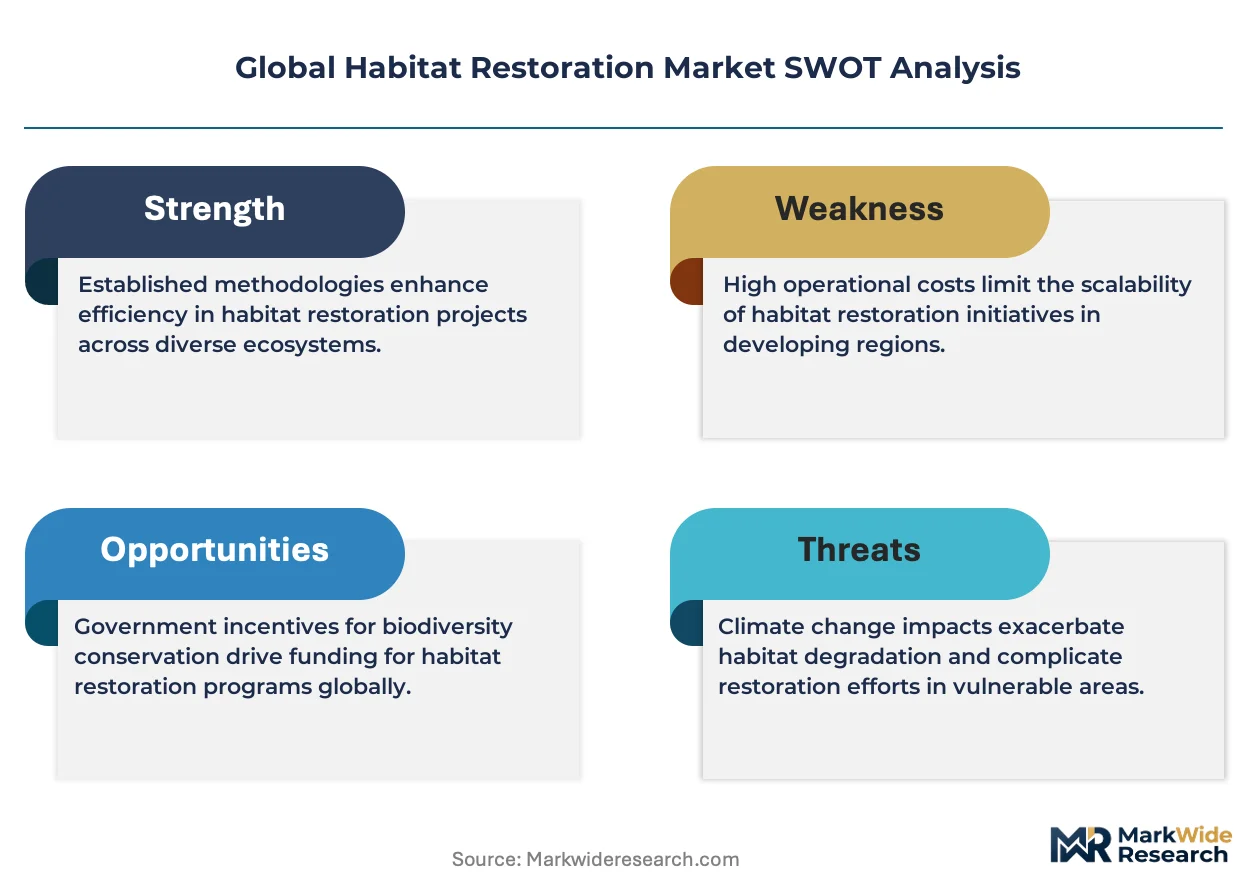
Bioengineered soil substrates is repositioning project economics across large-scale restoration sites. Tetra Tech, Inc. leverages its integrated design-build capacity to dominate complex riverine contracts. SWCA Environmental Consultants anchors its competitive position through deep regulatory permitting expertise. Cardno Limited specializes in coastal resilience engineering across the Asia-Pacific basin.
Habitat restoration encompasses the active rehabilitation of degraded ecosystems through re-establishment of native vegetation, hydrological reconstruction, and soil bioremediation to recover ecological function and biodiversity services. Wetland restoration commands the largest share of deployed capital due to stringent compensatory mitigation requirements under federal statutes, while reforestation segments exhibit the fastest project pipeline growth driven by carbon credit monetization. Public projects remain the dominant funding channel, though private initiatives are capturing margin pools through biodiversity offset mechanisms.
The EPA enforces compensatory mitigation ratios under Section 404 of the Clean Water Act, while the EU Nature Restoration Law establishes binding recovery targets across member states. Brazil's ICMBio and Australia's EPBC Act impose restoration conditions on development approvals. Stakeholders must monitor how evolving biodiversity credit standards reshape project finance structures and contractor qualification requirements.
Market Dynamics
The EU Nature Restoration Law is compressing project timelines across Europe while binding recovery targets force developers to pre-fund restoration liabilities, reshaping contractor qualification requirements and capital deployment patterns.
Growth Catalysts
- Section 404 Compensatory Mitigation:The EPA enforces strict wetland replacement ratios that mandate restoration acreage for permitted development, creating perpetual demand for mitigation banking credits.
- Carbon Credit Monetization:Reforestation projects generate verified carbon units through Verra and Gold Standard registries, attracting private capital to previously grant-dependent ecosystems.
- Mining Reclamation Bonds:Australia and Canada now require full-cost bonding for site rehabilitation before extraction permits issue, guaranteeing restoration funding regardless of operator solvency.
Market Restraints
- Native Seed Supply Bottlenecks:Specialized indigenous plant material requires multi-year cultivation cycles, and North American suppliers lack capacity to meet sudden demand surges from federal infrastructure packages.
- Soil Substrate Cost Volatility:Engineered growing media depend on perlite and biochar inputs whose prices fluctuate with energy markets, compressing margins on fixed-price restoration contracts.
- Long-Duration Liability Transfer:Performance bonds and monitoring obligations extend 5-10 years post-completion, trapping contractor capital and limiting balance sheet capacity for new awards.
Strategic Opportunities
- Biodiversity Credit Frameworks:Emerging offset mechanisms in the United Kingdom and Singapore create tradable habitat units that private developers purchase to satisfy planning conditions.
- Drone-Assisted Hydroseeding:Aerial application technology converges with precision seeding equipment to slash labor costs on steep terrain inaccessible to ground crews.
- Corporate Net-Zero Commitments:Voluntary restoration pledges by extractive industries exceed regulatory minimums in Brazil's Atlantic Forest corridor, opening premium service tiers.
Industry Challenges
- Ecological Engineering Talent Scarcity:Universities produce insufficient restoration ecologists and fluvial geomorphologists to staff expanding project pipelines, forcing wage inflation for specialized roles.
- Multi-Jurisdictional Permitting Complexity:Riverine projects spanning state or provincial boundaries trigger overlapping federal, state, and local approval processes that extend mobilization timelines.
- Legacy Contaminant Remediation Integration:Brownfield restoration sites require hazardous material handling certifications that most pure-play habitat contractors lack, necessitating subcontractor management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Habitat Restoration Market |
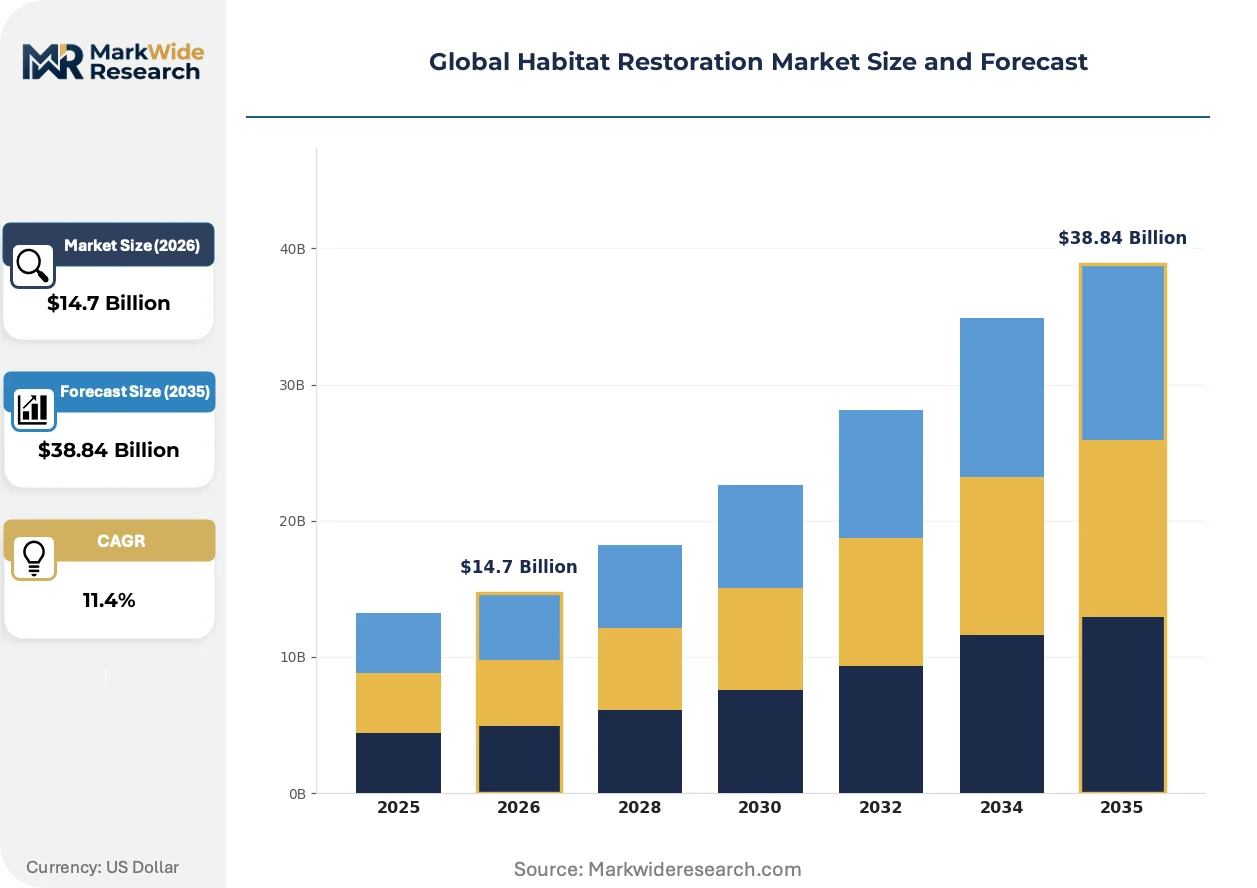
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Restoration Method: Reforestation, Wetland Restoration, River Restoration, Coastal Restoration Project Type: Public Projects, Private Initiatives, Non-Profit Programs, Community-Based Projects Target Ecosystem: Forests, Wetlands, Grasslands, Urban Areas Funding Source: Government Grants, Private Investments, Donations, International Aid |
| Companies Covered | Tetra Tech, Inc., Stantec Inc., AECOM, Jacobs Solutions Inc., Biohabitats, Inc., EnviroScience, Inc., SWCA Environmental Consultants, Environmental Restoration Services, Cardno Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Habitat Restoration Market Emerging Trajectories
Digital twin technology and autonomous monitoring systems are compressing verification costs while regulatory bodies accelerate approval frameworks for technology-assisted restoration methods.
Remote sensing platforms equipped with multispectral cameras and LiDAR sensors are automating vegetation health assessment across thousands of hectares. Mining operators in Western Australia deploy these systems weekly to demonstrate compliance with rehabilitation milestones. The technology is automating what required manual field surveys, collapsing monitoring costs by orders of magnitude and enabling performance-based contract structures.
The EU Nature Restoration Law establishes binding ecosystem recovery targets that member states must achieve by specified deadlines. National governments must submit restoration plans covering at least 20 percent of land and sea areas. Wetland restoration contractors in the Netherlands and Denmark report accelerated permitting for projects that demonstrate measurable biodiversity outcomes within compressed timelines.
Conservation procurement is consolidating around long-term stewardship contracts that transfer decades of monitoring liability to specialized operators. Infrastructure developers in Canada now prefer 30-year performance agreements over traditional design-bid-build arrangements. This preference shift concentrates award volume with firms carrying demonstrated biological asset management capabilities rather than pure construction credentials.
Global Habitat Restoration Market Segmentation
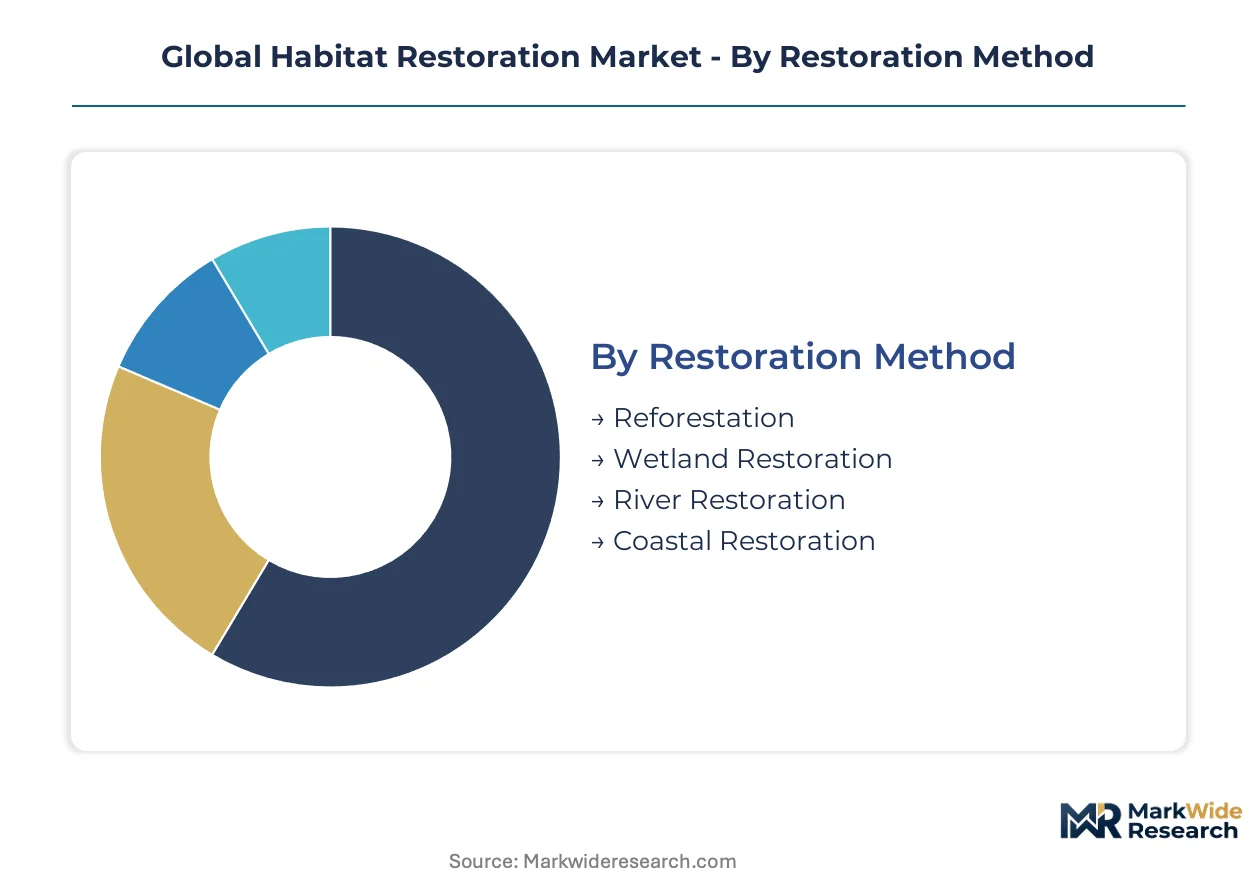
Restoration contractors configure service portfolios around ecosystem-specific technical requirements and liability structures. Method selection determines equipment specialization and regulatory compliance pathways. Funding source shapes contract duration, pricing models, and stakeholder engagement intensity.
Restoration Method:
Wetland restoration commands premium pricing due to compensatory mitigation mandates, while reforestation scales through carbon credit monetization.
- Reforestation:Large-scale native tree establishment generates verified carbon units through Verra and Gold Standard registries. Brazil's Atlantic Forest corridor and Australia's mining rehabilitation bonds concentrate demand for mechanized planting and drone-assisted seeding operations.
- Wetland Restoration:Hydrological reconstruction and native vegetation re-establishment satisfy EPA Section 404 compensatory mitigation ratios. The Netherlands and Denmark report accelerated permitting for projects demonstrating measurable biodiversity outcomes within compressed timelines mandated by the EU Nature Restoration Law.
- River Restoration:Fluvial geomorphology and riparian buffer engineering for sediment control and habitat connectivity.
- Coastal Restoration:Living shoreline implementation and dune stabilization across erosion-prone littoral zones.
Today's leader: Wetland Restoration. Tomorrow's challenger: Reforestation.
Project Type:
Public procurement dominates capital deployment, though private biodiversity offset mechanisms capture expanding margin pools.
- Public Projects:Federal infrastructure packages and state environmental agencies fund compensatory mitigation and watershed restoration. Canada's infrastructure developers now prefer 30-year performance agreements over traditional design-bid-build arrangements, concentrating awards with firms carrying biological asset management capabilities.
- Private Initiatives:Corporate net-zero commitments and extractive industry voluntary pledges exceed regulatory minimums. Voluntary restoration commitments in Brazil's Atlantic Forest corridor open premium service tiers for specialized contractors.
- Non-Profit Programs:Conservation organization grants supporting community stewardship and endangered species recovery.
- Community-Based Projects:Local watershed councils and indigenous land management initiatives with decentralized decision structures.
Public Projects anchor current volume. Private Initiatives are gaining share fastest through biodiversity credit frameworks.
Target Ecosystem:
Forests and wetlands absorb the majority of restoration capital, while urban green infrastructure emerges as a specialized contracting niche.
- Forests:Native canopy re-establishment and understory regeneration for biodiversity corridors and carbon sequestration.
- Wetlands:Hydric soil reconstruction and hydrophytic vegetation establishment for water quality and flood attenuation.
- Grasslands:Prairie restoration and savanna reconstruction requiring specialized native seed sourcing and prescribed fire management.
- Urban Areas:Brownfield remediation integration with green infrastructure, requiring hazardous material handling certifications that pure-play habitat contractors typically lack.
Forests dominate carbon-linked finance. Urban Areas present the steepest expansion trajectory as municipal climate adaptation budgets grow.
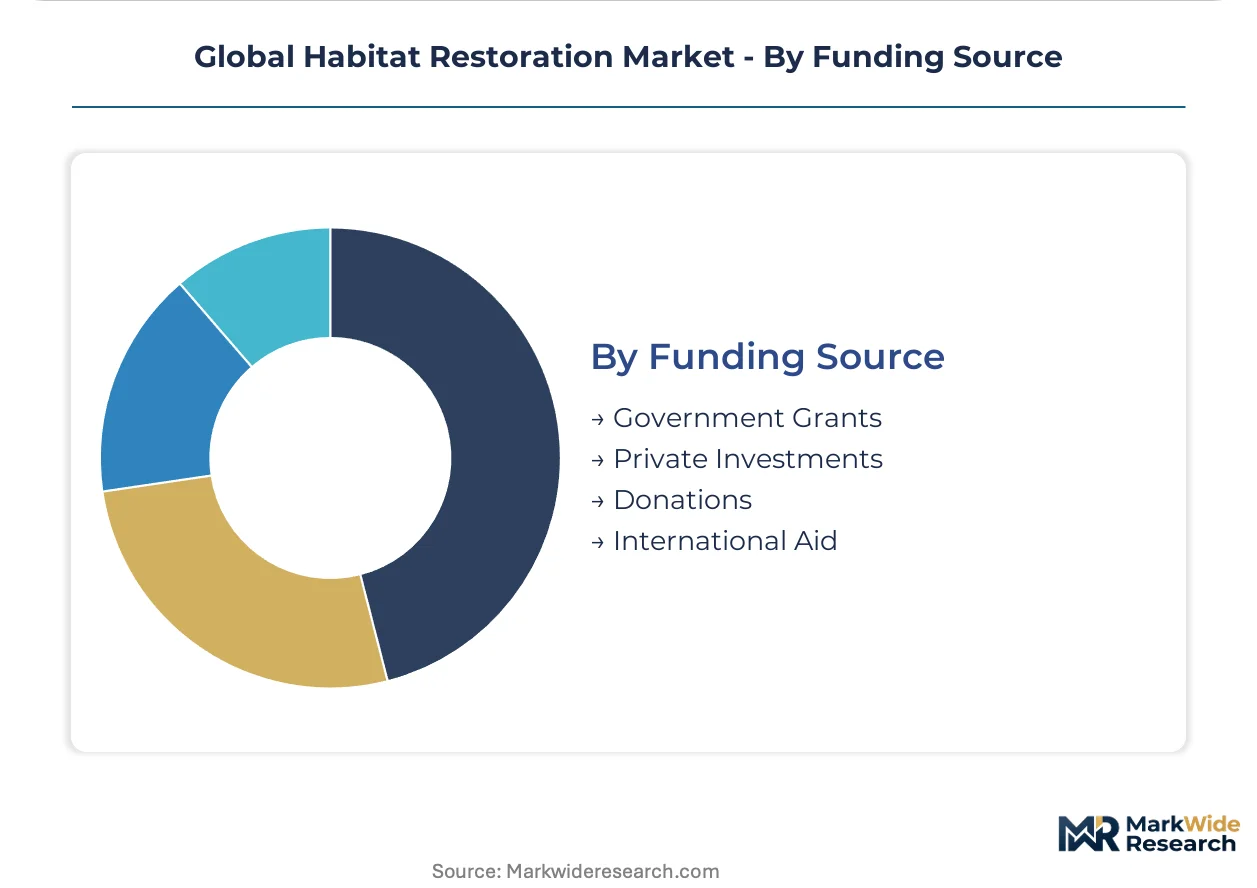
Funding Source:
Government grants provide baseline revenue stability, though private capital deployment is restructuring project finance timelines.
- Government Grants:Federal environmental agencies and state natural resource departments fund compensatory mitigation and endangered species recovery. The EU Nature Restoration Law forces developers to pre-fund restoration liabilities, reshaping contractor qualification requirements.
- Private Investments:Infrastructure funds and corporate sustainability budgets channel capital toward verified outcome projects. Biodiversity credit frameworks in the United Kingdom and Singapore create tradable habitat units that private developers purchase to satisfy planning conditions.
- Donations:Philanthropic conservation funding for high-profile species recovery and protected area buffer restoration.
- International Aid:Multilateral development bank financing for transboundary watershed and biodiversity hotspot programs.
Government Grants maintain structural dominance. Private Investments are climbing the fastest as biodiversity credit markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Atlantic Forest corridor anchors the most concentrated restoration investment flow worldwide. Mining rehabilitation bonds in Australia and compensatory mitigation mandates in the United States generate parallel demand clusters. The EU Nature Restoration Law is compressing project timelines across member states while forcing pre-funding of restoration liabilities.
United States
EPA Section 404 compensatory mitigation ratios drive perpetual demand for wetland banking credits. The Infrastructure Investment and Jobs Act channels federal capital toward watershed restoration in the Mississippi River basin. Design-build contractors in the Pacific Northwest dominate riverine contracts requiring fluvial geomorphology expertise.
Brazil
Atlantic Forest corridor projects absorb the majority of Latin American restoration capital. ICMBio imposes binding restoration conditions on development approvals in biodiversity hotspots. Mechanized planting operations in São Paulo state scale through carbon credit monetization under Verra registries.
Australia
Western Australian mining operators deploy weekly remote sensing surveys to demonstrate rehabilitation compliance. The EPBC Act mandates full-cost bonding for site rehabilitation before extraction permits issue. Perth-based contractors specialize in arid-zone restoration requiring engineered soil substrates and drought-tolerant seed mixes.
Canada
Oil sands operators in Alberta face escalating reclamation obligations under provincial environmental protection statutes. Infrastructure developers prefer 30-year performance agreements over traditional design-bid-build arrangements. Toronto-Ottawa corridor firms carry demonstrated biological asset management capabilities that concentrate award volume.
Netherlands
Accelerated permitting for wetland projects demonstrates measurable biodiversity outcomes within compressed EU deadlines. Delta restoration engineering expertise exports to Bangladesh and Vietnam through government development aid programs. Rotterdam-area contractors integrate living shoreline implementation with flood defense infrastructure.
Global Habitat Restoration Market Vendor Landscape
Strategic partnerships dominate the current landscape as engineering conglomerates absorb specialized ecological consultancies to secure mitigation banking permits. The vendor base stratifies across three tiers: integrated design-build operators with federal contracting credentials, pure-play restoration ecologists with deep regulatory permitting expertise, and regional site contractors executing vegetation establishment protocols. Portfolio diversification into carbon credit verification services and long-term stewardship contracting represents the primary competitive vector. Geographic expansion into Brazil's Atlantic Forest and Australia's mining jurisdictions captures premium margin pools.
Within the integrated engineering tier, Tetra Tech, Inc. and AECOM exemplify firms leveraging design-build capacity to dominate complex riverine and coastal contracts. SWCA Environmental Consultants occupies a distinct position among pure-play ecological specialists, anchoring competitive advantage through regulatory permitting depth rather than construction scale. These archetypes reflect the market's bifurcation between capital-intensive infrastructure delivery and knowledge-intensive compliance navigation.
| Leading Market Players |
|---|
| Tetra Tech, Inc. |
| Stantec Inc. |
| AECOM |
| Jacobs Solutions Inc. |
| Biohabitats, Inc. |
| EnviroScience, Inc. |
| SWCA Environmental Consultants |
| Environmental Restoration Services |
| Cardno Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EPA-approved mitigation banks and unverified restoration providers manifests in both contract pricing and procurement pathways. Premium-tier contractors command fixed-price certainty through pre-approved credit inventories, while commodity players absorb perlite and biochar cost volatility on cost-plus arrangements.
Pricing Analysis
Input-cost pass-through from engineered soil substrates dominates contract economics. Three-tier pricing structure across premium, standard, and economy levels separates design-build operators with federal credentials from regional vegetation contractors and unqualified site crews. Price differentiation hinges on Verra carbon verification status and compensatory mitigation banking permits. Cost compression in the standard tier intensifies because fixed-price contracts cannot absorb perlite price spikes. Mining operators in Western Australia exhibit lowest price sensitivity; municipal watershed councils in the United States show highest.
Supply Chain Analysis
Reverse-logistics flows for native seed stock reshape procurement geography. Supply concentrates in Australia, Canada, and Brazil for drought-tolerant seed mixes and engineered growing media. Raw material dependencies include indigenous plant material, biochar, and precision hydroseeding equipment. Single-source vulnerability runs through North American native seed suppliers lacking surge capacity for federal infrastructure packages. Distribution runs through long-term stewardship contracts that transfer decades of monitoring liability to specialized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Nature Restoration Law operates as a regulatory compounder, mandating binding ecosystem recovery targets that force developers to pre-fund restoration liabilities and reshape contractor qualification requirements.
For Market Incumbents: Cement competitive position through backward integration into native seed cultivation and carbon credit verification services. Acquire specialized ecological consultancies to secure mitigation banking permits before regulatory deadlines compress. Vertical integration into drone-assisted hydroseeding equipment reduces labor cost exposure on steep terrain contracts. For New Entrants and Emerging Players: Mid-tier mining operators in Australia's Pilbara region present an underserved buyer archetype seeking arid-zone restoration without design-build scale requirements. Penetrate through outcome-based performance agreements that demonstrate rehabilitation milestones via remote sensing rather than manual surveys. White-space exists in Singapore biodiversity credit verification services. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory permitting depth concentrates award volume with firms carrying biological asset management capabilities. Long-term viability favors acquirers targeting pure-play restoration ecologists with EPA Section 404 expertise and demonstrated 30-year stewardship contract execution. Monitor Verra registry approval velocity for early signals of carbon credit market liquidity.| Strategic Initiative | Industry Significance |
|---|---|
| Native Seed Supply Integration | Captive cultivation of indigenous plant material insulates margins from multi-year cultivation cycle bottlenecks. |
| Carbon Credit Verification Service Launch | Verra registry accreditation unlocks private capital flows to previously grant-dependent reforestation ecosystems. |
| Drone-Assisted Hydroseeding Deployment | Aerial application technology slashes labor costs on steep terrain inaccessible to ground crews in Brazil's Atlantic Forest. |
| 30-Year Performance Agreement Structuring | Long-term stewardship contracts transfer monitoring liability and concentrate award volume with biological asset managers. |
| Regulatory Permitting Depth Acquisition | EPA Section 404 expertise and EU Nature Restoration Law compliance capabilities reshape contractor qualification barriers. |
Methodological Framework
Coverage spans North America, Europe, Latin America, and Asia-Pacific, with primary inputs from each region combining structured interviews with restoration contractors, mining operators, environmental regulators, and carbon credit verifiers alongside secondary validation. Sources include EPA permitting databases, ICMBio restoration condition records, Verra registry disclosures, and mining rehabilitation bond filings. Bottom-up project pipeline analysis triangulates against top-down regulatory mandate quantification.
Granularity-level modeling disaggregates the analysis window by restoration method, project type, target ecosystem, and funding source, with additional dimensioning by regulatory jurisdiction cluster and carbon credit eligibility status. CAGRs derive from weighted project pipeline growth rates and regulatory mandate enforcement timelines. Forecast inputs incorporate mining reclamation bond expansion trajectories and biodiversity credit framework adoption curves.
Underlying measurement precision varies by segment; wetland restoration carries tighter precision than urban brownfield integration due to established compensatory mitigation ratios and verified credit trading volumes. Forecasts reflect assumptions around regulatory enforcement consistency and carbon market liquidity development. Practitioners should monitor EU member state restoration plan submission timelines and Verra methodology update cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Packaged Water Treatment System Market
Environment & Sustainability
Sludge Dewatering Equipment Market
Environment & Sustainability
Plant Based Water Filter Market
Environment & Sustainability
Environment Monitoring Devices Market
Environment & Sustainability
Green Building Market
Environment & Sustainability
Solar Glass Market
Environment & Sustainability
Europe Green Cement Market
Environment & Sustainability
Radon Gas Test Kits Market
Environment & Sustainability
South American Waste Management Market
Environment & Sustainability
Europe Green Wall Market
Environment & Sustainability
Home Water Filtration Unit Market
Environment & Sustainability
Storm Water Cleaning Services Market
Environment & Sustainability
North America Green Buildings Market
Environment & Sustainability
Desiccant Air Breather Market
Environment & Sustainability
Electronic Scrap Recycling Market
Environment & Sustainability
Global Water Market